
 Myanmar Plastics Market | 2026-2036
Myanmar Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Plastics Market Foresight
Polyethylene terephthalate is broadening its displacement of glass and metal in beverage packaging across Myanmar's processing sector. Shwe Pyi Tan Plastic Factory leverages its Yangon manufacturing base to dominate rigid container supply for domestic food brands. Indorama Ventures Public Company Limited anchors regional resin supply through its integrated PET chip-to-fiber operations serving Southeast Asian converters. Myanmar Plastic Industries Ltd. specializes in extruded pipe systems for municipal water infrastructure, competing with imported PVC alternatives on delivery speed.
Plastics comprise synthetic or semi-synthetic organic polymers, typically formulated with molecular weights exceeding ten thousand daltons and processed through extrusion, injection molding, or blow molding above their glass transition temperatures. Their primary commercial purpose centers on substituting heavier, costlier materials with moldable, chemically resistant alternatives across packaging, construction, and consumer durables. Polypropylene leads product type demand owing to its fatigue resistance in automotive interior components and woven sacks for Myanmar's rice export trade. Packaging captures the dominant application share, though pipes and fittings is accelerating fastest as the Ministry of Construction expands rural water access programs.
Myanmar's national environmental regulator and the country's standards bureau shape product compliance through emerging restrictions on single-use carrier bags and import quality certifications for food-contact materials. The central bank's foreign exchange controls indirectly constrain resin import financing, forcing processors to optimize inventory cycles or source from regional traders. Stakeholders must monitor regulatory enforcement consistency across Myanmar's states and evaluate local compounding partnerships to mitigate currency-driven supply disruptions.
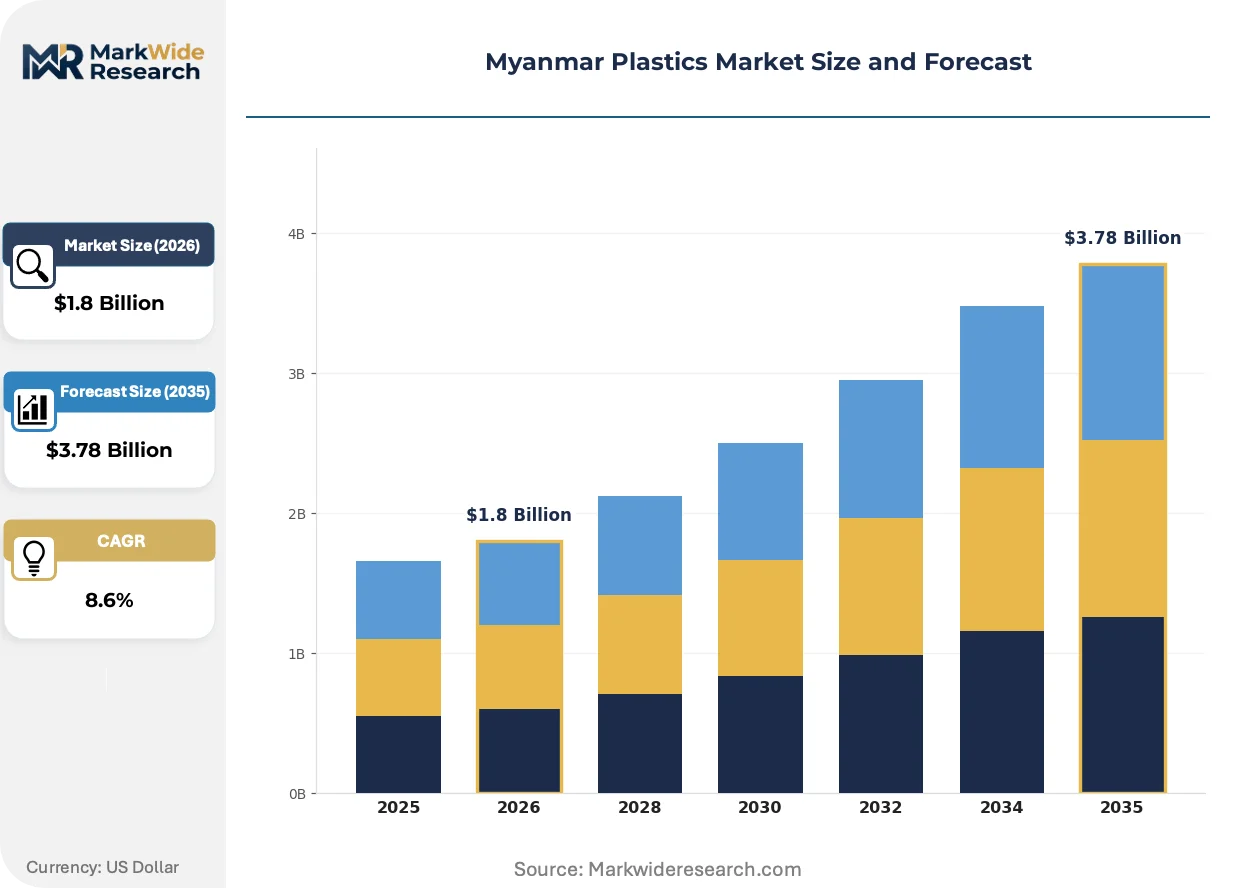
Market Dynamics
Myanmar's plastics market is compressing around foreign exchange rationing and regulatory tightening on single-use packaging, forcing converters to restructure resin procurement and accelerate recyclate integration.
Growth Catalysts
- Recyclable polyethylene grades:The national environmental regulator's waste management rules are pushing food processors toward post-consumer recyclate content in rigid containers.
- Rural water infrastructure:The Ministry of Construction's expansion of municipal pipe networks is accelerating demand for extruded PVC and HDPE systems in previously unserved townships.
- Yangon logistics corridor:Bulk resin distribution infrastructure along the Thilawa port-to-industrial zone route is reducing landed costs for processors serving domestic brands.
Market Restraints
- Import financing constraints:The central bank's foreign exchange controls are limiting resin import letters of credit, forcing processors to shrink inventory coverage or accept shorter payment terms from regional traders.
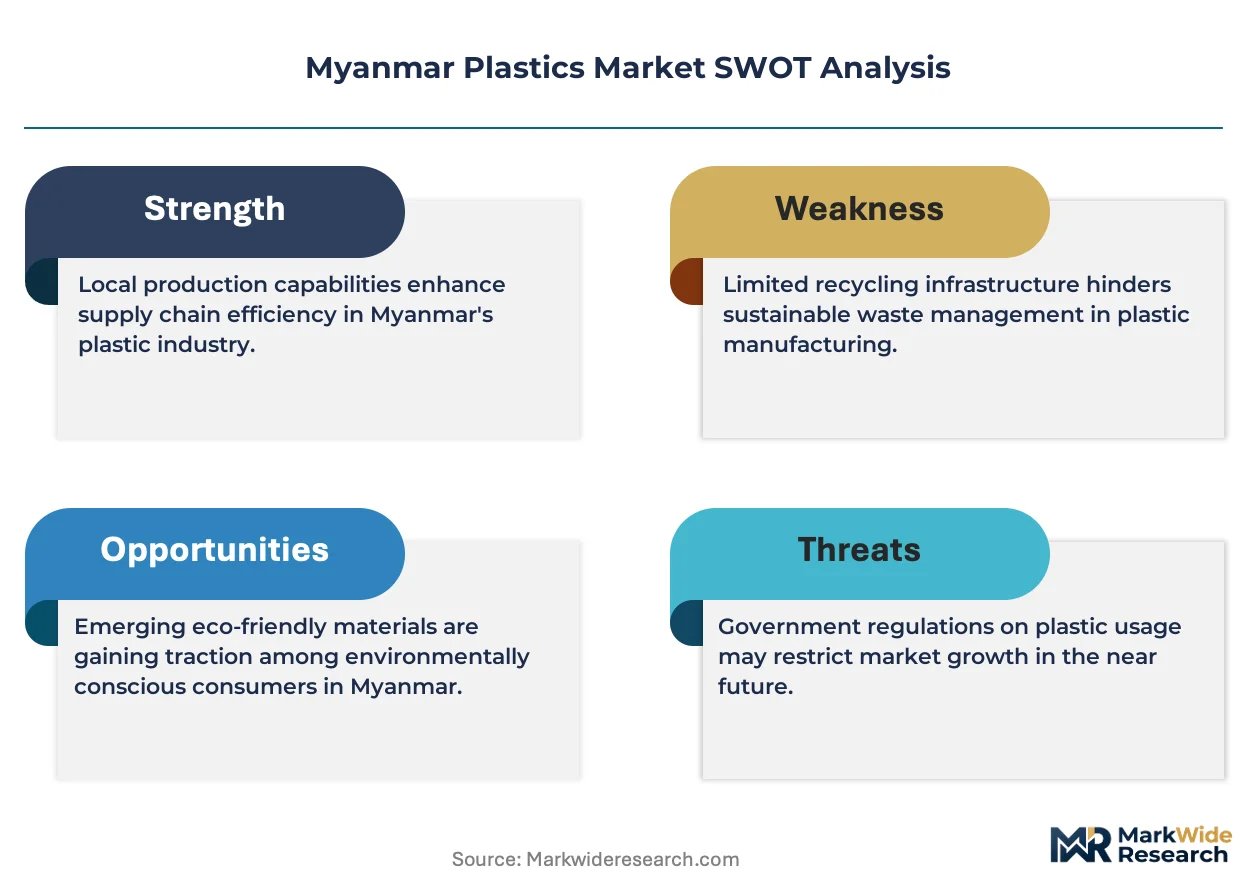
- Substitution by aluminum:Beverage bottlers in Mandalay are trialing aluminum cans for carbonated drinks, threatening PET bottle volumes in premium segments.
- Quality certification delays:The country's standards bureau food-contact material approvals are stretching to 14-18 months, blocking new resin grades from entering formulation.
Strategic Opportunities
- Shan State agricultural film:Underpenetrated highland farming regions present white space for UV-stabilized mulch films in strawberry and temperate vegetable cultivation.
- Compostable carrier bags:The emerging restriction on single-use polyethylene bags creates entry points for PLA and starch-blend alternatives in supermarket chains.
- Digital resin trading:Myanmar's processors are testing blockchain-tracked regional polymer procurement to bypass currency settlement bottlenecks with Thai and Vietnamese suppliers.
Industry Challenges
- Compounding technician shortage:Local vocational programs are not producing sufficient polymer processing engineers, forcing factories to recruit from Yangon Technical University at wage premiums.
- Legacy equipment retrofit costs:Converters running 1990s-vintage Chinese extruders face six-figure dollar outlays to meet emerging emissions and energy efficiency standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Plastics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polyvinyl Chloride, Polystyrene Application: Pipes & Fittings, Packaging, Automotive Parts, Consumer Goods End User: Construction, Agriculture, Electronics, Manufacturing Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | Shwe Pyi Tan Plastic Factory, Indorama Ventures Public Company Limited, Myanmar Plastic Industries Ltd., Myit Shwe Wah Industry Co. Ltd., Tokyo Pipe Co. Ltd, Aung Myin Hmu Plastic Co., Ltd., Golden Myanmar Plastic Industries, POPULAR PLASTIC GROUP, Myanmar Polypropylene Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Plastics Market Shifts & Advancements
Material substitution and processing automation are reconfiguring competitive advantage across Myanmar's converter base, with regulatory pressure acting as the primary acceleration mechanism for technology refresh cycles.
Post-consumer PET flake washing and pelletizing is expanding into beverage packaging supply chains as Yangon-based bottlers face downstream pressure from retail chains to demonstrate closed-loop content. Domestic recyclers are installing European-origin optical sorting lines to meet food-grade flake specifications. This capability buildout is compressing the price premium between virgin and recycled resin, enabling broader formulation substitution.
The national environmental regulator's draft extended producer responsibility framework is mandating brand-owner accountability for post-consumer packaging collection. Food processors serving Yangon's supermarket sector are pre-positioning reverse logistics partnerships with waste picker cooperatives. Rigid container converters anticipate reformulation requirements within 24-36 months as enforcement mechanisms crystallize.
Buyer concentration among Myanmar's rice export trading houses is compressing procurement cycles for woven polypropylene sacks. Mandalay-based processors are accepting shorter production runs and faster turnaround terms to retain volume commitments from the Myanmar Rice Federation's accredited exporters. This service-level escalation favors converters with in-house tape extrusion and circular loom operations over merchant-weave suppliers.
Myanmar Plastics Market Segmentation
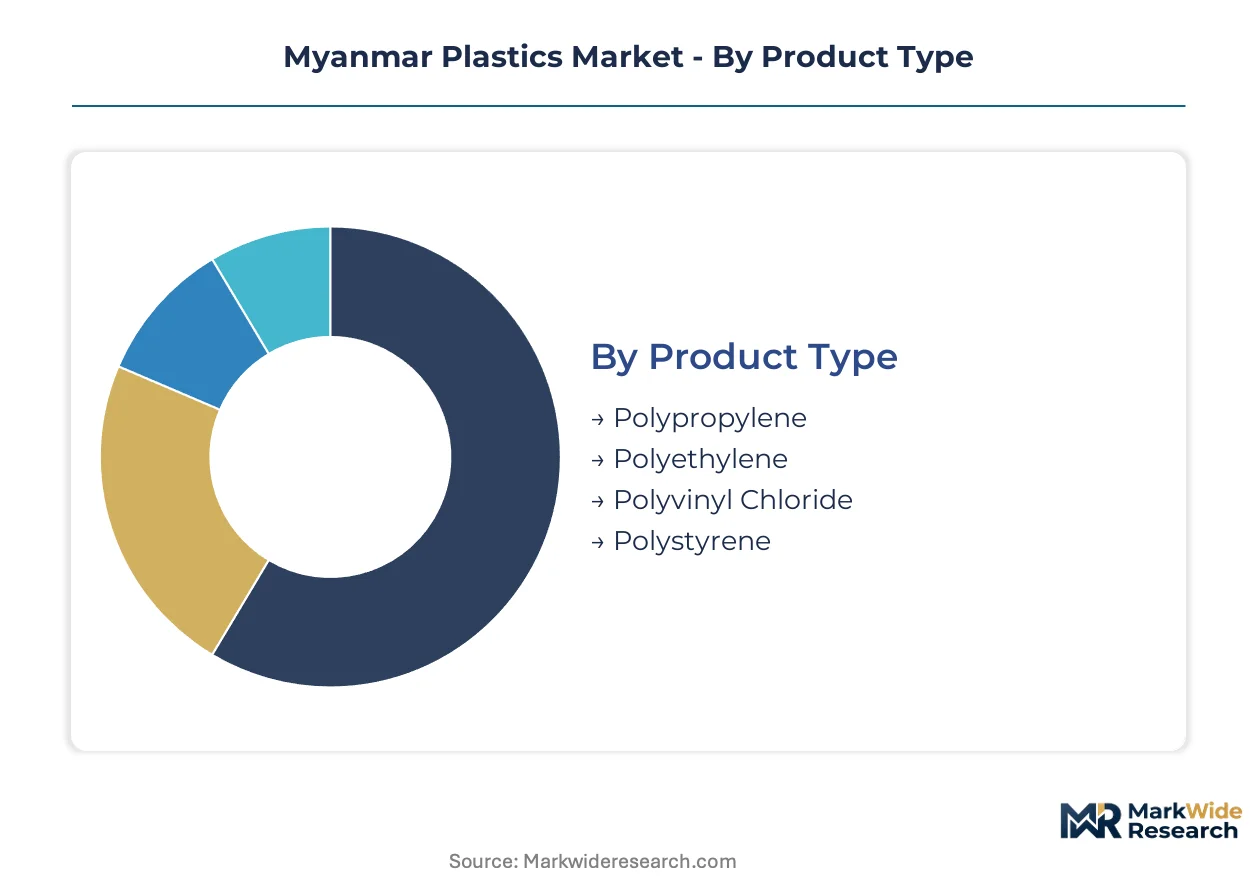
Myanmar's plastics market segments reflect divergent regulatory exposure across product grades and end-use applications. Certification requirements from the country's national environmental regulator and standards bureau create tiered compliance burdens that reshape procurement patterns among processors.
Product Type:
Food-contact approvals from the country's standards bureau impose 14-18 month validation timelines on polyethylene and polypropylene grades, while construction-grade PVC faces faster-track industrial material clearances.
- Polypropylene:Semi-crystalline thermoplastic with fatigue resistance and chemical inertness serves woven sack production for rice export trading houses concentrated in the Mandalay industrial zone. The Myanmar Rice Federation's volume procurement favors domestic converters with in-house tape extrusion and circular loom capabilities.
- Polyethylene:Linear low-density and high-density grades dominate rigid container supply for Yangon-based food processors facing downstream pressure from supermarket chains to integrate post-consumer recyclate. The national environmental regulator's waste management rules are accelerating formulation shifts toward recyclable polyethylene grades.
- Polyvinyl Chloride:Chlorinated polymer formulated for pressure-rated pipe systems competes with HDPE in municipal water infrastructure.
- Polystyrene:Amorphous thermoplastic with low thermal conductivity finds niche use in consumer electronics packaging and disposable food service items.
Leading the category by volume: Polypropylene. Growing fastest: Polyethylene.
Application:
Margin structures vary sharply across application segments, with infrastructure-linked pipe systems commanding project-financed premiums versus commoditized packaging volumes.
- Pipes & Fittings:Extruded PVC and HDPE systems for rural water access programs carry Ministry of Construction certification requirements and 10-15 year performance warranties. Mandalay-based processors compete with imports on delivery speed to township construction sites.
- Packaging:Rigid containers and flexible films face emerging extended producer responsibility mandates from the national environmental regulator's draft framework, forcing brand-owners to pre-position reverse logistics partnerships.
- Automotive Parts:Interior trim and under-hood components demand heat-stabilized polypropylene grades with OEM qualification protocols.
- Consumer Goods:Housewares and durables distribute through Yangon's retail corridor with shorter product lifecycles and lower technical specifications.
Volume leadership sits with Packaging. Steepest expansion trajectory belongs to Pipes & Fittings.
End User:
Customer concentration patterns split between state-funded infrastructure programs and fragmented private-sector procurement.
- Construction:Municipal water infrastructure expansion drives bulk resin demand with centralized tender processes through the Ministry of Construction.
- Agriculture:Shan State highland farming regions present white space for UV-stabilized mulch films in strawberry and temperate vegetable cultivation.
- Electronics:Consumer device assembly in Yangon industrial zones requires antistatic packaging grades with shorter qualification cycles.
- Manufacturing:Diverse industrial processing applications span food, textiles, and light engineering with varying technical specifications.
Construction dominates procurement scale. Agriculture offers the most underpenetrated expansion pathway.
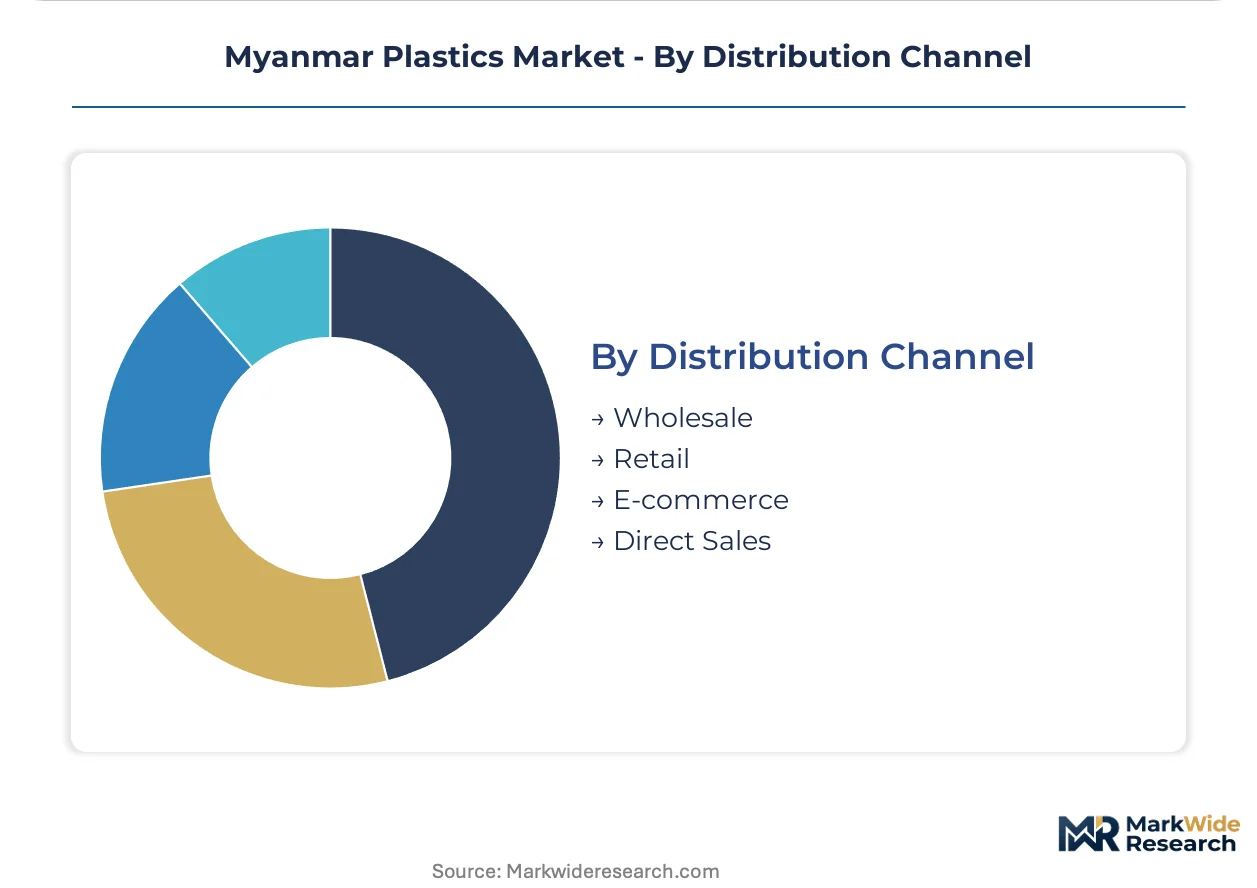
Distribution Channel:
Foreign exchange rationing from the central bank is restructuring how processors access resin supply, favoring channels with regional settlement flexibility.
- Wholesale:Bulk resin distribution through the Thilawa port-to-industrial zone route serves processors with established letters of credit and inventory coverage.
- Retail:Smaller converters source bagged compounds through Yangon-based traders with shorter payment terms and higher per-kilogram pricing.
- E-commerce:Digital resin trading platforms are testing blockchain-tracked procurement to bypass currency settlement bottlenecks with Thai and Vietnamese suppliers.
- Direct Sales:Integrated producers like Indorama Ventures supply regional converters through long-term offtake agreements.
Wholesale channels handle the largest tonnage. E-commerce is gaining share fastest among mid-cap processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Myanmar's plastics demand clusters in three distinct industrial corridors where infrastructure investment and agricultural processing create divergent resin consumption patterns. Each sub-region exhibits unique regulatory exposure and supply chain configuration.
Yangon Industrial Corridor
Food processors serving supermarket chains drive rigid container demand along the Thilawa port-to-industrial zone route. The national environmental regulator's draft extended producer responsibility framework is forcing brand-owners to pre-position reverse logistics partnerships with waste picker cooperatives. Shwe Pyi Tan Plastic Factory anchors rigid container supply from its Yangon manufacturing base.
Mandalay Industrial Zone
Rice export trading houses concentrate woven polypropylene sack procurement through the Myanmar Rice Federation's accredited exporters. The Ministry of Construction's rural water infrastructure expansion accelerates demand for extruded PVC and HDPE pipe systems. Local processors compete with imports on delivery speed to township construction sites.
Shan State Highlands
Strawberry and temperate vegetable cultivation creates white space demand for UV-stabilized agricultural mulch films in underpenetrated farming regions. The central bank's foreign exchange controls constrain resin import financing for regional distributors. Smaller converters source bagged compounds through Yangon-based traders with shorter payment terms.
Thilawa Special Economic Zone
Bulk resin distribution infrastructure reduces landed costs for processors serving domestic brands with established letters of credit. The country's standards bureau imposes 14-18 month food-contact material approval timelines on new polyethylene and polypropylene grades. Integrated producers supply regional converters through long-term offtake agreements.
Myanmar Plastics Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retrofit legacy equipment to meet emerging emissions standards and recyclate integration mandates. The vendor base organizes around three strategic archetypes: integrated resin-to-fabrication operators, specialized extrusion houses serving infrastructure tenders, and flexible packaging converters tied to agricultural commodity cycles. M&A activity concentrates among mid-cap processors seeking backward integration into compounding capabilities. Strategic partnerships with waste picker cooperatives are crystallizing as brand-owners prepare for extended producer responsibility enforcement.
Among Yangon-based fabricators, Shwe Pyi Tan Plastic Factory exemplifies the rigid container specialization archetype serving domestic food brands. Indorama Ventures Public Company Limited anchors regional resin supply through its integrated PET chip-to-fiber operations. Myanmar Plastic Industries Ltd. occupies a position within the infrastructure-focused tier competing on delivery speed for municipal pipe contracts.
| Leading Market Players |
|---|
| Shwe Pyi Tan Plastic Factory |
| Indorama Ventures Public Company Limited |
| Myanmar Plastic Industries Ltd. |
| Myit Shwe Wah Industry Co. Ltd. |
| Tokyo Pipe Co. Ltd |
| Aung Myin Hmu Plastic Co., Ltd. |
| Golden Myanmar Plastic Industries |
| POPULAR PLASTIC GROUP |
| Myanmar Polypropylene Co., Ltd. |
| Others |
Supply & Pricing Matrix
The national environmental regulator's waste management rules gate qualified supply and premium-tier pricing access, forcing converters to source certified recyclable polyethylene grades through vetted channels while commodity-grade resin flows through informal trader networks at compressed margins.
Pricing Analysis
Volume leadership sits with commoditized polypropylene woven sacks for rice export trading houses, while margin concentration rests with food-grade PET rigid containers serving Yangon's supermarket chains. Price differentiation hinges on food-contact certification timelines from the country's standards bureau and bulk volume commitments to the Myanmar Rice Federation. Pricing pressure stems from foreign exchange rationing that forces processors to accept shorter payment terms from regional traders. Small converters sourcing through Yangon-based bagged compound traders exhibit highest price sensitivity; integrated processors with established letters of credit at Thilawa port demonstrate lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Thai and Vietnamese resin suppliers who anchor polyethylene and polypropylene feedstock for Myanmar's converter base. Raw material flows draw from regional petrochemical complexes in Thailand, Vietnam, and Singapore, with specialty additives and masterbatch compounds sourcing from South Korea and Japan. Supply chain risk centers on central bank foreign exchange controls that constrain letters of credit for bulk resin imports. Distribution runs through the Thilawa port-to-industrial zone corridor for wholesale tonnage, while smaller processors access bagged compounds via Yangon-based traders with cash-settlement flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward integration into compounding capabilities separates margin-defensible processors from trader-dependent competitors squeezed by currency volatility.
For Market Incumbents: Cement compounding technician pipelines through partnerships with Yangon Technical University to offset wage premiums eroding margin structures. Secure captive recyclate supply by acquiring optical sorting lines and flake washing capacity ahead of extended producer responsibility enforcement. Aluminum can substitution in Mandalay beverage bottling threatens PET volumes; preempt with lightweighting investments and closed-loop content guarantees to retail chains.
For New Entrants and Emerging Players: Blockchain-tracked regional polymer procurement platforms offer a technology-first wedge to bypass currency settlement bottlenecks with Thai and Vietnamese suppliers. Target Shan State highland agriculture with UV-stabilized mulch films where underpenetrated strawberry and temperate vegetable cultivation lacks established supplier relationships. Lead with digital resin trading and shorter payment terms to displace Yangon-based bagged compound traders serving smaller converters.
For Investors and Strategic Acquirers: The national environmental regulator's draft extended producer responsibility framework crystallizing into enforceable mandates is the leading indicator that brand-owner accountability for post-consumer collection will reshape competitive economics. Mid-cap processors with in-house tape extrusion and circular loom capabilities present the strongest acquisition profile for consolidation plays. Watch for Ministry of Construction tender awards for rural water infrastructure as the signal for extruded pipe system demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compounding | Captive resin formulation reduces exposure to central bank foreign exchange rationing on imports. |
| Optical Sorting Line Installation | European-origin flake washing enables food-grade recyclate supply to Yangon bottlers. |
| Reverse Logistics Partnership | Waste picker cooperative alliances pre-position brand-owners for extended producer responsibility compliance. |
| Digital Resin Trading Platform | Blockchain-tracked procurement with Thai and Vietnamese suppliers bypasses currency settlement bottlenecks. |
| Lightweighting R&D Investment | Preempts aluminum can substitution in Mandalay carbonated beverage premium segments. |
Research Methodology
Trade statistics from Myanmar's customs administration, central bank foreign exchange flow reports, and Ministry of Construction infrastructure tender databases formed the secondary backbone of this analysis. Primary fieldwork encompassed interviews with plant managers at Yangon and Mandalay processing facilities, procurement leads at rice export trading houses, distribution channel partners along the Thilawa port corridor, and technical R&D directors overseeing recyclate integration programs. Bottom-up resin consumption estimates by product grade and application were cross-validated against top-down macroeconomic indicators and industrial production indices.
Historical trendline analysis of polyethylene, polypropylene, and PVC consumption patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, application, end-user industry, and distribution channel, with additional granularity on certification grade tier and regional production hub. CAGRs were derived through regression analysis of volume trajectories adjusted for regulatory inflection points and infrastructure investment cycles. Forecast inputs incorporated Ministry of Construction water access program allocations and Myanmar Rice Federation export volume projections.
Several conditions sit outside the modeled scope, including abrupt shifts in central bank foreign exchange policy, military-controlled trade route disruptions, and unilateral bans on single-use packaging categories. Forecasts reflect assumptions about regulatory enforcement consistency across Myanmar's states and the pace of extended producer responsibility framework crystallization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
United States Non-Ferrous Scrap Recycling Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Engineering Plastic Recycling Market