
 Industrial Paper Shredder Machine Market | 2026-2036
Industrial Paper Shredder Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Paper Shredder Machine Market Foresight
Market Context
High-security DIN P-7 certification is rotating toward the center of procurement decisions for defense contractors and intelligence-adjacent enterprises. Fellowes Brands leverages its North American distribution network to sustain placement in federal supply chains. HSM GmbH + Co. KG anchors European demand through precision-engineered cutting assemblies manufactured at its German facilities. Vecoplan LLC dominates the heavy-duty industrial segment with shredders engineered for continuous-operation recycling plants.
Technical Definition and Segments
An industrial paper shredder machine is a motorized destruction device equipped with hardened steel cutting cylinders, typically rated for continuous duty cycles exceeding eight hours, designed to reduce documents to irrecoverable particles for information security and recycling feedstock preparation. Cross-cut configurations lead volume in corporate and government applications where particle size standards align with mid-tier security protocols, while micro-cut technology captures the fastest expansion in banking and health institutions facing the strictest data protection requirements. Electromechanical systems occupy the largest installed base due to reliability and maintenance accessibility, though hydraulic drives extend into high-throughput recycling operations where torque demands exceed conventional motor capacities.
Regulatory Environment
Germany's BSI technical guidelines, the EU GDPR data minimization requirements, and the US NIST SP 800-88 media sanitization framework collectively shape equipment specifications and procurement checklists across multinational organizations. Health Canada and the FDA in the US impose parallel document control standards on pharmaceutical manufacturers, creating overlapping compliance obligations that favor certified destruction equipment. Stakeholders must monitor whether emerging state-level privacy laws in the US fragment certification requirements or consolidate toward federal standards.
Market Dynamics
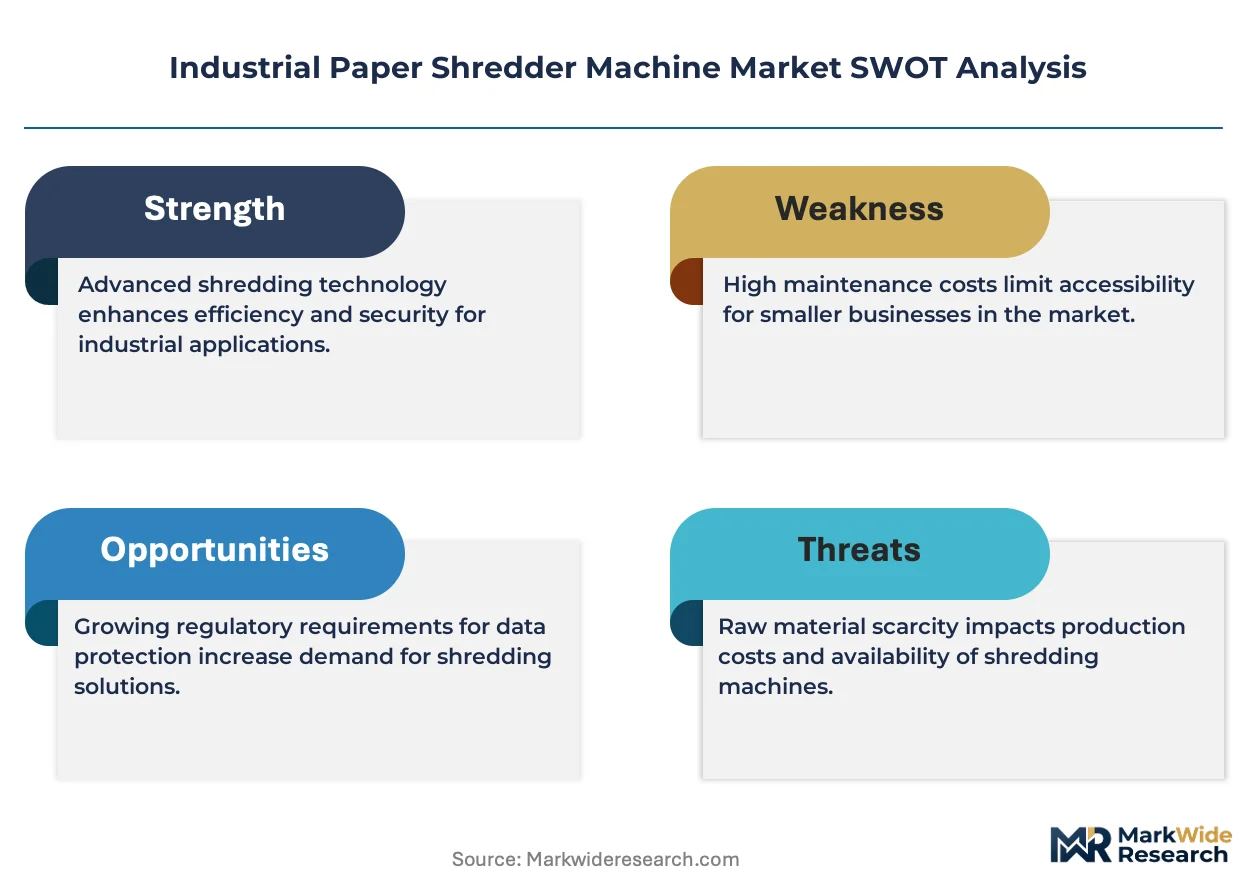
EU GDPR data minimization mandates and US NIST SP 800-88 sanitization protocols are compressing replacement cycles for industrial shredder fleets, forcing enterprises toward higher-security DIN P-7 certified equipment regardless of residual functional life.
Growth Catalysts
- GDPR Article 17 erasure obligations:European enterprises face penalties up to four percent of global turnover for inadequate document destruction, accelerating capital deployment into certified industrial shredders.
- Banking sector compliance audits:Financial institutions in Germany and Switzerland are expanding shredder procurement to satisfy BSI technical guidelines and FINMA data protection standards.
- Hydraulic drive torque advantages:Continuous-operation recycling plants in high-throughput environments are specifying hydraulic systems over electromechanical alternatives for particle consistency under load.
Market Restraints
- Hardened steel input volatility:Cutting cylinder manufacturers face alloy price swings tied to chromium and molybdenum supply concentration in South African mining operations.
- DIN certification timeline friction:German BSI laboratory testing queues extend equipment launch windows by six to nine months for non-European vendors seeking European market access.
- Digital document substitution:Enterprise content management platforms and qualified electronic signature frameworks are reducing physical document volumes in Scandinavian and Dutch corporate environments.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO document control requirements for active pharmaceutical ingredient batch records are creating first-time demand for industrial-grade destruction equipment in Mumbai and Hyderabad production clusters.
- IoT-enabled predictive maintenance convergence:Sensor-integrated shredders offering vibration monitoring and blade-wear algorithms command service contract premiums from facility management providers.
- Health Canada pharmaceutical mandates:Overlapping FDA and Health Canada inspection protocols on cross-border manufacturers favor certified destruction equipment with dual-jurisdiction documentation trails.
Industry Challenges
- Precision cutting assembly technician scarcity:Hardened steel cylinder grinding and heat-treatment expertise concentrates in German and Japanese industrial regions, constraining geographic expansion of manufacturing capacity.
- Legacy electromechanical fleet integration:Enterprises with eight-to-twelve-year-old installed bases face control system incompatibilities when retrofitting IoT monitoring modules to existing shredder motors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Paper Shredder Machine Market |
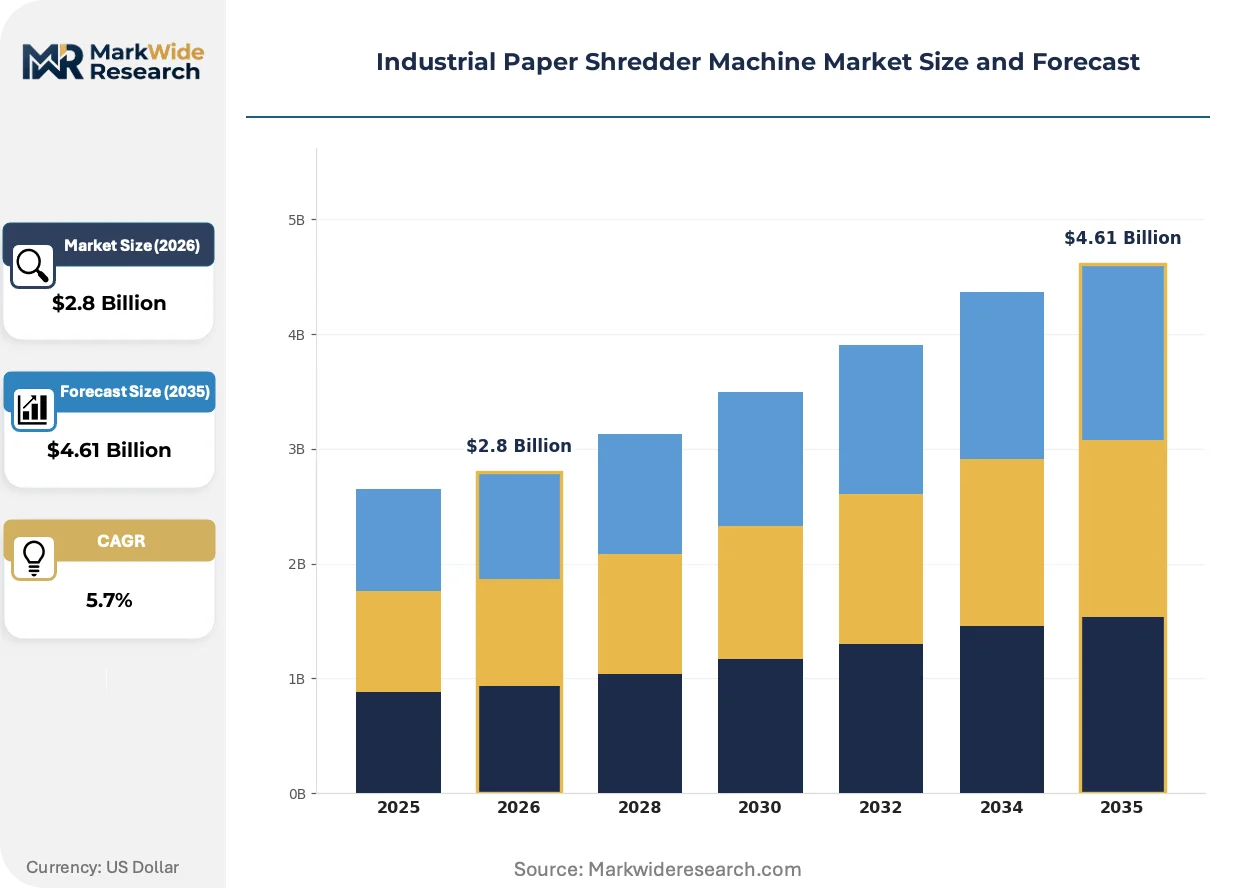
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strip-Cut, Cross-Cut, Micro-Cut, High-Security Application: Corporate, Government, Education, Banking End User: Enterprises, Small Businesses, Non-Profits, Health Institutions Technology: Electromechanical, Hydraulic, Pneumatic, Electric |
| Companies Covered | Vecoplan LLC, Allegheny Shredders, Fellowes Brands, Intimus International, HSM GmbH + Co. KG, Formax, Shred-Tech Corporation, Krug & Priester GmbH & Co. KG, Dahle North America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Paper Shredder Machine Market Shifts & Advancements
Intelligent shredding systems and automated feed mechanisms are compressing labor requirements while raising throughput consistency, reshaping competitive differentiation around software-enabled service models rather than mechanical specifications alone.
Smart shredding technology is fragmenting traditional equipment categories. Sensor-equipped cutting heads with real-time particle-size verification are penetrating defense contractor and intelligence-adjacent installations in Germany and the United Kingdom. This capability is fragmenting procurement decisions, separating vendors with embedded software competencies from pure mechanical specialists.
REACH substance restrictions on lubricants and coolants used in cutting cylinder manufacturing are forcing reformulation of maintenance consumables across European supply chains. Equipment vendors with captive chemical compliance teams are securing faster certification timelines. Health Canada is adopting parallel substance disclosure requirements, extending regulatory complexity to North American pharmaceutical manufacturers.
Leasing and managed service contracts are displacing capital purchase models for mid-tier corporate buyers. Facility management providers in France and the Netherlands are bundling shredder provision with document destruction certification. This shift concentrates vendor relationships with multi-site service integrators rather than direct end-user procurement departments.
Industrial Paper Shredder Machine Market Segmentation
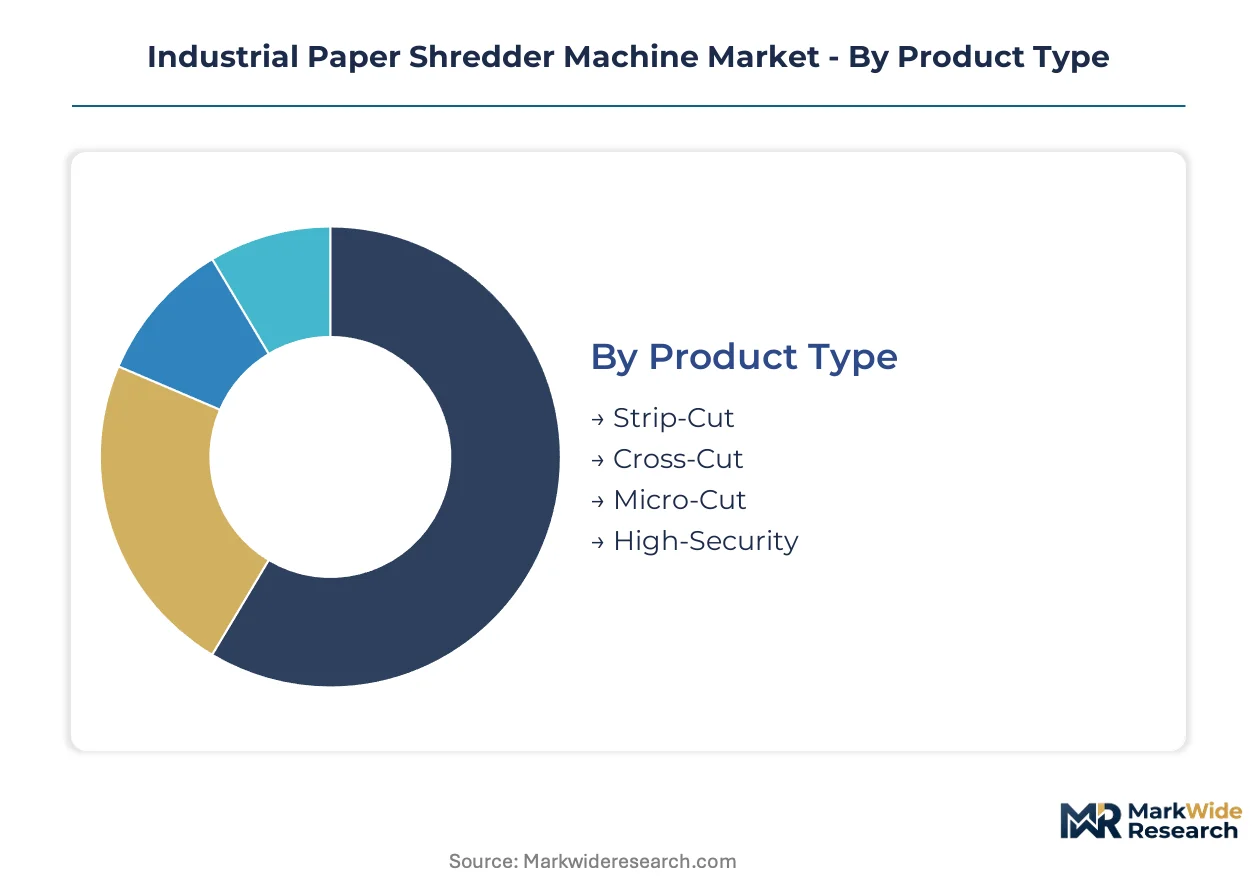
Industrial paper shredder procurement patterns diverge sharply across security mandates, operational scale, and regional regulatory intensity. Segment boundaries reflect these fault lines rather than simple mechanical differences.
Product Type:
Strip-cut configurations dominate domestic manufacturing supply chains in the United States and Germany, while micro-cut and high-security variants drive export demand from defense contractors and intelligence-adjacent installations.
- Strip-Cut:Single-direction cutting produces ribbon-shaped particles. German municipal recycling facilities specify these units for high-volume cardboard and mixed paper preprocessing where particle size standards remain permissive.
- Cross-Cut:Perpendicular blade arrays generate confetti-shaped fragments meeting mid-tier DIN P-3 through P-4 certifications. Corporate campuses in France and the Netherlands favor this format for general office destruction balancing throughput against disposal volume.
- Micro-Cut:High-density cutting matrices reduce documents to dust-like particles satisfying DIN P-5 and P-6 standards. Swiss banking regulators under FINMA guidelines mandate this grade for client file destruction.
- High-Security:DIN P-7 certified equipment produces sub-5mm particles under continuous monitoring protocols. UK intelligence services and German BSI-graded facilities represent the concentrated demand pool.
Cross-cut commands the established base. The steepest expansion runs through high-security.
Application:
Cost tier stratification separates capital-intensive government installations from leasing-preferred corporate deployments, with banking applications commanding premium pricing through compliance documentation requirements.
- Corporate:Multi-site enterprises in the Netherlands and Scandinavia increasingly contract facility management providers for shredder-as-a-service arrangements rather than direct capital purchase.
- Government:Federal supply chains in the United States and classified document handling facilities in the United Kingdom specify DIN P-7 equipment with tamper-evident destruction logging.
- Education:University administrative offices and research institutions in Germany generate seasonal demand tied to academic calendar archiving cycles.
- Banking:Frankfurt and Zurich financial centers under ECB and FINMA supervision drive replacement cycles compressed by audit failure penalties.
Corporate installations represent the volume anchor. Banking compliance mandates are expanding most quickly.
End User:
Customer type determines procurement channel—direct vendor relationships for enterprises, distributor networks for small businesses, and integrated service contracts for health institutions with dual-jurisdiction obligations.
- Enterprises:Multinational organizations with cross-border operations standardize on equipment meeting both EU GDPR and US NIST SP 800-88 frameworks to simplify fleet management.
- Small Businesses:Independent retailers and professional services firms in France purchase through office supply distributors with maintenance bundling.
- Non-Profits:Charitable organizations in Germany access subsidized procurement programs through BSI-certified vendor partnerships.
- Health Institutions:Pharmaceutical manufacturers in Mumbai and Hyderabad under CDSCO documentation control requirements are creating first-time demand for certified destruction equipment.
Enterprises retain the largest installed base. Health institutions are climbing the fastest.
Technology:
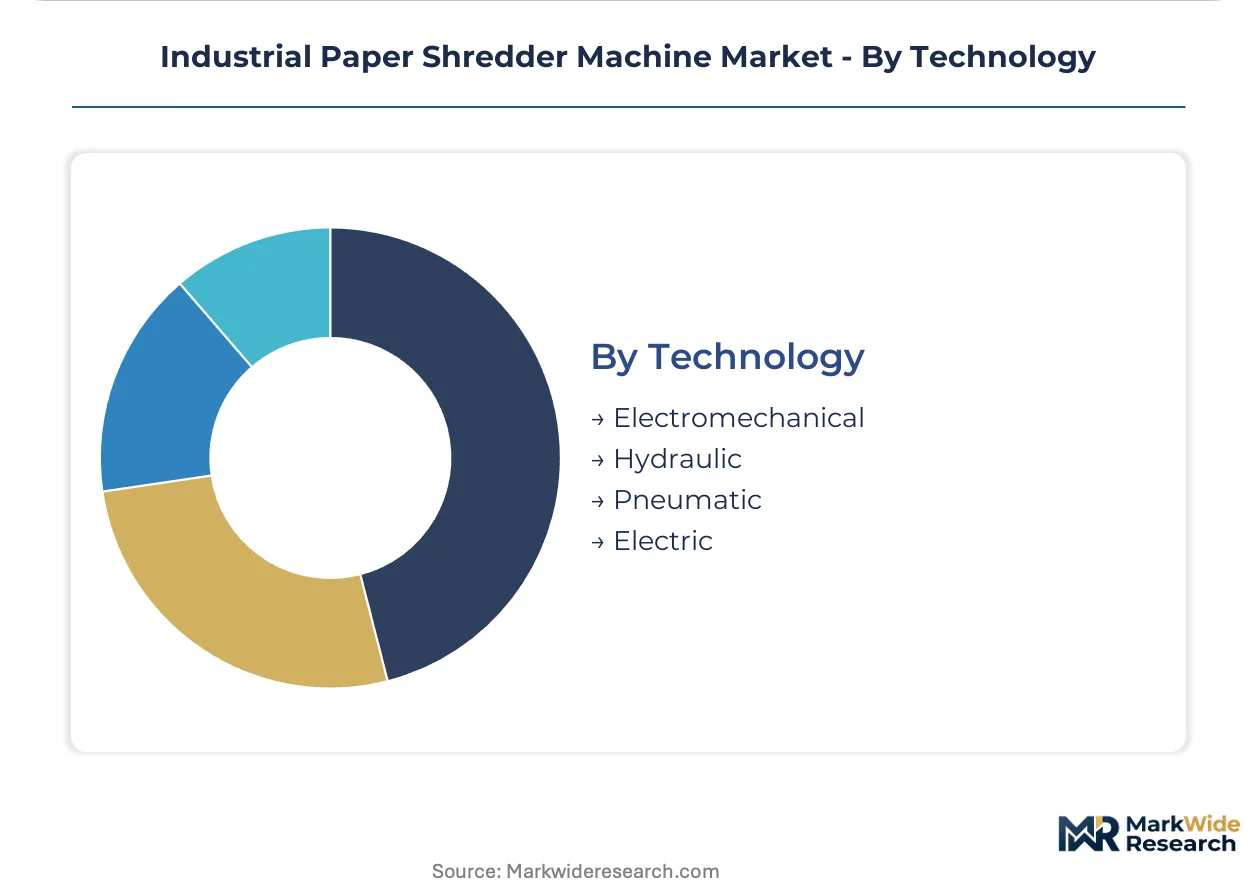
Maturity curves separate electromechanical reliability from hydraulic torque advantages, with pneumatic and electric alternatives occupying niche positions in specialized environments.
- Electromechanical:AC induction motor and gearbox assemblies dominate corporate and government installations where maintenance accessibility and parts availability outweigh raw throughput specifications.
- Hydraulic:Pressurized fluid drives deliver sustained torque under variable load conditions. Continuous-operation recycling plants in Germany specify these systems for particle consistency when processing contaminated or mixed feedstock.
- Pneumatic:Compressed air actuation suits explosive-atmosphere environments in chemical manufacturing facilities with ATEX compliance requirements.
- Electric:Brushless DC motor configurations serve mobile and space-constrained installations requiring reduced noise signatures.
Electromechanical systems anchor the installed base. Hydraulic drives are gaining share fastest in high-throughput recycling operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a shredder equipment trade surplus driven by precision-engineered cutting assembly exports, while the United States and India run structural deficits filled by German and Japanese supply chains.
United States
Federal supply chains and defense contractor procurement anchor domestic absorption. NIST SP 800-88 sanitization protocols compress replacement cycles for aging electromechanical fleets. Washington DC and Northern Virginia intelligence-adjacent facilities specify DIN P-7 certified equipment with tamper-evident logging systems.
Germany
Industrial manufacturing density and corporate compliance standards sustain the highest per-capita installed base. BSI technical guidelines and GDPR Article 17 erasure obligations force banking institutions toward premium equipment. Frankfurt financial centers and Baden-Württemberg precision engineering clusters drive specification-setting for European export markets.
India
Pharmaceutical manufacturing expansion under CDSCO documentation control requirements creates first-time demand for certified destruction equipment. Mumbai and Hyderabad active pharmaceutical ingredient production clusters are procuring industrial-grade shredders for batch record compliance.
Switzerland
FINMA data protection standards mandate micro-cut grades for client file destruction in Zurich and Geneva private banking centers. Swiss banking regulators impose audit failure penalties that compress replacement cycles below continental European averages.
United Kingdom
Classified document handling facilities and defense procurement sustain high-security equipment demand. UK intelligence services specify DIN P-7 equipment with continuous monitoring protocols. London and Southeast England government campuses anchor public sector absorption.
Industrial Paper Shredder Machine Market Competitive Landscape
Concentration sits with German precision engineering specialists and North American distribution-anchored brands. The vendor base organizes around three strategic archetypes: heritage European manufacturers with captive cutting assembly expertise, North American brands leveraging federal supply chain relationships, and recycling-focused heavy-duty specialists. Competitive moves center on IoT-enabled service contract bundling and geographic expansion into Indian pharmaceutical manufacturing clusters.
Among German fabricators, HSM GmbH + Co. KG and Krug & Priester GmbH & Co. KG exemplify the heritage precision engineering archetype with captive manufacturing of hardened steel cutting cylinders. Fellowes Brands represents the North American distribution-anchored model with sustained placement in federal supply chains. Vecoplan LLC occupies the heavy-duty recycling specialist position for continuous-operation industrial environments.
| Leading Market Players |
|---|
| Vecoplan LLC |
| Allegheny Shredders |
| Fellowes Brands |
| Intimus International |
| HSM GmbH + Co. KG |
| Formax |
| Shred-Tech Corporation |
| Krug & Priester GmbH & Co. KG |
| Dahle North America, Inc. |
| Others |
Supply & Pricing Matrix
Scale economies in hardened steel cutting cylinder production concentrate manufacturing capacity in German and Japanese industrial regions, compressing price floors for DIN-certified equipment while elevating entry barriers for non-captive fabricators. This concentration amplifies pricing power for heritage precision engineering specialists serving defense contractors and pharmaceutical manufacturers under multi-jurisdiction compliance mandates.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on DIN certification grade and after-sales service bundling, with DIN P-7 units commanding substantial premiums over P-4 alternatives. Cost compression in mid-tier electromechanical systems is intensifying because alloy price volatility in South African chromium supply feeds through to cutting cylinder manufacturers. Small businesses purchasing through office supply distributors exhibit highest price sensitivity, while banking institutions under FINMA and BSI supervision prioritize certification documentation over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for precision grinding equipment imports into Indian pharmaceutical manufacturing clusters. Supply concentrates in Germany, Japan, and South Korea for hardened steel cutting assemblies, with chromium and molybdenum alloy feedstock drawing from South African mining operations. Single-source vulnerability in precision heat-treatment expertise constrains geographic expansion of manufacturing capacity. Distribution runs through facility management integrators in France and the Netherlands, displacing direct end-user procurement for mid-tier corporate deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR Article 17 erasure obligations and US NIST SP 800-88 sanitization protocols are compressing replacement cycles and forcing equipment upgrades regardless of residual functional life, creating a high-growth disruption window for certified destruction equipment vendors.
For Market Incumbents: Consolidate captive cutting assembly expertise through backward integration into hardened steel cylinder grinding and heat-treatment operations, defending against emerging IoT-enabled service competitors. Lock in pharmaceutical manufacturing relationships in Mumbai and Hyderabad through CDSCO documentation trail capabilities, leveraging dual-jurisdiction FDA-Health Canada compliance bundling as a switching-cost amplifier. For New Entrants and Emerging Players: BSI laboratory testing fast-tracks for DIN P-7 certification offer a regulatory arbitrage path into European banking and defense contractor procurement queues. White-space concentration sits in Indian pharmaceutical manufacturing clusters under CDSCO batch record mandates, with leasing and managed service contract bundling as the preferred go-to-market angle for mid-tier corporate buyers in the Netherlands and Scandinavia. For Investors and Strategic Acquirers: Heritage German fabricators with captive precision engineering capabilities represent the priority acquisition archetype, given irreplaceable technician expertise concentration in Baden-Württemberg industrial regions. Long-term viability across the analysis window rests on software-enabled service contract attachment rates rather than equipment shipment volumes alone. The signal to watch is IoT predictive maintenance penetration in facility management provider portfolios, indicating service model transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cutting Cylinder Manufacturing | Captive production of hardened steel assemblies insulates HSM GmbH + Co. KG and Krug & Priester from South African alloy price volatility. |
| IoT-Enabled Predictive Maintenance Platform Launch | Sensor-integrated shredders with blade-wear algorithms command service contract premiums from French facility management providers. |
| CDSCO Certification Fast-Track Investment | DIN P-7 documentation trails accelerate penetration into Mumbai and Hyderabad pharmaceutical manufacturing clusters under batch record mandates. |
| Managed Service Contract Bundling | Shredder-as-a-service arrangements in the Netherlands and Scandinavia displace capital purchase models and concentrate vendor relationships. |
| Hydraulic Drive System Expansion | Pressurized fluid configurations serve German continuous-operation recycling plants where torque demands exceed electromechanical motor capacities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with maintenance directors at German automotive manufacturers, plant engineers at Swiss banking facilities, OEM procurement teams in North American federal supply chains, and aftermarket service heads at recycling operations providing operational validation. Secondary sources included BSI technical guideline documentation, FDA and Health Canada pharmaceutical inspection protocols, CDSCO batch record regulations, customs and trade data on hardened steel alloy imports, and SEC filings from publicly traded facility management providers. Bottom-up equipment shipment estimates were triangulated against top-down compliance mandate penetration models.
The projection horizon spans from base year through forecast terminus, with segmentation modeling across product type, application, end user, and technology dimensions. CAGRs were derived from regression analysis of historical replacement cycle compression under GDPR and NIST regulatory frameworks, with input variables including DIN certification adoption curves, pharmaceutical manufacturing capacity expansion in India, and IoT sensor integration rates in European service contracts.
Underlying assumptions cover sustained regulatory enforcement intensity across EU GDPR and US NIST frameworks, with deviation risk concentrated in digital document substitution velocity in Scandinavian and Dutch enterprise environments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
NCR Laser Paper Market
Paper Products
Europe Decor Paper Market
Paper Products
Africa Tissue Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Base Paper Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Recording Chart Paper Market
Paper Products
Ceramic Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
White Top Testliner Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Paper Machinery Market
Paper Products
Inlay Paper Market