
 Aluminum Recycling Market | 2026-2036
Aluminum Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Recycling Market Analysis
The widening purity gap between aerospace-grade recycled aluminum and general commodity scrap is repositioning tier strategy across the industry. Novelis leverages its closed-loop automotive partnerships to sustain premium pricing on certified alloys. Matalco Inc. anchors its competitiveness through geographic density in North American industrial corridors. Emirates Global Aluminium differentiates via integrated primary-to-recycled operations that control energy costs.
Aluminum recycling recovers metallic aluminum from post-consumer and industrial scrap through melting, refining, and alloying processes, typically achieving energy savings of roughly 95 percent versus primary electrolytic production. The output serves as feedstock for extrusion, rolling, and casting operations across transportation and packaging industries. Scrap metal and post-consumer waste dominate material source volumes, though industrial waste streams command tighter chemistry control and higher unit margins. Within end users, automotive applications lead absolute consumption while packaging segments expand fastest under single-substrate sustainability mandates. Mechanical recycling remains the baseline method, but advanced recycling technologies are capturing investment aimed at handling complex multi-alloy scrap streams.
The EPA enforces hazardous waste rules affecting smelter byproduct handling, while OSHA sets exposure limits for molten metal operations that shape facility design and labor costs. REACH compliance in Europe restricts certain alloying element thresholds, redirecting formulation R&D toward compliant substitute chemistries. Stakeholders must monitor how carbon accounting standards evolve to verify recycled content claims, as certification integrity becomes the decisive factor in contract eligibility.
Market Dynamics
The EU Carbon Border Adjustment Mechanism is redirecting procurement flows toward verified recycled content as importers face tightening compliance costs on primary aluminum. Automotive OEMs are expanding closed-loop sourcing programs to secure low-carbon feedstock for their manufacturing operations.
Growth Catalysts
- EU CBAM compliance pressure:Import tariffs on carbon-intensive primary aluminum are accelerating demand for certified recycled alloys across European manufacturing supply chains.
- Automotive closed-loop partnerships:OEMs are binding multi-year supply agreements with secondary smelters to lock in low-carbon aluminum volumes for electric vehicle production.
- Mechanical recycling advancement:Sorting and shredding technologies are improving recovery rates from complex multi-alloy scrap streams previously sent to landfill.
Market Restraints
- Scrap supply concentration:Post-consumer aluminum scrap flows concentrate in Germany's industrial corridor, creating geographic vulnerability for processors elsewhere.
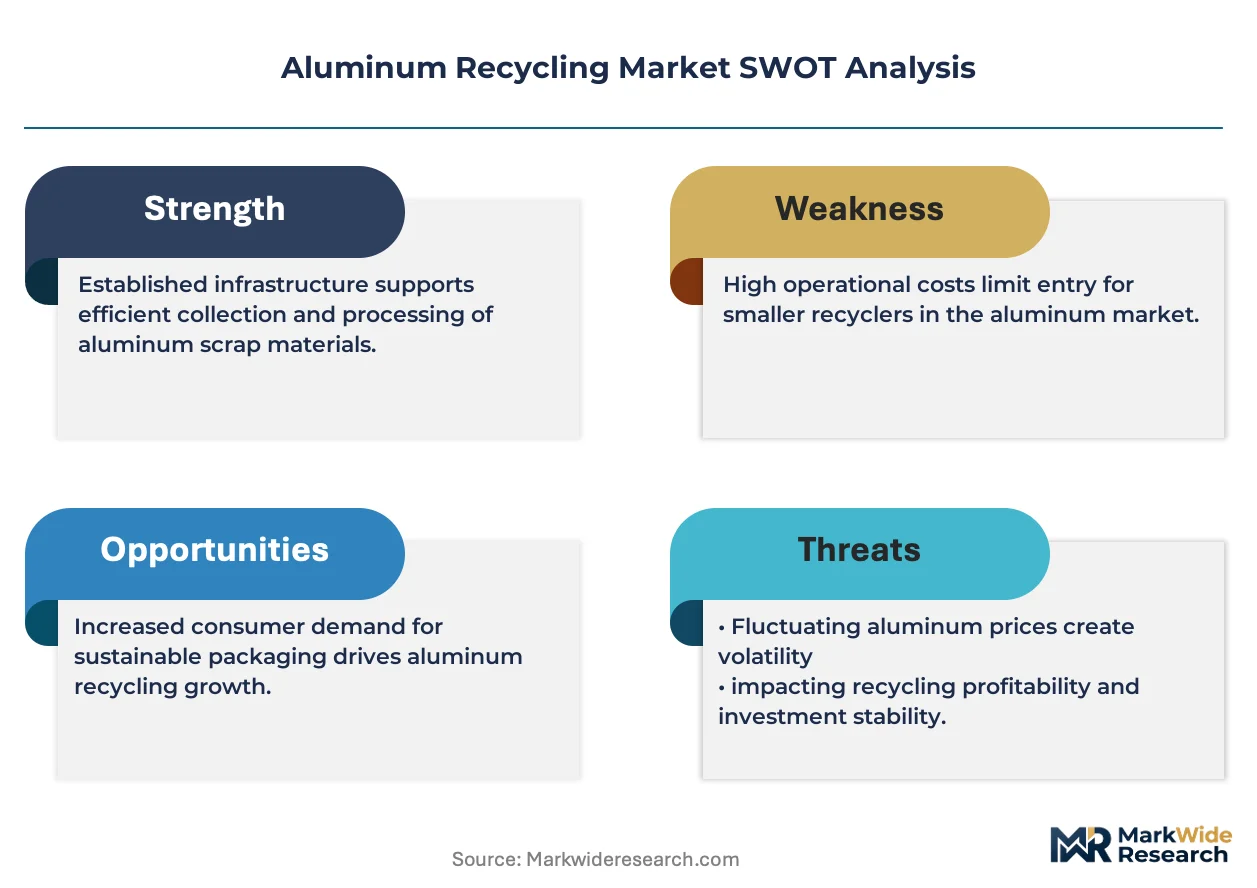
- Energy cost volatility:Secondary smelters face margin compression from natural gas and electricity price swings that erode the energy savings advantage over primary production.
- REACH alloying restrictions:European chemical regulations limit certain element thresholds in recycled formulations, forcing costly R&D into substitute chemistries.
Strategic Opportunities
- North American industrial corridor density:Secondary smelters can anchor competitiveness through geographic clustering near automotive and packaging manufacturing hubs.
- Packaging sustainability mandates:Single-substrate requirements in beverage and food containers are opening premium pricing for high-purity recycled aluminum.
- Integrated primary-to-recycled operations:Energy cost control through captive power generation and process heat integration offers structural margin advantages.
Industry Challenges
- Carbon accounting certification timelines:Third-party verification of recycled content claims requires extended audit periods that delay contract eligibility for new suppliers.
- Multi-alloy separation expertise:The widening purity gap between aerospace-grade and commodity scrap demands specialized metallurgical talent that remains scarce in secondary smelting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Recycling Market |
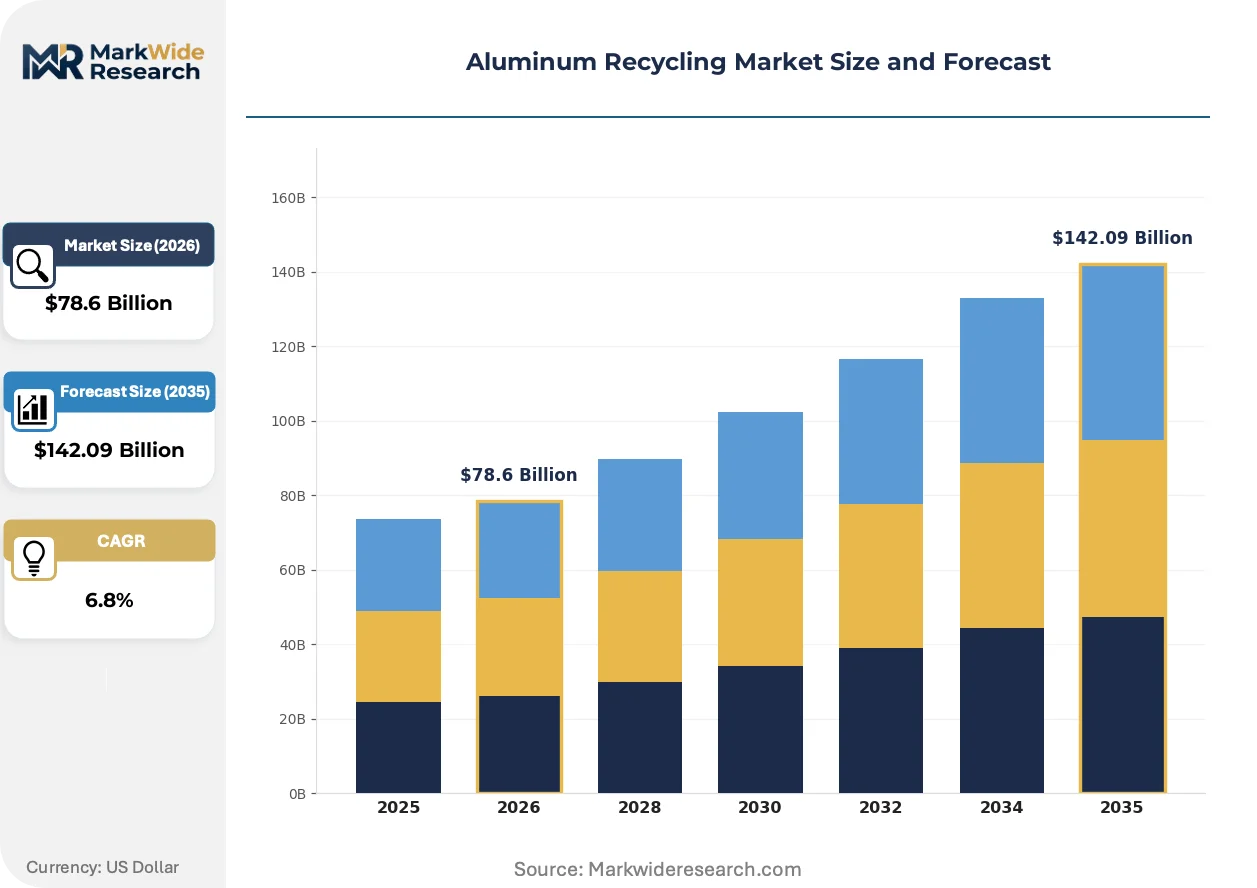
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Shredding, Melting, Refining, Casting End User: Automotive, Packaging, Construction, Consumer Goods Recycling Method: Chemical Recycling, Mechanical Recycling, Thermal Recycling, Advanced Recycling Material Source: Scrap Metal, Post-Consumer Waste, Industrial Waste, Others |
| Companies Covered | Speira, Matalco Inc., Novelis Inc., Emirates Global Aluminium, AMAG Austria Metall AG, Norsk Hydro ASA, REAL ALLOY, Alcoa Corporation, Constellium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Recycling Market Emerging Trajectories
Advanced recycling technologies are capturing investment aimed at handling complex scrap streams that mechanical methods cannot process efficiently. These innovations are reshaping how the industry recovers value from contaminated and mixed-alloy inputs.
Pyrometallurgical refining systems are absorbing capital deployment from processors seeking to extract aluminum from dross and salt cake residues previously treated as waste. Automotive tier suppliers are piloting these units at scale to reclaim metallic content from manufacturing byproducts. The technology is absorbing margin pressure from rising landfill costs and tightening EPA hazardous waste rules.
REACH compliance in Europe is restricting certain alloying element thresholds in recycled aluminum formulations. Manufacturers are redirecting R&D spending toward compliant substitute chemistries that maintain performance specifications. Packaging applications face the tightest reformulation timelines as brand owners accelerate sustainability commitments ahead of regulatory deadlines.
Buyer concentration among automotive OEMs is compressing supplier negotiation leverage and extending contract durations. Tier-one processors are responding by embedding technical service teams within customer engineering departments to secure preferred supplier status. Germany's industrial corridor exhibits the most pronounced consolidation of procurement decision-making across European aluminum recycling.
Aluminum Recycling Market Segmentation
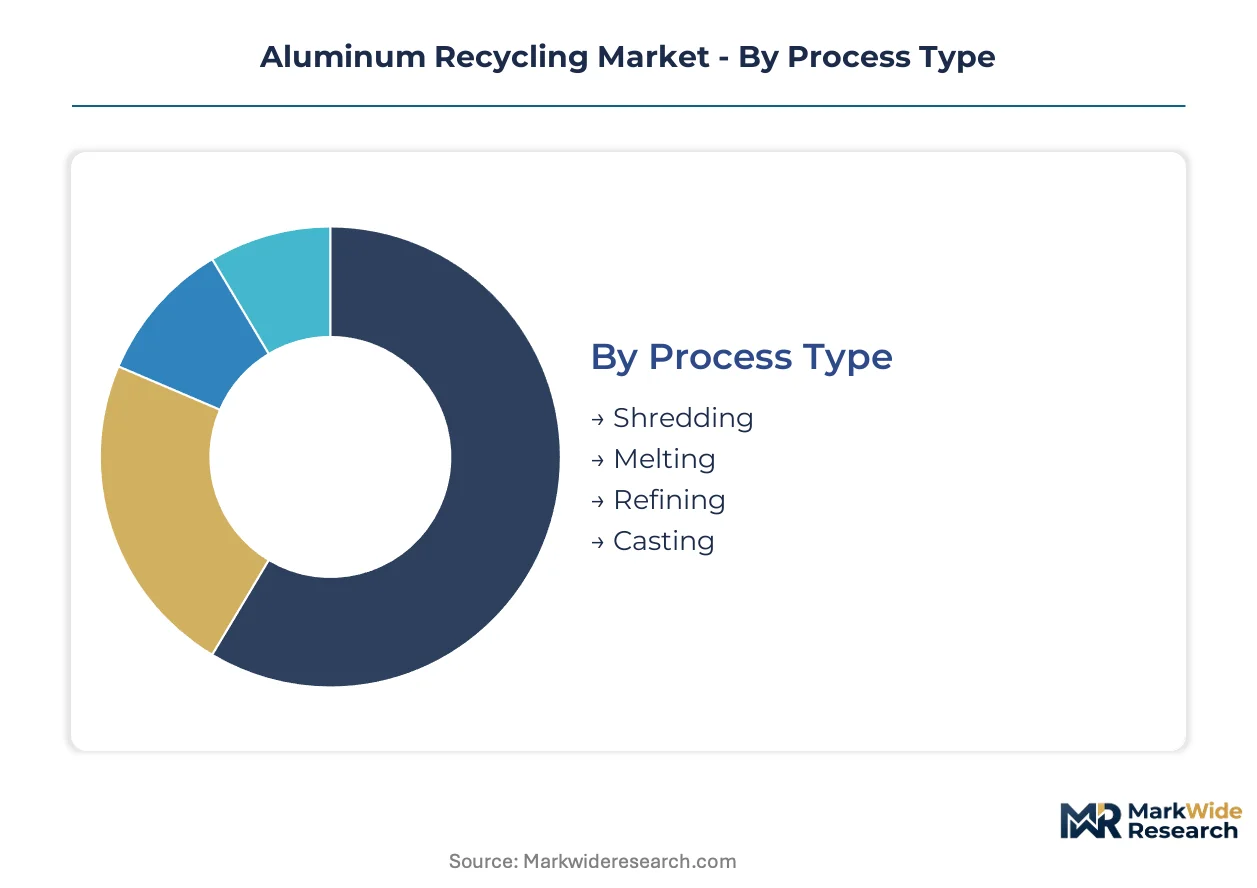
Aluminum recycling segments diverge sharply in certification requirements and margin profiles. Process type determines energy intensity and regulatory exposure, while end-user specifications dictate alloy purity thresholds and contract structures.
Process Type:
EPA hazardous waste rules and OSHA molten metal exposure limits apply differentially across process stages, with refining and casting carrying the heaviest compliance burdens.
- Shredding:Front-end size reduction of scrap streams using hammer mills and shears to liberate metallic aluminum from contaminants and coatings. Demand concentrates in North American industrial corridors near automotive stamping plants, driven by closed-loop sourcing programs that require just-in-time scrap preparation.
- Melting:Rotary and reverberatory furnaces convert shredded feedstock into molten metal at roughly 5% of primary smelting energy intensity. Germany's industrial corridor hosts the densest concentration of large-scale secondary smelters serving OEM supply chains under EU CBAM compliance pressure.
- Refining:Fluxing and degassing operations remove hydrogen and non-metallic inclusions to meet aerospace and automotive chemistry specifications.
- Casting:Direct chill and continuous casting systems solidify refined metal into rolling slab or extrusion billet for downstream fabrication.
Melting sits at the top of the volume ranking, with advanced shredding and sorting systems climbing the fastest.
End User:
Customer concentration and contract duration vary dramatically by end-use sector, with automotive procurement teams wielding the greatest pricing leverage.
- Automotive:Body sheet, structural castings, and battery enclosure extrusions requiring certified low-carbon aluminum with full supply chain traceability. German, US, and Japanese OEMs are binding multi-year supply agreements with secondary smelters to lock in volumes for electric vehicle platforms.
- Packaging:Beverage can sheet and food container foil demanding high-purity alloys with tight contamination controls. Single-substrate sustainability mandates from brand owners in the United States and Europe are opening premium pricing tiers for verified recycled content.
- Construction:Window frames, roofing, and structural extrusions with more permissive chemistry tolerances and spot-market procurement patterns.
- Consumer Goods:Appliances, electronics housings, and furniture components representing fragmented demand with limited scale economies.
Automotive commands the largest absolute tonnage, though packaging applications are expanding most quickly under regulatory and brand-owner pressure.
Recycling Method:
Capital intensity and technical risk profiles separate established mechanical approaches from emerging advanced technologies.
- Chemical Recycling:Hydrometallurgical and solvometallurgical processes that dissolve aluminum from complex multi-alloy scrap and dross residues. Pilot deployments in Germany and Belgium target recovery from salt cake byproducts previously landfilled under tightening EPA and REACH hazardous waste rules.
- Mechanical Recycling:Sorting, shredding, and remelting of single-alloy scrap streams without chemical transformation. This baseline method dominates current volumes across US and European secondary smelters due to lower capital requirements and established operational expertise.
- Thermal Recycling:Pyrometallurgical refining of dross and skimmings to reclaim metallic aluminum from oxidation products.
- Advanced Recycling:Integrated sensor-based sorting, laser-induced breakdown spectroscopy, and artificial intelligence-driven alloy separation enabling processing of mixed-grade scrap streams.
Mechanical recycling retains the dominant share, while advanced recycling technologies are gaining investment traction for handling contaminated inputs.
Material Source:
Scrap origin determines chemistry control, volume predictability, and margin structure for secondary smelters.
- Scrap Metal:Post-consumer collected aluminum from municipal recycling programs and demolition activities with variable alloy composition and contamination levels. Collection infrastructure in Germany's industrial corridor and the US Great Lakes region generates the most reliable high-volume flows.
- Post-Consumer Waste:Used beverage cans, end-of-life vehicles, and retired building materials requiring extensive sorting and delacquering before remelting. Deposit-return schemes in Germany, Norway, and several US states provide cleaner, more predictable feedstock than curbside collection.
- Industrial Waste:Manufacturing scrap, dross, and trimmings from primary and secondary production with tight chemistry documentation and premium pricing.
- Others:Foundry returns, obsolete military stockpiles, and specialized aerospace scrap requiring custom handling protocols.
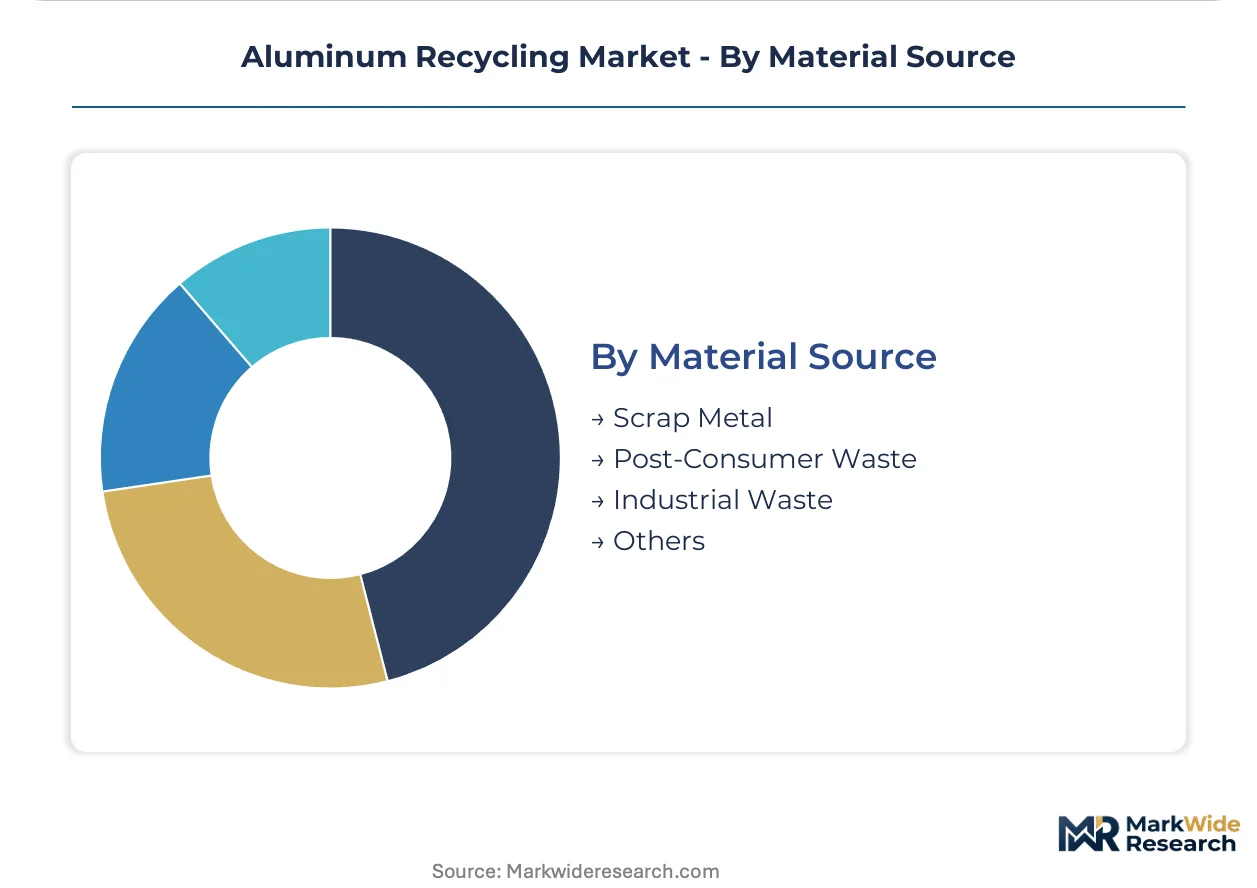
Scrap metal and post-consumer waste together dominate tonnage inputs, with industrial waste streams delivering the highest unit margins through chemistry certainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallurgical engineers and furnace operators concentrate in Germany's industrial corridor, anchoring European secondary smelting capacity. Chinese technicians dominate pyrometallurgical refining scale. North American talent clusters around automotive stamping plant networks.
Germany
Automotive OEMs in Stuttgart and Munich bind multi-year supply agreements with secondary smelters for electric vehicle platforms. The EU Carbon Border Adjustment Mechanism tightens compliance costs on primary aluminum imports, redirecting procurement toward verified recycled content. Speira and Novelis operate large-scale secondary smelters in the Rhine-Ruhr industrial corridor serving OEM supply chains.
United States
Closed-loop sourcing programs from Detroit and Tennessee automotive manufacturers secure low-carbon feedstock volumes. EPA hazardous waste rules governing smelter byproduct handling shape facility design and operating permits. Matalco Inc. anchors operations in Great Lakes industrial corridors near stamping plant networks.
China
Packaging sustainability mandates from beverage brand owners accelerate demand for high-purity recycled aluminum sheet. The Ministry of Ecology and Environment enforces dual carbon goals that favor secondary production over electrolytic smelting. Yangtze River Delta clusters around Shanghai host dense concentrations of sorting and remelting capacity.
United Arab Emirates
Integrated primary-to-recycled operations control energy costs through captive power generation at Gulf smelting complexes. The country's national environmental regulator enforces tightening standards on dross landfill disposal. Emirates Global Aluminium operates secondary refining capacity alongside primary electrolytic lines in Jebel Ali industrial zones.
Japan
Automotive tier suppliers pilot pyrometallurgical refining systems to reclaim metallic content from manufacturing byproducts. METI industrial policy supports advanced recycling technology deployment under resource circularity targets. Chubu region around Nagoya hosts specialized dross processing facilities serving Toyota and Honda supply chains.
Aluminum Recycling Market Vendor Landscape
Capital-heavy producers compete with asset-light traders across divergent margin structures. Secondary smelters with captive energy assets face off against merchant processors exposed to electricity price volatility. Three archetypes dominate: integrated primary-to-recycled operators controlling energy costs, automotive-captive specialists leveraging closed-loop partnerships, and geographic density players anchoring competitiveness through industrial corridor clustering. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with processors embedding technical service teams within customer engineering departments to secure preferred supplier status.
Within the integrated operator archetype, Emirates Global Aluminium exemplifies energy cost control through captive power generation. Among European automotive-captive specialists, Speira and Novelis occupy positions defined by OEM partnership density. These named entities anchor industry-level commentary on how certification integrity and closed-loop sourcing programs determine contract eligibility rather than commodity pricing alone.
| Leading Market Players |
|---|
| Speira |
| Matalco Inc. |
| Novelis Inc. |
| Emirates Global Aluminium |
| AMAG Austria Metall AG |
| Norsk Hydro ASA |
| REAL ALLOY |
| Alcoa Corporation |
| Constellium |
| Others |
Supply Flow & Price Mechanics
Captive energy integration at Gulf smelting complexes anchors both supply security and pricing power for secondary aluminum producers. Emirates Global Aluminium leverages in-house power generation to insulate margins from electricity volatility that compresses merchant processors elsewhere.
Pricing Analysis
Alloy-certification bundling separates contract structures in this market. Premium-mid-economy pricing differentiation tracks carbon accounting tiers and REACH compliance status. Cost compression in commodity-grade scrap is intensifying because automotive OEMs demand full supply chain traceability. Tier-one suppliers with verified low-carbon content face the least price sensitivity, while spot-market traders in construction-grade material absorb the most.
Supply Chain Analysis
EU CBAM domestic-content mandates are reshaping sourcing toward verified recycled feedstock within European boundaries. Supply concentrates in Germany, the United States, and China, with scrap flows drawing from automotive stamping networks and deposit-return collection systems. Raw material dependencies rest on post-consumer beverage can streams, manufacturing dross residues, and end-of-life vehicle hulks. Single-source vulnerability runs through Germany's industrial corridor, where Speira and Novelis secondary smelters dominate OEM procurement. Distribution runs through long-term offtake agreements rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aluminum recycling hinges on carbon-accounting certification premiums offsetting energy cost volatility. The shift toward closed-loop automotive partnerships creates structural pricing power for verified low-carbon suppliers.
For Market Incumbents: Lock in multi-year closed-loop agreements with Stuttgart and Munich automotive OEMs before EU CBAM compliance deadlines tighten. Anchor capacity expansion in Germany's Rhine-Ruhr corridor to exploit geographic clustering advantages. Invest in pyrometallurgical refining systems to reclaim metallic content from dross residues as EPA hazardous waste rules tighten landfill restrictions. For New Entrants and Emerging Players: The premium-to-economy price gap in aerospace-grade recycled aluminum opens white-space targets in specialized alloy separation. Target North American packaging sustainability mandates where single-substrate requirements outpace certified supply. Deploy advanced sensor-based sorting technology to handle complex multi-alloy scrap streams that mechanical methods cannot process efficiently. For Investors and Strategic Acquirers: Roll-up economics work for regional secondary smelters because carbon accounting certification creates barriers that favor scaled incumbents with audit infrastructure. Long-term viability centers on integrated primary-to-recycled operators controlling captive energy assets. Watch for inflection when automotive OEM procurement teams embed technical service requirements into supplier qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Supply Agreement | Stuttgart OEMs bind multi-year volumes with Speira under EU CBAM pressure. |
| Captive Power Integration | Gulf smelting complexes control energy costs through in-house generation assets. |
| Advanced Sorting Technology Deployment | AI-driven alloy separation enables processing of contaminated mixed-grade scrap. |
| Carbon Certification Investment | Third-party verification unlocks contract eligibility for European automotive supply chains. |
| Pyrometallurgical Refining Scale-Up | Dross reclamation units absorb capital as EPA rules tighten hazardous waste disposal. |
Methodological Framework
Coverage spans Germany, the United States, China, and the United Arab Emirates, with primary inputs from each market. The analysis combines interviews with secondary smelter operations managers, automotive OEM procurement leads, aluminum scrap traders, and regulatory compliance officers with secondary validation from EPA filings, REACH substance databases, EU CBAM implementation guidance, and customs trade data. Bottom-up scrap flow modeling and top-down alloy demand estimates were triangulated to anchor volume projections.
Granularity-level modeling tracked process type, end-use sector, recycling method, and material source dimensions across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro aluminum demand drivers. Forecast inputs incorporated automotive electric vehicle platform rollout schedules and packaging sustainability mandate adoption curves without specifying timeline milestones.
The model assumes a particular technology adoption path; alternative pathways for hydrometallurgical and solvometallurgical recycling would alter the outlook if capital deployment shifts from mechanical methods. Forecasts reflect assumptions about EU CBAM enforcement intensity and natural gas price normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled PET Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
North America Plastic Waste Management Market