
 Global Ferrous Scrap Recycling Market | 2026-2036
Global Ferrous Scrap Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ferrous Scrap Recycling Market Foresight
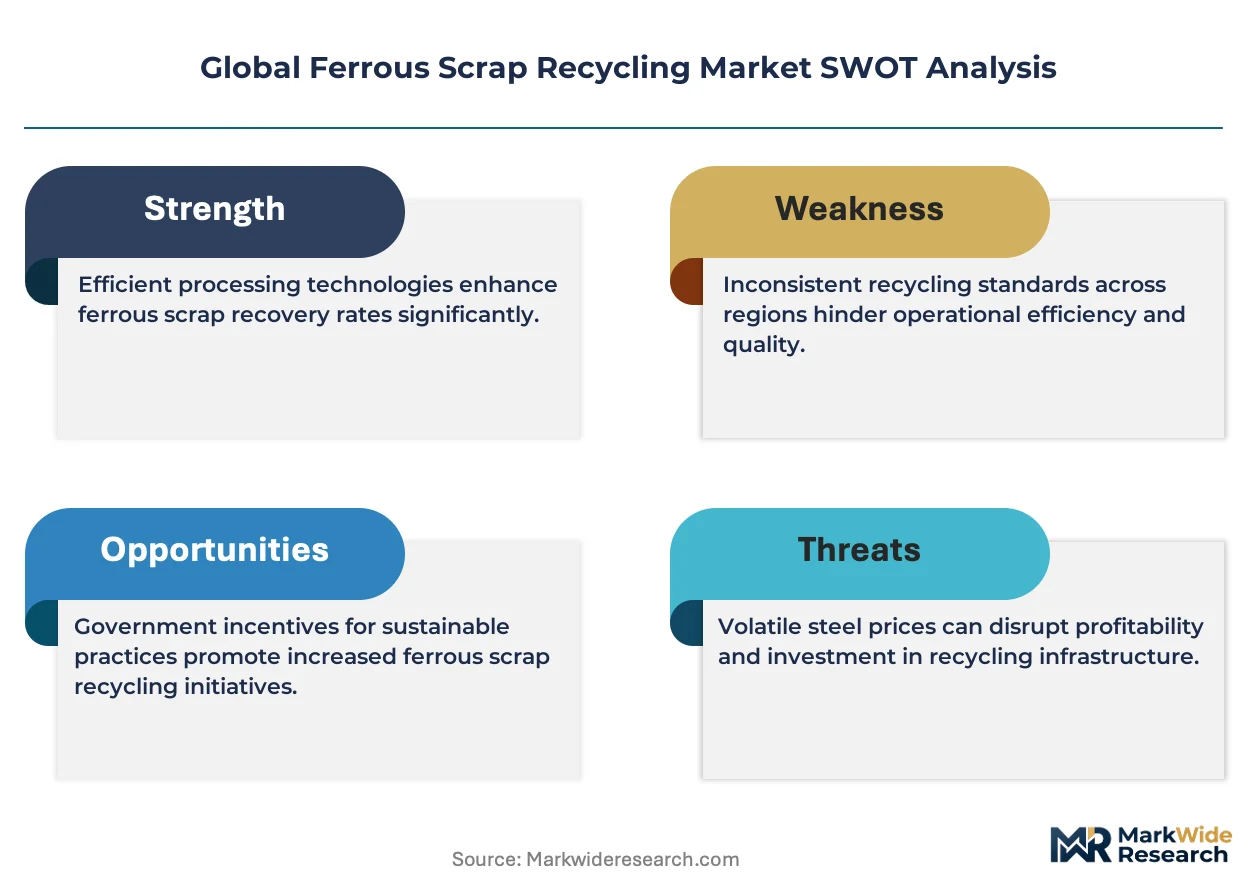
The EU Carbon Border Adjustment Mechanism is repositioning ferrous scrap trade flows, compelling steelmakers to document embedded carbon in recycled feedstock. Sims Limited leverages advanced shredding infrastructure across Australia and North America to capture premium grades for low-carbon steelmaking. European Metal Recycling Limited anchors its competitiveness through deep port access and dense collection networks across the United Kingdom, Germany, and the Netherlands. Steel Dynamics, Inc. dominates North American electric arc furnace production by sustaining backward integration into scrap collection and processing.
Ferrous scrap recycling encompasses the recovery, processing, and re-melting of iron-containing metallic waste, typically with iron content exceeding 50 percent and processed through shredding, magnetic separation, or shearing to achieve density and purity specifications for furnace charging. The practice displaces virgin iron ore demand while cutting energy use in steelmaking by roughly two-thirds compared to blast furnace routes. Industrial scrap from manufacturing offcuts commands stable volume and predictable chemistry, making it the foundation of premium pricing pools. Shredded scrap from end-of-life vehicles and appliances represents the fastest-expanding product form as automotive lightweighting accelerates obsolete unit generation. End-use concentration in electric arc furnace steel mills drives procurement scale, though foundry demand for high-purity bundles sustains niche margin premiums.
The US EPA enforces hazardous waste exclusions and air quality standards that shape shredder permitting and downstream slag management, while China's SAMR implements import purity thresholds that redirect regional trade flows. The EU REACH framework and F-Gas Regulation indirectly constrain processing chemistry and emissions profiles for scrap-derived steel entering European value chains. Stakeholders must monitor how carbon accounting standards and scrap quality specifications converge to determine market access and contract premiums.
Market Dynamics
Carbon accounting mandates embedded in the EU Carbon Border Adjustment Mechanism are restructuring procurement hierarchies for ferrous scrap, forcing steelmakers to document and certify embedded emissions in every ton of recycled feedstock traded across borders.
Growth Catalysts
- EU CBAM compliance pressure:European steelmakers now prioritize verified low-carbon scrap grades, creating premium pricing tiers for suppliers with certified emission documentation.
- India's secondary steel buildout:Rapid electric arc furnace capacity expansion in Gujarat, Odisha, and Karnataka is pulling shredded scrap imports from traditional Turkish buyers.
- Automotive lightweighting obsolescence:Aluminum-intensive vehicle designs are accelerating retirement cycles for steel-bodied fleets, swelling end-of-life vehicle scrap generation.
Market Restraints
- Natural gas price volatility:Shredder operations and electric arc furnace steelmaking face margin compression when European and Asian gas benchmarks spike.
- China's SAMR import purity thresholds:Strict contamination limits on ferrous scrap imports have redirected regional trade flows away from Chinese ports.
- Copper wire contamination in shredded grades:Persistent mechanical separation limitations create chemistry penalties and furnace operational risks for unprepared scrap.
Strategic Opportunities
- Underpenetrated Indonesian market:Limited domestic scrap collection infrastructure creates import-dependent supply gaps as Krakatau Steel expands electric arc furnace output.
- EU F-Gas Regulation alignment:Refrigerant recovery mandates from end-of-life appliances generate certified feedstock streams for compliant shredder operators.
- Sensor-based sorting convergence:X-ray fluorescence and laser-induced breakdown spectroscopy integration enables real-time chemistry verification for premium grade segregation.
Industry Challenges
- Scrap sorter technician shortage:Specialized skills in non-ferrous separation and spectroscopic quality verification remain scarce across North American and European yards.
- Shredder residue landfill constraints:EPA hazardous waste exclusions and state-level landfill restrictions complicate fluff and automotive shredder residue disposal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ferrous Scrap Recycling Market |
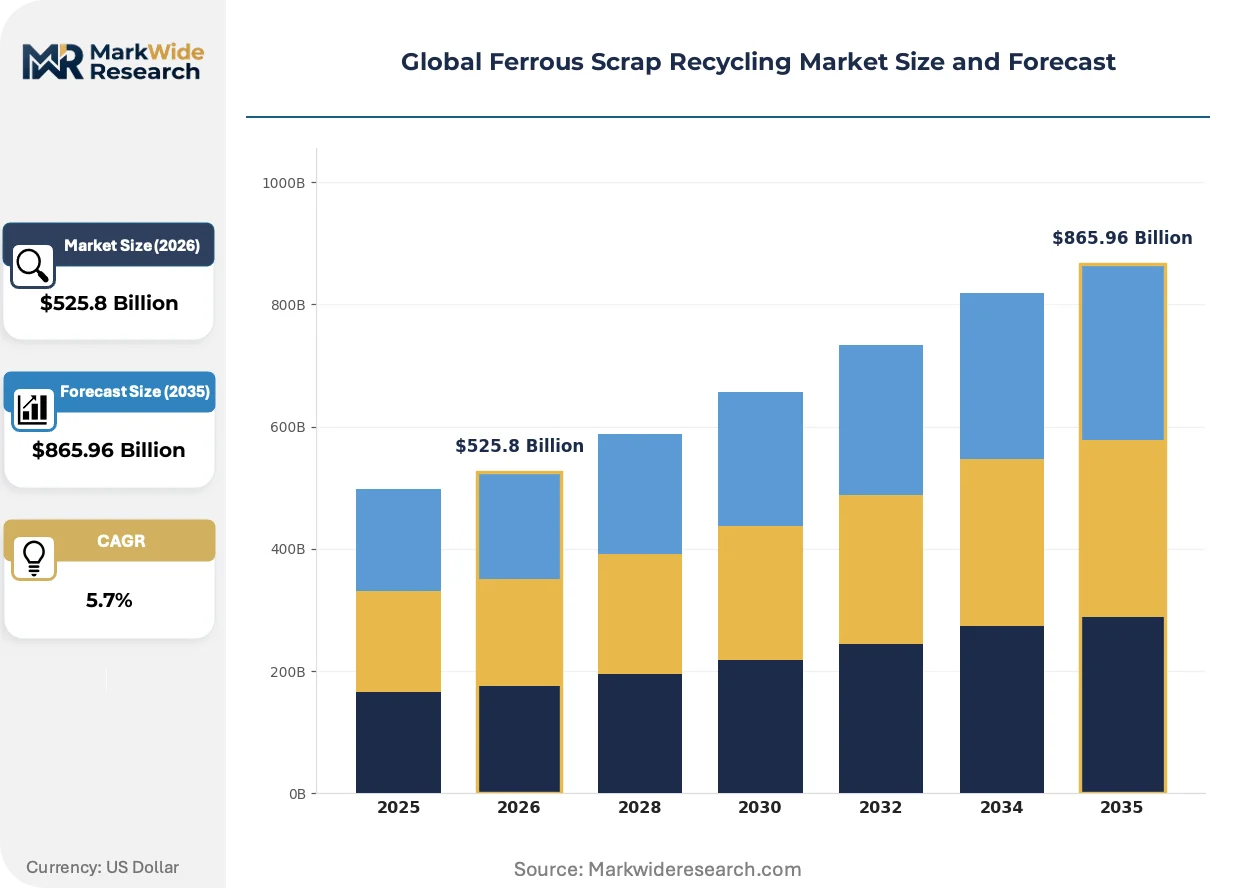
| Market Size in 2026 | $525.8 Billion |
| Market Size in 2035 | $865.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
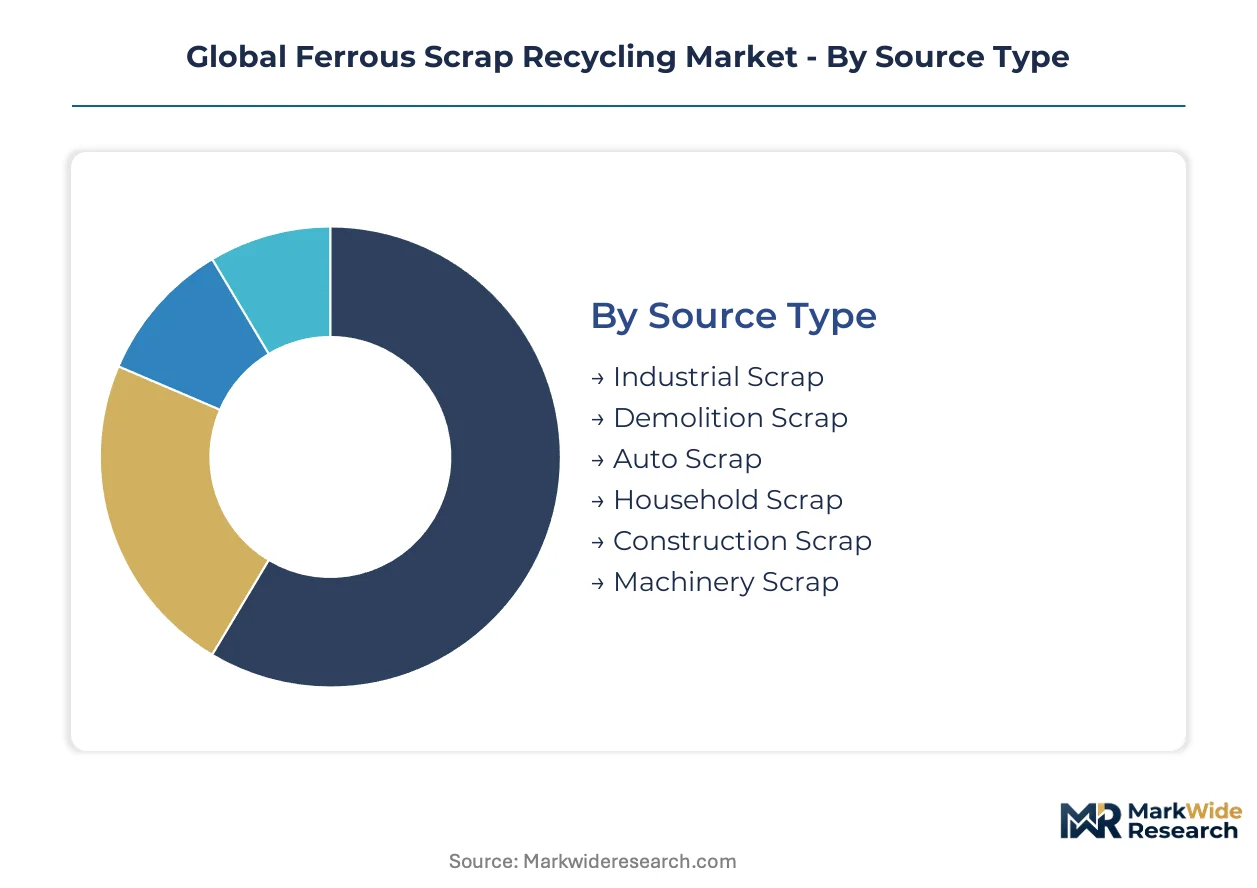
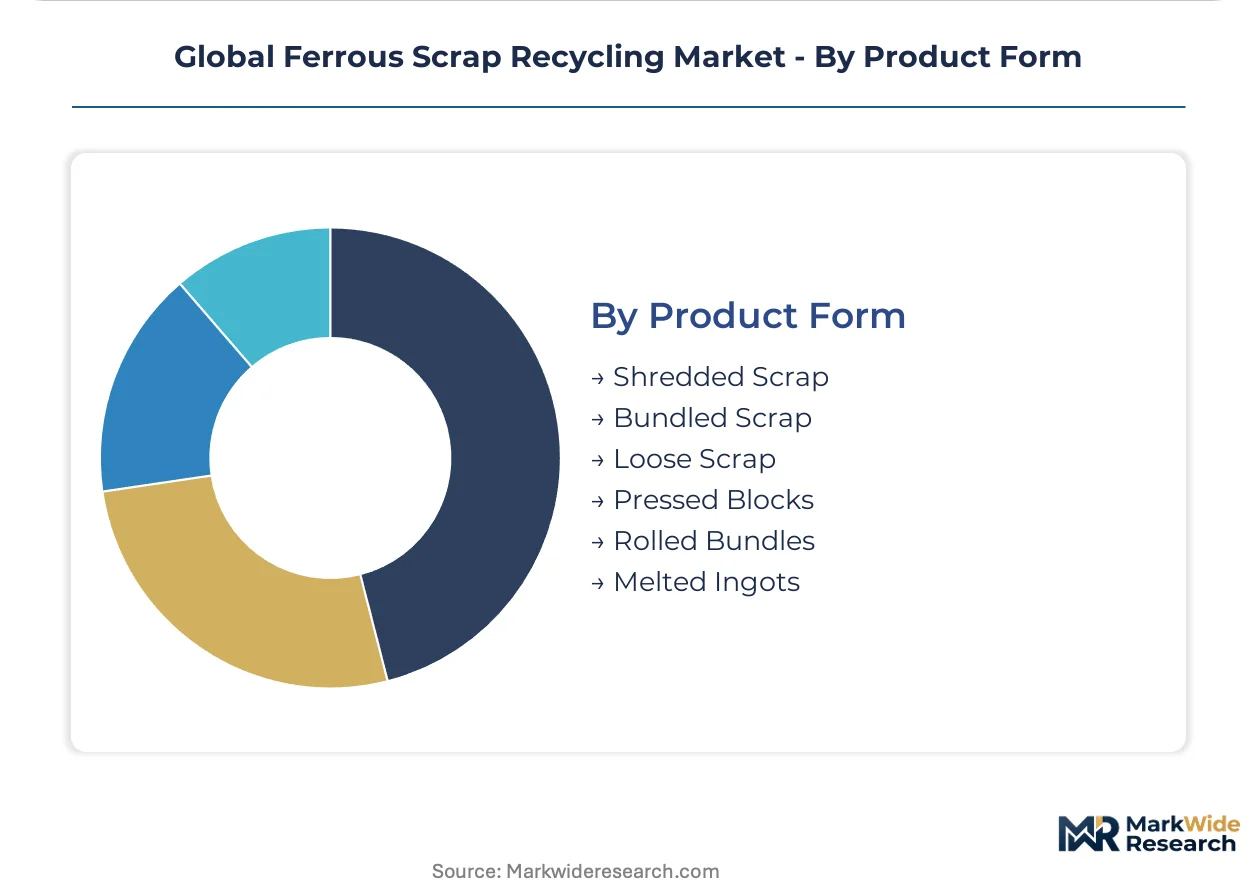
| Segmentation | Source Type: Industrial Scrap, Demolition Scrap, Auto Scrap, Household Scrap, Construction Scrap, Machinery Scrap Processing Method: Magnetic Separation, Eddy Current Separation, Shredding, Balancing, Shearing, Sorting End-Use Sector: Manufacturing, Foundries, Steel Mills, Heavy Machinery Production, Shipbuilding, Electrical Equipment Product Form: Shredded Scrap, Bundled Scrap, Loose Scrap, Pressed Blocks, Rolled Bundles, Melted Ingots |
| Companies Covered | Commercial Metals Company, China Metal Recycling (Holdings) Limited, European Metal Recycling Limited, Mitsubishi Materials Corporation, Veolia Environnement S.A., Sims Limited, Steel Dynamics, Inc., Kuusakoski Oy, Schnitzer Steel Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ferrous Scrap Recycling Market Shifts & Advancements
Digital traceability infrastructure and automated material recognition systems are displacing manual grading and paper-based chain-of-custody documentation across ferrous scrap value chains.
Artificial intelligence-driven robotic sorting is rewriting quality control economics in high-volume shredding operations. European Metal Recycling and Sims Limited have deployed computer-vision-equipped picker systems at Rotterdam and Chicago facilities. These installations compress labor costs while raising bundle chemistry consistency for electric arc furnace customers demanding narrow specification windows.
REACH framework amendments on persistent organic pollutants are tightening allowable concentrations in scrap-derived steel entering European manufacturing. Downstream automotive and appliance OEMs now require smelter-level documentation of contaminant screening protocols. Turkish mills serving EU export markets have responded by sourcing exclusively from shredders with certified downstream slag management systems.
Steelmakers are consolidating procurement relationships around long-term offtake agreements with embedded carbon guarantees. This behavior shift displaces spot market purchasing for volume cover. The transformation is most visible in Germany, where Thyssenkrupp and Salzgitter have locked three-to-five-year supply contracts with dedicated shredder operators holding EU-approved mass-balance certification.
Global Ferrous Scrap Recycling Market Segmentation
Ferrous scrap markets fragment across four dimensions that determine pricing tiers, processing margins, and furnace compatibility. Each segmentation axis creates distinct supply chain configurations and procurement hierarchies for electric arc furnace operators.
Source Type:
Industrial scrap concentrates in manufacturing corridors with dense automotive and appliance production, while demolition and construction scrap clusters around urban renewal zones with established decommissioning contractors.
- Industrial Scrap:Manufacturing offcuts from stamping, machining, and forging operations deliver predictable chemistry and minimal surface contamination. Steel mills in Turkey and India prioritize these streams for flat-rolled production requiring tight carbon and sulfur windows.
- Auto Scrap:End-of-life vehicles generate the highest-volume obsolete feedstock as global fleet turnover accelerates. Shredded auto scrap flows predominantly to electric arc furnace operators in the United States, Germany, and Japan seeking density advantages in furnace charging.
- Demolition Scrap:Structural steel from decommissioned infrastructure carries embedded concrete and coating residues requiring pre-processing.
- Household Scrap:Post-consumer appliances and white goods feed shredder networks with seasonal collection patterns.
- Construction Scrap:Reinforcing bar and structural sections from building sites command regional pricing premiums near major metropolitan construction zones.
- Machinery Scrap:Obsolete industrial equipment yields heavy-section feedstock for foundry remelting applications.
Industrial scrap absorbs the bulk of installed capacity; auto scrap is expanding most quickly.
Processing Method:
Capital intensity and energy costs stratify processing economics, with shredding requiring the heaviest infrastructure investment and magnetic separation offering the lowest barrier to entry.
- Shredding:Hammermill systems reduce end-of-life vehicles and appliances to fist-sized fragments with 95%+ ferrous recovery rates. European Metal Recycling and Sims Limited operate the largest installed shredding bases, serving steelmakers with density-specified grades.
- Magnetic Separation:Drum and belt magnets extract ferrous fractions from mixed waste streams at minimal operating cost. This method dominates initial recovery stages at municipal solid waste facilities across India and Brazil.
- Eddy Current Separation:Rotating magnetic fields eject non-ferrous contaminants downstream of primary shredding. Installations at Rotterdam and Hamburg ports enable export-grade purity certification.
- Shearing:Hydraulic guillotines section heavy structural scrap into furnace-chargeable dimensions for foundry customers.
- Balancing:Density optimization through controlled loading improves transportation economics for long-haul export routes.
- Sorting:Manual and sensor-based segregation separates alloy grades prior to melting.
Magnetic separation handles the highest tonnage throughput; shredding commands the steepest expansion trajectory as automotive obsolescence accelerates.
End-Use Sector:
Steel mill procurement scale dwarfs other demand channels, though foundry specifications sustain premium pricing for chemistry-controlled bundles.
- Steel Mills:Electric arc furnace operators consume shredded and bundled grades for long and flat product output. Turkey's Iskenderun and Aliaga clusters, India's Raigad and Jharsuguda districts, and the United States' Texas and Indiana mill corridors anchor global demand.
- Foundries:Gray and ductile iron foundries require low-residual bundles for automotive and pump casting applications. German foundries in Baden-Württemberg enforce strict copper and tin limits.
- Manufacturing:Direct remelting of industrial scrap within integrated forging and casting operations minimizes logistics costs.
- Heavy Machinery Production:Crane and mining equipment builders source thick-section scrap for cast component production.
- Shipbuilding:Korean and Chinese yards consume plate-grade remelt for vessel construction.
- Electrical Equipment:Motor and transformer manufacturers require low-phosphorus feedstock for magnetic core applications.
Steel mills absorb the bulk of installed capacity; foundries are expanding most quickly as automotive casting demand intensifies.
Product Form:
Density and handling characteristics determine furnace charging economics, with shredded grades commanding logistics premiums for seaborne export.
- Shredded Scrap:Fragmented auto and appliance feedstock achieves 70-75 pounds per cubic foot density, optimizing electric arc furnace charge buckets. This form dominates Turkish and Indian import specifications.
- Bundled Scrap:Wire-tied mill-grade bundles from industrial offcuts offer predictable chemistry for specialty steel production. Japanese mini-mills in Tokyo Bay and Osaka Bay corridors prefer this form for tool steel output.
- Loose Scrap:Unprocessed collection yard material requires downstream densification for furnace compatibility.
- Pressed Blocks:Briquetted turnings and borings from machining operations reduce oxidation losses during transport.
- Rolled Bundles:Continuous wire-tied configurations improve crane handling efficiency at large melt shops.
- Melted Ingots:Pre-alloyed remelt blocks serve foundries with constrained on-site melting capacity.
Bundled scrap absorbs the bulk of installed capacity; shredded scrap is expanding most quickly as export specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates surplus ferrous scrap beyond domestic electric arc furnace absorption, while Turkey and India compete aggressively for seaborne shredded grades. China's import restrictions have redirected trade flows toward Southeast Asian processors.
United States
Texas and Indiana mill corridors anchor North American electric arc furnace steel production, pulling shredded scrap from Gulf Coast collection networks. The EPA enforces hazardous waste exclusions that shape shredder permitting and downstream slag management protocols. Nucor and Steel Dynamics facilities in the Southeast maintain backward integration into scrap collection through captive yard networks.
Turkey
Iskenderun and Aliaga steel clusters consume premium shredded grades for rebar and wire rod exports to Middle Eastern construction markets. The country's national environmental regulator imposes air quality standards on shredder emissions that rival EU benchmarks. Izmir port handlers have expanded dedicated scrap terminal capacity to accommodate rising Gulf Cooperation Council demand.
India
Raigad and Jharsuguda districts host rapid electric arc furnace buildout under the Ministry of Steel's secondary steel capacity targets. BIS quality specifications for imported scrap create certification hurdles that favor established shredder relationships. Gujarat port infrastructure at Mundra and Hazira processes rising shredded volumes diverted from traditional Turkish buyers.
Germany
Salzgitter and Thyssenkrupp operations source certified low-carbon scrap grades under EU Carbon Border Adjustment Mechanism documentation requirements. The REACH framework constrains persistent organic pollutant concentrations in scrap-derived steel entering automotive value chains. Hamburg and Rotterdam port shredders serve as quality gatekeepers for EU-compliant export grades.
China
Domestic electric arc furnace capacity expansion in Jiangsu and Hebei provinces absorbs indigenous scrap generation previously targeted for export. SAMR import purity thresholds have redirected regional trade flows toward Vietnamese and Indonesian processors. Yangtze River Delta shredders focus on domestic automotive and appliance feedstock under dual carbon policy mandates.
Global Ferrous Scrap Recycling Market Competitive Landscape
The competitive structure tilts toward vertically integrated steelmakers with captive scrap supply chains. Tier-one operators combine deep port access with dense metropolitan collection networks, while mid-scale specialists concentrate on single-region density. Strategic archetypes include integrated mill-owned processors, independent port-based shredders, and technology-driven sorting specialists. Capacity expansion and certified carbon documentation partnerships dominate competitive moves as procurement relationships consolidate around long-term offtake agreements.
Within the integrated processor tier, Steel Dynamics, Inc. and Sims Limited exemplify scale-driven positioning through backward integration into collection infrastructure. European Metal Recycling Limited anchors the port-based independent archetype with dense yard networks across Northwestern Europe. Commercial Metals Company occupies a position bridging mill ownership and third-party supply to external electric arc furnace operators. These three entities collectively represent the spectrum of competitive configurations: captive steelmaker supply, independent export-grade processing, and hybrid merchant-mill integration.
| Leading Market Players |
|---|
| Commercial Metals Company |
| China Metal Recycling (Holdings) Limited |
| European Metal Recycling Limited |
| Mitsubishi Materials Corporation |
| Veolia Environnement S.A. |
| Sims Limited |
| Steel Dynamics, Inc. |
| Kuusakoski Oy |
| Schnitzer Steel Industries, Inc. |
| Others |
Supply & Pricing Matrix
Natural gas costs embedded in electric arc furnace operations and shredder energy consumption cascade through pricing tiers, compressing margins for European processors while amplifying premiums for low-carbon certified grades destined for CBAM-compliant buyers.
Pricing Analysis
Yield-based pricing tied to metallic recovery rates anchors contract structures, with shredder operators commanding premiums for 95%+ ferrous purity. Price differentiation separates EU Carbon Border Adjustment Mechanism-certified grades from standard export tiers, while volume scale discounts dominate Turkish and Indian procurement. Pricing pressure stems from natural gas volatility in European processing corridors. Spot buyers in Southeast Asia exhibit highest price sensitivity; German steelmakers under long-term offtake agreements show lowest sensitivity due to embedded carbon guarantee requirements.
Supply Chain Analysis
Regional distribution centers at Rotterdam, Hamburg, and Izmir form hub-and-spoke patterns feeding electric arc furnace clusters. Supply concentrates in the United States, Turkey, and India as primary consumption nodes. Raw material flows draw from automotive shredder residue, industrial offcut networks, and demolition recovery streams. Single-source vulnerability runs through concentrated port handling capacity at Mundra and Hazira. Distribution runs through seaborne bulk shipments to mill-adjacent yards with magnetic separation and densification capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified shredding capacity bottlenecks in EU-compliant corridors prop pricing premiums, constraining supply elasticity for carbon-documented grades.
For Market Incumbents: Cement backward integration into metropolitan collection networks to defend against independent port-based shredders capturing CBAM-premium volumes. Lock long-term offtake agreements with EU steelmakers holding mass-balance certification. Prioritize sensor-based sorting R&D to maintain chemistry consistency advantages as Turkish mills narrow specification windows. For New Entrants and Emerging Players: Indonesian mini-mills expanding electric arc furnace output represent the most penetrable buyer archetype given limited domestic collection infrastructure. Establish import-dependent supply relationships at Krakatau Steel-adjacent yards. Pursue joint venture structures with established port handlers to bypass capital-intensive shredding equipment barriers. For Investors and Strategic Acquirers: Three-to-five-year supply contract announcements from Thyssenkrupp and Salzgitter are the leading indicator that carbon-accounted procurement is consolidating around dedicated processor relationships. Frame long-term viability around certified documentation capability rather than volume scale alone. Target independent shredders with EU-approved downstream slag management systems as acquisition candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Steel Dynamics and Sims Limited secure captive feedstock streams for electric arc furnace supply security. |
| Carbon Certification Investment | EU-approved mass-balance documentation unlocks premium pricing tiers from Thyssenkrupp and Salzgitter procurement. |
| Sensor-Based Sorting Deployment | X-ray fluorescence integration at Rotterdam and Chicago facilities raises bundle chemistry consistency for narrow specification customers. |
| Port Terminal Capacity Expansion | Izmir and Mundra handlers accommodate rising shredded volumes diverted from Chinese import restrictions. |
| Long-Term Offtake Agreement Structuring | Embedded carbon guarantees displace spot purchasing for German steelmakers under CBAM compliance pressure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews covering scrap yard operators, electric arc furnace procurement managers, port terminal handlers, and shredding equipment manufacturers. Bottom-up volume modeling triangulated against top-down steel production forecasts from Bureau of International Recycling and World Steel Association sources.
Segment-level granularity modeled source type, processing method, end-use sector, and product form dimensions across the projection horizon. CAGRs derived from trend extrapolation of electric arc furnace capacity buildout in India and Turkey, cross-referenced with automotive fleet turnover projections and demolition activity indices. Forecast inputs incorporated EU CBAM implementation timelines and China's SAMR import threshold enforcement patterns.
Revisions become necessary when carbon accounting standards shift, natural gas benchmarks spike persistently, or major importing jurisdictions alter scrap purity thresholds. Forecasts reflect documented assumptions on secondary steel capacity expansion rates and trade flow redirection patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Californium Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Cesium Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Global Boron Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Selenium Market
Metals & Minerals
Steel Powder Market