
 Non-Alcoholic Steatohepatitis Treatment Market | 2026-2036
Non-Alcoholic Steatohepatitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Steatohepatitis Treatment Market Intelligence
Breakthrough therapy designation is reorganizing competitive dynamics across the NASH landscape. Madrigal Pharmaceuticals leverages its first-mover regulatory position in thyroid hormone receptor-beta agonism. Novo Nordisk anchors its metabolic franchise through GLP-1 receptor agonist expansion into liver disease indications. Eli Lilly and Company differentiates via parallel pipeline investments spanning incretin biology and antifibrotic mechanisms.
Non-alcoholic steatohepatitis represents progressive liver inflammation with hepatocyte ballooning and fibrosis staged histologically from F0 to F4, requiring sustained pharmacological intervention to halt cirrhosis progression. The primary commercial purpose centers on preventing end-stage liver disease and reducing transplantation burden. Oral administration routes dominate current development portfolios, though injectable formulations are capturing attention in combination regimens with metabolic agents. Early intervention stages command concentrated R&D investment, while advanced treatment segments carry premium pricing potential due to limited therapeutic alternatives and urgent unmet need.
FDA breakthrough therapy designations and EMA PRIME eligibility are compressing development timelines and reshaping market access negotiations for NASH innovators. The EPA maintains indirect influence through environmental assessments of pharmaceutical manufacturing facilities producing active ingredients. Stakeholders must monitor evolving surrogate endpoint acceptability criteria, as regulatory precedent for accelerated approval based on non-invasive biomarkers rather than liver biopsy will determine commercialization speed and payer reimbursement thresholds.
Market Dynamics
FDA breakthrough therapy designations are compressing clinical trial timelines and rewiring capital allocation across the NASH therapeutic landscape, forcing developers to front-load manufacturing scale-up before confirmatory data readouts.
Growth Catalysts
- Accelerated Approval Pathway:FDA breakthrough therapy designation enables earlier commercial access based on surrogate endpoints, compressing development cycles for fibrosis-targeting agents.
- Obesity-Driven Patient Pools:United States hepatology clinics are expanding screening protocols for steatohepatitis among metabolic syndrome patients, enlarging addressable populations for early intervention.
- GLP-1 Convergence:Metabolic disease centers are integrating liver-directed therapies with existing incretin regimens, creating combination treatment demand that expands prescription volume.
Market Restraints
- Biopsy Dependency:Regulatory validation still requires histological confirmation for pivotal trials, limiting patient recruitment and trial site expansion.
- Reimbursement Lag:CMS and commercial payers impose step-therapy requirements that delay access to novel mechanisms until generic alternatives fail.
- Active Pharmaceutical Ingredient Concentration:Contract manufacturing for thyroid hormone receptor modulators concentrates among European and Indian suppliers, creating single-source vulnerability.
Strategic Opportunities
- Non-Invasive Biomarker Adoption:FibroScan and MRI-PDFF technologies are replacing liver biopsy for patient monitoring, enabling point-of-care diagnosis expansion.
- Japan's Aging Cohort:METI and PMDA are fast-tracking NASH therapies for Japan's expanding elderly metabolic disease population with streamlined local trial requirements.
- Specialty Pharmacy Channels:Limited distribution networks for high-complexity biologics are capturing margin through patient adherence programs and outcomes tracking.
Industry Challenges
- Hepatopathologist Shortage:Centralized histology review for NASH trials requires scarce specialist pathologists, creating bottlenecks in data readout timelines.
- Surrogate Endpoint Validation:FDA skepticism toward non-invasive biomarkers for accelerated approval creates regulatory uncertainty that extends confirmatory study design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Steatohepatitis Treatment Market |
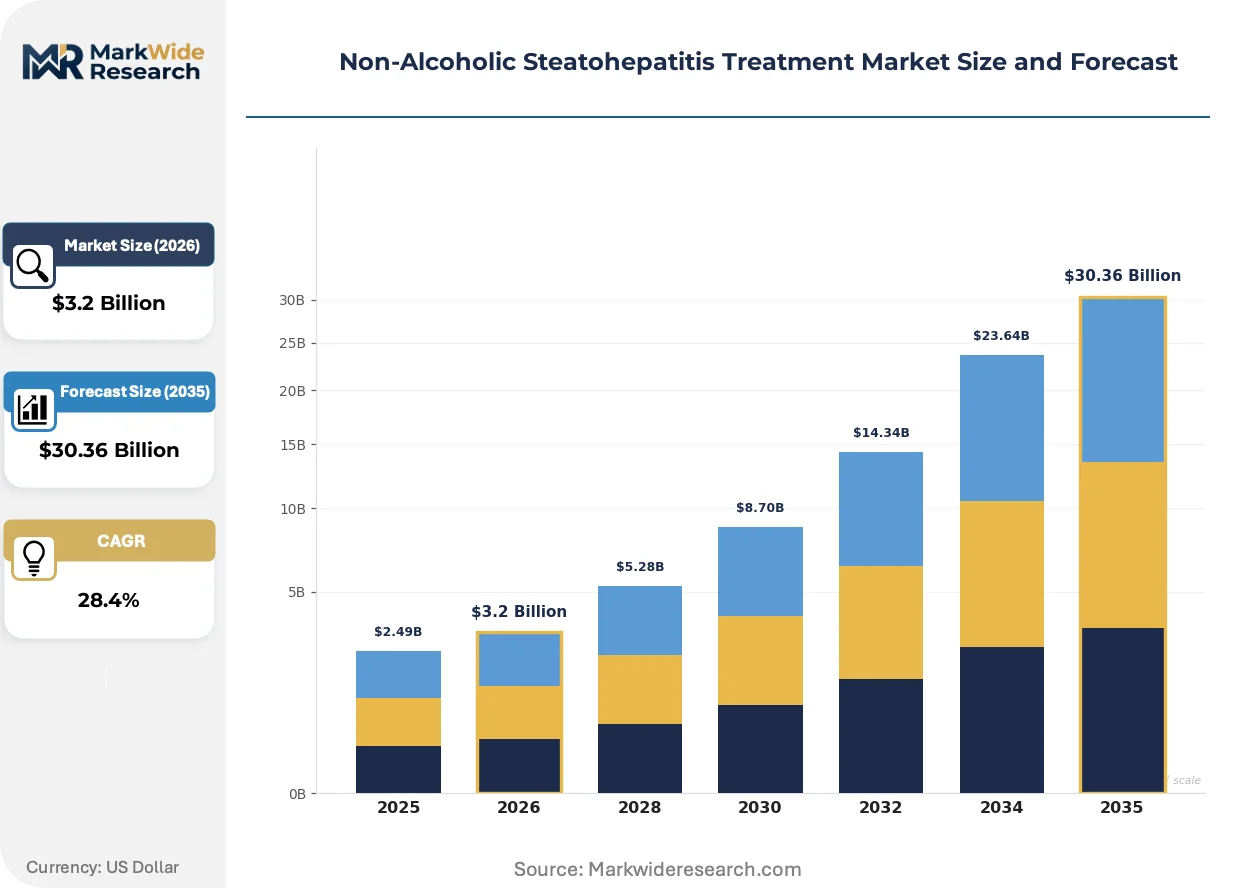
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $30.36 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrates, Insulin Sensitizers, Dietary Supplements, Hormonal Therapies Treatment Stage: Prevention, Early Intervention, Advanced Treatment, Supportive Care Administration Route: Oral, Injectable, Intravenous, Sublingual Patient Demographic: Adults, Pediatrics, Elderly, Obese Patients |
| Companies Covered | Madrigal Pharmaceuticals, Novo Nordisk, Intercept Pharmaceuticals, AbbVie, Eli Lilly and Company, Gilead Sciences, AstraZeneca, Galmed Pharmaceuticals, Inventiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Steatohepatitis Treatment Market Strategic Shifts & Innovations
Thyroid hormone receptor-beta agonism and GLP-1 receptor modulation are diverging into parallel development tracks, each attracting distinct investor cohorts and clinical trial infrastructures that reshape competitive positioning.
Resmetirom and similar selective thyroid hormone receptor-beta agonists are bifurcating the NASH therapeutic landscape into metabolic versus antifibrotic development camps. Hepatology specialists in the United States are adopting these agents for F2-F3 fibrosis patients, while endocrinology practices prioritize GLP-1 combinations. This split is compressing R&D budgets into mechanism-specific silos that limit cross-platform portfolio diversification.
EMA PRIME eligibility and FDA breakthrough therapy designation are creating dual-track regulatory strategies that accelerate European market entry while maintaining US commercial priority. Developers are structuring parallel submission packages that leverage EMA scientific advice to inform FDA pre-BLA meetings. This regulatory arbitrage most affects mid-stage biopharmaceutical companies with limited geographic infrastructure.
Patient identification through electronic health record algorithms is displacing traditional specialist referral pathways for NASH diagnosis. Integrated delivery networks in California and Texas are deploying automated screening tools that flag elevated liver enzymes and metabolic risk factors. This behavioral shift concentrates treatment initiation within accountable care organizations that demand outcomes-based contracting from manufacturers.
Non-Alcoholic Steatohepatitis Treatment Market Segmentation
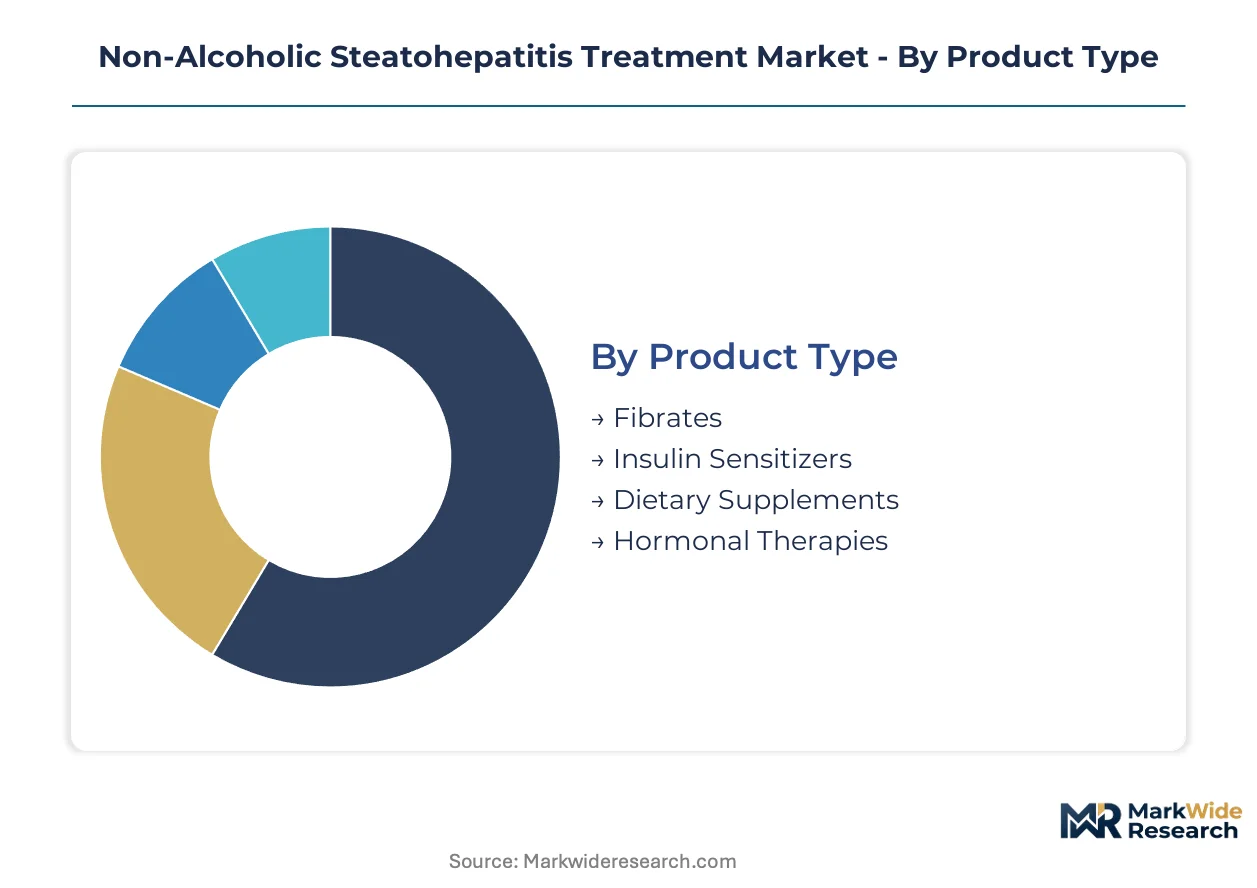
NASH therapeutics fragment across mechanism classes, intervention timing, and delivery modes that determine reimbursement pathways and prescriber access. Each segmentation dimension channels distinct commercial strategies through hepatology, endocrinology, or primary care settings.
Product Type:
Channel distribution varies sharply by mechanism—metabolic agents flow through endocrinology practices while antifibrotics concentrate in hepatology specialty pharmacies.
- Insulin Sensitizers:Thiazolidinediones and biguanides modulate hepatic glucose metabolism and improve insulin resistance in steatotic liver tissue. Demand clusters in United States metabolic disease centers managing comorbid type 2 diabetes, though cardiovascular safety profiles constrain formulary placement.
- Hormonal Therapies:Selective thyroid hormone receptor-beta agonists target hepatic lipid metabolism with minimal systemic thyroid activation. United States hepatology clinics are prioritizing these agents for F2-F3 fibrosis patients, driving concentrated prescription volume through limited distribution networks.
- Fibrates:Peroxisome proliferator-activated receptor-alpha agonists reduce hepatic triglyceride accumulation.
- Dietary Supplements:Vitamin E and polyunsaturated fatty acids serve as adjunctive interventions in early-stage disease management.
By volume, Insulin Sensitizers leads. By growth pace, Hormonal Therapies is ahead.
Treatment Stage:
Cost tiering separates prevention-focused primary care scripts from premium-priced advanced therapy regimens in transplant centers.
- Early Intervention:Pharmacological intervention at F1-F2 fibrosis stages aims to halt disease progression before irreversible architectural damage. United States integrated delivery networks are deploying EHR-based screening algorithms to capture this population, expanding addressable pools for oral metabolic agents.
- Advanced Treatment:F3-F4 fibrosis and compensated cirrhosis require intensive antifibrotic or combination regimens with limited therapeutic alternatives. Transplant center demand supports premium pricing, though CMS step-therapy requirements delay access until liver decompensation risk escalates.
- Prevention:Lifestyle modification support and risk factor management in pre-fibrotic steatosis.
- Supportive Care:Symptom management and complication mitigation in decompensated cirrhosis.
By patient volume, Prevention leads. By revenue intensity per patient, Advanced Treatment is climbing the fastest.
Administration Route:
Patient adherence patterns and site-of-care requirements dictate route selection across outpatient, infusion center, and self-administration settings.
- Oral:Small-molecule formulations dominate development portfolios for chronic daily administration in ambulatory settings. United States specialty pharmacies capture margin through adherence programs for once-daily regimens, though bioavailability challenges persist for hepatically metabolized compounds.
- Injectable:GLP-1 receptor agonists and biologic antifibrotics require subcutaneous delivery that integrates with existing diabetes management workflows. Endocrinology practices in the United States are adopting these for metabolic-NASH overlap populations, creating combination therapy demand.
- Intravenous:Hospital-based infusion for acute decompensation or peri-transplant immunomodulation.
- Sublingual:Emerging formulations targeting hepatic first-pass avoidance in development pipelines.
By prescription volume, Oral leads. By integration with metabolic disease management, Injectable is gaining share fastest.
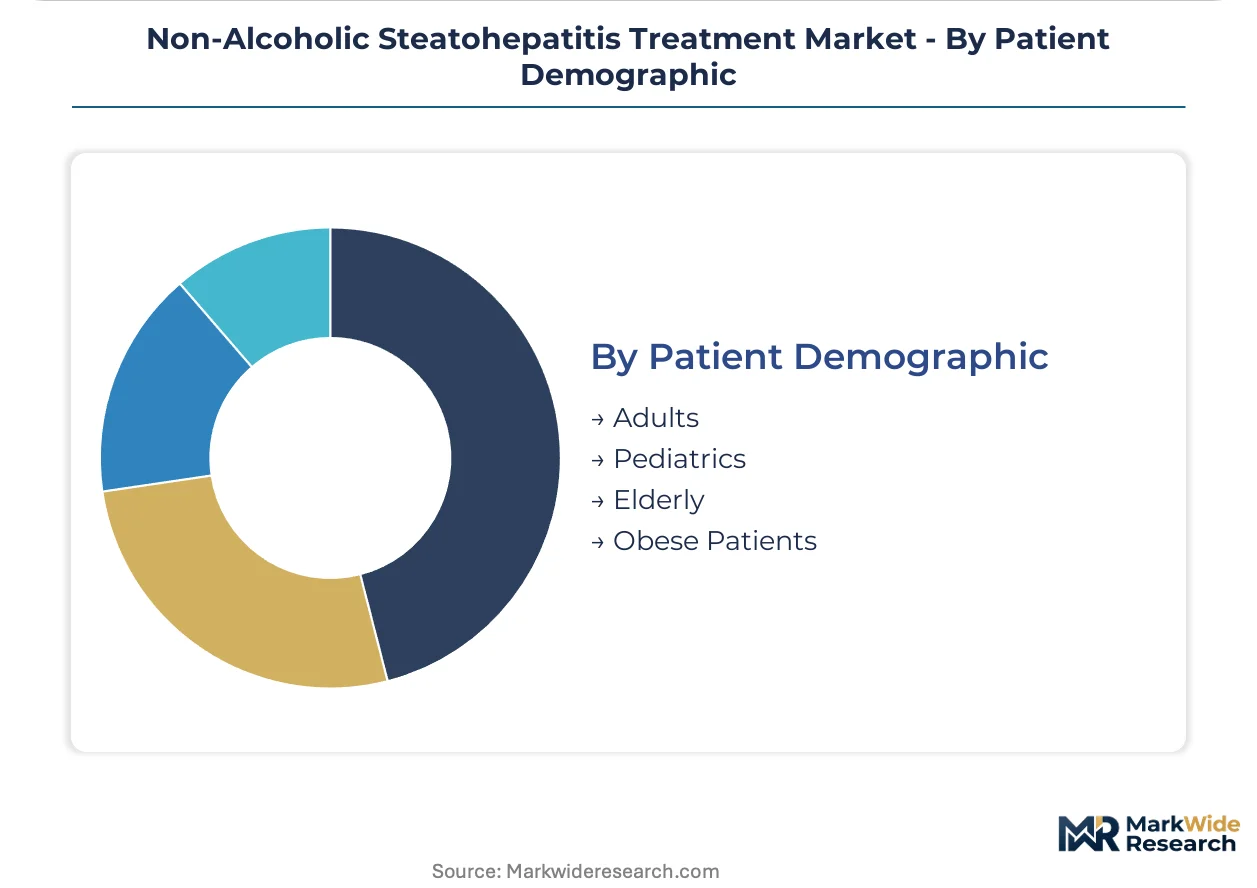
Patient Demographic:
Regulatory trial requirements and comorbidity profiles segment prescriber specialization and access pathways.
- Obese Patients:Body mass index above 30 kg/m² defines the core NASH population with highest progression risk to fibrosis. United States bariatric surgery centers and weight management clinics are expanding screening protocols, creating referral pipelines for pharmacological intervention.
- Elderly:Patients over 65 years carry elevated cirrhosis and hepatocellular carcinoma risk with polypharmacy complications. Medicare Part D formulary negotiations in the United States prioritize drug-drug interaction profiles in this segment.
- Adults:Working-age population 18-64 with commercial insurance coverage.
- Pediatrics:Adolescent non-alcoholic fatty liver disease with distinct regulatory trial requirements.
By absolute patient count, Adults leads. By unmet need intensity and pricing tolerance, Obese Patients shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States payers tolerate premium pricing for breakthrough therapies, while European health technology assessments enforce cost-effectiveness thresholds that compress margins. Emerging markets prioritize affordable oral generics over novel mechanisms.
United States
Obesity-driven screening protocols and integrated delivery network expansion are enlarging the addressable patient pool. FDA breakthrough therapy designation accelerates commercial timelines for fibrosis-targeting agents. Hepatology specialty pharmacies in California and Texas are deploying outcomes-based contracting models.
Germany
EMA scientific advice and parallel submission strategies attract developers seeking European market entry. The Federal Joint Committee (G-BA) conducts early benefit assessments that determine reimbursement levels for novel NASH therapies. Berlin and Munich host centralized pathology review centers for multinational clinical trials.
Japan
METI and PMDA fast-track NASH therapies for the aging metabolic disease population with streamlined local trial requirements. Elderly polypharmacy profiles drive demand for drug-drug interaction data in regulatory submissions. The Kanto region concentrates hepatology research infrastructure and specialist referral networks.
United Kingdom
NICE technology appraisals impose cost-per-QALY thresholds that limit access to premium-priced advanced therapies. The NHS Long Term Plan prioritizes early intervention in fatty liver disease through primary care screening. London and Manchester anchor clinical trial sites for non-invasive biomarker validation studies.
India
CDSCO regulatory pathways and domestic manufacturing capabilities support affordable generic production for early-stage metabolic agents. Rising obesity prevalence in urban centers is expanding diagnostic demand. Hyderabad and Ahmedabad concentrate contract research organizations supporting multinational Phase III programs.
Non-Alcoholic Steatohepatitis Treatment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the NASH therapeutic landscape. Large-cap biopharmaceutical firms command regulatory expertise and commercial infrastructure, while mid-stage developers concentrate on mechanism-specific innovation. The competitive structure segments into first-mover innovators, metabolic franchise extenders, and portfolio diversifiers. Dominant competitive moves include strategic partnerships for combination regimens and geographic licensing to accelerate market access.
Within the first-mover innovation tier, Madrigal Pharmaceuticals and Novo Nordisk exemplify divergent strategic approaches to the metabolic-liver disease convergence. Eli Lilly and Company occupies a position spanning incretin biology and antifibrotic mechanisms, representing the portfolio diversification archetype. These three anchors illustrate how regulatory positioning and therapeutic focus determine competitive segmentation in a market where FDA breakthrough designation reshapes capital allocation timelines.
| Leading Market Players |
|---|
| Madrigal Pharmaceuticals |
| Novo Nordisk |
| Intercept Pharmaceuticals |
| AbbVie |
| Eli Lilly and Company |
| Gilead Sciences |
| AstraZeneca |
| Galmed Pharmaceuticals |
| Inventiva |
| Others |
Cost & Logistics Intelligence
Thyroid hormone receptor-beta agonist substitution for traditional metabolic agents is redrawing supply geography toward European and Indian API manufacturers while compressing pricing premiums for first-mover hormonal therapies. This mechanism shift forces developers to front-load manufacturing scale-up before confirmatory data readouts, tightening working capital cycles and amplifying single-source vulnerability.
Pricing Analysis
Patient adherence programs and outcomes-based contracting drive lifetime value capture beyond the initial prescription. Three-tier pricing structure across breakthrough therapy premium, standard metabolic agent, and economy generic insulin sensitizer segments stratifies by fibrosis stage and CMS coverage determination. Cost compression in the economy tier is intensifying because of biguanide generic saturation and step-therapy requirements. United States integrated delivery networks show highest price sensitivity due to bundled payment pressures, while transplant centers demonstrate lowest sensitivity given urgent unmet need and limited alternatives.
Supply Chain Analysis
Active pharmaceutical ingredient concentration for selective thyroid hormone receptor modulators in Switzerland, India, and Germany creates single-source vulnerability that amplifies tariff exposure and regulatory inspection risk. Contract manufacturing draws from specialized European facilities for high-potency compounds and Indian suppliers for intermediate-scale production, with hepatic metabolism bioavailability challenges constraining formulation flexibility. Distribution runs through limited specialty pharmacy networks for hormonal therapies and broad wholesale channels for metabolic agents, with cold-chain requirements for injectable GLP-1 combinations adding logistics complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NASH therapeutic landscape functions as a service-attach opportunity where patient adherence monitoring and outcomes-based contracting expand faster than pharmaceutical product revenue alone. Recurring revenue from specialty pharmacy patient management programs and integrated delivery network risk-sharing agreements outpaces script volume growth.
For Market Incumbents: Shield formulary position against GLP-1 convergence by deepening hepatology specialty pharmacy relationships and securing FDA breakthrough therapy designation for combination regimens. Vertical integration into European API manufacturing reduces single-source exposure from Swiss and Indian contract suppliers. Investment in non-invasive biomarker validation preserves accelerated approval pathway access against histology-dependent competitors. For New Entrants and Emerging Players: Anchor in Japan's fast-track regulatory environment where METI and PMDA streamlined local trial requirements create lower barriers for elderly metabolic disease populations. The penetrable white space sits in F2-F3 fibrosis combination therapy protocols at United States metabolic disease centers seeking liver-directed adjuncts to existing incretin regimens. Go-to-market execution should prioritize hepatology-endocrinology co-prescriber education programs over traditional specialist detailing. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors mechanism-specific platform acquisitions over diversified portfolios. Long-term viability hinges on surrogate endpoint validation and CMS reimbursement determination for non-invasive monitoring technologies. Acquisition targets should display regulatory affairs infrastructure capable of parallel FDA-EMA submission strategies. The signal to watch is FDA advisory committee composition shifts toward biomarker-friendly hepatopathologists.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses commercial timelines for Madrigal Pharmaceuticals' resmetirom franchise. |
| Manufacturing Scale-Up | European API contract manufacturing expansion reduces single-source dependency for thyroid hormone receptor-beta agonists. |
| Pipeline Diversification | Eli Lilly's parallel incretin-antifibrotic investments span metabolic-liver disease convergence opportunities. |
| Licensing Agreement | Geographic licensing to Japanese partners accelerates METI fast-track access for aging cohort therapies. |
| Clinical Trial Advancement | Non-invasive biomarker validation studies at London and Manchester sites reshape surrogate endpoint acceptability. |
Research Approach
The analysis maps mechanism classes, treatment stages, administration routes, and patient demographics, each validated through hepatology specialists, regulatory affairs leads, formulary directors, and specialty pharmacy operations heads. Primary interviews with drug development executives at Madrigal Pharmaceuticals, Novo Nordisk, and Eli Lilly combine with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare data. Bottom-up prescription volume modeling and top-down epidemiological incidence estimates triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by treatment line, dosage form, administration route, patient population, and regional regulatory cluster throughout the forecast period. CAGRs derive from patient pool expansion, pricing trajectory assumptions, and penetration rate modeling. Forecast inputs include obesity prevalence projections, hepatopathologist workforce constraints, and surrogate endpoint validation timelines.
Material uncertainties — FDA skepticism toward non-invasive biomarkers, CMS step-therapy policy shifts, and API manufacturing inspection outcomes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory precedent and reimbursement determination that remain contingent on evolving payer behavior. Practitioners should keep alternative scenarios live as EMA PRIME eligibility criteria and hepatology specialist referral algorithm adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market