
 ACTH Deficiency Treatment Market | 2026-2036
ACTH Deficiency Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
ACTH Deficiency Treatment Market Outlook
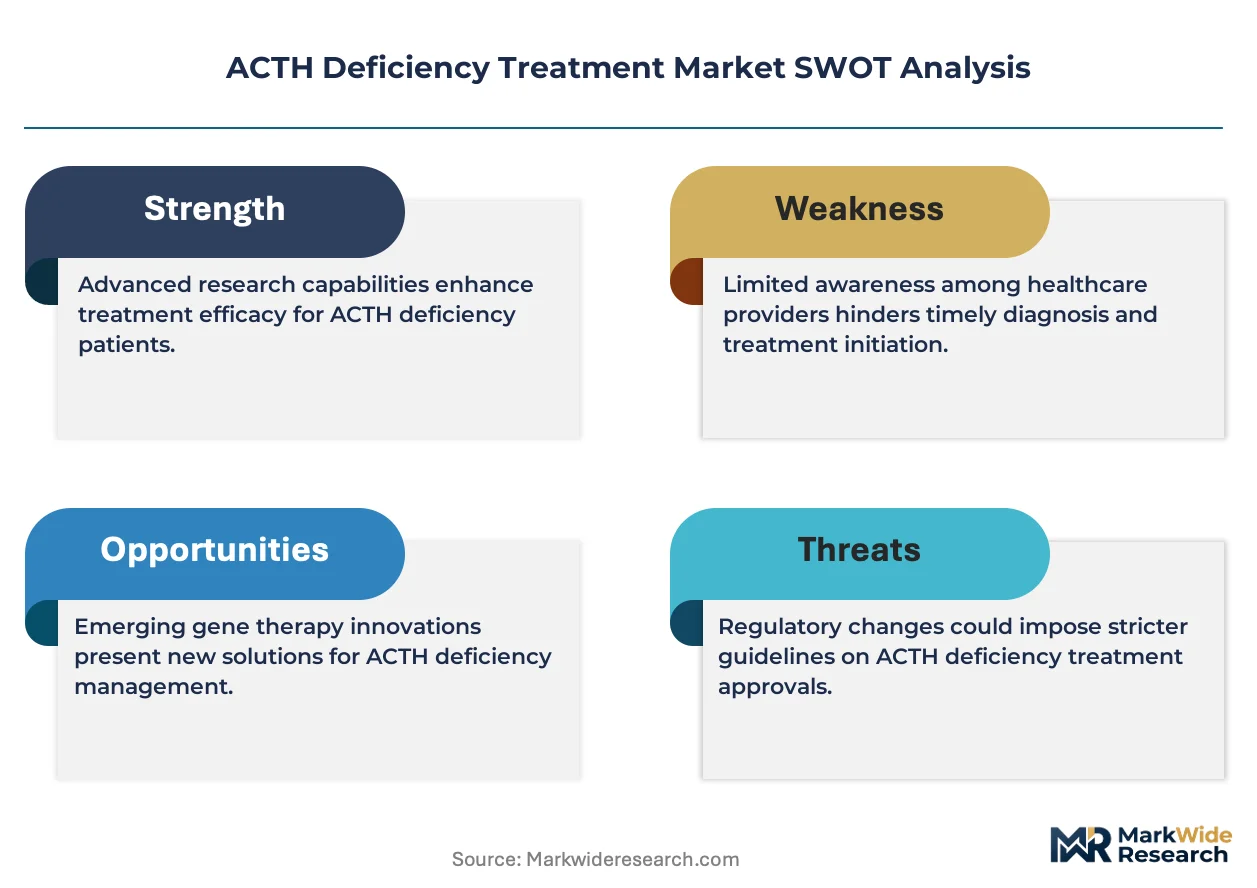
Endocrinology fellowship training capacity is reorganizing how quickly specialized care reaches ACTH deficiency patients. Mallinckrodt plc dominates the corticotropin injection segment through its established hospital formulary relationships. Pfizer competes via its broad glucocorticoid portfolio that spans acute and chronic replacement protocols. Novartis AG leverages its rare disease infrastructure to sustain access programs for complex endocrine conditions.
ACTH deficiency treatment encompasses hormone replacement therapies that restore cortisol homeostasis in patients with pituitary or hypothalamic dysfunction, typically administered as synthetic adrenocorticotropic hormone or glucocorticoid analogs with bioequivalence thresholds measured against endogenous cortisol curves. The primary purpose is preventing adrenal crisis while minimizing iatrogenic Cushingoid effects through circadian-matched dosing regimens. Injections retain the largest revenue share due to their use in acute adrenal crisis and diagnostic stimulation testing, while intranasal sprays represent the fastest-growing delivery innovation as patients seek alternatives to parenteral chronic therapy. Home healthcare channels are deepening their margin pools by managing the cold-chain logistics and nurse training that complex biologic hormone therapies require.
FDA orphan drug designation and EMA's protocol for rare endocrine conditions shape clinical trial incentives and pricing autonomy for ACTH-focused developers. The EU's MDR framework demands renewed clinical evidence for legacy hormone replacement devices, compressing timelines for delivery system upgrades. Stakeholders must monitor how decentralized diagnostic testing for secondary adrenal insufficiency reshapes the balance between hospital-based and home-administered therapy volumes.
Market Dynamics
Orphan drug incentives from FDA and EMA are concentrating manufacturer investment toward corticotropin analog development while compressing timelines for novel delivery system validation. This regulatory pull is restructuring competitive priorities across hormone replacement portfolios.
Growth Catalysts
- EMA Rare Endocrine Protocol:Accelerated assessment pathways for ACTH-focused therapies reduce development timelines and enable earlier patient access across EU member states.
- Diagnostic Stimulation Testing:Rising utilization of cosyntropin protocols in tertiary referral networks expands the addressable patient base for synthetic corticotropin injections.
- Japan's Hypopituitarism Clusters:Concentrated specialist capacity in Tokyo and Osaka metropolitan areas concentrates demand for advanced replacement therapies.
Market Restraints
- Cold-Chain Biologic Logistics:Temperature-controlled distribution requirements for peptide hormones inflate fulfillment costs and limit pharmacy network participation.
- Glucocorticoid Substitution:Oral hydrocortisone and prednisone protocols retain preference in primary care settings, constraining ACTH analog penetration.
- EU MDR Recertification Burden:Legacy hormone delivery devices face compressed evidence generation timelines for renewed CE marking under the 2017 framework.
Strategic Opportunities
- Intranasal Spray Formulations:Patient preference for non-parenteral chronic therapy creates whitespace for circadian-matched mucosal delivery systems.
- Home Healthcare Integration:Nurse-administered biologic programs in Germany and the United States capture margin pools from hospital-based infusion centers.
- FDA Orphan Drug Exclusivity:Seven-year market protection windows incentivize development of differentiated corticotropin analogs with improved pharmacokinetic profiles.
Industry Challenges
- Endocrinology Fellowship Pipeline:Constrained training capacity in the United States and Germany limits specialist availability for complex hypopituitarism management.
- Circadian Dosing Compliance:Multi-dose replacement regimens impose adherence burdens that complicate therapeutic outcomes and increase monitoring costs.
- Biologic Manufacturing Scale-Up:Peptide synthesis complexity creates capacity bottlenecks for manufacturers expanding ACTH analog production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ACTH Deficiency Treatment Market |
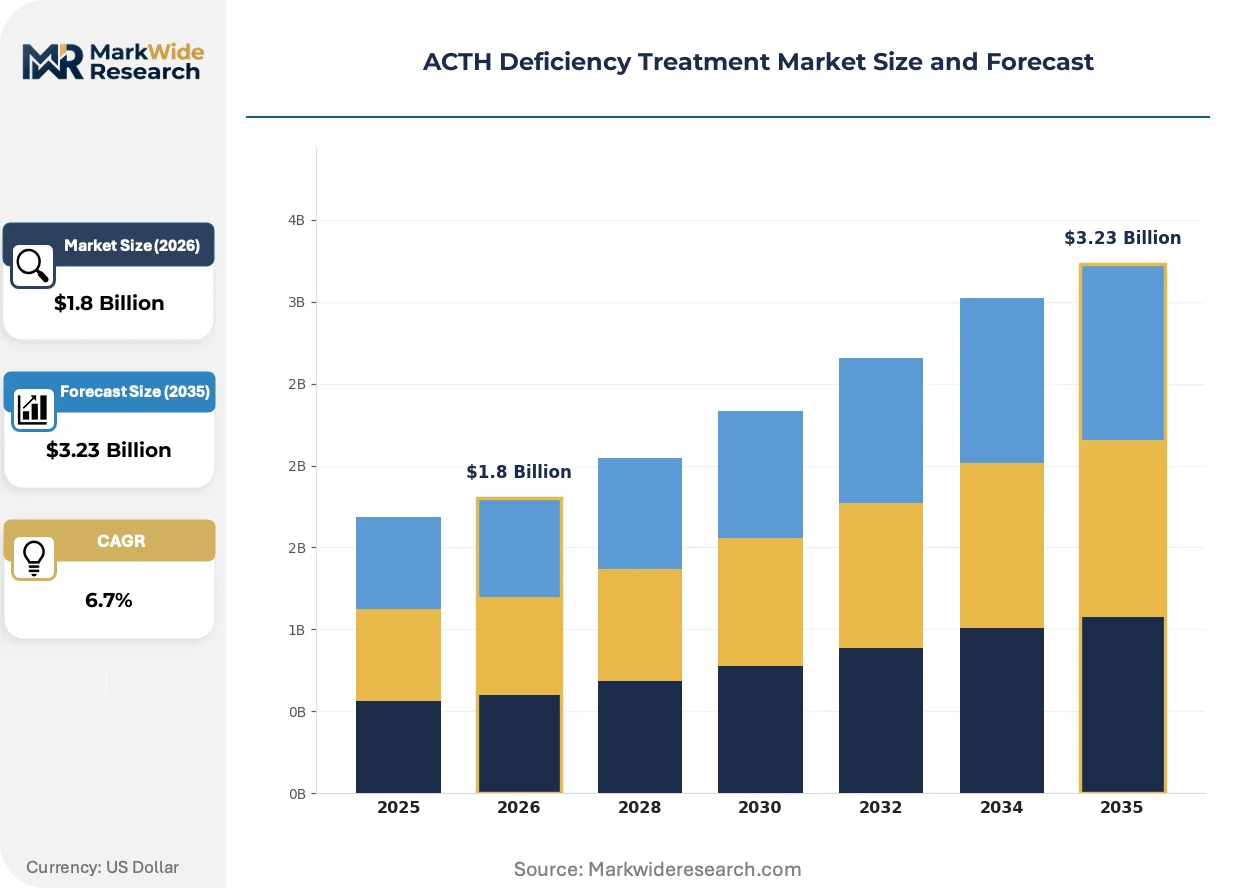
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injections, Oral Tablets, Intranasal Sprays, Infusion Solutions Delivery Mode: Self-Administration, Hospital Administration, Home Healthcare, Specialty Pharmacy End User: Hospitals, Clinics, Home Care Settings, Pharmacy Therapy Area: Endocrine Disorders, Metabolic Disorders, Immune Disorders, Others |
| Companies Covered | Mallinckrodt plc, Pfizer, Novartis AG, Viatris, Hikma Pharmaceuticals, Ferring B.V., Merck KGaA, Sandoz, Breckenridge Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ACTH Deficiency Treatment Market Strategic Shifts
Delivery modality innovation is fragmenting the chronic therapy landscape as patients and payers weigh convenience against clinical precision. Three distinct shifts are restructuring how corticotropin replacement reaches end-users.
Extended-release depot formulations are bifurcating the maintenance therapy segment from acute crisis management. Endocrinology clinics in Germany and Japan are adopting subcutaneous implant protocols that reduce dosing frequency from multiple daily administrations to monthly intervals. This modality shift is compressing revenue per patient while expanding eligible patient volumes through improved adherence profiles.
EMA's Medical Device Regulation implementation is forcing delivery system manufacturers to regenerate clinical evidence for legacy injection platforms. Pre-filled syringe and auto-injector devices face renewed conformity assessment requirements that compress upgrade timelines. Manufacturers with established notified body relationships in the Netherlands and Germany are securing first-mover advantage in recertified device categories.
Patient-administered therapy protocols are displacing hospital-dependent infusion models across tertiary networks in the United States. Home nursing services and specialty pharmacy distribution channels are capturing volume from traditional endocrinology clinic settings. This channel rotation is most visible in California and Texas, where integrated delivery networks have centralized biologic logistics capabilities.
ACTH Deficiency Treatment Market Segmentation
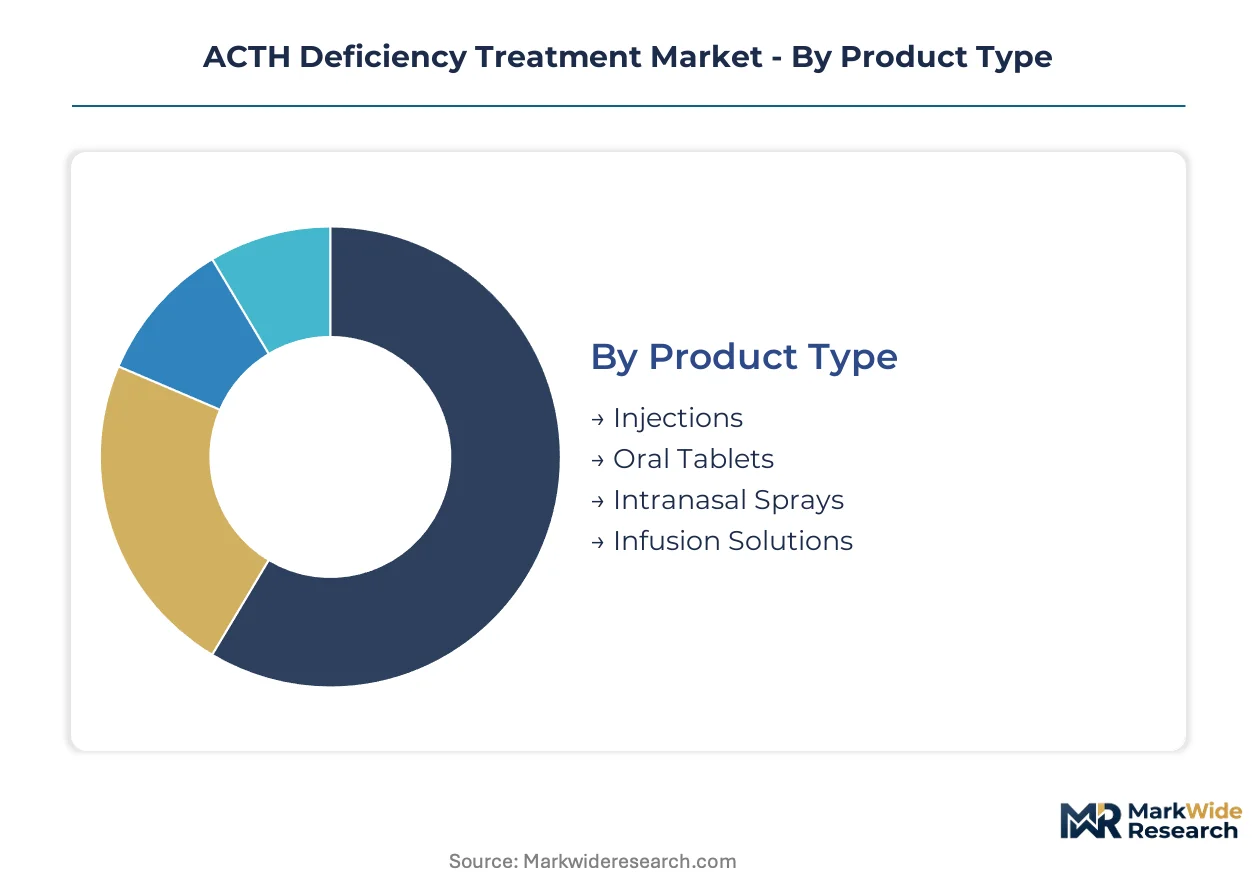
Treatment modality selection in ACTH deficiency hinges on regulatory pathways governing hormone replacement biologics. Segmentation reveals how FDA orphan drug incentives and EMA rare disease protocols concentrate investment across delivery technologies and care settings.
Product Type:
FDA's seven-year orphan exclusivity windows and EMA's accelerated assessment pathways differentiate approval timelines and pricing autonomy across formulation categories.
- Injections:Synthetic corticotropin peptides delivered via intramuscular or subcutaneous routes provide rapid cortisol elevation for acute adrenal crisis and diagnostic stimulation testing. Demand concentrates in tertiary referral networks across the United States, Germany, and Japan where hospital formulary relationships with established manufacturers dominate procurement.
- Intranasal Sprays:Mucosal delivery systems attempt circadian-matched absorption profiles for chronic maintenance therapy. Patient preference for non-parenteral administration in California and Texas integrated delivery networks is expanding eligible volumes despite pharmacokinetic variability challenges.
- Oral Tablets:Hydrocortisone and prednisone analogs serve glucocorticoid substitution protocols in primary care settings where ACTH peptide access remains limited.
- Infusion Solutions:Intravenous corticotropin formulations reserve for perioperative stress dosing and intensive care unit management of refractory cases.
Established volume favors injections; emerging adoption favors intranasal sprays.
Delivery Mode:
Cost tier differentiation separates capital-intensive hospital infrastructure from leaner home-based models reshaping margin capture.
- Hospital Administration:Nurse-supervised injection protocols in endocrinology wards and emergency departments retain dominance for acute crisis management and initial diagnostic workup.
- Home Healthcare:Specialty nursing services in Germany and the United States manage cold-chain biologic logistics and patient training, capturing margin pools from traditional infusion centers.
- Self-Administration:Patient-managed subcutaneous regimens reduce facility dependency for stable chronic replacement.
- Specialty Pharmacy:Centralized distribution hubs coordinate temperature-controlled fulfillment and adherence monitoring for complex peptide therapies.
Revenue concentration sits with hospital administration; margin expansion favors home healthcare.
End User:
Application specificity determines reimbursement coding and prescriber access constraints across care settings.
- Hospitals:Academic medical centers in Tokyo, Osaka, and metropolitan German clusters anchor diagnostic stimulation testing and acute crisis intervention volumes.
- Clinics:Endocrinology fellowship-trained specialists in tertiary referral networks manage complex hypopituitarism cases requiring dose titration and monitoring.
- Home Care Settings:Patient-administered maintenance protocols displace clinic dependency for stable chronic replacement.
- Pharmacy:Retail and specialty channels handle oral glucocorticoid substitution where ACTH peptide access remains restricted.
Clinical complexity favors hospitals; patient convenience favors home care settings.
Therapy Area:
Customer type stratification separates rare disease specialists from generalists managing broader endocrine portfolios.
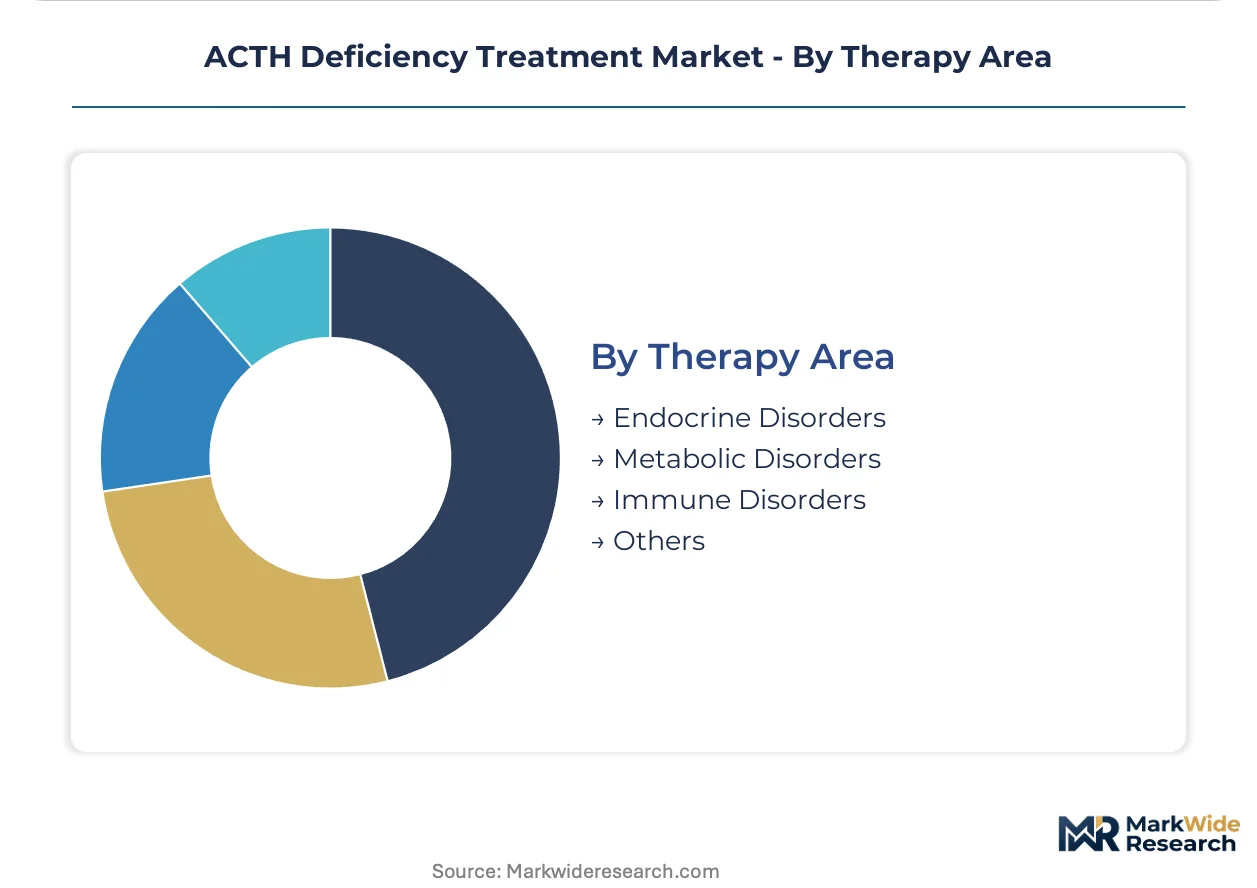
- Endocrine Disorders:Hypopituitarism and secondary adrenal insufficiency constitute the core addressable population for corticotropin replacement therapies.
- Metabolic Disorders:Adjunctive ACTH stimulation in congenital adrenal hyperplasia and related steroidogenesis defects extends utility beyond pituitary dysfunction.
- Immune Disorders:Diagnostic applications in autoimmune evaluation and off-label immunomodulatory protocols create secondary demand pockets.
- Others:Research applications and veterinary endocrinology represent marginal commercial relevance.
Prescription volume concentrates in endocrine disorders; label expansion potential favors metabolic disorders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives anchor the United States as the dominant geography, while EMA rare disease protocols and Japan's PMDA specialist networks concentrate advanced therapy adoption across three distinct regulatory spheres.
United States
Tertiary referral networks for hypopituitarism management drive concentrated demand, with California and Texas integrated delivery networks pioneering patient-administered therapy protocols. FDA's seven-year orphan exclusivity windows incentivize corticotropin analog development. The Greater Boston and Pacific Northwest clusters anchor diagnostic stimulation testing volumes through academic medical center relationships.
Germany
Home healthcare channels capture expanding margin pools through cold-chain biologic logistics and specialty nursing services. EMA's Medical Device Regulation implementation compresses timelines for legacy hormone delivery device recertification. The Munich and Hamburg metropolitan areas concentrate endocrinology fellowship-trained specialist capacity for complex case management.
Japan
Hypopituitarism clusters in Tokyo and Osaka metropolitan areas concentrate demand for advanced replacement therapies. PMDA's structured consultation pathways for rare endocrine conditions accelerate market entry timelines. The Kansai region sustains diagnostic stimulation testing infrastructure through university hospital networks.
United Kingdom
NHS specialist commissioning frameworks channel ACTH deficiency patients toward designated tertiary endocrinology centers. MHRA alignment with EMA rare disease protocols streamlines parallel regulatory submissions. The London-Southeast corridor anchors the national referral network for pituitary dysfunction management.
Switzerland
Swissmedic's expedited assessment pathways for orphan medicines attract corticotropin developers seeking early EU market validation. Private healthcare infrastructure supports premium-priced biologic hormone therapies outside national reimbursement constraints. The Basel and Zurich clusters concentrate pharmaceutical R&D partnerships for peptide synthesis scale-up.
ACTH Deficiency Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with hospital formulary relationships and rare disease infrastructure serving as the primary moats. The structure bifurcates between corticotropin injection incumbents with established acute care penetration and glucocorticoid portfolio players competing on chronic replacement breadth. Two strategic archetypes dominate: integrated pharmaceutical conglomerates leveraging orphan drug incentives, and specialty biologic manufacturers focused on peptide synthesis capabilities. Competitive moves center on delivery system innovation partnerships and home healthcare channel integration to displace hospital-dependent infusion models.
Within the integrated pharmaceutical tier, Mallinckrodt plc and Pfizer occupy positions reflecting distinct competitive vectors—one anchored in hospital formulary relationships for corticotropin injections, the other in broad glucocorticoid portfolio breadth spanning acute and chronic protocols. Novartis AG represents the rare disease infrastructure archetype, sustaining access programs that exemplify how specialized distribution capabilities capture complex endocrine condition volumes.
| Leading Market Players |
|---|
| Mallinckrodt plc |
| Pfizer |
| Novartis AG |
| Viatris |
| Hikma Pharmaceuticals |
| Ferring B.V. |
| Merck KGaA |
| Sandoz |
| Breckenridge Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Peptide synthesis scale economies in Switzerland and Germany anchor both supply concentration and price floors for corticotropin analogs. High-capacity utilization at Basel-area manufacturing clusters compresses unit costs for established incumbents while creating entry barriers for smaller competitors lacking comparable batch throughput.
Pricing Analysis
Geographic price spreads of 40-60% separate United States hospital formulary contracts from German home healthcare procurement. Three-tier pricing structure across premium biologic formulations, standard synthetic peptides, and economy glucocorticoid substitutes dominates the landscape. Pricing pressure stems from oral hydrocortisone substitution in primary care settings. Academic medical centers show least price sensitivity; primary care physicians demonstrate highest.
Supply Chain Analysis
Strategic stockpiling of peptide raw materials prevails over just-in-time approaches due to synthesis complexity and batch variability risks. Manufacturing concentrates in Switzerland, Germany, and the United States. Cold-chain logistics, sterile fill-finish capacity, and porcine-derived pituitary extracts constitute critical input dependencies. Single-source vulnerability characterizes specialized peptide synthesis equipment. Distribution runs through specialty pharmacy networks with temperature-controlled fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA orphan drug exclusivity and EMA rare disease protocols creates durable defensive moats for established corticotropin developers. Seven-year market protection windows and accelerated assessment pathways compound switching costs for hospital formularies.
For Market Incumbents: Secure hospital formulary relationships through expanded nurse training programs and cold-chain logistics partnerships. Deepen backward integration into peptide synthesis capacity to offset raw material cost volatility. Threat from intranasal spray entrants demands defensive patent portfolio investment in mucosal delivery formulations. For New Entrants and Emerging Players: Anchor in California and Texas integrated delivery networks where patient-administered therapy protocols are displacing hospital-dependent models. Target intranasal spray formulations as the most penetrable chronic maintenance segment. Pursue FDA orphan drug designation as the primary go-to-market accelerant. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty biologic manufacturers with established home healthcare channel relationships. Long-term viability favors peptide synthesis specialists with scalable GMP capacity and rare disease infrastructure. Watch FDA approval timelines for depot formulation candidates as inflection indicators for maintenance therapy segment capture.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA seven-year exclusivity windows protect corticotropin analog investments from immediate generic erosion. |
| Home Healthcare Channel Integration | Specialty nursing services in Germany capture margin pools from traditional hospital infusion centers. |
| Intranasal Delivery System Development | Circadian-matched mucosal absorption addresses patient preference for non-parenteral chronic therapy alternatives. |
| Peptide Synthesis Scale-Up Investment | Basel-area manufacturing clusters achieve cost advantages through high-capacity batch throughput. |
| EMA MDR Device Recertification | Pre-filled syringe platforms require renewed clinical evidence under 2017 framework timelines. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with endocrinology fellowship directors, hospital formulary managers, specialty pharmacy procurement leads, and rare disease access program directors; and secondary validation against FDA orphan drug designations, EMA accelerated assessment pathways, ClinicalTrials.gov corticotropin protocols, and hospital procurement databases. Bottom-up patient volume estimates triangulated against top-down manufacturer revenue allocations.
Across the projection horizon, the analytical framework modeled treatment modality, delivery mode, end-user setting, and therapy area segmentation. CAGRs derived from epidemiology-adjusted patient population forecasts and pricing trajectory assumptions. Key inputs included diagnostic stimulation testing volume trends, home healthcare penetration rates, and regulatory approval pathway timelines.
Decision-makers should treat outputs as directional under stable orphan drug incentive structures and consistent tertiary referral network capacity; material deviation would warrant model refresh. Revision becomes warranted when EMA MDR recertification delays or fellowship training pipeline constraints cross thresholds that alter patient access timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Hypersensitivity Pneumonitis Market