
 Microcephaly Market | 2026-2036
Microcephaly Market Size, Share, and Industry Trends Forecast 2026-2036
Microcephaly Market Foresight
WHO protocols on congenital anomaly surveillance is rebalancing investment toward prenatal and neonatal diagnostic infrastructure. Merck KGaA leverages its molecular diagnostics portfolio to serve high-throughput screening laboratories in Europe and Latin America. Novartis AG anchors its position through sustained R&D spending on antiviral and neuroprotective therapeutic candidates. Beckman Coulter Inc. differentiates via automated hematology and flow cytometry systems deployed in maternal-fetal medicine units.
Microcephaly denotes a neurodevelopmental condition characterized by occipitofrontal circumference measuring more than two standard deviations below the mean for gestational age and sex, typically resulting from disrupted neuronal proliferation or migration during fetal brain development. Diagnostic Tools command the largest revenue share due to mandatory newborn screening mandates and expanding ultrasound and MRI capabilities in prenatal care; Genetic Testing represents the fastest-expanding segment as chromosomal microarray and whole-exome sequencing enter standard-of-care protocols for unexplained cases. Pediatric end users dominate service volume, while Telehealth delivery is gaining structural traction for remote developmental monitoring in rural and underserved regions.
FDA premarket review governs diagnostic assay commercialization in the United States, while EMA centralised procedures shape market access across EU member states; WHO International Classification of Diseases coding and birth defect surveillance standards influence national registry participation and research funding eligibility. Brazil's ANVISA and national health surveillance protocols further condition product registration for Zika-linked congenital syndrome diagnostics. Stakeholders must monitor evolving reimbursement frameworks for exome sequencing and position for integrated care contracts that bundle diagnostic, therapeutic, and rehabilitative services.
Market Dynamics
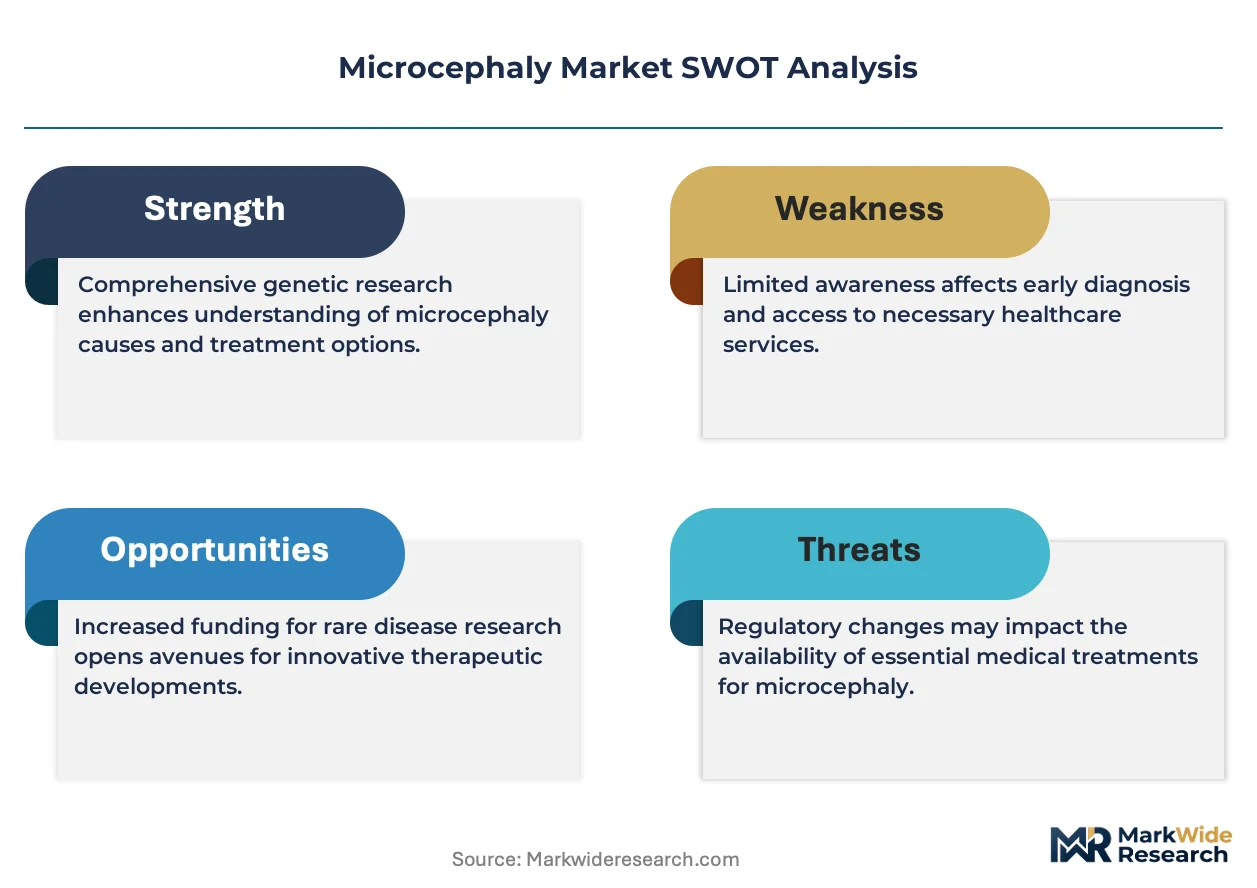
WHO International Classification of Diseases coding revisions and mandatory birth defect surveillance protocols are restructuring investment priorities across prenatal diagnostic infrastructure and neonatal screening networks.
Growth Catalysts
- Zika Virus Surveillance Mandates:Brazil's ANVISA protocols and national health surveillance programs are expanding molecular diagnostic capacity in maternal-fetal medicine units across public health systems.
- Chromosomal Microarray Adoption:Pediatric neurology clinics in Germany, the United Kingdom, and France are integrating cytogenomic testing into standard-of-care protocols for unexplained neurodevelopmental presentations.
- Telehealth Infrastructure:Remote developmental monitoring platforms are extending specialist reach into rural and underserved regions, compressing diagnostic delay timelines for isolated populations.
Market Restraints
- Sequencing Cost Volatility:Reagent supply concentration and semiconductor shortages in next-generation sequencing consumables are creating input cost instability for high-throughput laboratories.
- Reimbursement Fragmentation:Exome sequencing coverage policies vary across national health systems and private payers, creating access inequities and diagnostic pathway delays.
- Specialist Workforce Scarcity:Pediatric neurologist and clinical geneticist training pipeline constraints in emerging markets are limiting diagnostic service expansion despite equipment availability.
Strategic Opportunities
- Integrated Care Contracts:Bundled reimbursement models combining diagnostic, therapeutic, and rehabilitative services are creating new contracting structures for health system purchasers in European markets.
- Point-of-Care Molecular Testing:Miniaturized nucleic acid amplification platforms are enabling same-day Zika and TORCH screening in primary prenatal care settings without centralized laboratory infrastructure.
- EU MDR Harmonization:Centralized EMA procedures for in-vitro diagnostic medical devices are streamlining market access pathways across 27 member states for congenital anomaly screening assays.
Industry Challenges
- Bioinformatics Bottleneck:Variant interpretation expertise and computational infrastructure requirements are outpacing sequencing capacity expansion, creating diagnostic reporting delays.
- Legacy System Integration:Electronic health record interoperability gaps between prenatal ultrasound networks, genetic laboratories, and pediatric specialty clinics are fragmenting patient data continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcephaly Market |
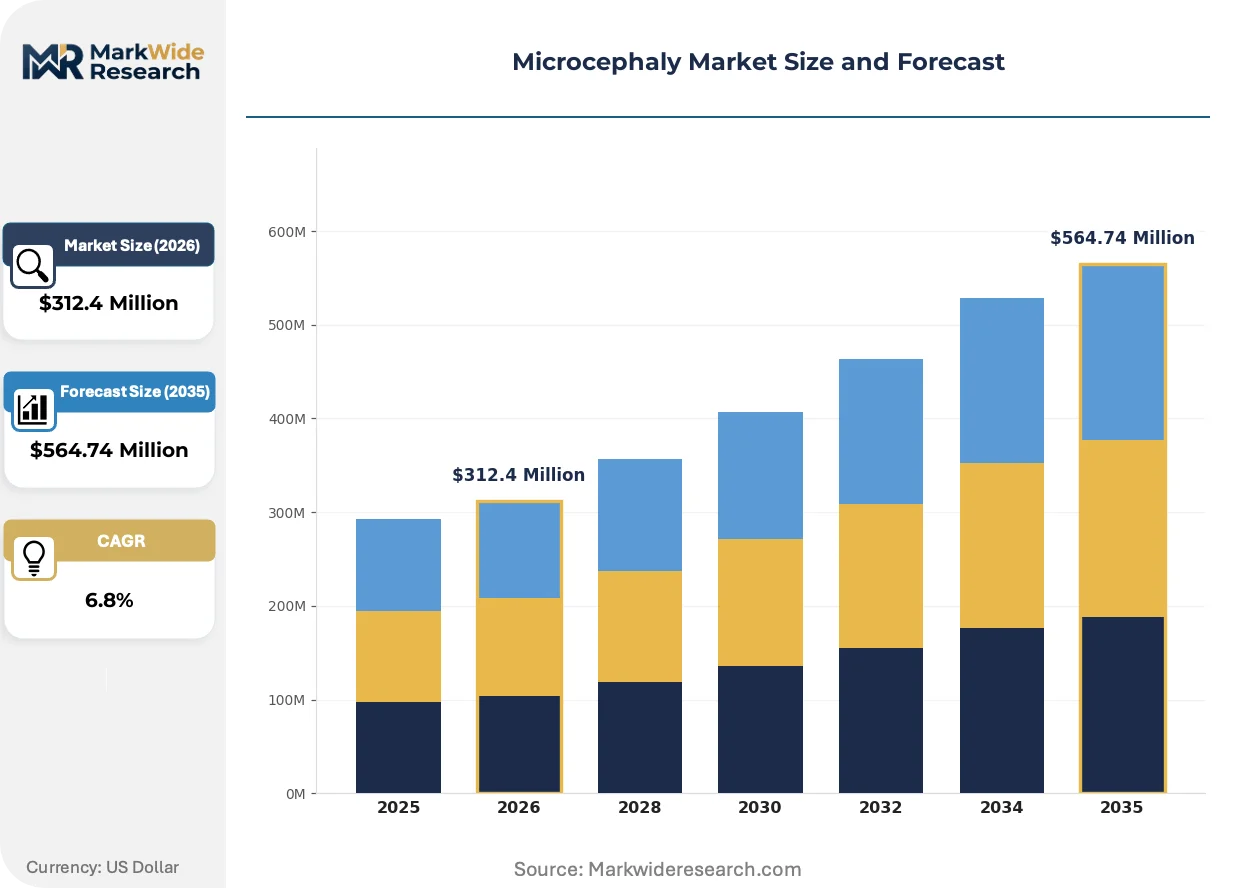
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Therapeutics, Genetic Testing, Supportive Care End User: Pediatrics, Neurologists, Genetic Counselors, Rehabilitation Centers Delivery Mode: Inpatient, Outpatient, Telehealth, Home Care Application: Clinical Assessment, Developmental Support, Genetic Research, Awareness Programs |
| Companies Covered | Merck KGaA, Novartis AG, Beckman Coulter Inc., bioMerieux, Bio-Rad Laboratories, Inc, Danaher, Hologic, F. Hoffmann-La Roche Ltd., Inovio Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcephaly Market Shifts & Advancements
Artificial intelligence-assisted fetal neurosonography and automated cranial biometry are compressing diagnostic timelines while WHO surveillance standardization is harmonizing cross-border birth defect registration.
Whole-exome sequencing paired with phenotype-driven variant filtering is absorbing interpretive workload from clinical geneticists in tertiary pediatric centers. Maternal-fetal medicine units in Brazil and select European university hospitals are deploying these platforms for rapid etiological diagnosis in severe microcephaly presentations. The technology is absorbing previously manual curation steps, enabling higher case throughput without proportional specialist hiring.
FDA premarket review pathways for breakthrough-designated in-vitro diagnostics are accelerating commercialization timelines for novel biomarker assays in the United States. Manufacturers are prioritizing de novo classification submissions for first-of-kind neurodevelopmental screening technologies. Pediatric reference laboratories are responding by building validation capabilities ahead of anticipated regulatory clearances.
Public health procurement is consolidating diagnostic service contracts under regional laboratory networks, displacing fragmented hospital-based purchasing. State-level health departments in Brazil and national health service commissioners in England are centralizing high-complexity genetic testing into designated supraregional centers. This concentration is most visible in Zika-affected municipalities where economies of scale in molecular surveillance are overriding institutional autonomy preferences.
Microcephaly Market Segmentation
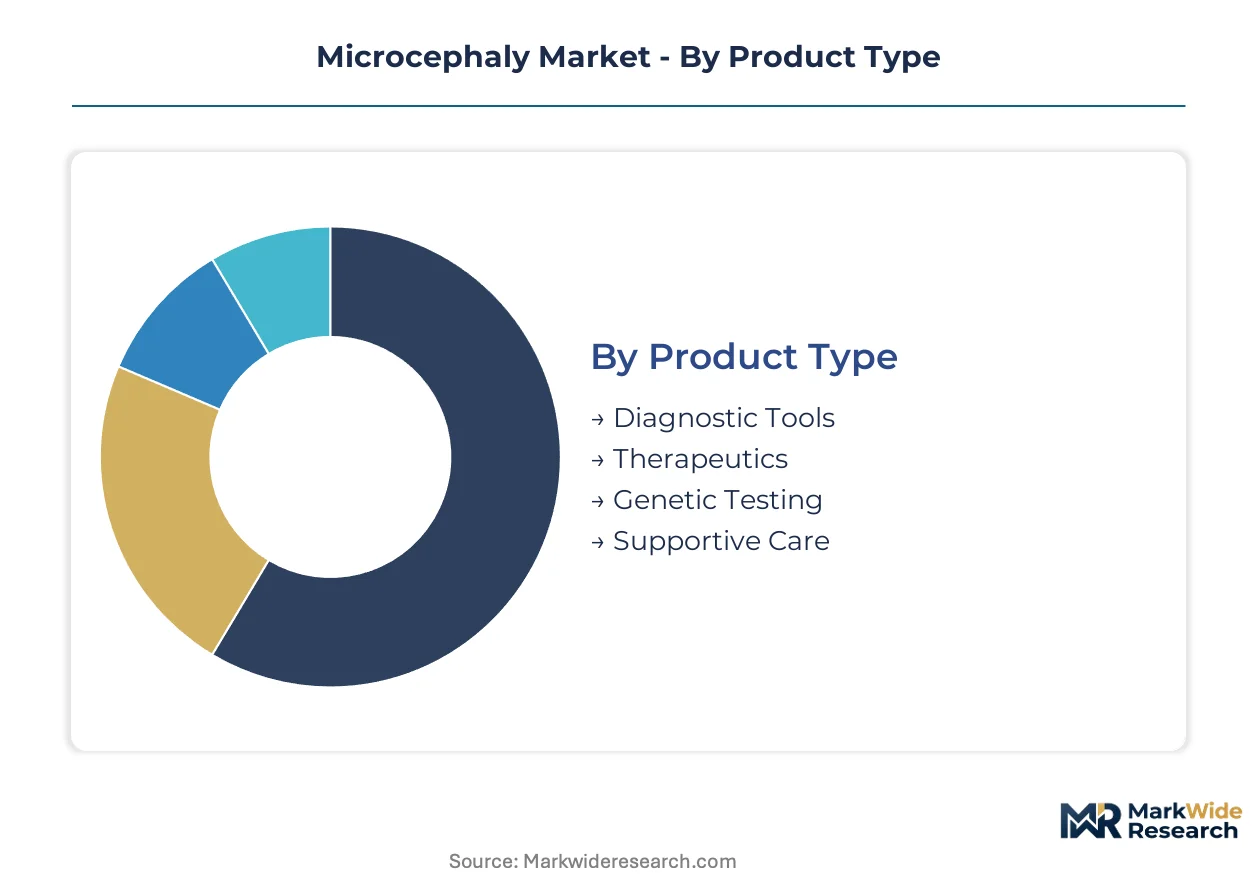
Microcephaly care pathways fragment across diagnostic, therapeutic, and supportive modalities. Segmentation reveals where capital equipment investments concentrate versus where service delivery models are restructuring.
Product Type:
Standardization dominates high-volume screening while customization governs complex diagnostic workups.
- Diagnostic Tools:Ultrasound biometry, MRI volumetrics, and head circumference measurement protocols constitute the procedural backbone. Mandatory newborn screening mandates in Brazil and expanding maternal-fetal medicine units in Germany, the United Kingdom, and France are absorbing imaging system deployments.
- Genetic Testing:Chromosomal microarray and whole-exome sequencing platforms identify underlying etiologies in unexplained cases. Pediatric neurology clinics across European university hospitals are integrating cytogenomic testing into standard protocols, compressing diagnostic odyssey timelines for severe presentations.
- Therapeutics:Antiviral agents and neuroprotective candidates address infectious and metabolic substrates. Development pipelines concentrate in sustained R&D programs targeting congenital infection sequelae.
- Supportive Care:Physical therapy, occupational intervention, and nutritional management address functional sequelae. Demand concentrates in rehabilitation networks serving motor and cognitive developmental delays.
Most installed capacity flows through Diagnostic Tools. Expansion is steepest in Genetic Testing.
End User:
Specialist density determines service accessibility, with concentration effects favoring academic medical centers over community settings.
- Pediatrics:General pediatricians conduct initial screening and longitudinal growth monitoring. Brazil's public health campaigns are routing screening volume through primary care networks in Zika-affected municipalities.
- Neurologists:Pediatric neurologists manage complex diagnostic workups and seizure comorbidities. Workforce scarcity in emerging markets is creating access bottlenecks despite equipment availability.
- Genetic Counselors:Pre-test risk assessment and post-test interpretation services bridge laboratory and clinical domains. European cytogenomic adoption is expanding counselor staffing in Germany, France, and the United Kingdom.
- Rehabilitation Centers:Multidisciplinary teams deliver motor, speech, and cognitive interventions. Service consolidation under regional contracts in England and Brazil is concentrating purchasing authority.
Service volume concentrates in Pediatrics. Specialist capacity is expanding fastest in Genetic Counselors.
Delivery Mode:
Facility-based care retains diagnostic complexity while remote modalities capture monitoring and follow-up.
- Inpatient:Neonatal intensive care units manage acute presentations and metabolic stabilization. Tertiary centers in Brazil and European university hospitals absorb high-acuity births with congenital anomaly protocols.
- Outpatient:Specialty clinics conduct scheduled assessments and developmental surveillance. Pediatric neurology expansion in Germany, the United Kingdom, and France is extending outpatient diagnostic capacity.
- Telehealth:Remote developmental monitoring platforms extend specialist reach into rural and underserved regions. WHO surveillance standardization is harmonizing cross-border data collection for remote assessment protocols.
- Home Care:Family-delivered therapies and nursing support address chronic care needs. Reimbursement frameworks for integrated home-based services are emerging in European bundled contracting models.
Diagnostic complexity retains Inpatient and Outpatient dominance. Telehealth is gaining structural traction fastest.
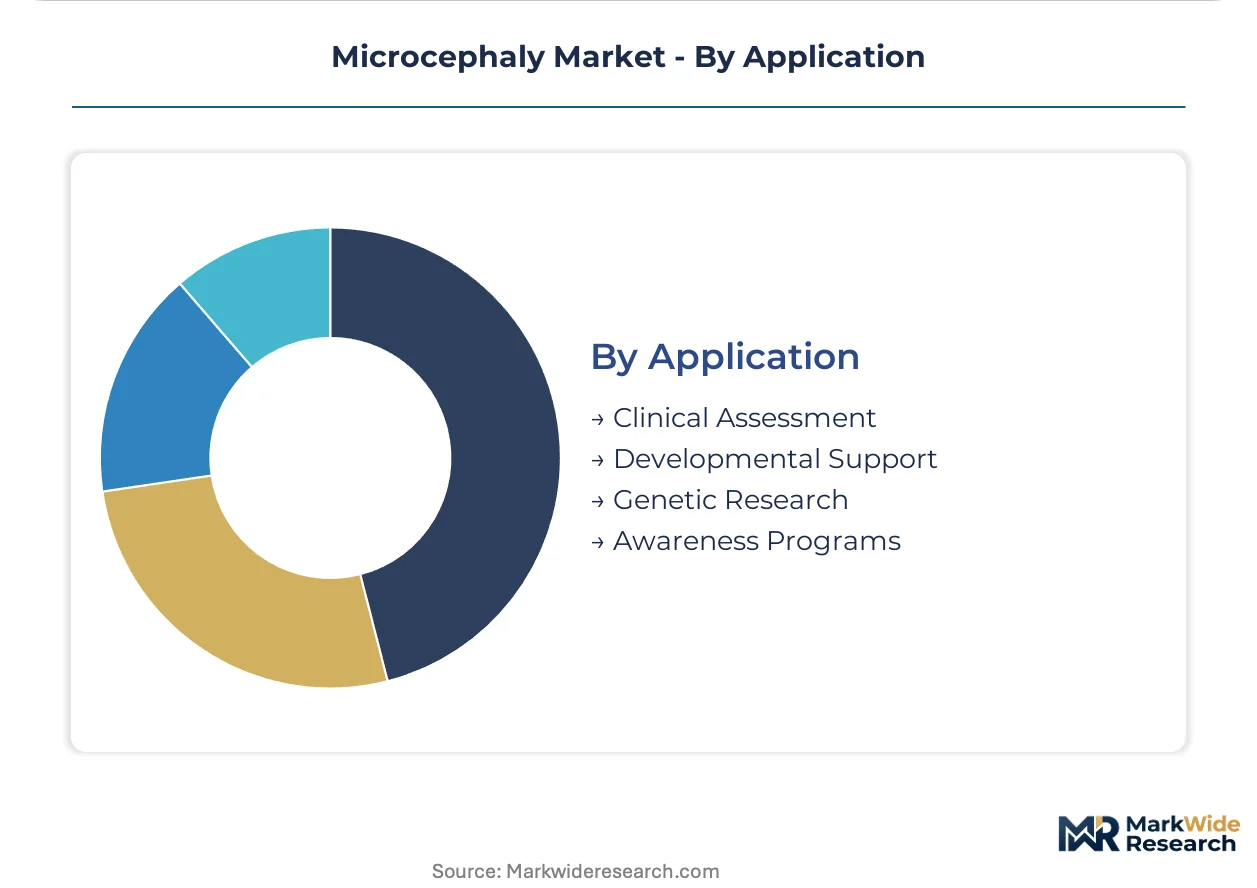
Application:
Clinical utility separates reimbursable care from public health investment and research funding streams.
- Clinical Assessment:Diagnostic confirmation and etiological classification drive medical decision-making. ANVISA protocols in Brazil and EMA centralized procedures in Europe are conditioning assay registration requirements.
- Developmental Support:Early intervention services target neuroplasticity windows. Rehabilitation networks in England and Brazil are consolidating service contracts under regional purchasing authorities.
- Genetic Research:Biobanking and variant databases advance etiological understanding. WHO birth defect surveillance standards are harmonizing cross-border registry participation.
- Awareness Programs:Public health campaigns address maternal infection prevention and screening compliance. Brazil's national health surveillance programs are intensifying Zika-related congenital syndrome education.
Reimbursed service volume concentrates in Clinical Assessment. Public health investment is expanding fastest in Awareness Programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered large-scale public health responses to Zika-linked microcephaly during the 2015-2016 epidemic, establishing surveillance protocols that now shape diagnostic infrastructure investment across multiple continents.
Brazil
Municipal health departments in Zika-affected regions are absorbing molecular diagnostic platforms for maternal-fetal screening. ANVISA registration requirements condition market access for congenital syndrome assays. São Paulo's university hospital networks are consolidating high-complexity genetic testing into designated reference centers.
Germany
Pediatric neurology clinics in Bavaria and North Rhine-Westphalia are expanding cytogenomic testing capacity for unexplained neurodevelopmental presentations. EMA centralized procedures govern IVD medical device market access across EU member states. Berlin-Brandenburg's academic medical centers are integrating whole-exome sequencing into standard-of-care protocols.
United States
FDA premarket review pathways for breakthrough-designated diagnostics are accelerating commercialization timelines for novel neurodevelopmental screening technologies. Reference laboratories in Greater Boston and the San Francisco Bay Area are building validation capabilities ahead of anticipated regulatory clearances. NIH-funded birth defect registries are harmonizing data collection standards.
United Kingdom
NHS England commissioners are centralizing high-complexity genetic testing into designated supraregional centers under consolidated service contracts. Genomics England's 100,000 Genomes Project infrastructure is repurposing sequencing capacity for rare disease diagnosis. London's tertiary pediatric centers are absorbing interpretive workload through automated variant filtering platforms.
France
ANSM oversight of in-vitro diagnostic performance standards is conditioning assay registration for prenatal screening applications. Île-de-France's maternal-fetal medicine units are deploying AI-assisted fetal neurosonography for automated cranial biometry. Auvergne-Rhône-Alpes university hospitals are piloting integrated care contracts bundling diagnostic and rehabilitative services.
Microcephaly Market Competitive Landscape
Capital-heavy diagnostic equipment manufacturers compete with asset-light molecular assay developers for positioning across prenatal and neonatal screening networks. The vendor base concentrates around three strategic tiers: diversified life science conglomerates with imaging and laboratory automation portfolios, specialized genetic testing platform providers, and emerging point-of-care molecular diagnostic firms. Consolidation pressure favors integrated solution bundling over standalone product sales. Geographic expansion through distributor partnerships and technology licensing agreements represent the dominant competitive moves.
Among diversified life science conglomerates, Merck KGaA, Danaher, and F. Hoffmann-La Roche Ltd. exemplify the capital-intensive tier anchoring high-throughput laboratory infrastructure. These Darmstadt-, Washington DC-, and Basel-based entities occupy positions spanning reagent supply, automated systems, and clinical diagnostics services. Their scale permits sustained R&D commitments across multiple congenital anomaly screening modalities while absorbing regulatory compliance costs that constrain smaller entrants.
| Leading Market Players |
|---|
| Merck KGaA |
| Novartis AG |
| Beckman Coulter Inc. |
| bioMerieux |
| Bio-Rad Laboratories, Inc |
| Danaher |
| Hologic |
| F. Hoffmann-La Roche Ltd. |
| Inovio Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Pediatric neurologist concentration in Germany, the United Kingdom, and France creates labor-cost differentials that widen pricing-tier spreads between premium academic medical centers and standard community hospitals. ANVISA registration requirements in Brazil and EMA centralized procedures in Europe add regulatory compliance layers that further stratify cost structures across delivery settings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs diagnostic service contracts. Premium tiers capture academic medical centers with whole-exome sequencing and AI-assisted fetal neurosonography; standard tiers serve regional hospital networks with chromosomal microarray and automated hematology; economy tiers address primary care screening with basic ultrasound biometry. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from public health procurement consolidation under regional laboratory networks in Brazil and England. Community hospitals and rural clinics exhibit highest price sensitivity; tertiary pediatric centers demonstrate lowest sensitivity due to research funding offsets.
Supply Chain Analysis
Direct-to-hospital channels handle high-complexity diagnostic equipment demand from academic medical centers; distributor-mediated routes serve mid-tier hospital networks and primary care expansion. Supply concentrates in Germany, the United States, and Japan for automated hematology and flow cytometry systems; China and South Korea dominate reagent and consumable manufacturing. Raw material dependencies include semiconductor components for sequencing platforms, optical sensors for imaging systems, and specialized reagents for molecular assays. Single-source vulnerability in next-generation sequencing consumables creates supply continuity exposure. Distribution runs through regional laboratory networks consolidating purchasing authority in Brazil and European national health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Microcephaly Market functions as a stable compounder anchored by mandatory newborn screening mandates and expanding prenatal diagnostic infrastructure. WHO surveillance standardization and national birth defect registry expansion provide structural demand visibility.
For Market Incumbents: To counter specialist workforce scarcity limiting diagnostic service expansion, Merck KGaA and Danaher should deepen backward integration into reagent manufacturing to secure input cost stability. Novartis AG must anchor capacity addition in Brazil's Zika-affected municipalities where ANVISA protocols concentrate molecular diagnostic demand. Certification investment in EMA MDR harmonization streamlines market access across EU member states.
For New Entrants and Emerging Players: Telehealth delivery platforms represent the most penetrable white-space target, extending specialist reach into rural and underserved regions without proportional workforce hiring. Point-of-care molecular testing for same-day Zika and TORCH screening in primary prenatal care settings offers second entry path. Go-to-market angle should emphasize miniaturized nucleic acid amplification platforms bypassing centralized laboratory infrastructure requirements.
For Investors and Strategic Acquirers: Diversified life science conglomerates are the most active acquirer in this space, consolidating genetic testing platform providers and point-of-care diagnostic firms. Long-term viability frames around integrated care contracts bundling diagnostic, therapeutic, and rehabilitative services. Acquisition target archetype: asset-light molecular assay developers with ANVISA or EMA regulatory pathways. Signal to watch: reimbursement framework finalization for exome sequencing across national health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Harmonization Pathway | Centralized procedures streamline IVD market access across 27 EU member states. |
| ANVISA Registration Completion | Brazil's congenital syndrome assay protocols condition product commercialization timelines. |
| Hospital System Partnership | São Paulo university hospital networks consolidate high-complexity genetic testing demand. |
| Software Companion Development | AI-assisted fetal neurosonography compresses diagnostic reporting timelines in maternal-fetal units. |
| Reimbursement Strategy | Exome sequencing coverage policies determine diagnostic pathway economics across payer systems. |
Research Methodology
Multiple input streams — primary interviews with pediatric neurologists, genetic counselors, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, and WHO surveillance protocols; and triangulation across bottom-up equipment deployment tracking and top-down health expenditure analysis — were reconciled to construct market estimates. Conversations with clinical laboratory directors in Brazil, Germany, and the United Kingdom informed diagnostic capacity expansion assumptions. Secondary sources included ANVISA registration databases, NHS England service contract disclosures, and Genomics England infrastructure reports.
Data-stream reconciliation across product type, end user, delivery mode, and application dimensions shaped the analytical framework. Segmentation modeling captured diagnostic tools, genetic testing, therapeutics, and supportive care modalities across inpatient, outpatient, telehealth, and home care delivery settings. CAGRs were derived from installed base expansion trajectories and service volume intensity projections. Forecast inputs incorporated Zika surveillance mandate compliance rates, chromosomal microarray adoption curves in European pediatric neurology clinics, and telehealth infrastructure deployment timelines in rural health systems.
Regulatory pathway delays, sequencing cost volatility, and specialist workforce pipeline constraints are the dominant revision risks to base-case projections. Forecasts reflect assumptions regarding WHO ICD coding adoption timelines and national registry participation rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Coagulation Disorders Market