
 Strep Throat Treatment Market | 2026-2036
Strep Throat Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Strep Throat Treatment Market Analytics
Indian generic antibiotic manufacturers is repositioning output toward penicillin and macrolide formulations serving strep throat protocols. Pfizer Inc. leverages its cephalosporin manufacturing scale to dominate hospital procurement channels across multiple continents. GlaxoSmithKline plc anchors its position through sustained R&D investment in pediatric-formulated amoxicillin suspensions. Teva Pharmaceutical Industries Ltd. competes aggressively on cost in the retail pharmacy segment with broad-spectrum generic alternatives.
Strep throat treatment encompasses pharmacological and supportive therapies targeting Group A Streptococcus pyogenes infection, with antibiotics typically prescribed at standard weight-based dosing regimens to eradicate bacterial load and prevent rheumatic fever sequelae. The primary commercial purpose centers on reducing symptom duration, preventing suppurative complications, and interrupting community transmission chains. Antibiotics command the largest product type revenue pool given mandatory prescription status and established clinical guidelines, while throat lozenges represent a mature, lower-margin adjunct category with heavy private-label competition. Oral treatment mode dominates volume due to patient compliance advantages, though injectable formulations retain structural importance in severe or vomiting pediatric cases where absorption reliability outweighs convenience considerations.
FDA antibiotic stewardship programs and CDC prescribing guidelines jointly constrain inappropriate broad-spectrum use, pushing demand toward narrow-spectrum penicillin derivatives with established susceptibility profiles. EMA pharmacovigilance frameworks and national reimbursement formularies across European member states further shape product access and pricing negotiations for strep throat therapeutics. Stakeholders must monitor evolving rapid molecular diagnostic adoption curves and corresponding shifts in point-of-care prescribing authority that will redistribute volume between clinic-administered and pharmacy-dispensed treatment pathways.
Market Dynamics
FDA streamlined approval pathways for point-of-care molecular diagnostics are compressing the time between symptom presentation and antibiotic initiation, fundamentally restructuring how outpatient clinics capture and retain strep throat treatment volume.
Growth Catalysts
- CDC Prescribing Guidelines:Narrow-spectrum penicillin protocols endorsed by CDC stewardship programs redirect demand away from broad-spectrum alternatives toward first-line generics with established susceptibility profiles.
- Pediatric Clinic Networks:Same-day diagnosis and treatment integration in United States urban outpatient settings drives protocol standardization and volume concentration.
- Rapid Molecular Diagnostics:CLIA-waived point-of-care strep tests with nucleic acid amplification are displacing culture-based confirmation in high-throughput clinic environments.
Market Restraints
- API Supply Concentration:Penicillin and macrolide active pharmaceutical ingredient production concentrates in Indian and Chinese manufacturing clusters, exposing formulators to single-source disruption risk.
- Antibiotic Resistance Surveillance:EMA pharmacovigilance frameworks mandate post-market monitoring that extends approval timelines and elevates compliance costs for novel formulations.
- Generic Substitution Mandates:United States state-level substitution laws and pharmacy benefit manager formularies compress branded antibiotic margins irrespective of clinical differentiation.
Strategic Opportunities
- Retail Clinic Expansion:MinuteClinic and similar walk-in formats in United States suburban corridors create new prescription origination points outside traditional physician office channels.
- Pediatric Formulation Innovation:Taste-masked amoxicillin suspensions with extended stability profiles address compliance gaps in school-age populations.
- Telehealth-Triage Integration:Remote consultation platforms coupled with home diagnostic kit distribution are compressing the initial evaluation step before antibiotic authorization.
Industry Challenges
- Diagnostic-Pharmacy Workflow Integration:Point-of-care test result transmission to pharmacy dispensing systems requires EHR interoperability investments that strain independent clinic capital budgets.
- Antimicrobial Stewardship Training:Frontline clinicians face competency gaps in rapid test interpretation and resistance-pattern awareness that slow protocol adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strep Throat Treatment Market |
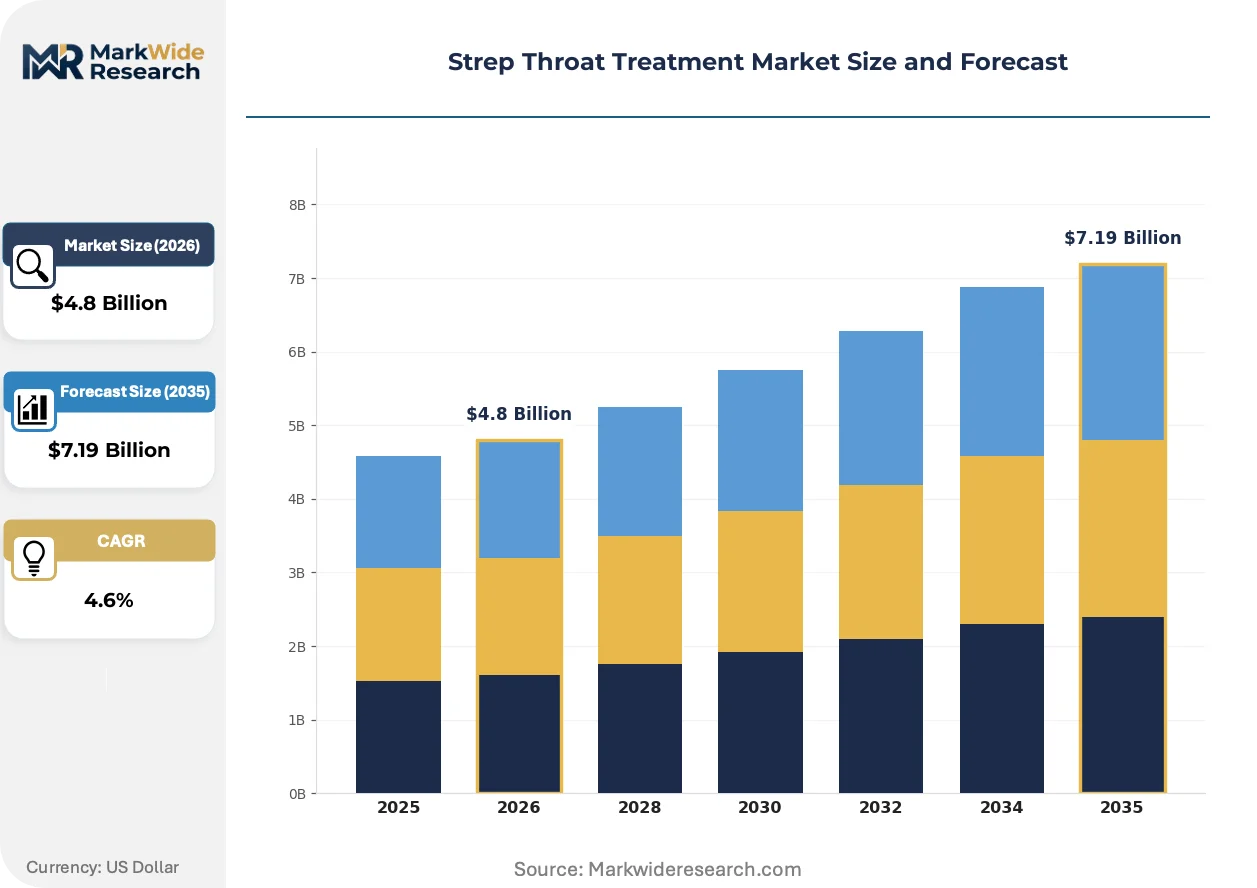
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Antipyretics, Throat Lozenges End User: Clinics, Hospitals, Home Care, Pharmacies Treatment Mode: Oral, Injectable, Topical, Combination Therapy Age Group: Pediatrics, Adolescents, Adults, Seniors |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Novartis AG, Abbott Laboratories, Sanofi, AstraZeneca, Bayer AG, Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strep Throat Treatment Market Evolving Landscape
Diagnostic-assisted prescribing protocols are compressing the traditional separation between testing and treatment, enabling same-session antibiotic initiation that reshapes patient flow and revenue capture across outpatient settings.
Molecular point-of-care strep assays with nucleic acid amplification technology are expanding into pediatric urgent care networks and school-based health centers. These platforms deliver results within fifteen minutes, eliminating the delay associated with send-out cultures. Retail clinic operators are adopting this technology aggressively, enabling antibiotic dispensing before patient departure and capturing pharmacy revenue that previously leaked to external dispensaries.
EMA pharmacovigilance frameworks and FDA antibiotic stewardship programs are jointly constraining broad-spectrum prescribing authority across European and North American jurisdictions. These regulations elevate documentation requirements for non-first-line selections and mandate prospective audit mechanisms in institutional settings. Hospital formulary committees are responding by restricting macrolide access to documented penicillin allergy cases, compressing volume for intermediate-spectrum alternatives.
Direct-to-consumer telehealth platforms are fragmenting the traditional physician-pharmacy relationship for uncomplicated strep presentations. Patients in United States metropolitan areas increasingly initiate consultations through smartphone applications, receive electronic prescriptions, and select pharmacy fulfillment based on convenience rather than provider affiliation. This channel shift concentrates volume in retail pharmacy chains with integrated digital infrastructure and 24-hour dispensing capability.
Strep Throat Treatment Market Segmentation
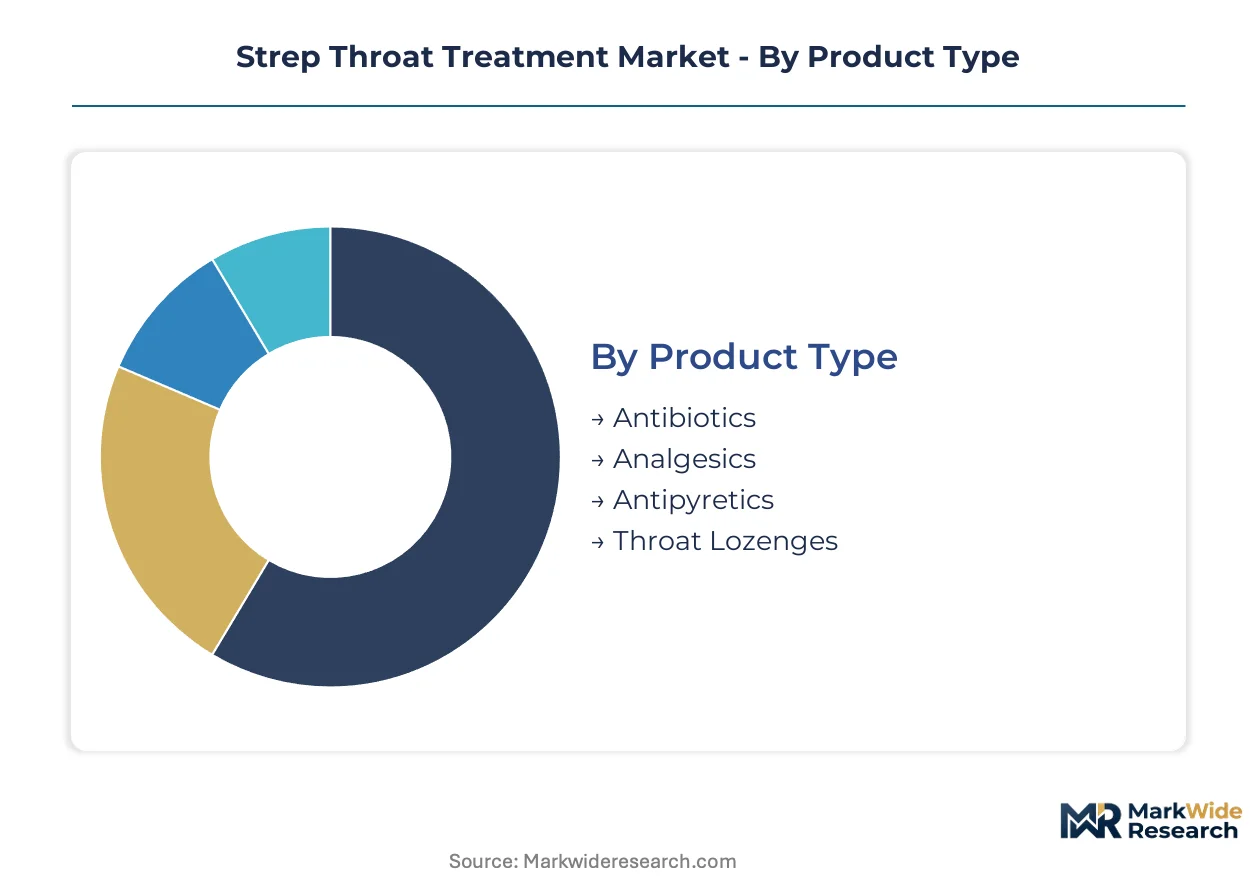
Strep throat treatment segmentation reveals how prescribing authority, reimbursement pathways, and patient compliance requirements reshape commercial opportunity across distinct product and delivery categories. Understanding these divisions exposes where volume concentrates and where new protocols are displacing established workflows.
Product Type:
Cost tier differentiation separates acute infection management from symptomatic relief, with reimbursement status determining commercial scale.
- Antibiotics:Beta-lactam and macrolide formulations targeting Group A Streptococcus eradication command mandatory prescription status and dominate institutional procurement. United States pediatric clinics drive volume through rapid diagnostic-assisted protocols that compress time-to-treatment.
- Analgesics:NSAID and acetaminophen combinations address pharyngeal pain without antibacterial activity, serving adjunct roles in comprehensive management. Retail pharmacy chains capture recurring purchase patterns through private-label positioning and 24-hour accessibility.
- Antipyretics:Fever-reducing agents prescribed alongside antibiotics to manage systemic symptoms during acute infection phases.
- Throat Lozenges:Demulcent and anesthetic preparations offering transient symptomatic relief with minimal clinical differentiation.
Antibiotics lead volumes today; analgesics are gaining share fastest through over-the-counter channel expansion.
End User:
Volume distribution tracks the migration of diagnostic capability from centralized laboratories to point-of-care settings.
- Clinics:United States urban outpatient networks integrate same-day molecular diagnostics with immediate antibiotic dispensing, capturing patient flow that previously required multi-visit protocols. CLIA-waived strep assays enable prescription authorization within fifteen minutes of presentation.
- Hospitals:Emergency departments and inpatient units manage severe presentations with IV antibiotic access and observation capacity, though volume share contracts as ambulatory protocols improve.
- Home Care:Telehealth-triage platforms and home diagnostic kit distribution compress initial evaluation steps before electronic prescription routing.
- Pharmacies:Retail clinic operators co-located with dispensing infrastructure capture prescription origination through walk-in diagnostic services.
Clinics anchor current prescription origination; home care channels are expanding most quickly through digital health integration.
Treatment Mode:
Patient compliance requirements and absorption reliability concerns determine formulation selection across age and severity spectrums.
- Oral:Tablet and liquid suspensions dominate pediatric and ambulatory populations due to administration convenience and established palatability profiles. Taste-masked amoxicillin formulations address school-age compliance gaps with extended stability.
- Injectable:Intramuscular cephalosporin preparations retain structural importance in vomiting pediatric cases where gastrointestinal absorption is unreliable. Hospital procurement channels prioritize manufacturing scale and cold-chain integrity.
- Topical:Limited application for localized symptomatic relief without systemic antibacterial effect.
- Combination Therapy:Co-packaged antibiotic-analgesic protocols addressing multiple symptom domains in single dispensing events.
Oral formulations dominate current dispensing patterns; injectable modes are climbing the fastest in severe pediatric protocols.
Age Group:
Physiological factors and regulatory frameworks shape dosing precision and formulation requirements across developmental stages.
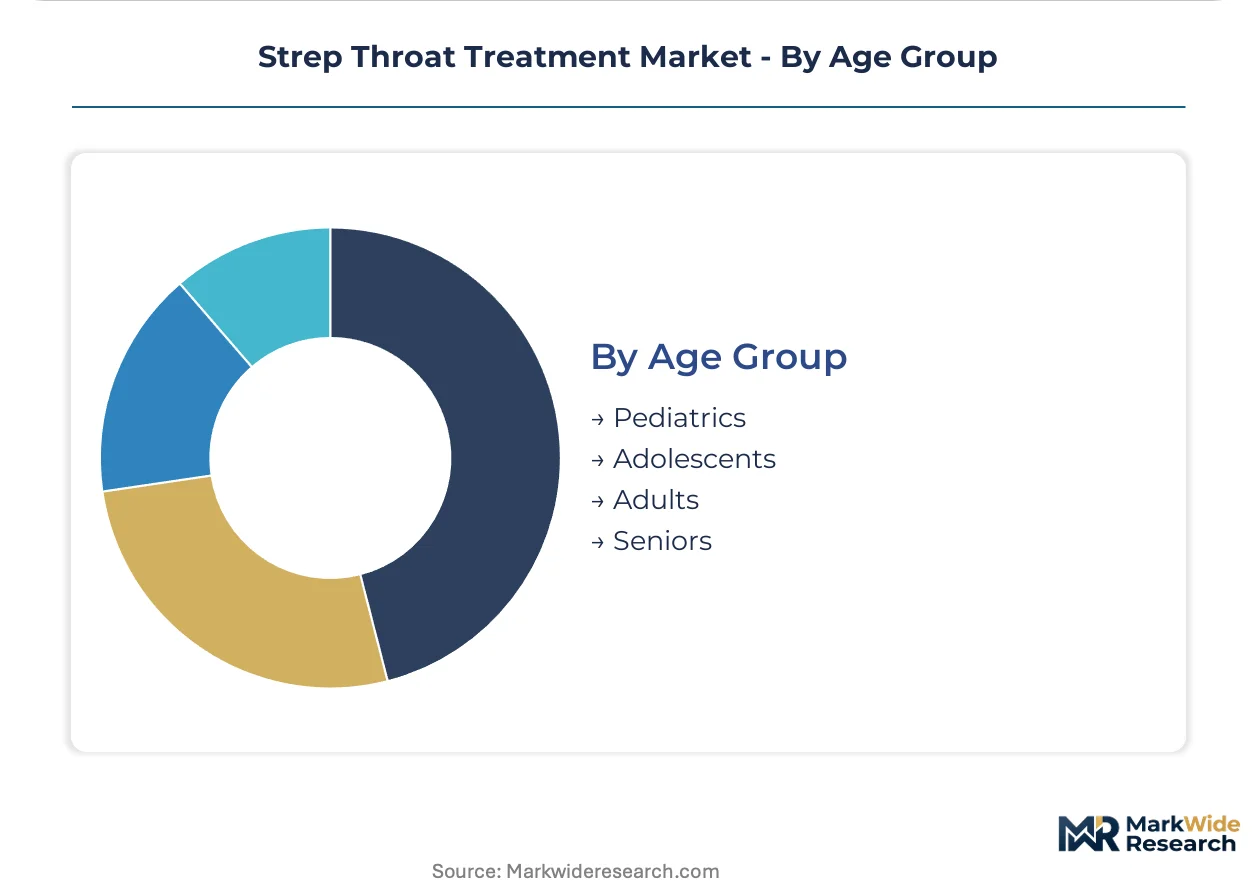
- Pediatrics:Weight-based dosing regimens and palatability engineering drive specialized suspension development, with FDA pediatric exclusivity incentives shaping manufacturer investment priorities.
- Adolescents:Transition populations requiring dose adjustments and compliance support through school-based health center access.
- Adults:Standard tablet formulations with established pharmacokinetic profiles serving occupational health and primary care channels.
- Seniors:Polypharmacy considerations and renal function monitoring requirements influence macrolide selection in long-term care settings.
Pediatrics commands the steepest expansion trajectory through school-based diagnostic deployment; adults retain the largest absolute volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate generic antibiotic manufacturing in jurisdictions with streamlined active pharmaceutical ingredient oversight, while formulation and packaging gravitate toward markets with established pediatric distribution networks and reimbursement density.
United States
Urban pediatric clinics in Chicago, Houston, and Atlanta deploy CLIA-waived molecular diagnostics to compress same-day treatment protocols. FDA streamlined approval pathways for point-of-care strep tests reshape prescribing behavior across outpatient networks. MinuteClinic operators in suburban Dallas-Fort Worth corridors capture prescription origination through integrated diagnostic-dispensing workflows.
India
Hyderabad and Ahmedabad manufacturing clusters supply penicillin and macrolide active pharmaceutical ingredients to global formulators seeking cost-competitive sourcing. CDSCO regulatory frameworks govern export certification timelines that influence contract manufacturing competitiveness. Mumbai-based generic houses reposition output toward strep throat protocol formulations serving North American and European procurement channels.
Germany
EMA pharmacovigilance frameworks mandate post-market surveillance that elevates compliance costs for novel antibiotic submissions. Bavarian pharmaceutical clusters specialize in pediatric suspension engineering with extended stability profiles. Berlin-based hospital procurement consortia restrict macrolide access to documented penicillin allergy cases, compressing volume for intermediate-spectrum alternatives.
China
NMPA regulatory harmonization initiatives accelerate domestic generic approval timelines for beta-lactam formulations targeting domestic and export markets. Yangtze River Delta manufacturing hubs concentrate cephalosporin active pharmaceutical ingredient production with vertical integration into finished dosage forms. Shanghai-based formulators supply hospital procurement channels across Southeast Asian jurisdictions.
United Kingdom
NHS antimicrobial stewardship programs enforce narrow-spectrum penicillin protocols in primary care settings across Greater London and the Midlands. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for rapid diagnostic platforms. Manchester and Birmingham clinic networks integrate telehealth-triage platforms with electronic prescription routing to retail pharmacy chains.
Strep Throat Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue diagnostic-pharmacy workflow integration and pediatric formulation specialization. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with cephalosporin manufacturing scale, regional generic specialists competing on cost in retail pharmacy segments, and diagnostic-platform developers capturing clinic-level prescribing authority. Consolidation pressures concentrate among API suppliers seeking backward integration into finished dosage forms, while formulation specialists pursue geographic expansion through contract manufacturing partnerships.
Among multinational pharmaceutical conglomerates, Pfizer Inc. and GlaxoSmithKline plc occupy positions exemplifying scale-driven and pediatric-focused archetypes respectively. Teva Pharmaceutical Industries Ltd. represents the aggressive cost-competition archetype in retail pharmacy channels. These three entities anchor the competitive structure without exhausting its diversity, as regional generic houses and diagnostic-platform developers populate adjacent tiers with distinct strategic positioning.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Abbott Laboratories |
| Sanofi |
| AstraZeneca |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Others |
Value Network & Pricing Analysis
United States retail pharmacy chains and hospital procurement consortia concentrate antibiotic purchasing power, forcing manufacturers toward volume-based contract pricing with narrow margins on penicillin and macrolide formulations.
Pricing Analysis
Retailer markup compression dominates downstream economics, with pharmacy benefit manager formularies and state-level generic substitution laws eliminating branded antibiotic premiums irrespective of clinical differentiation. Price differentiation hinges on FDA pediatric exclusivity status and manufacturing scale certification, with narrow-spectrum penicillin derivatives commanding stability against macrolide erosion. Cost compression in retail channels is intensifying because Indian generic houses reposition output toward strep throat protocols. Medicaid and uninsured populations exhibit highest price sensitivity, while hospital procurement consortia prioritize supply security over unit cost.
Supply Chain Analysis
Specialized chemical engineering talent availability in Hyderabad and Ahmedabad sustains Indian API manufacturing competitiveness against Chinese cephalosporin producers. Active pharmaceutical ingredient production draws from penicillin fermentation feedstocks, macrolide precursor chemicals, and cephalosporin intermediate compounds. Single-source vulnerability concentrates in Yangtze River Delta manufacturing hubs where environmental regulatory enforcement disrupts seasonal output. Distribution runs through pharmaceutical wholesale distributors serving retail pharmacy chains and hospital procurement channels with cold-chain integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic antibiotic manufacturing presents a geographic-arbitrage opportunity between Indian cost structures and North American reimbursement density, with CDSCO export certification timelines determining contract manufacturing competitiveness.
For Market Incumbents: Acquire molecular diagnostic platform capabilities to capture clinic-level prescribing authority before retail clinic operators consolidate diagnostic-pharmacy workflows. Defend against telehealth-triage fragmentation by embedding electronic prescription routing directly into urgent care EHR systems. Backward integration into penicillin API production mitigates single-source exposure from Indian and Chinese manufacturing clusters. For New Entrants and Emerging Players: Enter via school-based health center diagnostic deployment, the most penetrable channel for rapid molecular strep assays with nucleic acid amplification technology. Target suburban United States corridors where MinuteClinic expansion outpaces traditional physician office density. Partner with telehealth platforms for home diagnostic kit distribution preceding electronic prescription authorization. For Investors and Strategic Acquirers: Diagnostic-platform developers with CLIA-waived strep assays are the most active acquirer category in this space, seeking captive antibiotic dispensing relationships. Five-to-ten year viability favors manufacturers with pediatric formulation specialization and EHR interoperability investments. Watch FDA streamlined approval pathway expansion for point-of-care molecular diagnostics as the inflection signal for clinic workflow restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA streamlined pathways for CLIA-waived strep tests compress diagnostic-to-treatment timelines in outpatient settings. |
| Manufacturing Scale-Up | Indian API clusters expand penicillin fermentation capacity to serve North American generic procurement channels. |
| Platform Integration | EHR interoperability investments enable point-of-care test result transmission to pharmacy dispensing systems. |
| Geographic Expansion | Retail clinic operators deploy suburban corridor networks capturing prescription origination outside traditional channels. |
| Pipeline Diversification | Taste-masked amoxicillin suspensions address pediatric compliance gaps with extended stability profiles. |
Research Methodology
Direct dialogue with formulary directors, hospital procurement managers, regulatory affairs leads, and retail pharmacy chain executives grounded qualitative findings in operational reality. Secondary validation drew from FDA filings, EMA pharmacovigilance reports, ClinicalTrials.gov entries, and CMS Medicare reimbursement data. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated against manufacturer shipment disclosures.
Bottom-up segment modeling tracked antibiotics, analgesics, antipyretics, and throat lozenges across oral, injectable, topical, and combination therapy modes through the projection horizon. Patient population segmentation by pediatric, adolescent, adult, and senior cohorts intersected with clinic, hospital, home care, and pharmacy end-use channels. CAGRs were derived from prescription origination volume trajectories and molecular diagnostic adoption curves, with antibiotic stewardship program enforcement intensity and rapid test penetration rates serving as key forecast inputs.
Inputs from FDA approval databases and EMA post-market surveillance repositories were available through the study window; gaps in real-time pharmacy dispensing data introduce uncertainty bands around retail channel volume estimates. Forecasts reflect documented assumptions regarding CLIA-waiver expansion timelines and telehealth regulatory permanence. Material deviation in FDA diagnostic approval velocity or CDC stewardship program enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Lung Cancer Therapeutics Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market