
 Osteogenesis Imperfecta Treatment Market | 2026-2036
Osteogenesis Imperfecta Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Osteogenesis Imperfecta Treatment Market Outlook
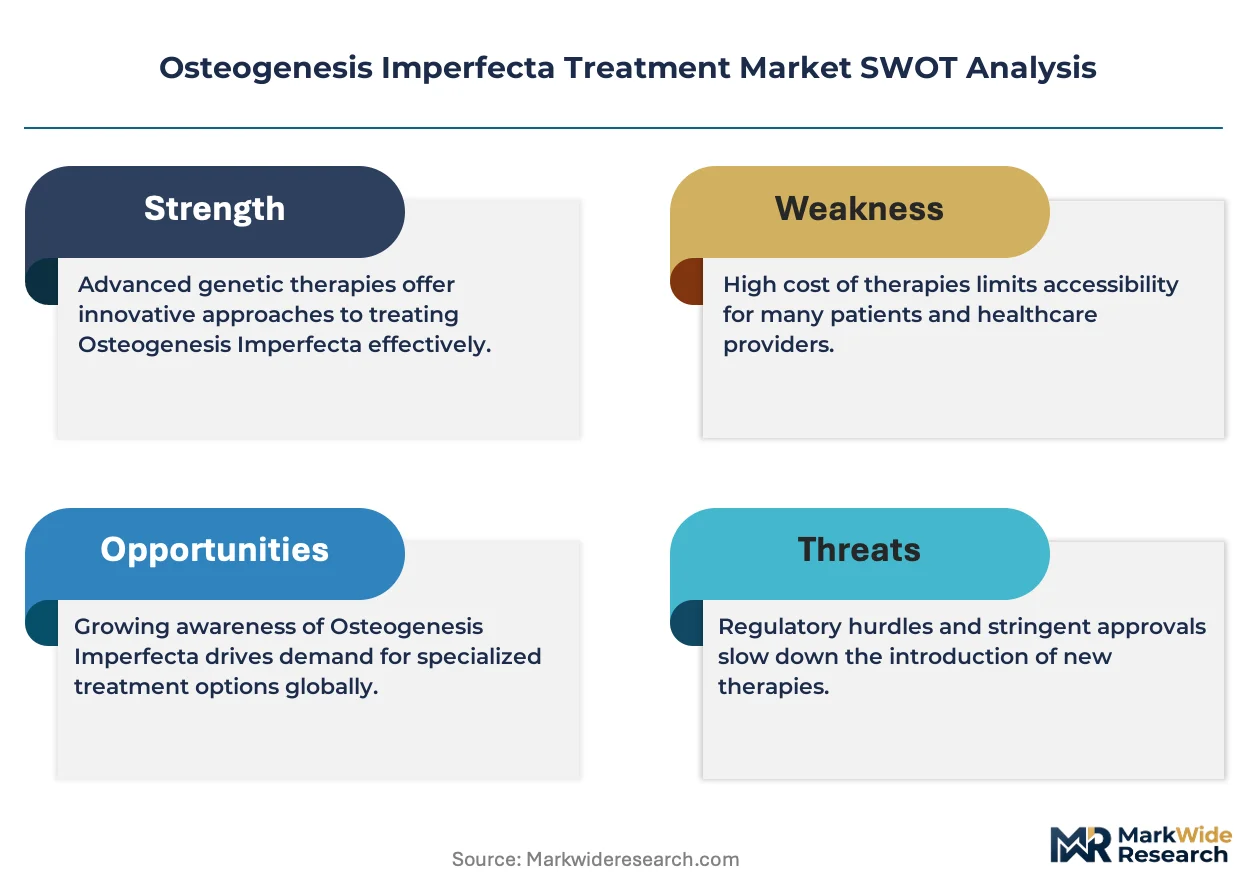
Modular combination therapies is pivoting how clinicians configure OI treatment protocols, moving from single-agent bisphosphonate regimens toward integrated surgical-pharmacological bundles. Ultragenyx Pharmaceutical Inc. leverages its rare disease commercial infrastructure to sustain access across dispersed patient populations. Amgen Inc. anchors its position through biologics manufacturing scale, while Mereo BioPharma Group plc differentiates via novel sclerostin inhibitor development for bone fragility.
Osteogenesis imperfecta treatment encompasses pharmacological and surgical interventions targeting collagen type I defects that cause brittle bone disease, with intravenous bisphosphonates like pamidronate administered in cyclic infusions to suppress osteoclast-mediated resorption and reduce fracture incidence. The primary purpose centers on improving bone mineral density, managing pain, and enabling functional mobility across pediatric and adult patient cohorts. Intravenous bisphosphonates dominate current prescribing patterns due to established pediatric efficacy data and hospital-based infusion infrastructure. Growth hormones occupy a narrower but expanding niche for patients with concurrent short stature, while oral bisphosphonates compete primarily on homecare convenience in maintenance-stage protocols.
The FDA orphan drug program shapes developer incentives through seven-year exclusivity and waived user fees, while the EMA's Committee for Orphan Medicinal Products coordinates parallel European designations that streamline cross-border trial recruitment. ISO 14155 governs clinical investigation standards for interventional OI studies, ensuring harmonized safety documentation across multinational protocols. Stakeholders must monitor how evolving pediatric trial endpoint guidance from both regulators affects biomarker validation for novel anabolic agents.
Market Dynamics
Pediatric orthopedic centers are consolidating treatment protocols around bisphosphonate infusion cycles, creating standardized care pathways that reshape pharmaceutical procurement and surgical scheduling across referral networks.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity and waived user fees accelerate developer commitment to rare bone disease portfolios.
- Specialized OI Clinic Expansion:NIH-affiliated treatment centers anchor multi-state referral networks for severe type III and IV patients.
- Biologics Manufacturing Scale:Production infrastructure for anabolic bone agents enables cost-efficient supply to dispersed pediatric populations.
Market Restraints
- Intravenous Infusion Infrastructure Dependency:Hospital-based pamidronate administration limits access in rural and underserved regions.
- Collagen Type I Defect Heterogeneity:Genetic mutation diversity complicates standardized endpoint validation across clinical trials.
- Reimbursement Variability:Payer coverage for growth hormone adjunct therapy remains inconsistent across state Medicaid programs.
Strategic Opportunities
- Homecare Oral Bisphosphonate Transition:Maintenance-stage protocols create channel expansion beyond hospital infusion centers.
- EMA Parallel Designation Pathway:Coordinated orphan status streamlines multinational trial recruitment for novel sclerostin inhibitors.
- Surgical-Pharmacological Bundle Integration:Combined intramedullary rodding and cyclic bisphosphonate regimens improve outcomes in severe OI types.
Industry Challenges
- Pediatric Biomarker Validation:ISO 14155 harmonization demands complicate bone mineral density surrogate endpoint acceptance.
- Dispersed Patient Logistics:Rare disease prevalence requires costly travel support programs for specialized center access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteogenesis Imperfecta Treatment Market |
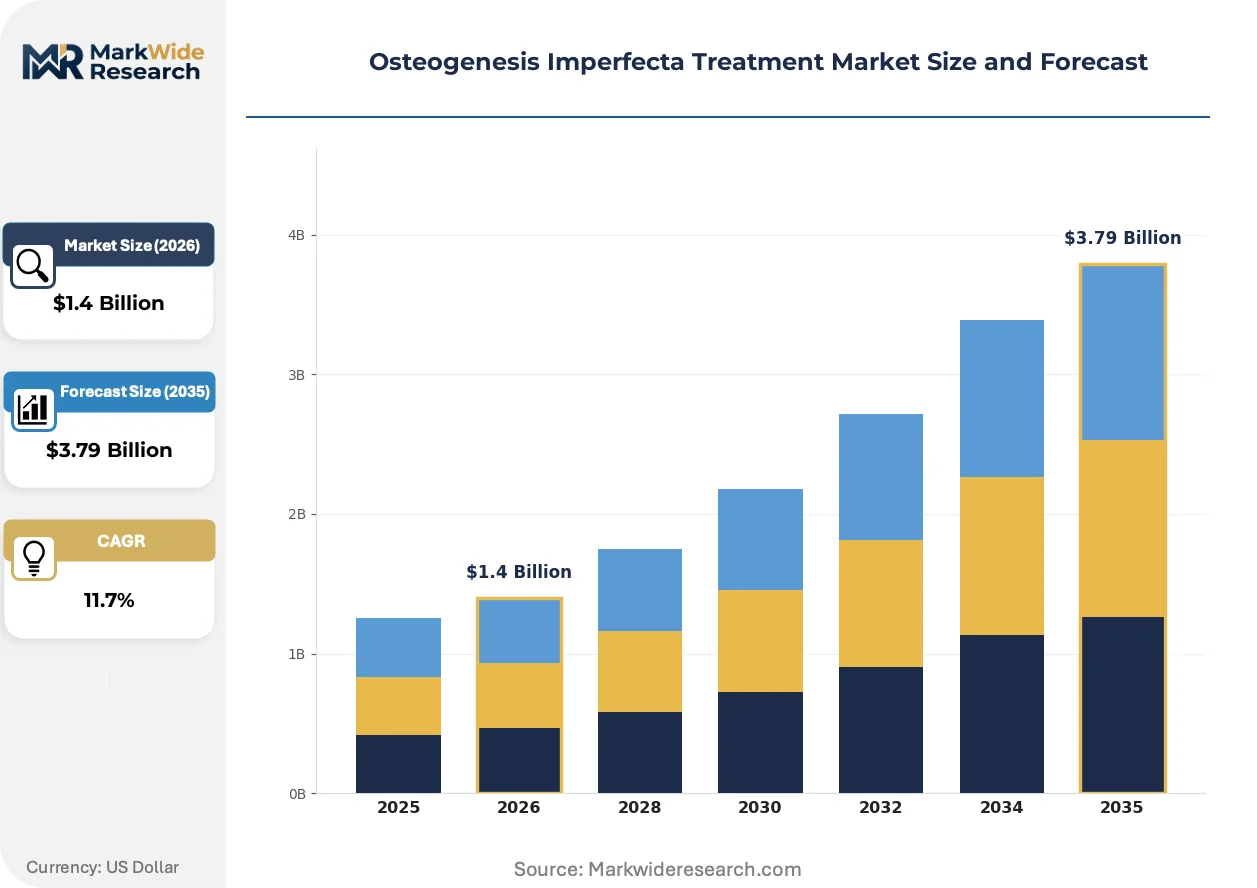
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Bisphosphonates, Oral Bisphosphonates, Growth Hormones, Other Treatments Administration Route: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Stage of Treatment: Preventive, Acute, Chronic, Maintenance |
| Companies Covered | BioSenic SA, UCB, Mereo BioPharma Group plc, CELGENE CORPORATION, Ascendis Pharma A/S, Ultragenyx Pharmaceutical Inc., OrthoPediatrics Corp., Eli Lilly and Company, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteogenesis Imperfecta Treatment Market Strategic Shifts
Modular therapeutic configurations are displacing single-agent protocols across severe OI management, with clinicians integrating pharmacological, surgical, and rehabilitative interventions into coordinated care bundles.
Sclerostin inhibition technology is overtaking traditional antiresorptive mechanisms in developmental pipelines. Novel biologics targeting the Wnt signaling pathway demonstrate anabolic bone formation potential. Pediatric endocrinology departments at tertiary centers are prioritizing these candidates for compassionate use protocols. The shift is compressing development timelines for agents that simultaneously increase bone mass and improve bone quality metrics.
EMA Committee for Orphan Medicinal Products coordination is harmonizing European trial frameworks with FDA precedent. Parallel designation procedures reduce redundant documentation burdens for developers pursuing transatlantic approval. Pediatric orthopedic research consortia in Germany, France, and the Netherlands are consolidating patient registries to meet post-marketing surveillance requirements.
Caregiver-administered home infusion services are fragmenting traditional hospital-centered delivery. Specialty pharmacy distributors are building cold-chain capabilities for bisphosphonate storage and nurse deployment. This channel evolution is most advanced in the United States, where commercial payers favor site-of-care cost differentials and families prioritize reduced travel burdens for cyclic treatment schedules.
Osteogenesis Imperfecta Treatment Market Segmentation
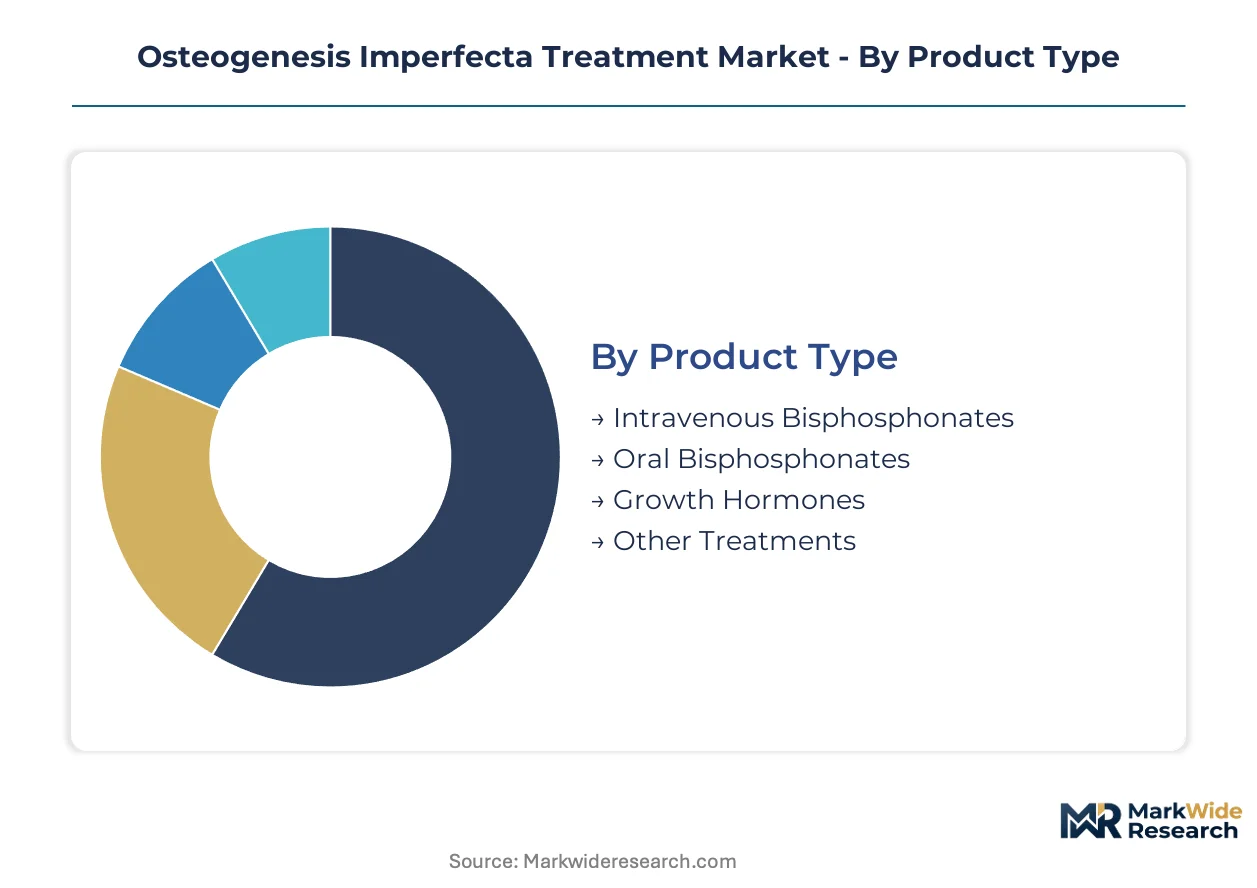
Osteogenesis imperfecta treatment configurations vary dramatically across patient severity, care setting infrastructure, and reimbursement pathways. Understanding how these segments intersect reveals where pharmaceutical investment and clinical protocol standardization are concentrating.
Product Type:
Customization intensity spans from standardized cyclic infusions to patient-tailored combination regimens across this category.
- Intravenous Bisphosphonates:Cyclic pamidronate and zoledronic acid infusions suppress osteoclast-mediated bone resorption through nitrogen-containing pyrophosphate analogs. Demand concentrates at NIH-affiliated pediatric orthopedic centers and tertiary children's hospitals where infusion infrastructure and specialized nursing protocols anchor severe OI type III and IV management.
- Oral Bisphosphonates:Alendronate and risedronate tablets offer home-based administration convenience for maintenance-stage patients with milder type I presentations. Prescribing clusters in suburban and rural markets where travel to infusion centers creates adherence barriers, though bioavailability concerns limit adoption in severe phenotypes.
- Growth Hormones:Recombinant human growth hormone addresses concurrent short stature in pediatric OI cohorts with quantitative collagen defects.
- Other Treatments:Sclerostin inhibitors and novel Wnt pathway modulators occupy developmental and compassionate use niches.
Leading the category by volume: Intravenous Bisphosphonates. Expanding most quickly: Other Treatments.
Administration Route:
Cost tier stratification separates hospital-based premium administration from homecare economy options in this dimension.
- Intravenous:Hospital and ambulatory infusion center delivery of bisphosphonates requires specialized vascular access and cardiac monitoring capabilities. Concentrated demand at pediatric orthopedic centers in the United States where Medicare and commercial payer site-of-care differentials favor institutional billing.
- Oral:Tablet and liquid formulations enable patient or caregiver administration without clinical supervision. Prescribing expands in state Medicaid programs prioritizing cost containment over clinical oversight for stable maintenance-phase patients.
- Subcutaneous:Growth hormone pen injectors and emerging biologic delivery systems target endocrinology clinic populations.
- Topical:Compounded and investigational transdermal formulations occupy preclinical and niche dermatology applications.
Dominant by patient volume: Intravenous. Gaining share fastest: Subcutaneous.
End User:
Application criticality varies from life-sustaining acute intervention centers to quality-of-life maintenance settings.
- Hospitals:Tertiary pediatric centers manage severe OI type III and IV patients requiring intramedullary rodding, cyclic bisphosphonate initiation, and multidisciplinary coordination. Concentrated at academic medical centers with dedicated brittle bone units where surgical and pharmacological bundles integrate.
- Homecare Settings:Specialty pharmacy distributors deploy nurse-administered infusion services for maintenance bisphosphonate cycles. Channel evolution advances fastest in United States commercial payer networks favoring site-of-care cost differentials and families prioritizing reduced travel burdens.
- Clinics:Community endocrinology and orthopedic practices manage milder type I phenotypes and growth hormone monitoring.
- Rehabilitation Centers:Post-fracture and post-surgical functional recovery programs address mobility preservation.
Leading by revenue concentration: Hospitals. Steepest expansion trajectory: Homecare Settings.
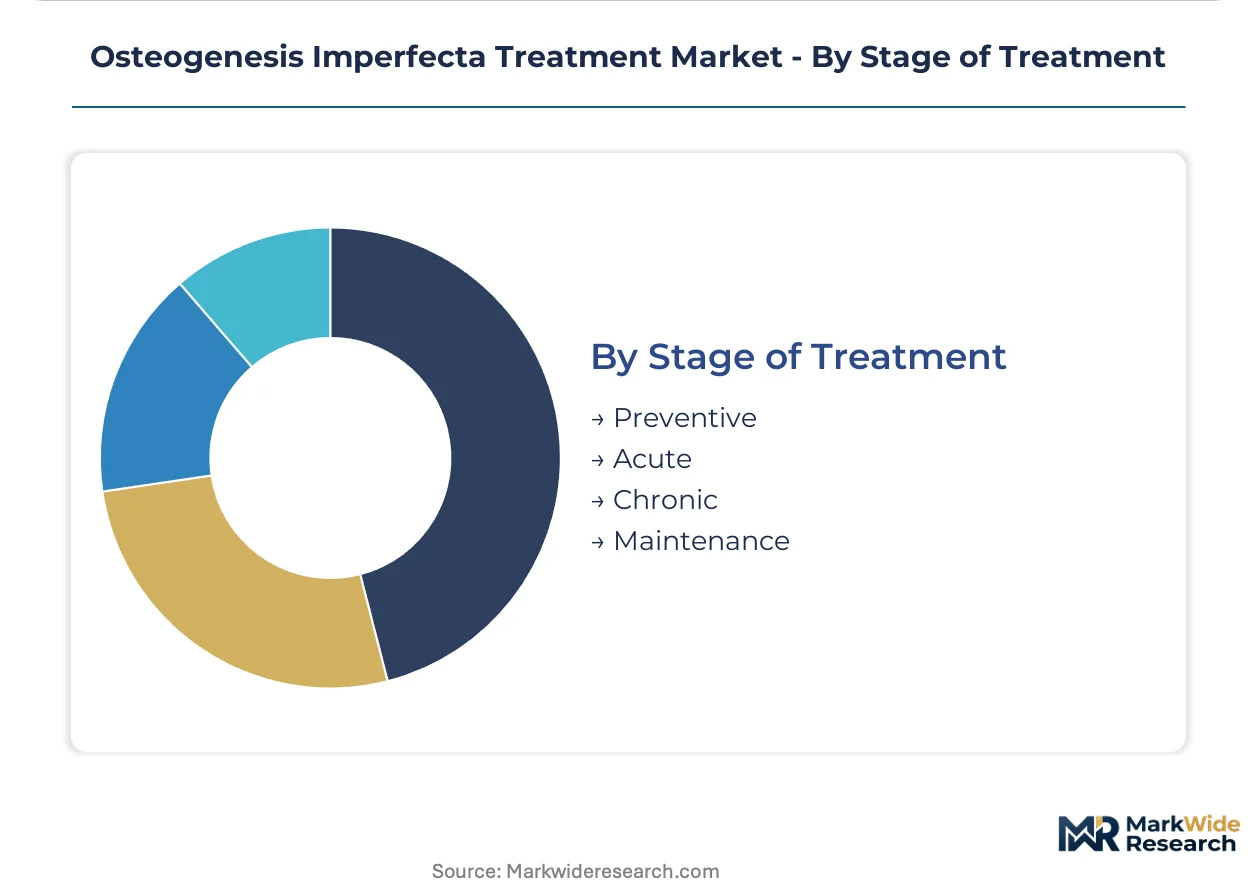
Stage of Treatment:
Patient journey mapping from diagnosis through lifetime management creates distinct protocol and purchasing patterns.
- Preventive:Early bisphosphonate initiation in infancy and toddlerhood aims to maximize bone mineral density before ambulation increases fracture risk. Concentrated at specialized OI clinics where newborn screening referrals and prenatal diagnosis enable intervention timing optimization.
- Maintenance:Long-term cyclic therapy continuation through adolescence and adulthood requires protocol adaptation for growth plate closure and reproductive planning. Demand concentrates in transition medicine programs bridging pediatric and adult care coordination.
- Acute:Fracture management and surgical intervention for severe traumatic events.
- Chronic:Ongoing pain management and secondary complication surveillance.
Dominant by patient-years: Maintenance. Climbing the fastest: Preventive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of bisphosphonate APIs concentrates in contract manufacturing hubs across India and China, while consumption and clinical trial activity cluster in the United States and Western Europe where specialized pediatric orthopedic centers anchor patient access.
United States
NIH-affiliated OI clinics in Bethesda, Maryland and academic medical centers in Boston anchor multi-state referral networks for severe type III and IV patients. FDA orphan drug exclusivity accelerates developer commitment through seven-year market protection and waived user fees. Pediatric orthopedic research consortia in Philadelphia and Houston consolidate patient registries to meet post-marketing surveillance requirements for novel anabolic agents.
Germany
EMA Committee for Orphan Medicinal Products coordination streamlines trial recruitment across university hospitals in Heidelberg and Hamburg. Germany's national pharmaceutical regulator enforces ISO 14155 standards for interventional OI studies, ensuring harmonized safety documentation. The German Pediatric Orthopedic Society consolidates newborn screening referrals in Bavaria and North Rhine-Westphalia to optimize early bisphosphonate initiation timing.
United Kingdom
NHS England's specialized commissioning framework concentrates severe OI management at designated pediatric centers in London and Birmingham. The MHRA aligns pediatric trial endpoint guidance with FDA precedent to accelerate novel sclerostin inhibitor development. Academic research clusters in Oxford and Cambridge prioritize Wnt pathway modulator candidates for compassionate use protocols.
Japan
PMDA's orphan drug designation parallels FDA incentives, with Tokyo and Osaka pediatric centers leading Asia-Pacific trial enrollment for intravenous bisphosphonate protocols. METI funding supports domestic biologics manufacturing scale for anabolic bone agents. The Japanese Orthopaedic Association standardizes care pathways across tertiary children's hospitals in Nagoya and Fukuoka.
Switzerland
Swissmedic coordinates with EMA on parallel designation procedures for rare bone disease portfolios, reducing redundant documentation for developers. Basel and Zurich anchor pharmaceutical R&D clusters where sclerostin inhibition technology advances through preclinical stages. The Swiss Pediatric Orthopedic Group consolidates patient data across Lausanne and Geneva to support biomarker validation for novel agents.
Osteogenesis Imperfecta Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the OI treatment landscape, creating a tiered structure where biologics manufacturing scale anchors one strategic position and rare disease commercial infrastructure anchors another. The market fragments across three archetypes: large-cap pharmaceutical firms with orphan disease divisions, mid-cap rare disease specialists, and orthopedic device manufacturers integrating pharmacological bundles. Dominant competitive moves include strategic partnerships between biologics manufacturers and pediatric orthopedic centers, plus portfolio diversification into homecare oral bisphosphonate channels.
Within the rare disease specialist tier, Ultragenyx Pharmaceutical Inc. and Mereo BioPharma Group plc exemplify focused development strategies targeting dispersed pediatric populations. Amgen Inc. anchors the large-cap biologics manufacturing archetype, leveraging production infrastructure to supply anabolic bone agents cost-efficiently. These three firms occupy positions across the development-commercialization spectrum, from novel sclerostin inhibitor pipelines to established infusion protocol supply.
| Leading Market Players |
|---|
| BioSenic SA |
| UCB |
| Mereo BioPharma Group plc |
| CELGENE CORPORATION |
| Ascendis Pharma A/S |
| Ultragenyx Pharmaceutical Inc. |
| OrthoPediatrics Corp. |
| Eli Lilly and Company |
| Amgen Inc. |
| Others |
Value Chain & Pricing Dynamics
Sclerostin inhibitor manufacturing scale-up is compressing unit economics for anabolic bone agents while concentrating API production in contract manufacturing hubs across India and China. This dual shift simultaneously lowers per-dose costs for developers and tightens supplier leverage over formulation and finishing stages.
Pricing Analysis
Margin tightening in intravenous bisphosphonate tiers reflects site-of-care cost differentials that commercial payers exploit to push utilization toward homecare channels. Three-tier pricing structure across premium institutional, standard ambulatory, and economy homecare levels separates NIH-affiliated centers from suburban infusion networks. Price differentiation hinges on nursing supervision intensity and cold-chain certification grade. Medicaid programs exhibit highest price sensitivity, while commercial payers prioritize site-of-care savings over per-unit drug costs.
Supply Chain Analysis
Regional distribution centers in Indianapolis and Rotterdam anchor hub-and-spoke patterns for bisphosphonate cold-chain deployment to dispersed pediatric populations. API production concentrates in India, China, and Switzerland, with formulation and finishing tethered to FDA-inspected facilities in the United States and Germany. Nitrogen-containing pyrophosphate analogs and recombinant bioreactor media constitute critical input dependencies. Single-source vulnerability in specialized nurse staffing for home infusion creates bottlenecks. Distribution runs through specialty pharmacy networks with direct-to-patient last-mile capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug exclusivity creates a cost-of-compliance moat where seven-year market protection and waived user fees reward developers who navigate pediatric trial endpoint guidance. ISO 14155 harmonization demands further deepen barriers for under-resourced entrants.
For Market Incumbents: Anticipate sclerostin inhibitor pipelines displacing antiresorptive market share by securing priority review vouchers through FDA orphan designation acceleration. Defensive consolidation should center on backward integration into bioreactor manufacturing capacity in Basel or Boston to capture anabolic agent supply leverage. Channel control through specialty pharmacy partnerships protects against homecare oral bisphosphonate erosion. For New Entrants and Emerging Players: Specialty pharmacy distributors represent the most penetrable channel partner type for maintenance-stage oral bisphosphonate protocols in state Medicaid programs. White-space targets cluster in rural and underserved regions where hospital-based infusion infrastructure creates access barriers. Compassionate use protocols at tertiary pediatric centers offer the most viable go-to-market angle for novel Wnt pathway modulators. For Investors and Strategic Acquirers: Exit pathways concentrate in rare disease specialist acquisitions by large-cap biologics manufacturers seeking dispersed patient commercial infrastructure. Long-term viability favors developers with parallel EMA-FDA designation strategies and pediatric biomarker validation capabilities. Watch FDA pediatric trial endpoint guidance revisions as the critical inflection signal for anabolic agent approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Orphan Drug Designation | Priority review vouchers and tax incentives accelerate sclerostin inhibitor development timelines. |
| EMA Parallel Designation Pathway | Coordinated European orphan status streamlines multinational trial recruitment across Heidelberg and Hamburg centers. |
| Specialty Pharmacy Partnership | Homecare infusion channel expansion captures site-of-care cost differentials favored by commercial payers. |
| Bioreactor Manufacturing Scale-Up | In-house production of anabolic bone agents reduces dependency on contract API manufacturers in Asia. |
| Pediatric Biomarker Validation | ISO 14155-compliant surrogate endpoint acceptance enables novel agent approval pathways. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for pipeline and regulatory tracking across the analysis window. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated commercial assumptions. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation anchored market sizing across preventive, maintenance, acute, and chronic treatment stages.
Historical trendline analysis of intravenous bisphosphonate utilization patterns informed the projection framework across the modeling period. Segmentation dimensions modeled include product type, administration route, end user, and stage of treatment, with regional regulatory clusters capturing FDA, EMA, and PMDA pathway variations. CAGRs derived from consensus clinical trial enrollment trajectories and orphan drug approval velocity assumptions, with bone mineral density surrogate endpoint acceptance timelines as a key industry-specific input.
Caveats apply where FDA pediatric trial endpoint guidance revisions, EMA Committee for Orphan Medicinal Products coordination delays, or state Medicaid reimbursement variability could materially shift the outlook. Forecasts reflect documented assumptions regarding bisphosphonate protocol standardization and sclerostin inhibitor pipeline advancement. Periodic stress-testing of base assumptions against regulatory precedent changes and biomarker validation outcomes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Neuroscience Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market