
 US Actinic Keratosis Treatment Market | 2026-2036
US Actinic Keratosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
US Actinic Keratosis Treatment Market Intelligence
Modular treatment protocols is decoupling single-modality prescriptions from bundled care pathways, letting physicians sequence topical agents, cryotherapy, and photodynamic therapy across separate visits. Galderma leverages its dermocosmetic channel to cross-sell maintenance regimens. Bausch Health Companies Inc. anchors its position through vertical control of imiquimod supply and distribution. LEO Pharma A/S differentiates via R&D intensity in field-directed combination therapies.
Actinic keratosis treatment encompasses interventions targeting ultraviolet-induced precancerous epidermal lesions, with topical 5-fluorouracil formulations, imiquimod creams, photodynamic therapy using aminolevulinic acid or methyl aminolevulinate, and cryogenic destruction of visible lesions serving as standard modalities. The primary purpose is preventing progression to squamous cell carcinoma while minimizing cosmetic impact and patient downtime. Topical agents occupy the largest revenue pool due to repeat prescription cycles and broad primary care accessibility. Photodynamic therapy represents the fastest-growing delivery mode as dermatology clinics invest in blue and red light systems. Home-based treatment segments carry thinner margins but expand addressable patient populations beyond specialist access constraints.
FDA oversees premarket approval and post-market surveillance of actinic keratosis drugs and devices, while CMS reimbursement policies determine site-of-care economics for in-office versus home-administered therapies. State-level scope-of-practice regulations govern whether nurse practitioners and physician assistants can independently initiate field-directed treatment, directly affecting channel volume distribution. OSHA standards for clinic-based photodynamic therapy light sources add compliance costs that favor larger dermatology group practices over independent operators. Stakeholders must monitor whether FDA accelerates novel immunomodulatory pathways and how Medicare telehealth flexibilities reshape the home-based versus in-office treatment mix.
Market Dynamics
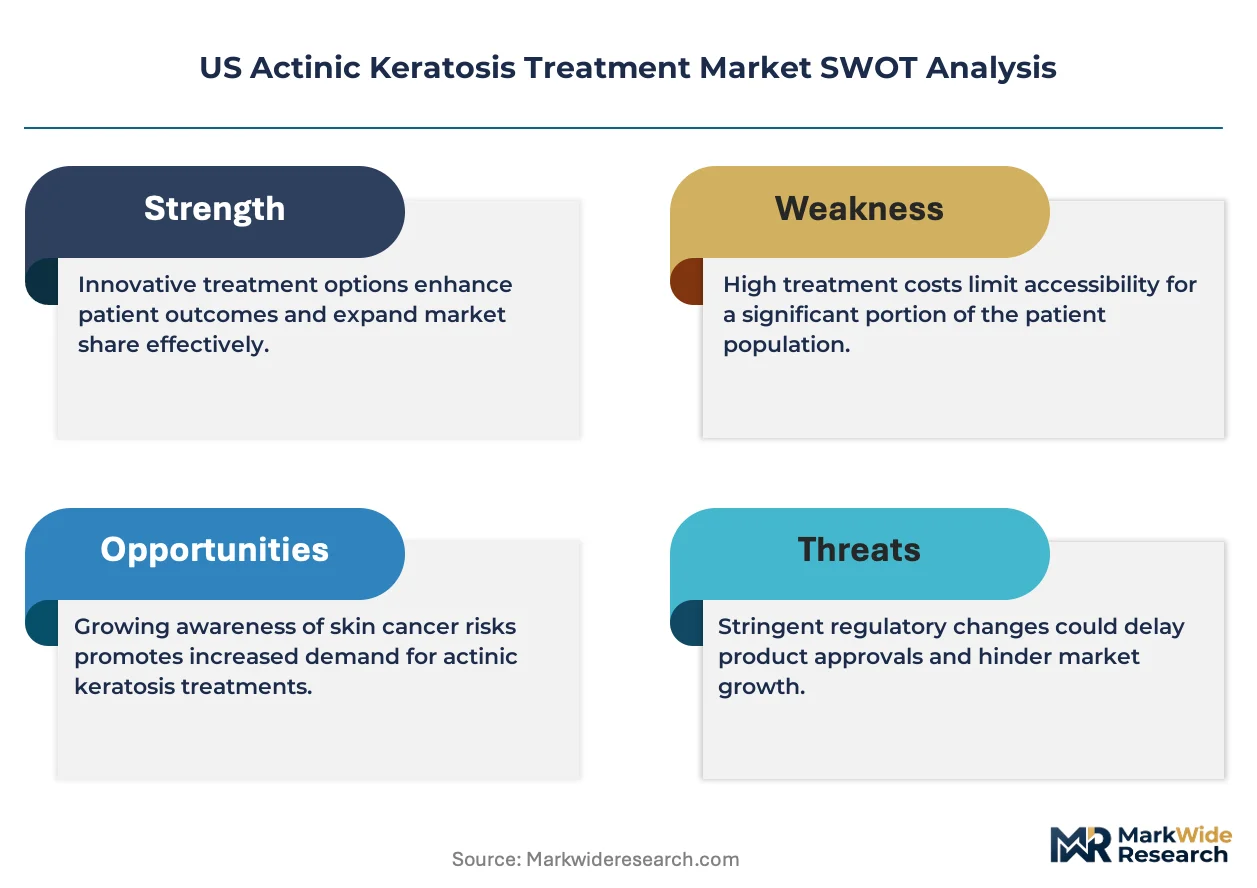
Photodynamic therapy is consolidating the in-office treatment segment as dermatology clinics invest in blue and red light systems, compressing margins on traditional cryotherapy while expanding procedural revenue per patient encounter. This technology shift is redrawing site-of-care economics and forcing repositioning among topical agent manufacturers.
Growth Catalysts
- Sun Belt Demographics:Arizona, Florida, and Texas harbor aging populations with cumulative UV exposure, generating sustained patient volumes for field-directed therapies.
- CMS Reimbursement Expansion:Medicare coverage for photodynamic therapy in outpatient settings reduces patient out-of-pocket burden and accelerates clinic adoption of light-based systems.
- Topical Agent Cycling:Primary care physicians initiate 5-fluorouracil or imiquimod regimens, creating downstream referrals to dermatology for refractory lesions.
Market Restraints
- Device Capital Intensity:Photodynamic therapy light systems require $15,000-$40,000 upfront investment, favoring consolidated dermatology groups over independent practices.
- Imiquimod Supply Concentration:Single-source API manufacturing creates vulnerability to production disruptions and price volatility.
- Lesion Recurrence Rates:Cryotherapy achieves incomplete clearance in field cancerization, necessitating repeat procedures that strain patient compliance.
Strategic Opportunities
- Telehealth Integration:Post-pandemic Medicare flexibilities allow asynchronous lesion photography review, expanding rural patient access to specialist-directed home-based topical regimens.
- Combination Protocol Development:Sequenced aminolevulinic acid photodynamic therapy with topical immunomodulators addresses heterogeneous lesion burden within single treatment plans.
- Maintenance Regimen Expansion:Dermocosmetic channels cross-sell retinoid-based prevention products to treated patients, capturing lifetime value beyond acute intervention.
Industry Challenges
- Scope-of-Practice Fragmentation:State-level regulations governing nurse practitioner independence in field-directed therapy initiation create uneven channel access and prescribing authority.
- OSHA Compliance Burden:Clinic-based photodynamic therapy requires staff eye protection protocols and light source safety documentation, adding operational overhead.
- Prior Authorization Complexity:Commercial insurers impose step-therapy requirements that delay photodynamic therapy access, frustrating patients and providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Actinic Keratosis Treatment Market |
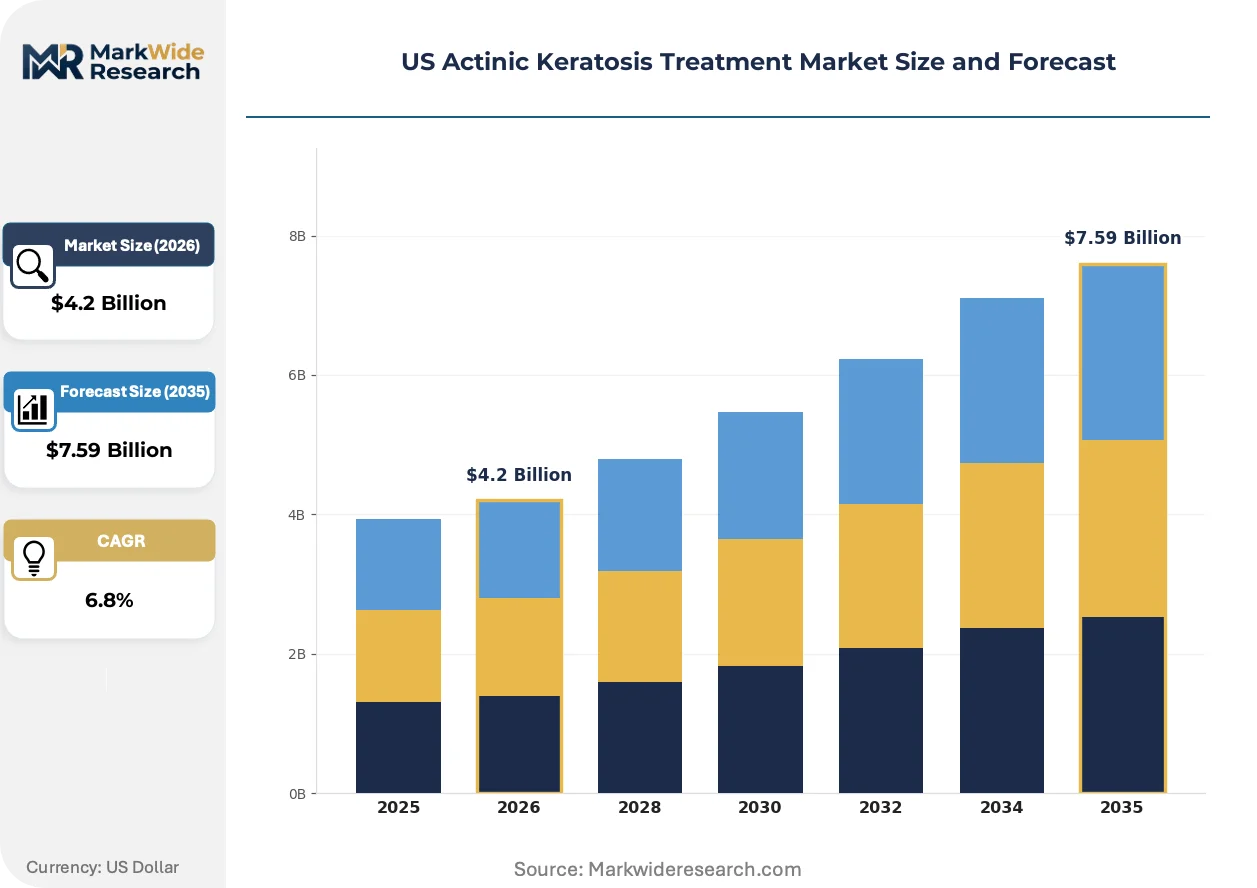
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.59 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Cryotherapy, Photodynamic Therapy, Surgical Procedures Delivery Mode: In-office Treatment, Home-based Treatment, Combination Therapy, Surgical Intervention End User: Dermatology Clinics, Hospitals, Home Care Settings, Research Institutions Treatment Stage: Initial Stage, Moderate Stage, Advanced Stage, Maintenance Stage |
| Companies Covered | Bausch Health Companies Inc., LEO Pharma A/S, Almirall S.A., Biofrontera AG, Galderma, Sun Pharmaceutical Industries Ltd., Novartis AG, Hill Dermaceuticals Inc., 3M Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Actinic Keratosis Treatment Market Strategic Shifts & Innovations
Modular treatment sequencing is displacing single-modality protocols across US dermatology practices, enabling physicians to tailor interventions to lesion burden, patient tolerance, and cosmetic priorities. This flexibility is reshaping product positioning and channel strategy.
Daylight photodynamic therapy is consolidating the ambulatory treatment landscape by eliminating clinic-based light source requirements. Patients apply aminolevulinic acid and expose treated areas to natural sunlight, reducing facility dependency. Dermatology groups in California and Florida are piloting this protocol for diffuse scalp and facial lesions, compressing per-procedure costs while maintaining efficacy comparable to conventional blue-light activation.
FDA's evolving guidance on field-directed therapies is accelerating combination product development. The agency's clarified pathway for fixed-dose topical-immunomodulator pairings reduces regulatory uncertainty for developers. Manufacturers are responding with integrated kits bundling 5-fluorouracil with corticosteroid pre-treatment to mitigate inflammation, particularly targeting Medicare-aged populations with extensive actinic damage.
Patient-driven channel migration is fragmenting the traditional specialist-referral model. Direct-to-consumer teledermatology platforms in Texas and Arizona now offer asynchronous lesion assessment with e-prescribed topical agents, bypassing geographic access constraints. This shift pressures traditional dermatology practices to integrate digital triage or risk losing early-stage patient capture to virtual-first competitors.
US Actinic Keratosis Treatment Market Segmentation
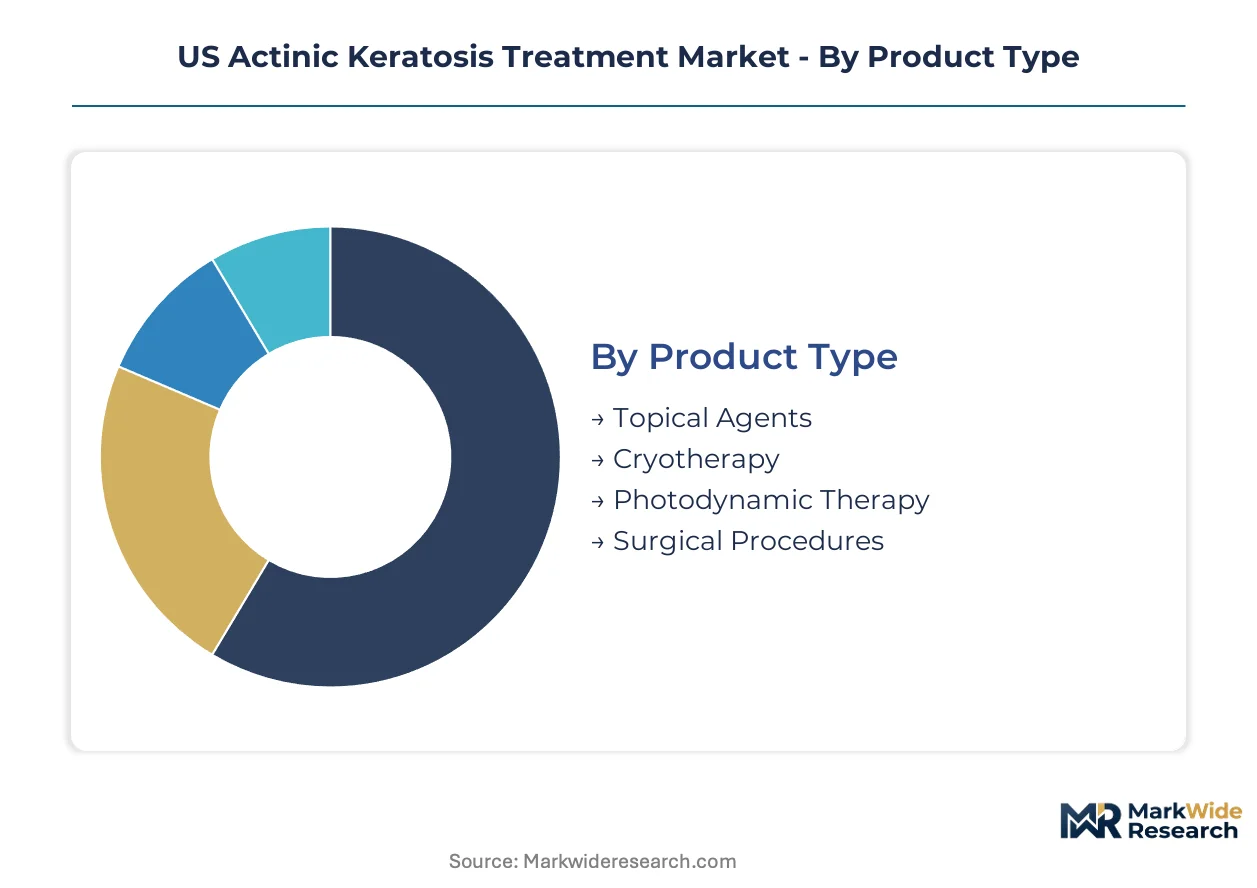
Segmentation in the US actinic keratosis treatment market reveals distinct economic and clinical logics across product categories, delivery modes, and care settings. Each axis shapes reimbursement pathways, prescribing authority, and manufacturer channel strategy.
Product Type:
Formulation chemistry and mechanism of action differentiate therapeutic options across the efficacy-convenience spectrum.
- Topical Agents:5-fluorouracil, imiquimod, and diclofenac formulations penetrate dysplastic keratinocytes to interrupt malignant progression. Medicare-aged patients in Florida and Arizona generate repeat prescription cycles due to field cancerization patterns, though inflammation-driven discontinuation limits completion rates.
- Photodynamic Therapy:Aminolevulinic acid and methyl aminolevulinate activate under blue or red light to destroy atypical cells. California dermatology groups are consolidating this modality for facial and scalp lesions, drawn by procedural revenue per encounter and superior cosmetic outcomes versus cryotherapy.
- Cryotherapy:Liquid nitrogen destroys visible lesions through thermal necrosis. Texas primary care networks favor this for isolated, hypertrophic lesions given minimal training requirements.
- Surgical Procedures:Excision and curettage address biopsy-proven or refractory lesions. Academic medical centers in the Northeast deploy this for suspected invasive transformation.
Topical agents lead on scale; photodynamic therapy leads on momentum.
Delivery Mode:
Site-of-care economics and patient autonomy preferences are redistributing volume across institutional and self-administered settings.
- In-office Treatment:Photodynamic therapy and cryotherapy require clinical infrastructure, staff training, and device capital. Consolidated dermatology groups in Sun Belt states capture this volume through light system investments and Medicare reimbursement optimization.
- Home-based Treatment:Topical regimens allow patient-managed application without facility dependency. Arizona and Texas teledermatology platforms are expanding asynchronous prescribing for rural patients beyond specialist geographic reach.
- Combination Therapy:Sequenced protocols pair initial photodynamic therapy with maintenance topical agents. Mayo Clinic and Cleveland Clinic networks pilot this for extensive field damage.
- Surgical Intervention:Excisional management demands sterile environments and histopathologic confirmation. Hospital outpatient departments handle complex cases requiring anesthesia support.
In-office delivery concentrates revenue; home-based delivery expands addressable population fastest.
End User:
Prescribing authority and reimbursement mechanics fragment demand across institutional categories.
- Dermatology Clinics:Specialist-directed care dominates photodynamic therapy and combination protocol adoption. Large group practices in California and Florida leverage scale to amortize device costs and negotiate payer contracts.
- Hospitals:Academic and community hospitals manage complex, multi-lesion cases requiring coordinated care. Surgical intervention and advanced-stage treatment concentrate here due to anesthesia and pathology infrastructure.
- Home Care Settings:Patient or caregiver administration of topical agents bypasses facility constraints. Medicare home health benefit coverage varies by state, creating access unevenness.
- Research Institutions:NIH-funded centers and pharmaceutical trial sites generate protocol development data. Johns Hopkins and Stanford dermatology departments lead field-directed therapy investigation.
Dermatology clinics command procedural margins; home care settings extend reach into access-constrained populations.
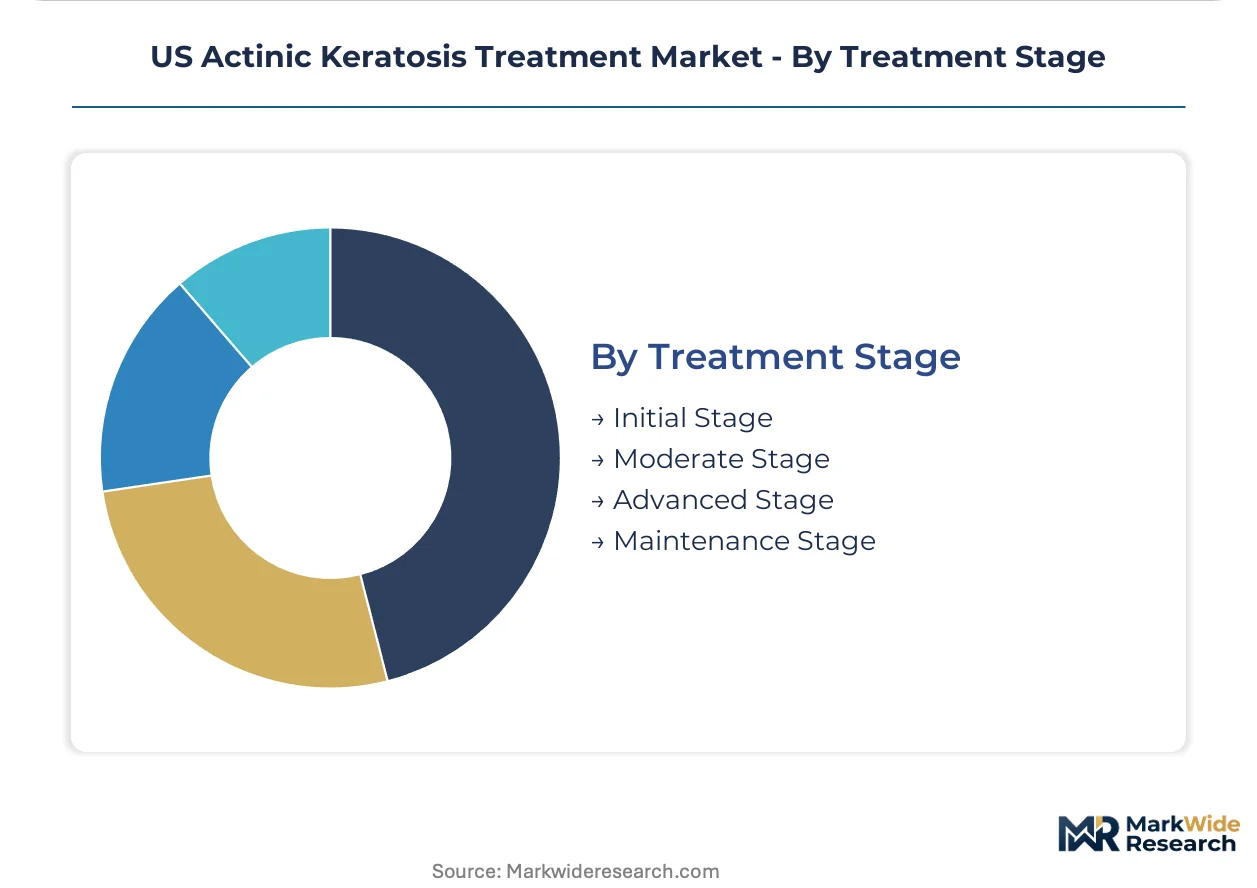
Treatment Stage:
Lesion burden and progression risk stratify intervention intensity and duration.
- Initial Stage:Limited, clinically apparent lesions respond to cryotherapy or short-course topical agents. Primary care physicians in Texas initiate most of this volume under collaborative care agreements.
- Moderate Stage:Multiple lesions or early field cancerization require extended topical regimens or single-session photodynamic therapy. Florida dermatology groups capture referrals at this threshold.
- Advanced Stage:Extensive actinic damage with high squamous cell carcinoma risk demands combination or surgical management. Arizona cancer centers manage this through multidisciplinary cutaneous oncology programs.
- Maintenance Stage:Post-clearance prevention using retinoids and photoprotection extends patient lifetime value. Galderma and LEO Pharma target this through dermocosmetic channel integration.
Moderate-stage treatment concentrates intervention value; maintenance-stage protocols extend commercial duration longest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US actinic keratosis treatment industry traces its commercial origins to mid-20th century dermatology practices in the Northeast, where liquid nitrogen cryotherapy first gained clinical traction before expanding nationwide through academic medical center networks.
Southwest
Arizona and New Mexico harbor the nation's highest per-capita actinic keratosis prevalence due to extreme UV exposure and aging retirement populations. FDA regulates field-directed therapy approvals that determine which topical agents reach these markets first. Phoenix and Tucson dermatology groups are consolidating photodynamic therapy capacity to capture Medicare reimbursement for light-based procedures.
Southeast
Florida's subtropical climate generates sustained patient volumes with cumulative sun damage across coastal retirement communities. State scope-of-practice laws here permit nurse practitioners to initiate topical regimens independently, expanding primary care channel access. Miami and Orlando dermatology networks are piloting daylight photodynamic therapy protocols for diffuse scalp lesions.
Texas
The state's vast rural geography creates access constraints that telehealth platforms are exploiting for asynchronous lesion assessment. CMS reimbursement policies for home-based topical administration vary by Medicare Advantage plan, creating patchwork coverage. Houston and Dallas medical centers anchor combination therapy research for extensive field cancerization cases.
California
Coastal populations with recreational sun exposure patterns drive demand for cosmetic-sparing treatment options. OSHA compliance requirements for clinic-based light systems favor larger dermatology groups over independent operators in Los Angeles and San Francisco markets. Northern California academic centers lead protocol development for sequenced aminolevulinic acid therapies.
Northeast
Older industrial cities with legacy manufacturing populations show delayed presentation patterns due to lower baseline UV awareness. Medicare fee-for-service reimbursement rates here lag Sun Belt states, compressing margins for in-office procedures. Boston and New York dermatology departments concentrate surgical intervention capacity for suspected invasive transformation cases.
US Actinic Keratosis Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across the topical-generic divide, with branded field-directed therapies commanding reimbursement advantages over older chemotherapeutic agents. The market structure reflects moderate consolidation among photodynamic therapy device and photosensitizer suppliers alongside fragmented topical manufacturing. Three archetypes dominate: vertically integrated dermatology pharmaceutical groups, European specialty pharma exporters, and generic topical compounders. Competitive moves center on backward integration into photosensitizer supply and strategic partnerships with teledermatology platforms.
Within the branded specialty tier, Bausch Health Companies Inc. and LEO Pharma A/S occupy positions anchored by historical imiquimod and combination therapy development. Galderma represents the dermocosmetic integration archetype, leveraging aesthetic channel relationships to cross-sell maintenance regimens. These three entities exemplify distinct strategic postures—supply chain control, R&D intensity, and channel diversification—without any single approach dominating market evolution.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| LEO Pharma A/S |
| Almirall S.A. |
| Biofrontera AG |
| Galderma |
| Sun Pharmaceutical Industries Ltd. |
| Novartis AG |
| Hill Dermaceuticals Inc. |
| 3M Co |
| Others |
Cost & Logistics Intelligence
OSHA workplace safety mandates for photodynamic therapy light sources gate qualified supply to larger dermatology groups with compliance infrastructure, simultaneously segmenting premium-tier procedural pricing from commodity cryotherapy rates. This environmental-health regulatory filter concentrates device procurement authority among consolidated practices while fragmenting topical agent distribution across broader channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the US actinic keratosis treatment landscape. FDA-approved branded field-directed therapies command premium positioning against generic 5-fluorouracil, with price differentiation anchored in clinical outcome data and Medicare reimbursement tier. Cost compression in the cryotherapy segment is intensifying because primary care networks favor low-capital thermal destruction over device-dependent modalities. Rural Medicare beneficiaries exhibit highest price sensitivity, while commercially insured patients in California and Florida cosmetic dermatology practices show lowest elasticity.
Supply Chain Analysis
Direct-to-dermatology clinic channels handle photodynamic therapy device and photosensitizer demand, while wholesale pharmaceutical distribution runs through retail pharmacy networks for topical agents. Active pharmaceutical ingredient production for imiquimod concentrates in India and China, with final formulation in US and European facilities. Supply chain vulnerability rests on single-source methyl aminolevulinate manufacturing, creating exposure to regulatory inspection delays and import restriction cascades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US actinic Keratosis Treatment Market represents a late-cycle quality story as patient demand shifts toward cosmetic-sparing photodynamic protocols that command superior reimbursement rates and repeat encounter economics.
For Market Incumbents: Extend field-directed therapy portfolios through backward integration into photosensitizer supply to mitigate API concentration risk. Secure teledermatology platform partnerships to defend against virtual-first competitors capturing early-stage patient triage in Texas and Arizona rural markets. For New Entrants and Emerging Players: Rural Medicare Advantage populations in Sun Belt states present an underserved buyer archetype with limited specialist geographic access. Target asynchronous prescribing infrastructure and home-based topical kit logistics to penetrate this white space, leveraging Medicare telehealth flexibilities as primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among generic topical compounders facing margin compression from 5-fluorouracil commoditization. Long-term viability favors photodynamic therapy device manufacturers with installed base expansion potential; monitor FDA combination product guidance acceleration as inflection signal for M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Photodynamic Therapy Device Certification | OSHA-compliant light system deployment unlocks Medicare reimbursement in consolidated dermatology groups. |
| Photosensitizer Supply Agreement | Captive aminolevulinic acid sourcing insulates against FDA import alert disruptions and price volatility. |
| Teledermatology Platform Partnership | Asynchronous lesion triage extends patient capture beyond traditional referral geography in access-constrained markets. |
| Combination Protocol Clinical Trial | Sequenced topical-photodynamic data supports FDA field-directed therapy label expansion and premium positioning. |
| Dermocosmetic Channel Integration | Post-treatment retinoid maintenance regimens capture lifetime patient value through aesthetic practice relationships. |
Research Approach
Bottom-up dermatology clinic and pharmacy dispensing modeling reconciled against top-down pharmaceutical manufacturer shipment tracking forms the analytical core of this study. Primary interviews with dermatology practice administrators, Medicare reimbursement specialists, formulary directors at national payers, and pharmaceutical supply chain managers combined with secondary validation from FDA 510(k) filings, CMS Medicare claims data, state scope-of-practice regulatory databases, and dermatology society clinical guidelines.
Historical procedure volume and prescription dispensing trendlines established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include treatment modality, site-of-care delivery setting, lesion burden severity, and prescriber specialty type, with CAGRs derived from regression analysis against demographic and reimbursement input variables. Forecast inputs incorporated Medicare Advantage penetration rates and photodynamic therapy device installation trajectories in Sun Belt metropolitan markets.
Underlying measurement precision varies by segment; pharmaceutical dispensing data carries tighter precision than procedural volume estimates. Forecasts reflect assumptions regarding regulatory pathway stability and reimbursement rate continuity, with periodic stress-testing of base assumptions recommended given potential Medicare telehealth policy reversals and FDA combination product guidance revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Immunology Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market