
 Herpes Zoster (Shingles) Market | 2026-2036
Herpes Zoster (Shingles) Market Size, Share, and Industry Trends Forecast 2026-2036
Herpes Zoster (Shingles) Market Foresight
Modular vaccine packaging is pivoting how healthcare systems procure shingles immunization products, shifting from single-dose vials toward multi-dose configurations that reduce cold-chain costs. GlaxoSmithKline leverages its recombinant platform to dominate the high-efficacy segment, while Pfizer Inc. competes through established distribution networks in institutional channels. Merck & Co. anchors its position via long-standing relationships with public health immunization programs.
Herpes zoster, the reactivated form of varicella-zoster virus causing painful dermal eruptions along sensory nerve distributions, requires recombinant glycoprotein E formulations with AS01B adjuvant systems to elicit strong cell-mediated immunity in older adults. The recombinant vaccine category leads absolute revenue contribution due to superior efficacy profiles in patients over fifty, while the elderly age group segment commands the deepest margin pools as payers prioritize proven prevention over downstream antiviral treatment costs. Pain management therapies represent a mature, slower-growing adjunction for post-herpetic neuralgia cases.
The FDA maintains stringent lot-release protocols for live attenuated and recombinant shingles vaccines, while the EMA's Good Manufacturing Practice inspections shape European supply qualification. WHO prequalification standards govern access for developing-country procurement through Gavi and UNICEF channels. Stakeholders must monitor how CMS reimbursement rate adjustments and ACIP recommendation expansions reshape site-of-care economics for adult vaccination.
Market Dynamics
Recombinant glycoprotein E platforms with AS01B adjuvant systems are compressing development timelines and reshaping how healthcare systems prioritize prevention over reactive antiviral therapy, fundamentally altering site-of-care economics for adult immunization programs.
Growth Catalysts
- ACIP Recommendation Expansion:The Advisory Committee on Immunization Practices broadened age-based recommendations for recombinant shingles vaccines, triggering Medicare Part D coverage expansion across outpatient pharmacy and physician office settings.
- Geriatric Care Infrastructure:Long-term care facilities and Medicare Advantage plans are embedding vaccination protocols into annual wellness visits, creating systematic touchpoints for adults over fifty.
- Recombinant Platform Maturation:Cell-culture manufacturing processes have achieved yield improvements that reduce per-dose production costs while maintaining glycoprotein E antigen fidelity.
Market Restraints
- AS01B Adjuvant Supply Concentration:Saponin-derived QS-21 and MPL components rely on limited qualified suppliers, creating input vulnerability for manufacturers scaling recombinant output.
- Cold-Chain Infrastructure Gaps:Rural and frontier counties in the United States lack consistent ultra-cold storage capacity, restricting vaccine access outside metropolitan distribution hubs.
- Two-Dose Compliance Drop-Off:The required second dose administration window sees substantial patient attrition, limiting real-world effectiveness and payer return-on-prevention calculations.
Strategic Opportunities
- Pharmacy-Based Immunization Networks:CVS Health and Walgreens are expanding clinic capacity within retail footprints, capturing patients during prescription pickup encounters without appointment barriers.
- Combination Vaccine Development:Adjuvant platforms compatible with respiratory and pneumococcal antigens enable single-visit administration, addressing polypharmacy concerns among elderly cohorts.
- Employer-Sponsored Prevention Programs:Self-insured corporations are adding shingles vaccines to on-site occupational health offerings, targeting pre-Medicare employees aged fifty to sixty-four.
Industry Challenges
- Immunogenicity Assay Standardization:Cell-mediated immunity measurement lacks harmonized correlates of protection across clinical trial sites, complicating head-to-head efficacy comparisons and regulatory submissions.
- Post-Herpetic Neuralgia Trial Endpoint Variability:Pain scale heterogeneity and duration definitions create inconsistent labeling claims, forcing sponsors to run separate studies for regulatory authorities.
- Workforce Shortage in Vaccine Administration:Pharmacist and nurse staffing constraints in community settings limit throughput during peak fall immunization seasons, creating appointment backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herpes Zoster (Shingles) Market |
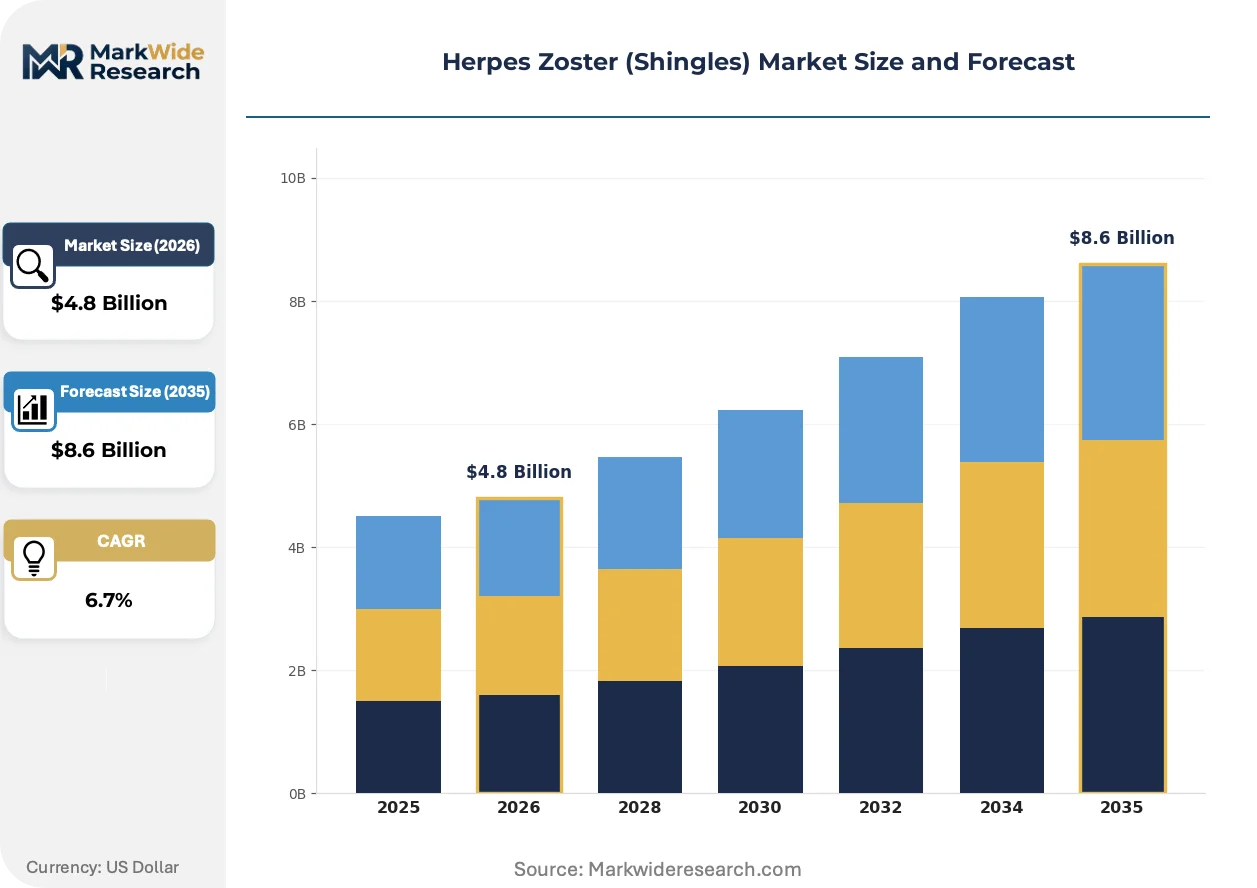
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated Vaccine, Recombinant Vaccine, Antiviral Drugs, Pain Management Therapies End User: Hospitals, Clinics, Homecare Settings, Pharmacies Delivery Mode: Intramuscular, Subcutaneous, Oral, Intravenous Age Group: Children, Adults, Elderly, Immunocompromised Patients |
| Companies Covered | GlaxoSmithKline, Pfizer Inc., Merck & Co., Sanofi, Astellas Pharma Inc., Novartis AG, Moderna Inc., Curevo Inc., GSK plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herpes Zoster (Shingles) Market Shifts & Advancements
Messenger RNA manufacturing methods and point-of-care delivery models are converging to compress the distance between production and patient administration, reducing reliance on centralized cold-chain networks.
Microarray patch technology is decentralizing shingles vaccine administration by eliminating needle requirements and enabling non-refrigerated storage. Retail pharmacy chains in Australia and community health workers in sub-Saharan pilot programs are evaluating thermostable dissolvable arrays for elderly populations with needle phobia or mobility limitations. This platform is decentralizing distribution economics by removing specialist administration costs and enabling home-based or workplace delivery without clinician oversight.
The FDA's accelerated approval pathway for adjuvanted recombinant vaccines has compressed Phase III to licensure timelines, incentivizing sponsors to invest in glycoprotein E platform extensions. European manufacturers are aligning with EMA's Good Manufacturing Practice inspection protocols to secure mutual recognition agreements, reducing duplicate facility audits. Pediatric and immunocompromised label expansions represent the segments most affected, with sponsors submitting supplemental biologics license applications to capture these restricted populations.
Site-of-care migration from physician offices to retail pharmacies is restructuring how shingles vaccines are purchased and reimbursed. Medicare Part D plans are steering beneficiaries toward preferred pharmacy networks through reduced copay tiers, displacing traditional medical benefit billing. This behavioral shift is most visible in United States metropolitan markets where CVS MinuteClinic and Walgreens Healthcare locations have achieved density sufficient for same-day appointment availability.
Herpes Zoster (Shingles) Market Segmentation
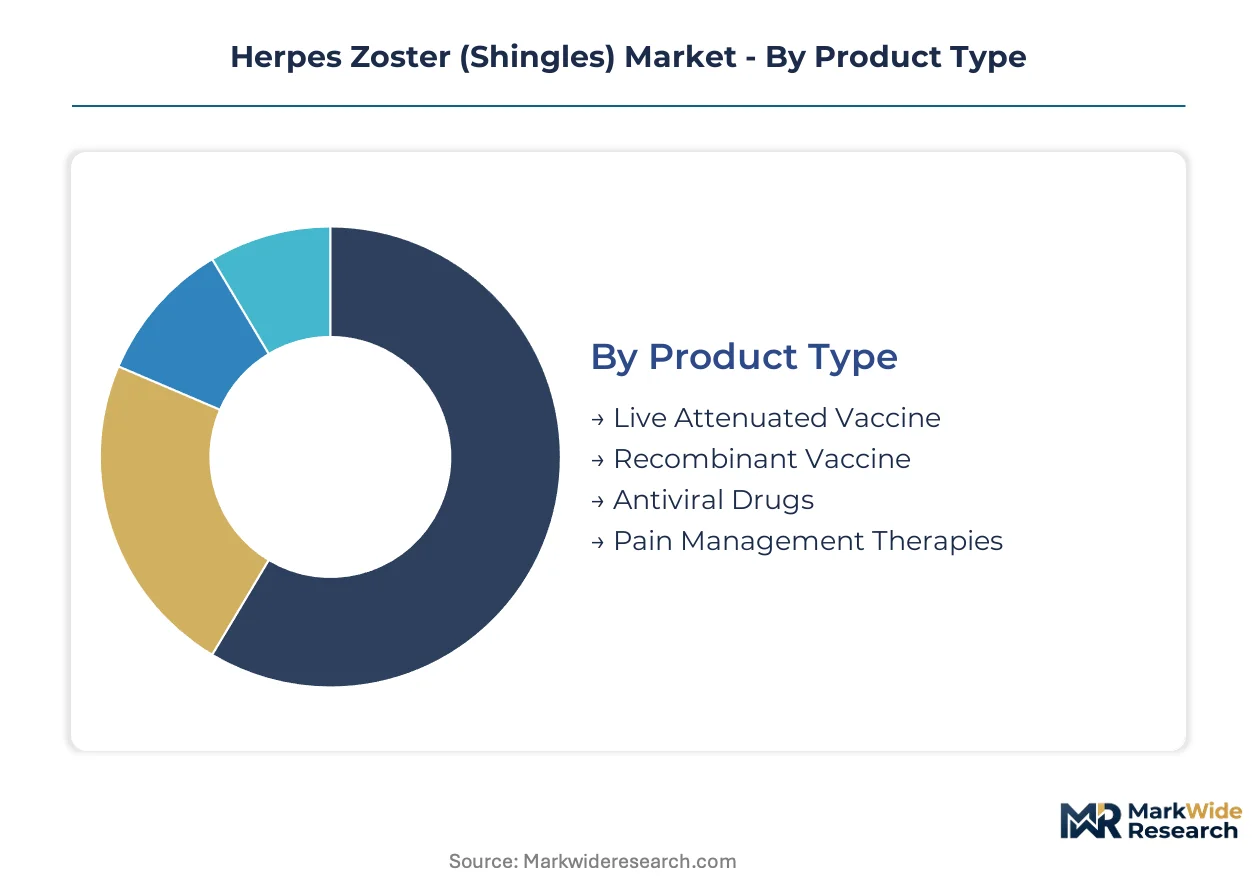
Shingles market segmentation reveals how supply-side specialization and patient access pathways diverge across immunization technologies and care settings. Manufacturers configure production assets around adjuvant platform economics while distribution networks optimize for site-of-care reimbursement mechanics.
Product Type:
Supply concentration in recombinant glycoprotein E manufacturing has reconfigured competitive positioning around AS01B adjuvant access and cell-culture yield optimization.
- Live Attenuated Vaccine:Single-dose administration using Oka/Merck strain varicella-zoster virus delivers moderate efficacy in adults over sixty. Demand concentrates in institutional channels with established cold-chain infrastructure, constrained by inferior cell-mediated immunity induction relative to recombinant alternatives.
- Recombinant Vaccine:Glycoprotein E antigen combined with AS01B adjuvant system elicits robust T-cell responses in immunosenescent populations. Medicare Part D reimbursement drives uptake in outpatient pharmacy settings, with two-dose compliance patterns shaping real-world effectiveness metrics.
- Antiviral Drugs:Acyclovir-family nucleoside analogs for breakthrough infection management.
- Pain Management Therapies:Gabapentinoids and topical lidocaine for post-herpetic neuralgia symptom control.
Recombinant vaccine absorbs the bulk of installed capacity; antiviral drugs are expanding most quickly among breakthrough case protocols.
End User:
Site-of-care migration is redistributing procurement authority from medical benefit billing toward pharmacy benefit managers with vaccine-specific formularies.
- Pharmacies:Retail clinic networks capture Medicare beneficiaries through reduced copay tiers and same-day accessibility. CVS MinuteClinic and Walgreens Healthcare locations in metropolitan United States markets drive volume through prescription pickup encounter integration.
- Hospitals:Outpatient infusion centers and emergency departments manage complicated presentations with disseminated zoster or ophthalmic involvement. Academic medical centers concentrate immunocompromised patient protocols requiring specialist oversight.
- Clinics:Physician office administration faces reimbursement compression under Medicare Part D restructuring.
- Homecare Settings:Mobile nursing services for homebound elderly with mobility limitations.
Pharmacies absorb the bulk of patient throughput; homecare settings are climbing the fastest as aging-in-place policies expand.
Delivery Mode:
Route selection determines cold-chain requirements, administration workforce training, and patient compliance architecture across immunization programs.
- Intramuscular:Deltoid injection for recombinant vaccine delivery requires trained administrator presence. United States retail pharmacy networks optimize staffing models around peak fall immunization season throughput constraints.
- Subcutaneous:Live attenuated vaccine administration permits broader healthcare worker scope-of-practice delegation.
- Oral:Antiviral tablet formulations for outpatient breakthrough infection management.
- Intravenous:Acyclovir infusion for hospitalized disseminated zoster or central nervous system complications.
Intramuscular delivery commands the deepest infrastructure investment; oral administration is gaining share fastest among post-exposure prophylaxis protocols.
Age Group:
Immunosenescence patterns and payer coverage thresholds segment addressable populations across distinct risk-stratification frameworks.
- Elderly:Adults over fifty generate the preponderance of zoster incidence and post-herpetic neuralgia burden. Medicare coverage expansion and Medicare Advantage wellness visit integration drive systematic vaccination touchpoints in United States geriatric care infrastructure.
- Immunocompromised Patients:Transplant recipients, oncology patients, and autoimmune disease cohorts on immunosuppressive therapy face elevated reactivation risk. Hospital-based specialist protocols govern access given live vaccine contraindications and recombinant timing requirements.
- Adults:Pre-Medicare employer-sponsored prevention programs target fifty-to-sixty-four cohorts.
- Children:Rare pediatric zoster cases in immunocompromised or varicella-unvaccinated populations.
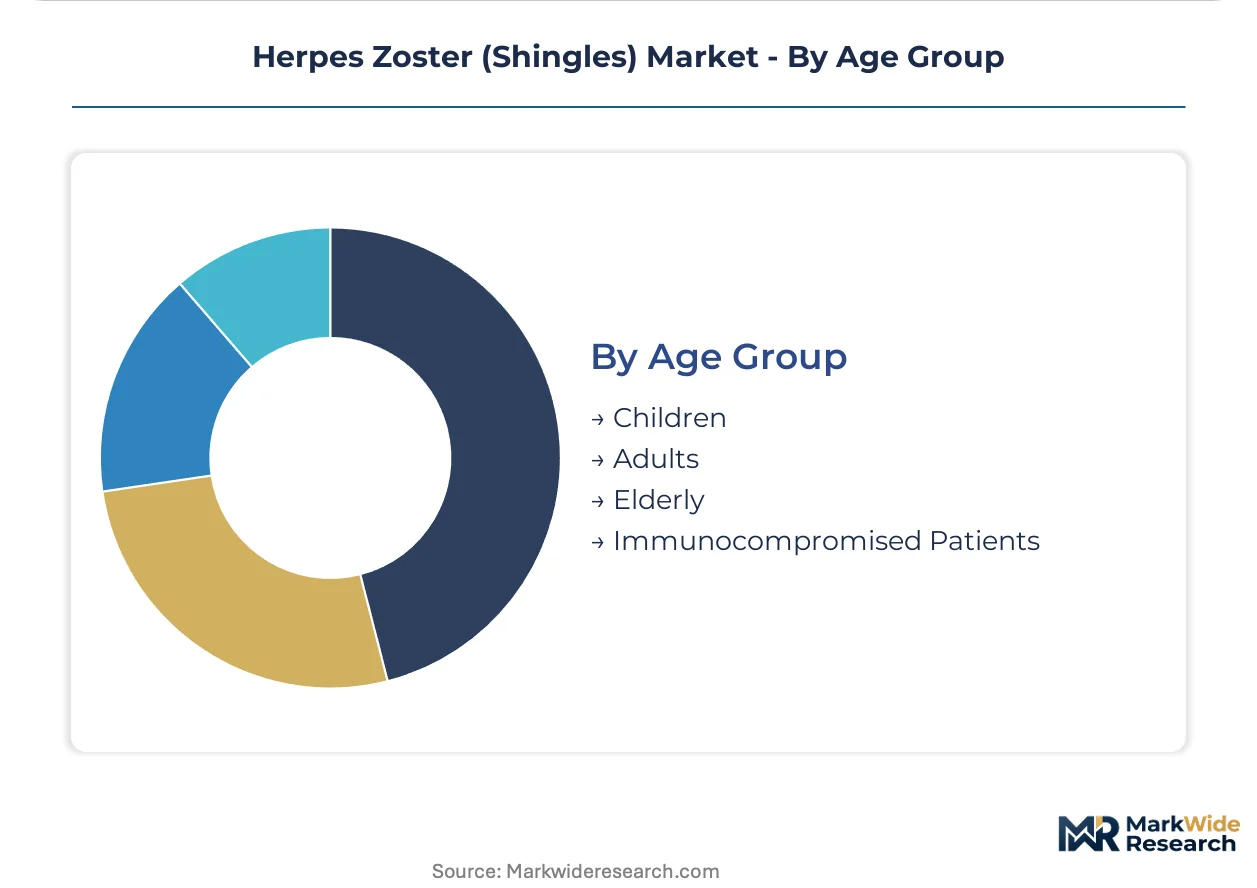
Elderly populations absorb the bulk of dose volume; immunocompromised patients are expanding most quickly as transplant volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of recombinant shingles vaccines concentrates in Belgium and the United States, while consumption patterns track geriatric population density and reimbursement infrastructure across developed economies. Distribution networks optimize for Medicare Part D pharmacy channels in North America and statutory health insurance frameworks in Europe.
United States
Medicare Part D coverage expansion drives recombinant vaccine uptake through CVS Health and Walgreens retail networks. The FDA's accelerated approval pathway for adjuvanted vaccines compresses licensure timelines for manufacturers. Boston's biotech corridor hosts cell-culture production facilities supplying domestic demand.
Germany
Statutory health insurance funds embed shingles vaccination into preventive care protocols for adults over sixty. EMA Good Manufacturing Practice inspections shape facility qualification standards across the European supply base. The Rhine-Main region concentrates fill-finish operations serving Central European distribution.
Japan
PMDA review pathways for geriatric vaccines prioritize immunosenescence-targeted efficacy data in regulatory submissions. METI industrial policy supports domestic recombinant manufacturing capacity expansion. The Kansai region's pharmaceutical cluster houses adjuvant formulation expertise for Asia-Pacific supply.
United Kingdom
NHS England's national immunization program funds shingles vaccination through primary care networks. MHRA post-Brexit regulatory autonomy enables streamlined approval for EMA-authorized products. London's research hospitals conduct real-world effectiveness studies informing ACIP-equivalent guidance.
Australia
National Immunisation Program schedule inclusion drives recombinant vaccine procurement through federal vaccine supply contracts. TGA batch release testing protocols align with WHO prequalification standards for regional export eligibility. Melbourne's biomedical precinct hosts clinical trial infrastructure for Southern Hemisphere enrollment.
Herpes Zoster (Shingles) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the shingles vaccine value chain. The market structure consolidates around recombinant platform holders with captive adjuvant supply, while antiviral and pain management segments fragment among generic manufacturers. Three archetypes dominate: Big Pharma vaccine divisions with cell-culture infrastructure, biotech platform licensors seeking label expansions, and regional distributors capturing pharmacy channel economics. Competitive moves center on Medicare Part D formulary positioning and two-dose compliance program deployment.
Within the Big Pharma tier, GlaxoSmithKline and Pfizer Inc. occupy positions shaped by recombinant platform maturity and retail distribution depth respectively. Merck & Co. anchors the live attenuated vaccine segment through legacy institutional relationships. These three exemplify how manufacturing scale, site-of-care access, and public health program integration create distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Pfizer Inc. |
| Merck & Co. |
| Sanofi |
| Astellas Pharma Inc. |
| Novartis AG |
| Moderna Inc. |
| Curevo Inc. |
| GSK plc. |
| Others |
Supply & Pricing Matrix
QS-21 saponin pricing benchmarks cascade through recombinant shingles vaccine manufacturing into three-tier pricing structures across premium, standard, and economy levels, with AS01B adjuvant component scarcity compressing margins for non-integrated manufacturers while Medicare Part D reimbursement floors establish baseline access tiers.
Pricing Analysis
Margin tightening in the recombinant vaccine tier reflects AS01B adjuvant supply concentration among qualified saponin extractors. Three-tier pricing structure across premium, standard, and economy levels separates GSK's Shingrix premium positioning from contract-manufactured alternatives and emerging biosimilar entrants. Price differentiation hinges on glycoprotein E antigen fidelity certification and cold-chain logistics bundling. Cost-down pressure on live attenuated alternatives accelerates because Medicare Advantage plans steer beneficiaries toward higher-efficacy recombinant options with reduced copay differentials. Pharmacy benefit managers exhibit highest price sensitivity, while hospital outpatient departments absorb premium markups for immunocompromised patient protocols.
Supply Chain Analysis
Domestic-content mandates in Japan's METI industrial policy and the United States' Biomedical Advanced Research and Development Authority procurement preferences are reshaping sourcing toward regional cell-culture facilities. Supply concentrates in Belgium, the United States, and Japan for recombinant glycoprotein E production, with fill-finish operations distributed across the Rhine-Main region and Boston's biotech corridor. Raw material dependencies center on QS-21 saponin extracts from Chilean soapbark, synthetic MPL from Merck's Darmstadt facilities, and specialized cell-culture media. Single-source vulnerability in qualified AS01B component suppliers creates input concentration risk. Distribution runs through pharmaceutical wholesale networks to retail pharmacy chains, with direct-to-hospital channels serving academic medical centers and transplant programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shingles vaccine market sits at a technology-transition inflection as recombinant glycoprotein E platforms displace live attenuated alternatives, with microarray patch delivery systems poised to further decentralize administration economics.
For Market Incumbents: Deploy captive adjuvant supply agreements to lock in QS-21 and MPL component access before competitor offtake commitments solidify. Secure preferred pharmacy network status with CVS Health and Walgreens through dedicated clinic staffing during peak immunization seasons. Counter mRNA platform entrants by accelerating combination vaccine development with pneumococcal and respiratory antigens. For New Entrants and Emerging Players: Retail pharmacy clinic operators represent the most accessible channel partners for bypassing physician office reimbursement compression. Target employer-sponsored prevention programs for pre-Medicare employees aged fifty to sixty-four, a white-space segment with limited incumbent penetration. Pursue thermostable microarray patch technology licensing to eliminate cold-chain infrastructure requirements and capture homebound elderly populations. For Investors and Strategic Acquirers: Distressed-cycle entries favor adjuvant platform specialists with EMA-qualified manufacturing in Central Europe during AS01B supply crunches. Five-to-ten year viability hinges on combination vaccine pipeline depth and pediatric label expansion optionality. Monitor ACIP recommendation age-threshold reductions as the critical inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AS01B Adjuvant Supply Security | Captive QS-21 sourcing from Chilean soapbark plantations insulates production from competitor offtake competition. |
| Microarray Patch Development | Thermostable dissolvable arrays eliminate ultra-cold chain requirements for rural and frontier county access. |
| Combination Vaccine Formulation | Single-visit administration with pneumococcal antigens addresses polypharmacy compliance in elderly cohorts. |
| Pharmacy Network Exclusivity | Preferred status with Medicare Part D plans captures prescription pickup encounter integration volumes. |
| Pediatric Label Expansion | Supplemental biologics license applications for immunocompromised children open restricted population access. |
Research Methodology
Multi-period observation of Medicare Part D reimbursement rates, ACIP recommendation timelines, and recombinant vaccine lot-release volumes anchored the trend analysis, supplemented by interviews with vaccine development executives, regulatory affairs leads at FDA and EMA, formulary directors at national pharmacy chains, and hospital procurement managers specializing in immunocompromised patient protocols. Secondary validation drew from FDA biologics license application filings, EMA marketing authorization submissions, ClinicalTrials.gov protocol registries, and CMS Medicare utilization databases. Bottom-up demand modeling across patient age cohorts and site-of-care channels triangulated against top-down manufacturer capacity disclosures.
Segment-weighting approaches applied differential growth assumptions across recombinant versus live attenuated platforms, pharmacy versus hospital administration settings, and elderly versus immunocompromised patient populations throughout the forecast period. CAGRs derived from patient epidemiology projections, payer coverage expansion trajectories, and manufacturing yield improvement curves. Forecast inputs incorporated ACIP recommendation elasticity estimates and two-dose compliance attrition patterns from real-world effectiveness studies.
Caveats apply where ACIP age-threshold revisions, AS01B supply disruptions, or microarray patch regulatory pathways could materially shift the outlook. Forecasts reflect assumptions about Medicare Part D formulary stability and recombinant manufacturing scale-up success. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Neuromuscular Disorders Treatment Market