
 Cluster Headache Syndrome Market | 2026-2036
Cluster Headache Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Cluster Headache Syndrome Market Analysis
Specialty pharmaceutical manufacturing in North America and Europe is consolidating as CMOs scale capacity for CGRP-targeted formulations. Eli Lilly and Company leverages its migraine-to-cluster pipeline infrastructure to sustain development velocity across neurology. Novartis AG anchors European supply through its Basel-area manufacturing network. Teva Pharmaceutical Industries Ltd. competes on generic injectable economics while extending its specialty portfolio into orphan indications.
Cluster headache syndrome comprises severe, unilateral trigeminal-autonomic cephalalgias with attack durations of 15-180 minutes, diagnosed per International Classification of Headache Disorders criteria. The condition demands rapid-abortive intervention and preventive suppression due to its excruciating intensity and circadian rhythmicity. Abortive treatments, particularly subcutaneous sumatriptan and high-flow oxygen, dominate current clinical utilization and command premium pricing. Novel therapies, including CGRP receptor antagonists and non-invasive vagus nerve stimulation, represent the fastest-expanding segment as regulatory pathways for rare disease indications compress development timelines.
FDA breakthrough therapy and orphan drug designations, alongside EMA PRIME eligibility and Japan PMDA sakigake status, shape competitive positioning by accelerating review and enabling early market access. WHO inclusion of headache disorders in the Global Action Plan on Epilepsy and Other Neurological Disorders elevates national reimbursement priority. Stakeholders must monitor evolving payer evidence requirements for device-based interventions as health technology assessment bodies tighten comparative effectiveness standards.
Market Dynamics
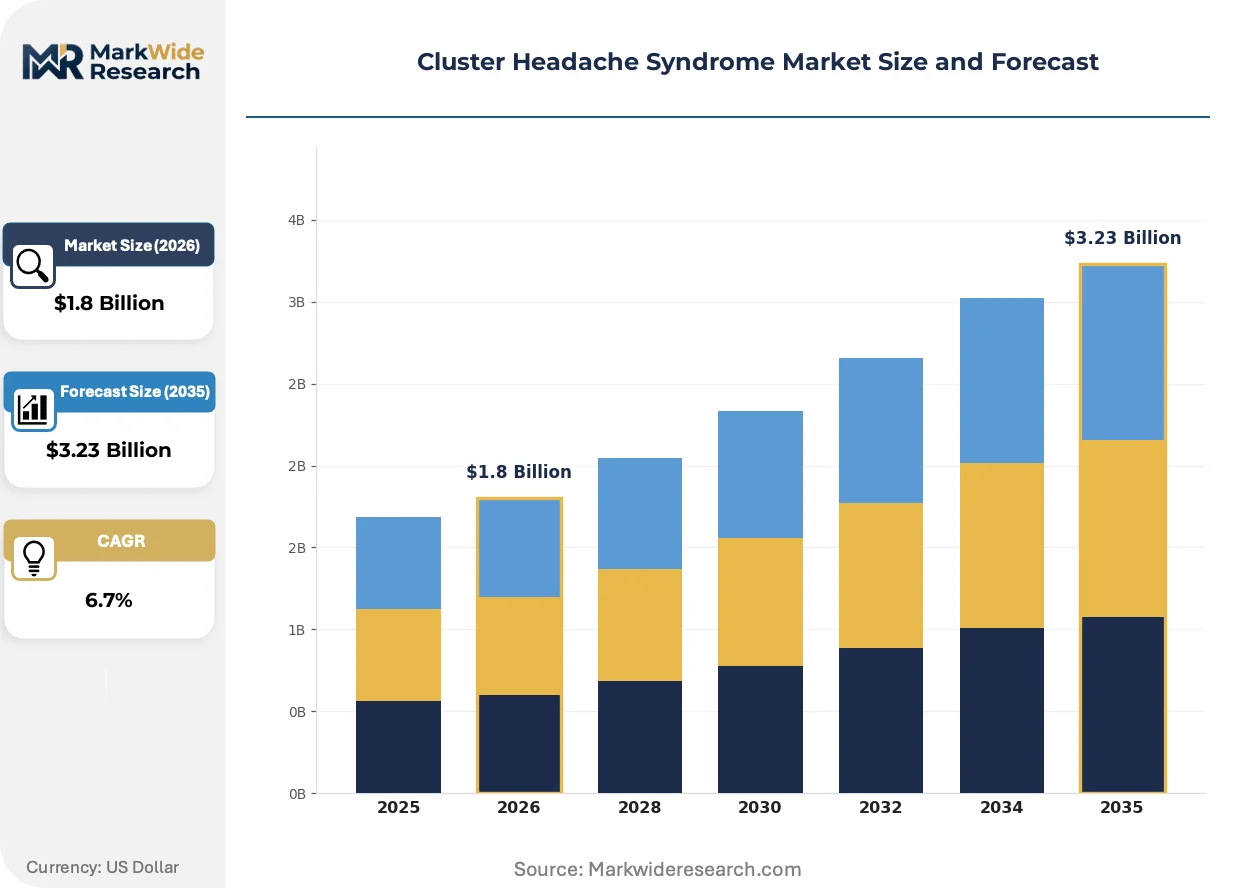
FDA breakthrough therapy designations and EMA PRIME eligibility are compressing clinical development timelines for CGRP-targeted therapies, while specialist headache center networks concentrate demand in urban medical clusters across three continents.
Growth Catalysts
- Orphan drug incentives:FDA and EMA pathways for rare neurological indications reduce regulatory burden and accelerate market entry for novel abortive formulations.
- High-flow oxygen protocols:Emergency medicine departments in the United States, Germany, and Japan are standardizing non-pharmacological first-line interventions.
- Neurology clinic specialization:Dedicated headache centers in metropolitan hospital systems are deepening referral networks and concentrating diagnosed patient volume.
Market Restraints
- Specialty manufacturing concentration:CGRP monoclonal antibody production capacity concentrates among a limited cohort of North American and European contract manufacturers.
- Reimbursement heterogeneity:Germany's G-BA and Japan's Chuikyo impose divergent health technology assessment criteria for device-based preventive therapies.
- Diagnostic underrecognition:Primary care physicians frequently misclassify cluster headache as migraine or sinus pathology, delaying specialist referral.
Strategic Opportunities
- Telemedicine triage platforms:Remote neurology consultation networks in Australia and Canada are expanding access to specialist diagnosis outside urban headache centers.
- Non-invasive vagus nerve stimulation:Home-use device protocols are creating preventive therapy categories distinct from acute injectable interventions.
- WHO Global Action Plan implementation:National neurological disorder strategies in India and Brazil are elevating headache syndrome reimbursement priority.
Industry Challenges
- Specialist neurologist scarcity:Headache medicine fellowship programs in the United States and United Kingdom produce insufficient board-certified practitioners to serve expanding diagnostic demand.
- Device-therapy integration complexity:Electronic health record systems in hospital networks lack standardized coding for combined pharmaceutical and neuromodulation treatment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cluster Headache Syndrome Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sumatriptan, Oxygen Therapy, Corticosteroids, Ergots End User: Hospitals, Neurology Clinics, Outpatient Centers, Telehealth Providers Treatment Type: Preventive, Abortive, Non-Pharmacological, Novel Therapies Distribution Channel: Pharmacies, Online Pharmacies, Hospital Pharmacies, Other Retailers |
| Companies Covered | Eli Lilly and Company, Novartis AG, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, AstraZeneca plc, Zosano Pharma, Lundbeck Seattle BioPharmaceutical, ElectroCore Medical LLC, Autonomic Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cluster Headache Syndrome Market Emerging Trajectories
CGRP pathway science is restructuring therapeutic development priorities across neurology, while regulatory innovation programs and shifting site-of-care preferences are redefining how interventions reach diagnosed patients.
Calcitonin gene-related peptide receptor antagonists are rewriting the preventive treatment paradigm for episodic and chronic cluster headache subtypes. Neurology clinics in the United States and Germany are adopting subcutaneous and intravenous formulations at accelerating velocity. This mechanism is compressing the historical dominance of triptan-based abortive protocols and enabling extended prophylaxis without steroid exposure.
EMA PRIME eligibility and FDA breakthrough therapy designation are streamrolling orphan neurological indication pathways. Accelerated assessment frameworks reduce phase-to-phase transition intervals and enable conditional reimbursement during confirmatory trials. European headache centers are responding by establishing early-access programs for patients with treatment-resistant circadian attack patterns.
Specialist referral networks are consolidating diagnostic and therapeutic decision-making away from general neurology practices. Academic medical centers in Japan, the United Kingdom, and the United States are absorbing regional patient volume through telemedicine triage and satellite clinic partnerships. This concentration is most visible in Germany's university hospital system, where integrated headache units now coordinate oxygen, pharmacological, and device-based protocols through single-point care pathways.
Cluster Headache Syndrome Market Segmentation
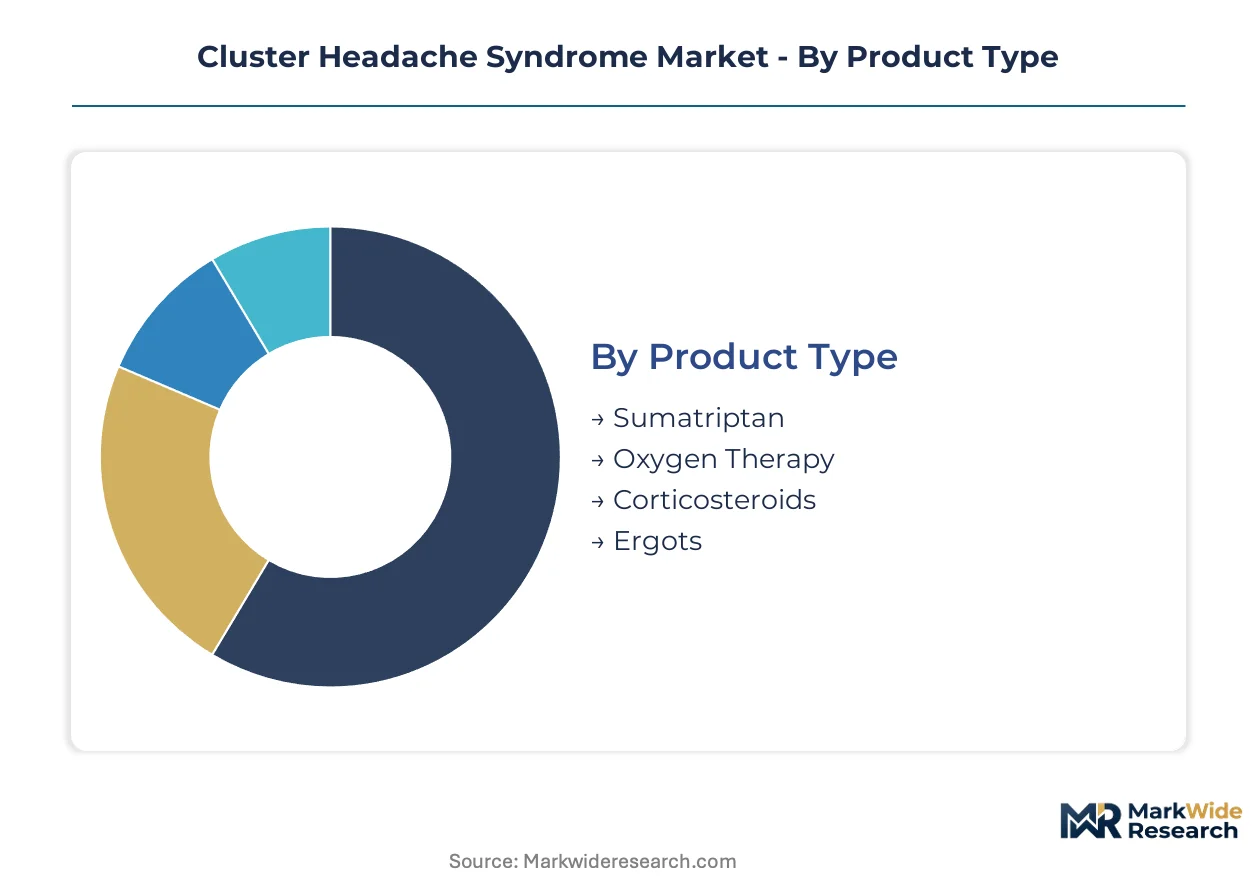
Segmentation in the cluster headache syndrome market reveals distinct procurement patterns across acute intervention versus chronic management pathways. Treatment setting and regulatory classification shape pricing power and reimbursement velocity for each product category.
Product Type:
Standardization dominates acute abortive formulations while preventive therapies demand higher customization for individual attack patterns.
- Sumatriptan:Subcutaneous and intranasal formulations deliver rapid serotonin receptor agonism with onset under 15 minutes. United States emergency departments and German university hospitals anchor demand through standardized acute protocols. FDA-approved auto-injector devices command premium positioning against generic alternatives.
- Oxygen Therapy:High-flow 100% oxygen via non-rebreather mask provides non-pharmacological abortive intervention without vascular contraindications. Specialist headache centers in Japan and metropolitan United States hospital systems are expanding dedicated oxygen infrastructure for first-line attack termination.
- Corticosteroids:Oral prednisone and suboccipital steroid injections serve transitional preventive bridging during medication initiation.
- Ergots:Dihydroergotamine formulations retain niche utilization in triptan-nonresponsive patients with cardiovascular comorbidities.
Most installed capacity flows through Sumatriptan. Expansion is steepest in Oxygen Therapy.
End User:
Site-of-care migration from inpatient to ambulatory settings is redistributing treatment economics across provider types.
- Hospitals:Emergency departments manage refractory status migrainosus and initial diagnostic workup for atypical presentations. Academic medical centers in Germany and the United States concentrate interventional capabilities including occipital nerve blocks and inpatient detoxification protocols.
- Neurology Clinics:Dedicated headache centers coordinate multimodal preventive regimens with longitudinal attack diary monitoring. Japan's specialist certification system restricts these services to board-certified practitioners, creating supply-constrained access tiers.
- Outpatient Centers:Ambulatory infusion suites deliver parenteral abortive therapy for patients lacking home injection capability.
- Telehealth Providers:Remote neurology platforms extend diagnostic access beyond urban headache center catchment areas.
Revenue concentration sits with Hospitals. Telehealth Providers are gaining share fastest.
Treatment Type:
Preventive versus abortive allocation decisions hinge on attack frequency thresholds and circadian pattern predictability.
- Preventive:Daily or scheduled interventions suppress attack frequency in chronic and high-frequency episodic subtypes. CGRP monoclonal antibodies and verapamil dominate prescribing in United States and European specialist practices.
- Abortive:Attack-triggered interventions demand rapid onset formulations for time-sensitive symptom control. Subcutaneous sumatriptan and high-flow oxygen constitute standard of care across all major markets.
- Non-Pharmacological:Oxygen, nerve blocks, and neuromodulation address patients with medication contraindications or inadequate pharmaceutical response.
- Novel Therapies:CGRP receptor antagonists and non-invasive vagus nerve stimulation represent mechanism-of-action expansion beyond historical pathways.
Abortive treatments retain the largest patient volume base. Novel Therapies show the steepest expansion trajectory.
Distribution Channel:
Channel selection correlates with urgency requirements and reimbursement preauthorization complexity.
- Pharmacies:Community retail networks dispense oral preventive medications with established prior authorization pathways. German pharmacy benefit structures and United States Medicare Part D formularies shape access tiering.
- Online Pharmacies:Mail-order and digital platforms serve maintenance preventive prescriptions with 90-day supply economics. Japan's Chuikyo reimbursement revisions are expanding remote dispensing eligibility for chronic neurological indications.
- Hospital Pharmacies:Inpatient and emergency department formularies control acute parenteral and inhaled product access.
- Other Retailers:Specialty durable medical equipment suppliers distribute oxygen concentrators and neuromodulation devices for home preventive protocols.
Pharmacies process the highest prescription volume. Online Pharmacies are climbing the fastest among channel types.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating CGRP-targeted manufacturing in jurisdictions with streamlined orphan drug pathways and established biologics infrastructure. Switzerland and the United States attract development-stage investment through accelerated FDA and Swissmedic review timelines, while Germany and Japan leverage specialist clinical networks to anchor commercialization.
United States
Academic medical centers in Boston and New York Metro drive specialist referral volume for circadian attack patterns. FDA breakthrough therapy designations compress phase-to-phase intervals for novel abortive formulations. The Cleveland Clinic and Mayo Clinic headache units coordinate multimodal oxygen, pharmacological, and neuromodulation protocols through single-point care pathways.
Germany
University hospital networks in Munich and Heidelberg standardize high-flow oxygen as first-line emergency intervention. G-BA health technology assessments shape reimbursement velocity for device-based preventive therapies. The Basel-area manufacturing corridor anchors European CGRP monoclonal antibody supply through Novartis AG's integrated production network.
Japan
PMDA sakigake status accelerates market entry for CGRP receptor antagonists in treatment-resistant subtypes. Specialist certification systems restrict dedicated headache center access to board-certified practitioners in Tokyo and Osaka. Metropolitan hospital systems are expanding dedicated oxygen infrastructure for acute attack termination.
Switzerland
Swissmedic accelerated assessment pathways attract development-stage biopharmaceutical investment for orphan neurological indications. The Basel biotech cluster concentrates CGRP-targeted formulation expertise alongside Novartis AG's headquarters operations. Zurich university hospitals coordinate early-access programs for patients with refractory chronic cluster patterns.
United Kingdom
NHS England specialized commissioning frameworks concentrate diagnostic resources in London and Manchester headache centers. MHRA innovation passports streamline regulatory review for novel neuromodulation devices. The National Institute for Health and Care Excellence is tightening comparative effectiveness standards for preventive therapy reimbursement.
Cluster Headache Syndrome Market Vendor Landscape
United States producers anchor one tier; Swiss and German specialists hold manufacturing and regulatory science advantages. The market structure consolidates around three strategic archetypes: integrated pharmaceutical conglomerates with migraine-to-cluster pipeline infrastructure, pure-play neurology specialists with orphan indication focus, and device manufacturers with home-use neuromodulation platforms. Competitive moves center on CMO capacity reservation for biologics manufacturing and specialist headache center partnership networks for patient access.
Among integrated pharmaceutical conglomerates, Eli Lilly and Company and Novartis AG exemplify the infrastructure-heavy archetype leveraging cross-indication neurology platforms. Teva Pharmaceutical Industries Ltd. occupies a position bridging generic injectable economics with specialty portfolio extension into orphan indications. These three anchors represent distinct competitive vectors: Lilly's pipeline velocity, Novartis's European supply chain integration, and Teva's cost-positioned access strategies.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Zosano Pharma |
| Lundbeck Seattle BioPharmaceutical |
| ElectroCore Medical LLC |
| Autonomic Technologies, Inc. |
| Others |
Supply Flow & Price Mechanics
Captive biologics manufacturing networks in Switzerland and the United States anchor supply positions for CGRP-targeted formulations while simultaneously defending premium pricing tiers against generic erosion. This integration choice concentrates production expertise near regulatory agencies and specialist headache centers, creating defensive moats through manufacturing complexity rather than patent exclusivity alone.
Pricing Analysis
Distributor margin structures for injectable abortive therapies compress as hospital pharmacy formularies consolidate procurement through single-source contracts. Three-tier pricing structure across premium auto-injector devices, standard vial formulations, and economy generic alternatives stratifies access by insurance tier and site-of-care. Price differentiation hinges on FDA breakthrough designation status and companion diagnostic bundling. Cost compression in the generic triptan segment intensifies because of pharmacy benefit manager formulary exclusions. Uninsured and high-deductible plan patients exhibit highest price sensitivity; institutional purchasers with GPO contracts demonstrate lowest.
Supply Chain Analysis
Cold-chain logistics costs for monoclonal antibody formulations concentrate distribution economics around metropolitan hospital clusters within the United States, Germany, and Switzerland. Active pharmaceutical ingredient production draws from Chinese and Indian contract manufacturers for small-molecule components, while biologic drug substance manufacturing rests on North American and European CMO capacity. Single-source vulnerability pervades the fill-finish segment where limited facilities handle sterile injectable formats. Distribution runs through specialty pharmacy networks for home-use preventive therapies and direct-to-hospital channels for acute inpatient formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cluster headache syndrome market represents a late-cycle quality story where diagnostic accuracy improvements and specialist center expansion are redirecting demand toward premium CGRP-targeted formulations with superior adherence profiles.
For Market Incumbents: Acquire early-stage CGRP receptor antagonist programs to backfill pipeline exposure as triptan franchises mature. Defend against device-manufacturer encroachment by embedding neuromodulation protocols within integrated headache center partnerships. Capacity addition in the Basel-area corridor strengthens European supply security against regulatory inspection disruptions. For New Entrants and Emerging Players: Enter via telemedicine-enabled diagnostic platforms that capture undiagnosed patients outside established urban headache center catchments. White-space targets include Australia and Canada where specialist neurologist scarcity creates access gaps. The most penetrable segment combines home-use oxygen therapy with remote attack monitoring. A direct-to-patient subscription model bypasses traditional pharmacy benefit structures. For Investors and Strategic Acquirers: Consolidation pressure builds where CMO capacity constraints intersect with accelerating CGRP monoclonal antibody demand. Long-term viability favors platforms with cross-indication neurology infrastructure spanning migraine to cluster headache. Acquisition target archetypes include orphan-focused device manufacturers with FDA breakthrough designation momentum. The signal to watch is G-BA and NICE reimbursement decisions for preventive therapy categories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Accelerates review timelines for novel abortive mechanisms in treatment-resistant subtypes. |
| CMO Capacity Reservation | Secures sterile injectable manufacturing slots amid biologics industry-wide capacity constraints. |
| Headache Center Partnership Networks | Converts diagnostic volume into captive prescribing pathways for integrated protocol adoption. |
| Home-Use Neuromodulation Development | Creates preventive therapy categories distinct from acute pharmaceutical interventions. |
| EMA PRIME Eligibility Pursuit | Unlocks accelerated assessment pathways for European market entry in orphan indications. |
Methodological Framework
Bottom-up neurology clinic modeling reconciled against top-down pharmaceutical manufacturing tracking forms the analytical core of this analysis. Primary interviews with headache medicine specialists, formulary directors at academic medical centers, regulatory affairs leads, and payer access specialists were cross-validated against secondary sources including FDA breakthrough therapy designations, EMA PRIME eligibility records, ClinicalTrials.gov protocol registries, and hospital procurement databases. This triangulation ensures supply-side capacity assumptions align with demand-side prescribing velocity across the projection horizon.
Historical trendline analysis of CGRP-targeted therapy adoption curves informed the forecast framework. Segmentation dimensions modeled include treatment type, product formulation, end-user setting, and regional regulatory cluster. CAGRs were derived from fitted growth curves adjusted for orphan drug incentive impacts and specialist center expansion rates. Forecast inputs incorporate attack frequency epidemiology, diagnostic coding accuracy improvements, and reimbursement pathway velocity by national health technology assessment body.
Inputs from regulatory filing databases and hospital financial disclosures were available through the study window; gaps in real-world attack diary adherence data introduce uncertainty bands around preventive therapy persistence assumptions. Forecasts reflect documented assumptions regarding specialist neurologist supply expansion and CMO capacity buildout timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurology Services Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Spinal Laminoplasty Market
Neurology
South America Neurology Monitoring Market
Neurology
United States Neurology Devices Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Italy Neurology Devices Market
Neurology
Spasticity Treatment Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Global Neuromarketing Market
Neurology
Optic Neuritis Treatment Market
Neurology
Neuro Critical Care Market
Neurology
Neuropsychiatric Disorders and Treatment Market