
 Idiopathic Thrombocytopenic Purpura Therapeutics Market | 2026-2036
Idiopathic Thrombocytopenic Purpura Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Idiopathic Thrombocytopenic Purpura Therapeutics Market Outlook
Good Manufacturing Practice certification for biologic active pharmaceutical ingredients is reorganizing which manufacturers can supply thrombopoietin receptor agonists to regulated markets. Amgen Inc. leverages its recombinant protein manufacturing infrastructure to sustain supply security for megakaryocyte-stimulating therapies. Novartis AG anchors its hematology portfolio through specialized oncology distribution channels that reach academic medical centers. GSK plc. differentiates via long-standing relationships with transfusion medicine departments across European and North American hospital networks.
Idiopathic thrombocytopenic purpura therapeutics comprise pharmacologic agents designed to elevate platelet counts in autoimmune-mediated peripheral platelet destruction, including corticosteroids that suppress antibody-mediated clearance, immunoglobulins that block Fc receptor signaling, thrombopoietin receptor agonists that stimulate megakaryopoiesis, and monoclonal antibodies targeting B-cell or complement pathways. Their primary purpose is to prevent hemorrhagic complications while minimizing chronic immunosuppression. Corticosteroids still occupy the largest volume share in induction settings despite well-documented long-term toxicity profiles that limit duration. Thrombopoietin receptor agonists represent the fastest-expanding segment as oral outpatient administration shifts treatment from hospital-based infusion centers to homecare settings, capturing margin pools previously held by intravenous immunoglobulin suppliers.
The FDA's orphan drug designation program and EMA's PRIME eligibility pathway for hematology products create divergent market access timelines across the Atlantic, with FDA breakthrough therapy status enabling earlier commercial presence for novel mechanisms. Health Canada and the PMDA in Japan maintain distinct platelet threshold requirements for trial endpoints, forcing sponsors to design region-specific pivotal studies rather than unified global protocols. Stakeholders must monitor how CMS reimbursement policies for physician-administered drugs under the hospital outpatient prospective payment system evolve relative to Medicare Part D coverage for oral TPO-RA agents, as this payment divergence will determine site-of-care economics and manufacturer channel strategy.
Market Dynamics
Thrombopoietin receptor agonist protocols are decomposing the traditional hospital-centric infusion model, shifting platelet disorder management toward ambulatory and homecare settings while compressing margins for intravenous immunoglobulin suppliers.
Growth Catalysts
- FDA Accelerated Approval Pathways:Orphan hematology indications benefit from breakthrough therapy status, compressing development timelines for novel megakaryocyte-stimulating agents and enabling earlier commercial presence.
- Specialty Clinic Expansion:Outpatient hematology centers in the United States are building dedicated ITP service lines to capture recurring maintenance therapy volume previously managed in academic medical centers.
- Homecare Administration:Oral TPO-RA formulations eliminate infusion center dependency, allowing patients to self-administer platelet-stimulating therapy outside institutional settings.
Market Restraints
- Recombinant Protein Manufacturing Concentration:Good Manufacturing Practice certification for biologic active pharmaceutical ingredients limits supplier pools to established recombinant protein manufacturers with validated mammalian cell culture infrastructure.
- Long-Term Corticosteroid Toxicity:First-line induction protocols rely on corticosteroids despite documented bone density loss, diabetes induction, and infection risk that cap treatment duration and drive treatment cycling.
- Regional Endpoint Divergence:Health Canada and PMDA maintain distinct platelet threshold requirements for trial endpoints, forcing sponsors to run parallel rather than unified pivotal studies.
Strategic Opportunities
- Site-of-Care Economics Arbitrage:Medicare Part D coverage for oral TPO-RA agents creates margin advantages over hospital outpatient prospective payment system reimbursement for infused products.
- EMA PRIME Eligibility:Priority medicines designation for hematology products accelerates European market access timelines relative to standard regulatory pathways.
- Transfusion Medicine Integration:European and North American hospital networks seek consolidated platelet management protocols spanning prophylaxis, active therapy, and surgical support.
Industry Challenges
- Reimbursement Policy Fragmentation:CMS physician-administered drug payment methodologies diverge from pharmacy benefit coverage, complicating channel strategy and site-of-care contracting.
- Biologic Supply Security:Cold chain logistics and batch release timing for megakaryocyte-stimulating therapies require redundant manufacturing capacity to prevent treatment interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idiopathic Thrombocytopenic Purpura Therapeutics Market |
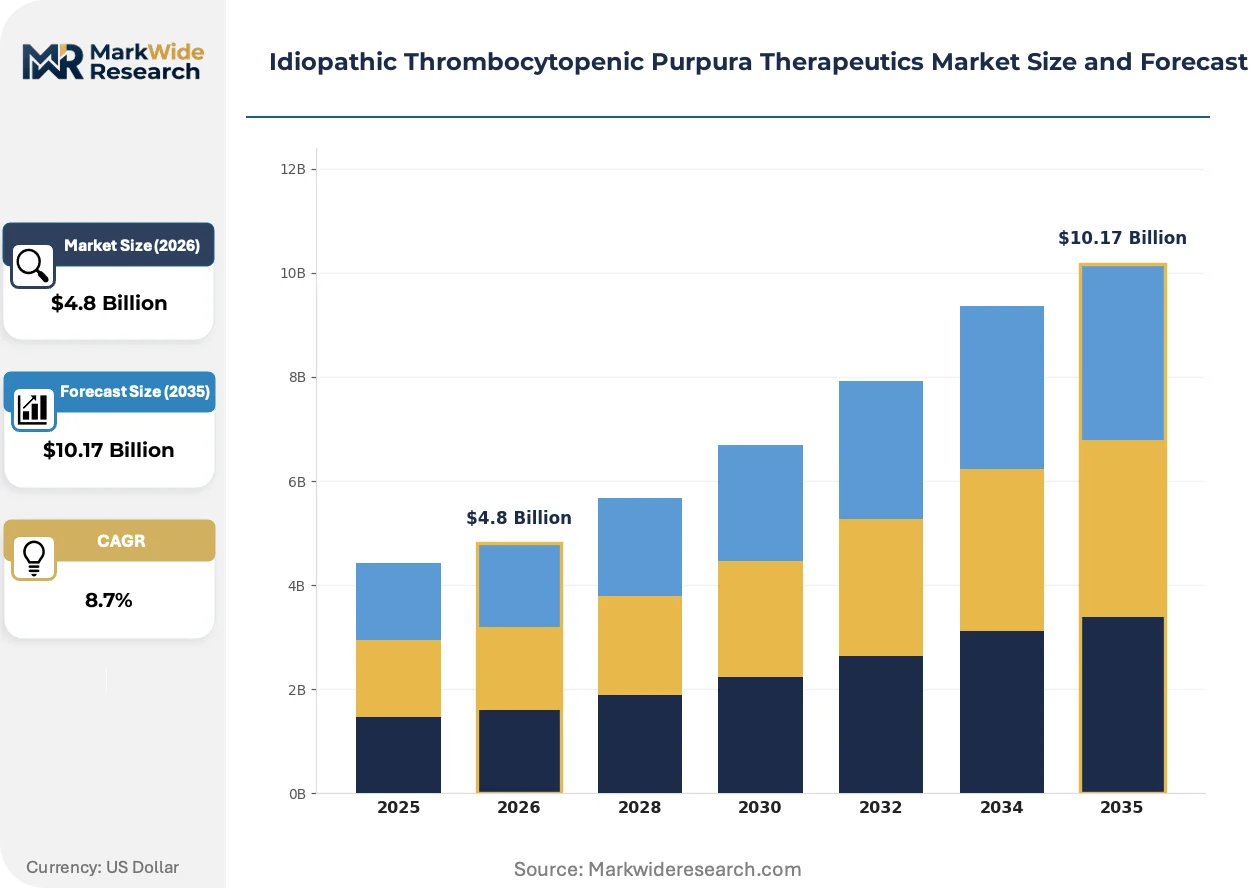
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunoglobulins, Thrombopoietin Receptor Agonists, Monoclonal Antibodies Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Specialty Clinics, Homecare Settings, Ambulatory Surgical Centers Treatment Stage: Induction, Maintenance, Rescue, Second-Line |
| Companies Covered | Amgen Inc., Novartis AG, F. Hoffmann-La Roche Ltd, GSK plc., Grifols, S.A., Pfizer, Bristol-Myers Squibb, Merck & Co., Takeda Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idiopathic Thrombocytopenic Purpura Therapeutics Market Strategic Shifts
Oral small-molecule platelet stimulation is displacing parenteral biologics across maintenance settings, while regulatory pathways for rare hematology indications compress development timelines and payer cost-containment mechanisms reshape site-of-care economics.
Second-generation thrombopoietin receptor agonists with improved pharmacokinetic profiles are decomposing the historical trade-off between platelet response durability and hepatotoxicity risk. Academic medical centers in Germany and the United States are adopting these agents for steroid-refractory patients. The technology is compressing the addressable market for intravenous immunoglobulin in chronic ITP management.
EMA's PRIME eligibility pathway for hematology products is accelerating European commercial entry relative to standard centralized procedures. Sponsors with breakthrough therapy status from FDA are leveraging parallel EMA engagement to synchronize transatlantic launches. Small-cap biologics developers without established European distribution infrastructure face compressed timelines to secure specialized oncology channel partnerships.
Integrated health systems in the United States are consolidating platelet disorder management under value-based purchasing arrangements that bundle diagnostic workup, induction therapy, and maintenance monitoring. Hospital networks are displacing independent hematology practices as the primary site for ITP diagnosis and treatment initiation. This concentration is most visible in Medicare Advantage populations where capitated payments incentivize vertical integration of specialty pharmacy and clinical services.
Idiopathic Thrombocytopenic Purpura Therapeutics Market Segmentation
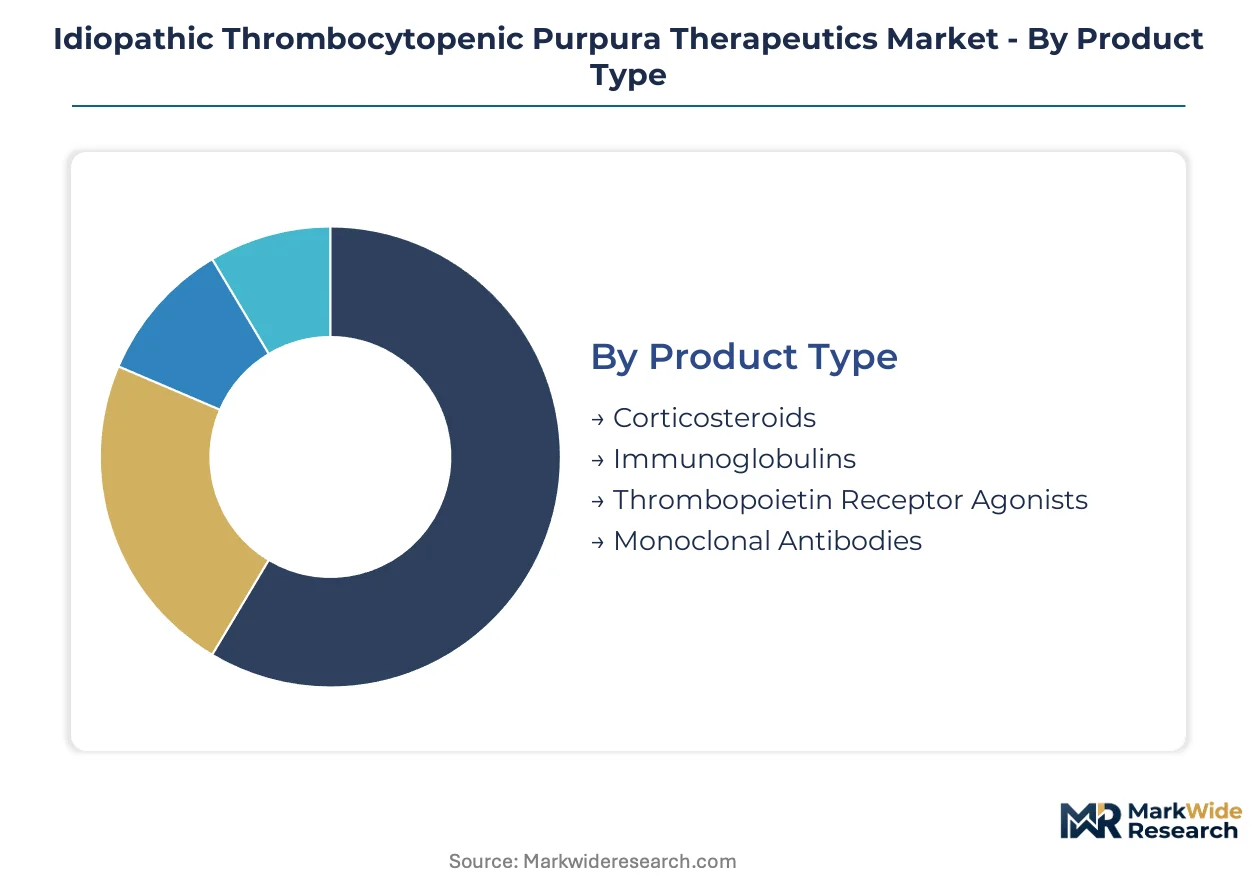
ITP therapeutics fragment across pharmacologic mechanisms, administration routes, and care settings, with reimbursement pathways and regulatory designations determining which segments capture volume versus margin. Understanding these divides reveals where manufacturers must position for sustainable returns.
Product Type:
FDA breakthrough therapy status and EMA PRIME eligibility create asymmetric commercial timelines across mechanism classes, advantaging novel biologics over established small molecules in regulated markets.
- Corticosteroids:Oral prednisone and dexamethasone remain the first-line induction standard despite well-documented toxicities including osteoporosis, hyperglycemia, and infection susceptibility that limit treatment duration. Demand concentrates in acute hospital settings where rapid platelet elevation is required for bleeding emergencies, though long-term use is constrained by mandatory tapering protocols.
- Thrombopoietin Receptor Agonists:Oral eltrombopag and subcutaneous romiplostim stimulate megakaryopoiesis through distinct receptor binding sites, enabling outpatient maintenance without immunosuppression. Specialty clinics in the United States and Germany are capturing recurring prescription volume as these agents displace intravenous immunoglobulin for chronic management.
- Immunoglobulins:High-dose intravenous immunoglobulin blocks Fc receptor-mediated platelet destruction, reserved for rescue scenarios and perioperative platelet support.
- Monoclonal Antibodies:B-cell depleting and complement-inhibiting biologics target refractory populations with autoimmune-driven pathology.
Established volume favors corticosteroids; emerging adoption favors thrombopoietin receptor agonists.
Delivery Mode:
Site-of-care economics diverge sharply between hospital-administered infusion products and self-administered oral agents, with Medicare Part D versus outpatient prospective payment system reimbursement determining manufacturer channel investments.
- Oral:Small-molecule TPO-RAs eliminate infusion center dependency, allowing home administration with pharmacy benefit coverage that bypasses hospital markup structures. Patient adherence monitoring and remote platelet tracking are expanding in integrated US health systems.
- Intravenous:Immunoglobulin and emergency corticosteroid protocols require institutional administration, capturing higher per-dose reimbursement under hospital outpatient payment systems despite compressing utilization.
- Subcutaneous:Weekly self-injection of peptide TPO-RAs bridges convenience and bioavailability for patients with hepatic contraindications to oral therapy.
- Intramuscular:Limited to specific corticosteroid formulations in acute settings where vascular access is compromised.
Margin concentration favors intravenous; volume expansion favors oral.
End User:
Vertical integration of specialty pharmacy services into hospital networks is displacing independent hematology practices as the primary site for ITP diagnosis and treatment initiation.
- Specialty Clinics:Outpatient hematology centers are building dedicated ITP service lines to capture recurring maintenance therapy volume, particularly for TPO-RA monitoring and dose titration. These facilities optimize throughput for stable chronic patients requiring quarterly platelet surveillance.
- Hospitals:Academic medical centers retain dominance for induction therapy, rescue interventions, and complex cases requiring multidisciplinary coordination with transfusion medicine and surgical services.
- Homecare Settings:Self-administration of oral agents and subcutaneous biologics is expanding with remote patient monitoring platforms and specialty pharmacy distribution.
- Ambulatory Surgical Centers:Pre-procedural platelet optimization for elective interventions represents a narrow but high-margin niche.
Acute revenue concentrates in hospitals; recurring lifetime value concentrates in specialty clinics.
Treatment Stage:
Clinical guidelines stratify therapy intensity by disease phase, with corticosteroid-refractory definitions and platelet count thresholds determining eligibility for advanced mechanisms.
- Induction:High-dose corticosteroid protocols aim for rapid platelet response within weeks, with failure to achieve thresholds triggering escalation to second-line options.
- Maintenance:Long-term TPO-RA therapy prevents relapse while minimizing corticosteroid exposure, representing the steepest expansion trajectory as oral outpatient administration displaces hospital-based care.
- Rescue:Emergency immunoglobulin and platelet transfusion support for life-threatening hemorrhage or urgent surgical requirements.
- Second-Line:Splenectomy-sparing biologics for persistent or chronic ITP following induction failure, including monoclonal antibodies with orphan drug exclusivity.
Treatment cycling favors induction volume; patient lifetime value favors maintenance retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designations and Medicare Part D reimbursement advantages for oral agents are concentrating ITP therapeutic development and commercialization in markets with mature orphan drug frameworks and integrated specialty pharmacy infrastructure.
United States
Integrated health systems in Texas and the Northeast Corridor are consolidating ITP diagnosis and maintenance therapy under value-based purchasing arrangements. CMS reimbursement policies for physician-administered drugs under the hospital outpatient prospective payment system diverge from Medicare Part D coverage for oral TPO-RA agents, reshaping site-of-care economics. The Greater Boston cluster anchors clinical trial density for novel megakaryocyte-stimulating agents.
Germany
Academic medical centers in Bavaria and Baden-Württemberg are adopting second-generation thrombopoietin receptor agonists for steroid-refractory patients. EMA PRIME eligibility for hematology products accelerates European market access timelines relative to standard centralized procedures. The Rhine-Ruhr metropolitan region concentrates specialized oncology distribution channels reaching university hospitals.
Japan
PMDA maintains distinct platelet threshold requirements for trial endpoints, forcing sponsors to design region-specific pivotal studies rather than unified global protocols. The Kanto region around Tokyo anchors hematology research infrastructure and orphan drug commercialization. METI incentives for rare disease therapeutic development are expanding domestic biologics manufacturing capacity.
Switzerland
Swissmedic's alignment with EMA centralized procedures enables synchronized European launches for breakthrough-designated therapies. The Basel-Zurich corridor concentrates transfusion medicine expertise and hospital network procurement consolidation. Specialized oncology distribution channels from this cluster reach academic medical centers across German-speaking Europe.
United Kingdom
NHS England's specialized commissioning frameworks for rare hematology conditions are concentrating ITP service delivery in designated treatment centers. The London-Southeast cluster dominates biologics access and maintenance therapy monitoring infrastructure. NICE technology appraisals for orphan indications are compressing formulary inclusion timelines for novel mechanisms.
Idiopathic Thrombocytopenic Purpura Therapeutics Market Competitive Environment
Listed leaders compete with private specialists across recombinant protein manufacturing infrastructure and specialized oncology distribution reach. The market structure concentrates around established biologics manufacturers with validated mammalian cell culture capacity and hospital network relationships. Three archetypes dominate: large-cap diversified pharmaceuticals with hematology portfolios, mid-cap biologics specialists with orphan drug focus, and plasma-derived therapy suppliers with transfusion medicine integration. Competitive moves center on site-of-care contracting for oral versus infused products and EMA-FDA parallel regulatory engagement.
Among large-cap diversified pharmaceuticals, Amgen Inc., Novartis AG, and GSK plc. exemplify distinct strategic positioning. Amgen occupies a position anchored in recombinant protein manufacturing infrastructure for megakaryocyte-stimulating therapies. Novartis sits within the specialized oncology distribution tier reaching academic medical centers. GSK represents the transfusion medicine integration archetype through hospital network relationships across European and North American markets.
| Leading Market Players |
|---|
| Amgen Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| GSK plc. |
| Grifols, S.A. |
| Pfizer |
| Bristol-Myers Squibb |
| Merck & Co. |
| Takeda Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Mammalian cell culture capacity utilization above 80% at established recombinant protein facilities creates natural price floors for thrombopoietin receptor agonists, while simultaneously concentrating supply security leverage with manufacturers holding validated GMP infrastructure across multiple regulatory jurisdictions.
Pricing Analysis
Certification level (FDA breakthrough/EMA PRIME/orphan designation tier) creates the primary spread between premium biologics and standard-of-care small molecules. Three-tier pricing structure across premium TPO-RAs, standard corticosteroid protocols, and economy rescue immunoglobulin segments reflects reimbursement pathway divergence under Medicare Part D versus hospital outpatient payment systems. Cost compression in the intravenous immunoglobulin tier is intensifying as oral TPO-RAs displace maintenance volume. Academic medical centers exhibit lowest price sensitivity due to bundled value-based purchasing arrangements, while independent specialty clinics face highest sensitivity to pharmacy benefit coverage gaps.
Supply Chain Analysis
Cold chain logistics for biologic active pharmaceutical ingredients represents the critical chokepoint, with batch release timing at FDA-inspected mammalian cell culture facilities determining treatment continuity for megakaryocyte-stimulating therapies. Manufacturing concentrates in the United States, Switzerland, and Japan, drawing from recombinant protein expression systems, sterile fill-finish capacity, and validated viral clearance infrastructure. Single-source vulnerability runs through concentrated supplier pools for GMP-certified biologic APIs. Distribution runs through specialized oncology channels reaching academic medical centers and integrated health system specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral thrombopoietin receptor agonist protocols are accelerating market expansion as homecare administration unlocks patient populations previously excluded from hospital-centric infusion models.
For Market Incumbents: Secure redundant manufacturing capacity across FDA and EMA-inspected facilities to mitigate single-source biologic API risk. Deepen backward integration into recombinant protein expression systems to defend margin position against emerging biosimilar entrants targeting TPO-RA maintenance volume. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track creates expedited commercial entry for novel megakaryocyte-stimulating mechanisms. Target steroid-refractory patient segments in Medicare Advantage populations where capitated payments incentivize site-of-care shifts toward oral outpatient administration. Pursue parallel EMA PRIME engagement to synchronize transatlantic launches through specialized oncology distribution partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biologics specialists with validated mammalian cell culture infrastructure and orphan drug exclusivity portfolios. Long-term viability rests on manufacturers capable of serving both induction rescue scenarios and chronic maintenance settings across diversified reimbursement pathways. Watch FDA accelerated approval decisions for second-generation TPO-RAs as inflection indicator for intravenous immunoglobulin displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA breakthrough status compresses development timelines for novel megakaryocyte-stimulating agents. |
| Specialty Clinic Network Expansion | Outpatient hematology centers capture recurring TPO-RA maintenance volume from academic medical centers. |
| Site-of-Care Economics Arbitrage | Medicare Part D coverage for oral agents creates margin advantages over hospital outpatient reimbursement. |
| EMA-FDA Parallel Regulatory Engagement | Synchronized transatlantic launches accelerate commercial presence in German and UK hospital networks. |
| Biologic Manufacturing Scale-Up | Redundant GMP-certified capacity prevents treatment interruption for platelet disorder patients. |
Study Parameters
The analysis maps pharmacologic mechanism classes, delivery modes, and treatment stage segments, each validated through hematology practice administrators, specialty pharmacy directors, payer formulary managers, and transfusion medicine chiefs. Primary interviews with these stakeholders combined with secondary validation against FDA orphan drug designations, EMA PRIME eligibility records, ClinicalTrials.gov protocols, and CMS Medicare Part D claims data. Bottom-up prescription volume modeling and top-down therapeutic class expenditure estimates undergo cross-triangulation to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models treatment line progression, administration route substitution patterns, patient population stratification by platelet threshold, and regional regulatory cluster differentiation. CAGRs derive from segmented adoption curves and reimbursement pathway evolution. Forecast inputs include specialty clinic expansion rates, site-of-care shift velocity, and orphan drug exclusivity expiration sequencing.
Underlying assumptions cover stable FDA accelerated approval pathway continuity, with deviation risk concentrated in CMS reimbursement policy shifts between hospital outpatient and pharmacy benefit coverage. Forecasts reflect these documented assumptions. Practitioners should keep alternative scenarios live as Medicare Advantage penetration and value-based purchasing arrangement evolution reshape site-of-care economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Gallbladder Cancer Therapeutics Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market