
 Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market | 2026-2036
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market Foresight
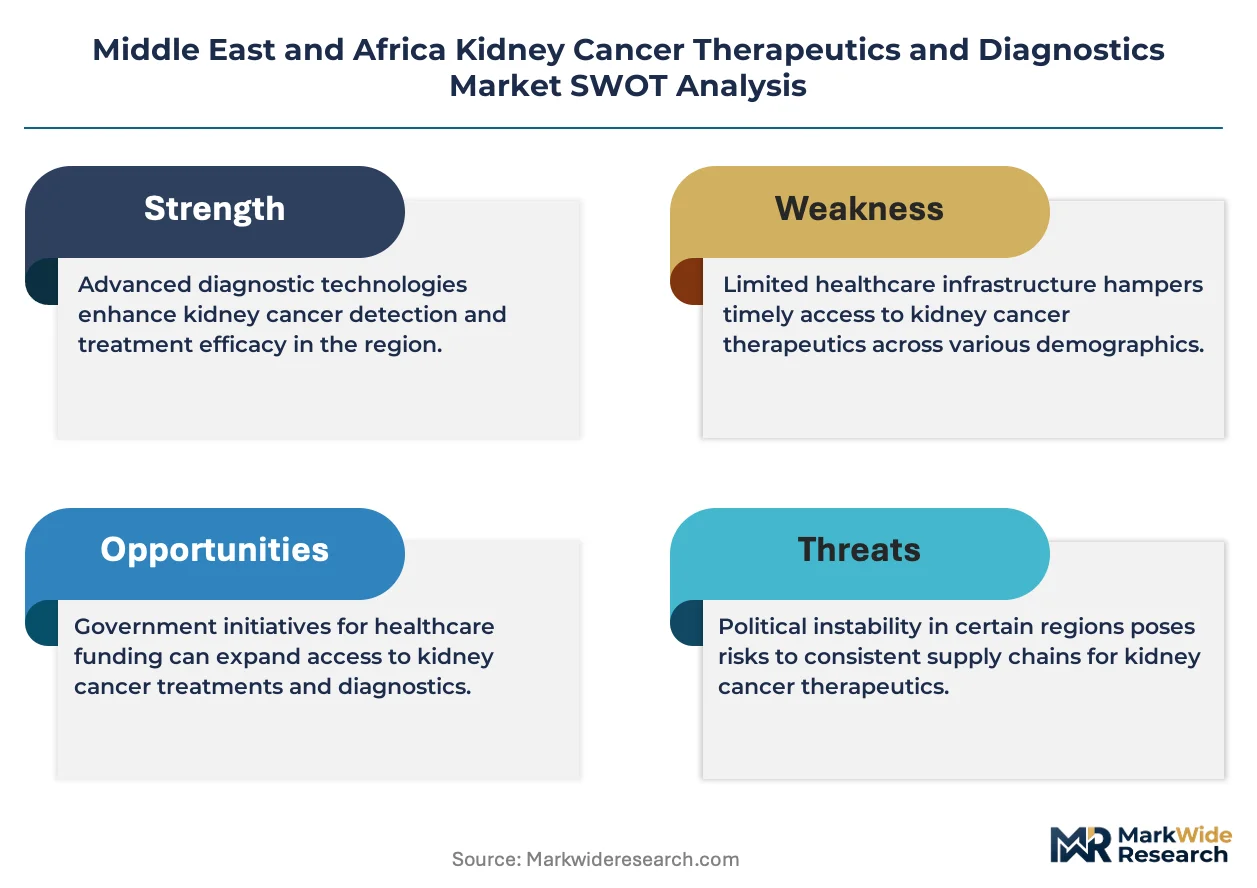
Hospital procurement networks across the Middle East and Africa is tilting toward centralized oncology purchasing agreements that bundle therapeutics with companion diagnostics. Bristol Myers Squibb Company leverages its immuno-oncology portfolio to anchor long-term supply contracts with major hospital systems. Pfizer competes through targeted therapy franchises that dominate renal cell carcinoma protocols in private hospital chains. Novartis differentiates via integrated diagnostic-therapeutic platforms that extend clinical decision support to regional cancer centers.
Kidney cancer therapeutics and diagnostics encompasses pharmaceutical interventions and detection systems designed to treat and identify malignant neoplasms of the renal parenchyma, with molecular diagnostics employing polymerase chain reaction and fluorescence in situ hybridization to detect VHL gene mutations at detection thresholds below 1% mutant allele frequency. Immunotherapy commands the largest revenue share among product types due to durable response rates in metastatic settings, while genomic sequencing represents the fastest-expanding technology segment as liquid biopsy adoption accelerates in Gulf state reference laboratories. Hospitals retain dominant end-user status, though home care settings for oral targeted therapy administration are capturing incremental volume as reimbursement frameworks evolve.
South Africa's SAHPRA, Saudi Arabia's SFDA, and Egypt's national pharmaceutical regulator enforce varying oncology product registration standards that shape market entry sequencing and local clinical trial requirements. Egypt's centralized tender system for oncology medicines restricts direct hospital purchasing, forcing manufacturers to navigate state procurement cycles. Stakeholders must monitor how Gulf state health insurance reforms and South Africa's national cancer control strategy revisions redistribute payment responsibility between public budgets and private coverage pools.
Market Dynamics
Centralized oncology purchasing agreements across tertiary hospital networks are consolidating procurement power, forcing manufacturers to bundle companion diagnostics with therapeutic portfolios to secure long-term supply contracts in South Africa, Egypt, and Saudi Arabia.
Growth Catalysts
- South Africa's national cancer control strategy:Government-funded screening programs are expanding diagnostic infrastructure in tertiary hospitals, creating sustained demand for molecular testing platforms.
- Liquid biopsy acceleration:Gulf state reference laboratories are adopting genomic sequencing for VHL mutation detection at sub-1% allele frequency thresholds, driving companion diagnostic volume.
- SFDA expanded oncology pathways:Saudi Arabia's streamlined registration timelines are compressing product access delays for immunotherapy agents.
Market Restraints
- Cold chain infrastructure gaps:Temperature-controlled distribution for biologics remains unreliable across sub-Saharan Africa, constraining mAb penetration outside major urban centers.
- Egypt's centralized tender system:State procurement cycles restrict direct hospital purchasing, forcing manufacturers into extended negotiation timelines with limited pricing autonomy.
- Pathologist workforce scarcity:Diagnostic interpretation capacity concentrates in Johannesburg, Cairo, and Riyadh, creating reporting bottlenecks for FISH and PCR-based assays.
Strategic Opportunities
- Home oral therapy administration:Reimbursement evolution in private South African coverage pools is enabling targeted therapy delivery outside hospital settings.
- Public-private diagnostic partnerships:Egypt's Ministry of Health is contracting private laboratories to clear reference testing backlogs, opening channel access for platform vendors.
- AI-assisted pathology:Integration of digital image analysis with conventional histopathology is digitizing diagnostic workflows in Saudi tertiary centers.
Industry Challenges
- Multi-regulator clinical trial duplication:SAHPRA, SFDA, and Egypt's national pharmaceutical regulator maintain non-harmonized oncology trial requirements, inflating development costs.
- Biomarker assay standardization:Lack of inter-laboratory concordance for PD-L1 scoring creates treatment selection variability across immunotherapy protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market |
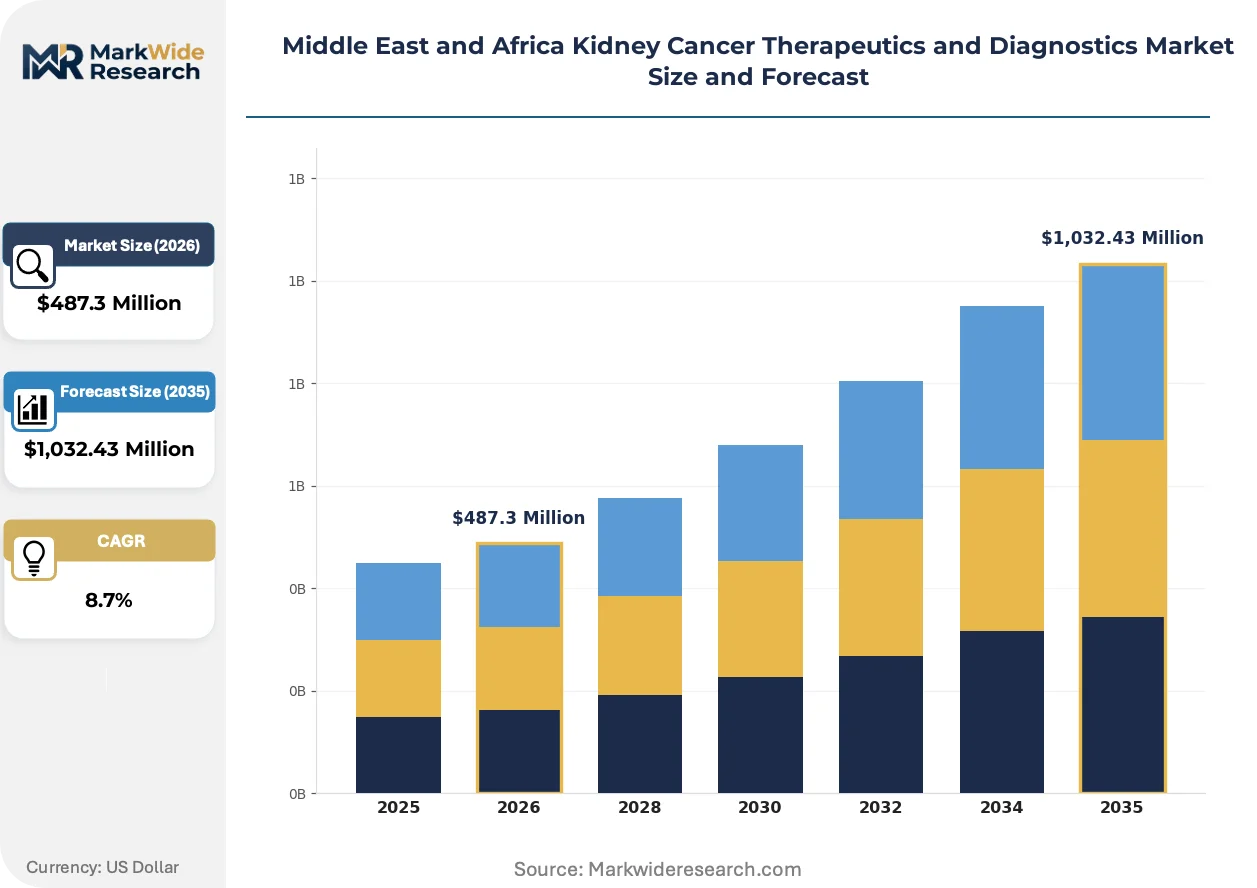
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Targeted Therapy, Chemotherapy, Radiation Therapy End User: Hospitals, Clinics, Research Laboratories, Home Care Settings Delivery Mode: Intravenous, Oral, Subcutaneous, Injectable Technology: Molecular Diagnostics, Biomarkers, Imaging Techniques, Genomic Sequencing |
| Companies Covered | Bayer AG, F. Hoffmann-La Roche, Bristol Myers Squibb Company, Abbott Laboratories, Amgen Inc., Merck & Co., Pfizer, Novartis AG, AstraZeneca, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Digital pathology platforms and AI-assisted diagnostic interpretation are transforming renal carcinoma classification workflows, while regulatory harmonization efforts and evolving procurement models reshape competitive access across the Middle East and Africa.
Next-generation sequencing panels are digitizing VHL mutation profiling and chromosomal aberration detection in regional cancer centers. Academic medical centers in Cape Town and Riyadh are deploying these platforms for prospective patient stratification. The technology is digitizing clinical decision support by enabling real-time biomarker reporting that compresses time-to-treatment initiation.
SAHPRA's expanded oncology registration pathways are accelerating market access timelines for novel therapeutics. The framework reduces duplicate local clinical trial requirements when FDA or EMA approval precedes submission. South African private hospital chains are responding by front-loading formulary negotiations for checkpoint inhibitors ahead of public sector tender cycles.
Hospital procurement networks are consolidating into multi-year framework agreements that bundle imaging, surgery, and systemic therapy under single-source contracts. Regional cancer centers in Saudi Arabia are displacing transactional purchasing with integrated service agreements. Egypt remains the exception where state tender processes preserve fragmented acquisition channels.
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market Segmentation
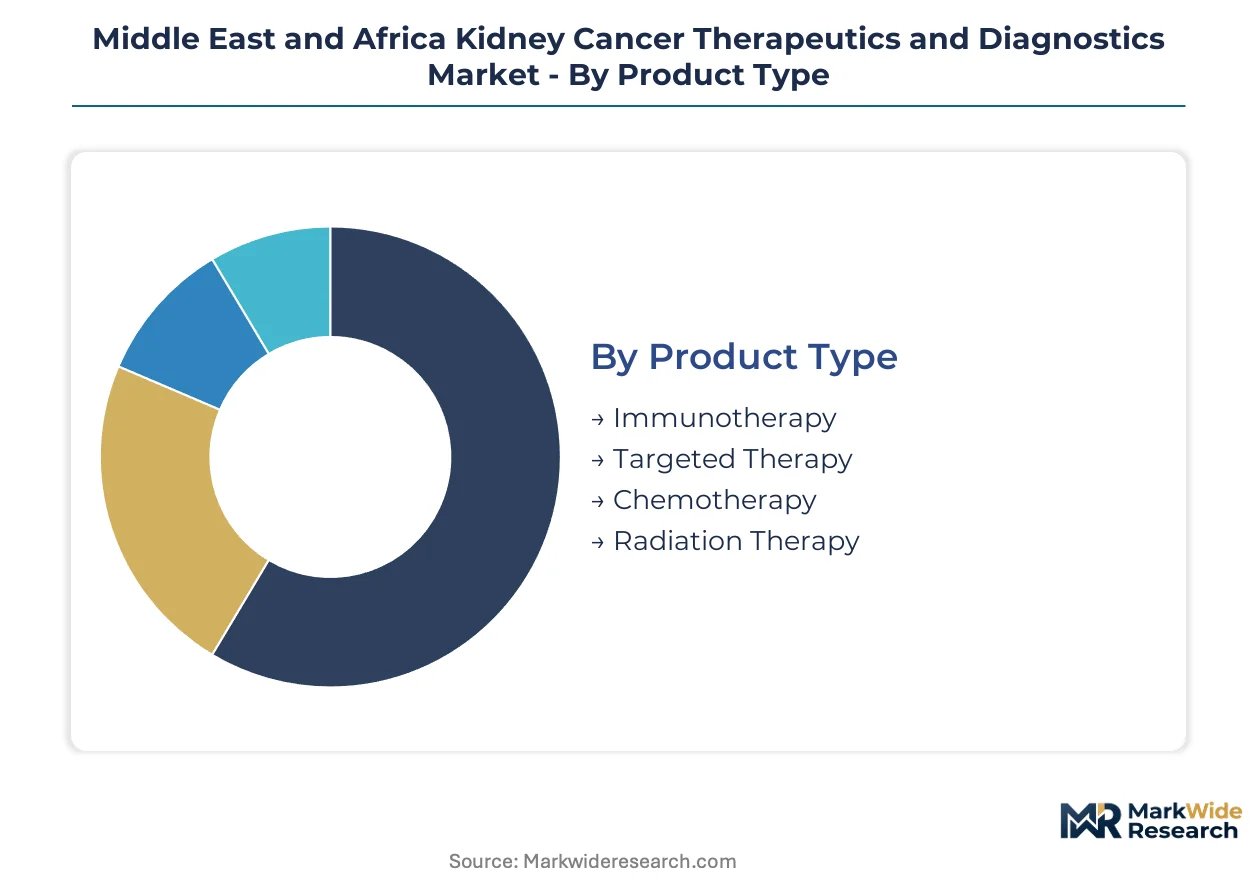
Segmentation in the Middle East and Africa kidney cancer market reveals distinct procurement patterns across therapeutic modalities and diagnostic platforms. Each category reflects divergent infrastructure requirements, reimbursement pathways, and clinical adoption timelines that shape vendor positioning.
Product Type:
Mature biologics anchor current revenue while emerging modalities reshape treatment protocols across South African and Saudi tertiary centers.
- Immunotherapy:Checkpoint inhibitors and cytokine therapies targeting PD-1/PD-L1 and CTLA-4 pathways dominate metastatic renal cell carcinoma protocols. Oncology departments in Johannesburg and Riyadh concentrate demand as government screening programs expand eligible patient pools for first-line combination regimens.
- Targeted Therapy:Tyrosine kinase inhibitors and mTOR inhibitors deliver precision intervention against VHL-mutant tumors. Private hospital chains in Egypt and South Africa drive procurement volume as oral administration protocols reduce infusion center burden.
- Chemotherapy:Cytotoxic agents retain niche utility in sarcomatoid histology and combination salvage settings.
- Radiation Therapy:Stereotactic body radiotherapy addresses oligometastatic disease in reference centers with linear accelerator capacity.
Immunotherapy retains volume leadership; genomic sequencing companion diagnostics are gaining share fastest.
End User:
Institutional scale and reimbursement sophistication determine purchasing authority across the patient care continuum.
- Hospitals:Tertiary oncology centers with embedded pathology laboratories control therapeutic decision-making and diagnostic platform procurement. SAHPRA-registered institutions in Cape Town and Pretoria anchor centralized purchasing agreements that bundle imaging, surgery, and systemic therapy.
- Clinics:Community oncology practices and day-care infusion centers handle stable patient monitoring and oral therapy dispensing. Egyptian private clinic networks are expanding as the Ministry of Health contracts external providers to clear reference testing backlogs.
- Research Laboratories:Academic medical centers conduct prospective biomarker stratification and clinical trial enrollment.
- Home Care Settings:Oral targeted therapy administration outside institutional walls is capturing incremental volume as South African private coverage pools evolve reimbursement frameworks.
Hospitals command procurement volume; home care settings are climbing the fastest as oral therapy protocols proliferate.
Delivery Mode:
Route of administration directly shapes cold chain requirements, patient compliance, and care setting economics.
- Intravenous:Infusion-dependent biologics require temperature-controlled distribution and specialized nursing capacity. Cold chain infrastructure gaps across sub-Saharan Africa constrain monoclonal antibody penetration outside major urban corridors.
- Oral:Small-molecule inhibitors enable decentralized administration and reduce hospital occupancy pressure. Saudi private hospital chains are front-loading formulary negotiations for oral TKIs ahead of public sector tender cycles.
- Subcutaneous:Self-administered formulations reduce clinic visit frequency for maintenance regimens.
- Injectable:Depot formulations and cytotoxic agents require healthcare professional administration.
Intravenous retains institutional dominance; oral delivery is expanding most quickly across reimbursement-evolving markets.
Technology:
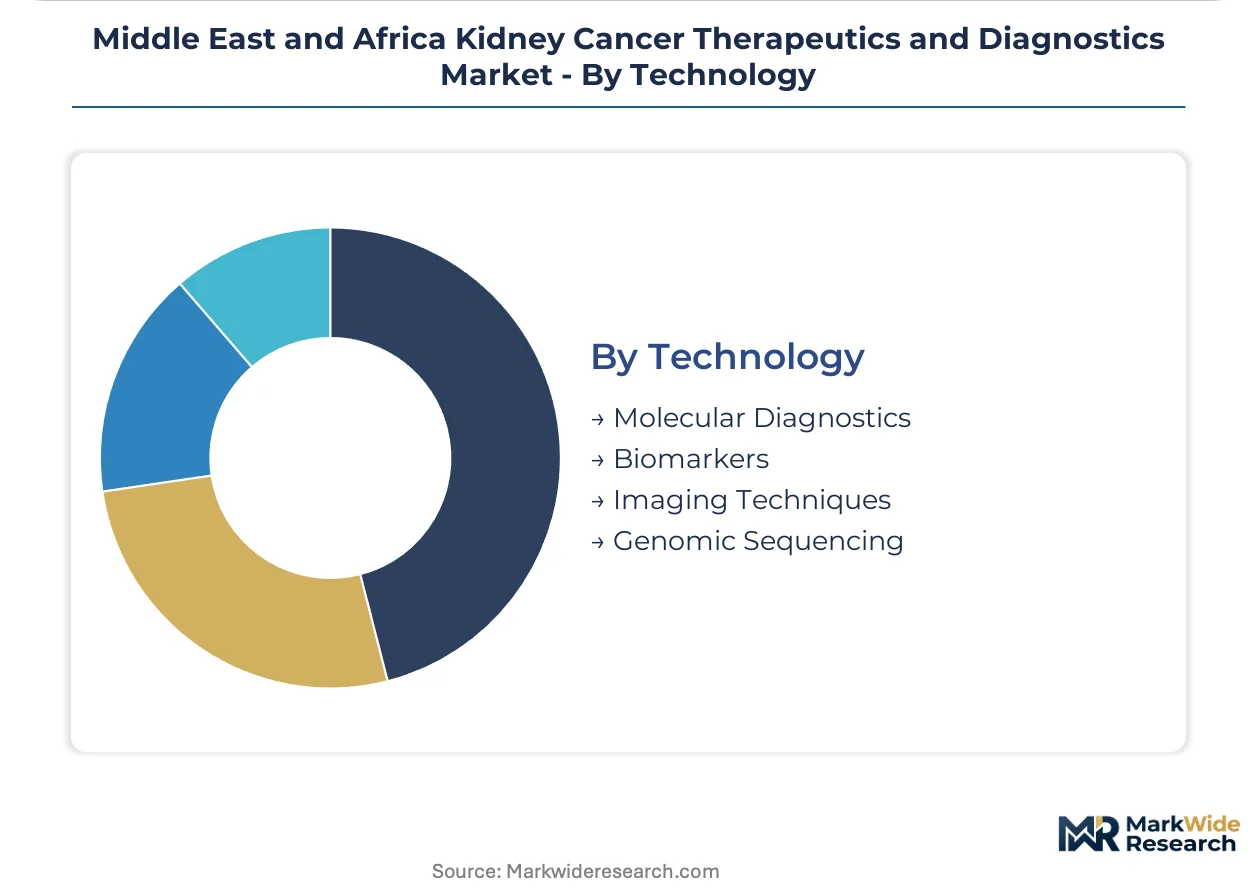
Diagnostic platform sophistication determines biomarker detection thresholds and clinical decision support capabilities.
- Molecular Diagnostics:PCR and FISH platforms detect VHL gene mutations at sub-1% mutant allele frequency. Pathologist workforce scarcity concentrates interpretation capacity in Johannesburg, Cairo, and Riyadh, creating reporting bottlenecks for assay processing.
- Genomic Sequencing:Next-generation sequencing panels digitize chromosomal aberration detection and enable real-time patient stratification. Gulf state reference laboratories in Dubai and Riyadh are adopting liquid biopsy protocols that accelerate time-to-treatment initiation.
- Biomarkers:PD-L1 scoring and angiogenesis markers guide immunotherapy and targeted therapy selection.
- Imaging Techniques:CT, MRI, and PET-CT protocols stage disease and monitor therapeutic response.
Molecular diagnostics holds current volume leadership; genomic sequencing displays the steepest expansion trajectory as liquid biopsy adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi tertiary hospital networks while South African public procurement cycles compress margins. Egypt's state tender system fragments access further. Gulf state insurance reforms and national cancer strategies redistribute payment responsibility across the region.
Saudi Arabia
Oncology departments in Riyadh and Jeddah anchor demand for checkpoint inhibitors and companion diagnostics. SFDA's streamlined oncology registration pathways compress product access timelines for novel immunotherapy agents. King Faisal Specialist Hospital anchors centralized procurement agreements that bundle molecular testing with therapeutic portfolios.
South Africa
Johannesburg and Pretoria tertiary centers drive volume for genomic sequencing platforms and oral targeted therapies. SAHPRA's expanded oncology registration pathways reduce duplicate clinical trial requirements when FDA or EMA approval precedes submission. Cape Town academic medical centers deploy next-generation sequencing for prospective patient stratification.
Egypt
Cairo-based oncology centers concentrate diagnostic interpretation capacity for FISH and PCR-based assays. The Ministry of Health's centralized tender system for oncology medicines restricts direct hospital purchasing and forces extended state negotiation timelines. Private laboratory networks in Alexandria and Giza contract with public hospitals to clear reference testing backlogs.
United Arab Emirates
Dubai and Abu Dhabi reference laboratories accelerate liquid biopsy adoption for VHL mutation detection at sub-1% allele frequency. MOHAP's regulatory frameworks align with Gulf Cooperation Council harmonization efforts for oncology product registration. Sheikh Khalifa Medical City anchors integrated diagnostic-therapeutic platforms that extend clinical decision support.
Israel
Tel Aviv metropolitan hospitals concentrate demand for AI-assisted pathology and digital diagnostic interpretation platforms. The national health insurance system's comprehensive oncology coverage enables rapid adoption of novel therapeutics. Hadassah Medical Center and Sheba Medical Center anchor research partnerships for biomarker-driven clinical trials.
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying molecular assays and biomarker reagents. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with immuno-oncology portfolios, diagnostic platform vendors with integrated sequencing capabilities, and regional distributors managing cold chain logistics. Strategic moves concentrate on long-term supply contract anchoring and diagnostic-therapeutic bundling. Geographic expansion through local clinical trial partnerships and regulatory pathway optimization shapes competitive positioning.
Among Swiss-based pharmaceutical conglomerates, Novartis AG and Roche occupy positions exemplifying integrated diagnostic-therapeutic platform strategies. Bristol Myers Squibb Company anchors the immuno-oncology tier through checkpoint inhibitor portfolios. Pfizer sits within the targeted therapy specialist archetype, with Merck & Co. representing the combination regimen approach to metastatic renal cell carcinoma.
| Leading Market Players |
|---|
| Bayer AG |
| F. Hoffmann-La Roche |
| Bristol Myers Squibb Company |
| Abbott Laboratories |
| Amgen Inc. |
| Merck & Co. |
| Pfizer |
| Novartis AG |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
The Jebel Ali-Durban maritime corridor channels biologics and molecular diagnostics into Middle East and Africa oncology markets, with freight cost volatility amplifying price spreads between reference laboratories in Gulf states and tertiary hospitals in sub-Saharan Africa. This logistics architecture concentrates pricing power among manufacturers with integrated cold chain capabilities while forcing tiered access models based on institutional refrigeration infrastructure.
Pricing Analysis
The customization-premium spread separates configured-to-order companion diagnostic bundles from standard immunotherapy vials across South African and Saudi procurement networks. Contract-based long-term offtake agreements dominate, with price differentiation driven by SFDA registration tier and cold chain service bundling. Pricing pressure stems from Egypt's centralized tender cycles compressing manufacturer margins. Private hospital chains in Johannesburg and Riyadh exhibit lowest price sensitivity; public sector buyers in Cairo and Lagos face acute budget constraints.
Supply Chain Analysis
Upstream feedstock for monoclonal antibodies and PCR reagents draws from Switzerland, Singapore, and the United States, with active pharmaceutical ingredients and diagnostic enzymes constituting critical dependencies. Single-source vulnerability concentrates in temperature-controlled distribution networks spanning the Sahara and Horn of Africa. Distribution runs through Johannesburg and Dubai regional hubs before final-mile delivery to tertiary oncology centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa kidney cancer market represents early-cycle expansion as liquid biopsy adoption penetrates Gulf state reference laboratories and South African private coverage pools enable home oral therapy administration.
For Market Incumbents: Build regulatory pathway expertise as the defensive moat. Secure SAHPRA and SFDA pre-approval commitments ahead of competitor submissions to compress access timelines. Anchor long-term supply contracts with King Faisal Specialist Hospital and Johannesburg tertiary networks before public tender cycles commence. Deepen backward integration into diagnostic platform manufacturing to capture companion testing revenue streams threatened by independent laboratory vendors. For New Entrants and Emerging Players: Pursue public-private diagnostic partnerships in Egypt as the most penetrable channel, where Ministry of Health contracting of private laboratories clears reference testing backlogs. Target oral targeted therapy distribution networks in South African home care settings where reimbursement evolution outpaces established infusion center relationships. Deploy AI-assisted pathology platforms as the go-to-market angle for Saudi tertiary centers digitizing diagnostic workflows. For Investors and Strategic Acquirers: Regional distributors with captive cold chain logistics represent the priority acquisition archetype for portfolio exposure to biologics penetration outside major urban corridors. Long-term viability hinges on Gulf state health insurance reforms sustaining private coverage expansion and South Africa's national cancer control strategy maintaining screening program funding. Watch liquid biopsy reimbursement decisions by Saudi and UAE health authorities as the inflection signal for genomic sequencing platform adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Bundling | Integrates molecular testing with therapeutic portfolios to secure multi-year hospital framework agreements. |
| SFDA Registration Pathway Optimization | Compresses product access timelines for novel immunotherapy agents in Saudi tertiary networks. |
| AI-Assisted Pathology Integration | Digitizes renal carcinoma classification workflows at Riyadh and Tel Aviv academic medical centers. |
| Home Oral Therapy Distribution | Captures incremental volume as South African private coverage pools evolve reimbursement frameworks. |
| Public-Private Diagnostic Partnership | Opens channel access for platform vendors clearing Egypt's Ministry of Health reference testing backlogs. |
Research Methodology
Desk research of regulatory filings, clinical trial registries, and hospital procurement databases preceded structured interviews with oncology department heads, pharmaceutical regulatory affairs leads, formulary directors at private hospital chains, and diagnostic platform procurement managers. Secondary validation drew from SAHPRA registration records, SFDA oncology pathway documentation, Egypt's centralized tender announcements, and Gulf state health insurance reform policy papers. Bottom-up patient volume estimates and top-down healthcare expenditure allocations were triangulated to anchor market sizing.
Assumptions held fixed include current reimbursement frameworks for immunotherapy and targeted therapy across South Africa, Saudi Arabia, and Egypt; varied assumptions include liquid biopsy adoption velocity and AI-assisted pathology penetration rates. The analytical framework modeled product type, end user institution tier, delivery mode, and technology platform across the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing evolution in public tender versus private procurement channels. Forecast inputs incorporated biomarker assay standardization progress and pathologist workforce expansion timelines.
Sensitivities concentrate around Gulf state health insurance reform implementation pace, SAHPRA registration pathway continuity, and cold chain infrastructure investment levels in sub-Saharan Africa. Forecasts reflect these assumptions alongside screening program budget allocations in Egypt and South Africa. Cross-checking against WHO cancer registry data and national health accounts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Interstitial Lung Disease Treatment Market