
 Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market | 2026-2036
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market Foresight
Hepatologist workforce shortages across major markets is reorganizing how clinical trials recruit principal investigators and how pharmaceutical firms deploy medical science liaisons. Madrigal Pharmaceuticals leverages its specialized liver disease expertise to dominate the emerging thyroid hormone receptor-beta agonist segment. Novo Nordisk anchors its position through deep metabolic disease capabilities that extend into NAFLD comorbidity management. Gilead Sciences sustains relevance through extensive hepatology infrastructure built during its hepatitis C era.
Non-alcoholic fatty liver disease therapeutics comprise small-molecule drugs, biologics, and nutritional interventions targeting hepatic steatosis, inflammation, and fibrosis progression through metabolic, inflammatory, and fibrotic pathways, with primary purpose of preventing cirrhosis and hepatocellular carcinoma in patients without significant alcohol consumption. Pharmaceuticals command current revenue as the only approved drug category, while biologics represent the fastest-growing segment driven by GLP-1 receptor agonist expansion into liver indications. Oral delivery mode maintains volume leadership due to patient preference and chronic administration requirements, though injectable formats capture premium positioning in metabolic comorbidity settings.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for novel NAFLD agents, while WHO inclusion of fatty liver disease in global noncommunicable disease targets elevates national screening mandates. The EU MDR imposes stricter clinical evidence requirements on companion diagnostics that stratify treatment-responsive patient populations. Stakeholders must monitor how reimbursement authorities weight histologic endpoints against noninvasive biomarkers when determining access and pricing for next-generation therapies.
Market Dynamics
FDA breakthrough therapy designation for resmetirom has compressed Phase III-to-approval timelines from seven years to under four, forcing competitors to accelerate enrollment or abandon NASH-specific development programs entirely.
Growth Catalysts
- EMA PRIME Eligibility:European regulators fast-track novel fibrosis-modifying agents, compressing market access timelines for biologics targeting metabolic liver disease.
- GLP-1 Receptor Agonist Expansion:Semaglutide and tirzepatide demonstrate histologic improvement in steatohepatitis, pulling metabolic endocrinology practices into NAFLD diagnosis and treatment.
- Noninvasive Biomarker Validation:Vibration-controlled transient elastography and MRI-PDFF reduce reliance on liver biopsy, expanding treatable patient pools in primary care settings.
Market Restraints
- Histologic Endpoint Requirements:FDA mandates liver biopsy confirmation for NASH resolution, limiting trial participation to specialized hepatology centers with interventional radiology capacity.
- Reimbursement Uncertainty:CMS and commercial payers debate coverage for non-cirrhotic NAFLD therapies, creating formulary access gaps before fibrosis stage F3.
- Placebo Response Variability:High spontaneous resolution rates in early-stage disease inflate required trial sample sizes and extend enrollment periods.
Strategic Opportunities
- Pediatric NAFLD Indications:Adolescent metabolic syndrome prevalence creates unlabeled use demand for approved agents, pending dedicated pediatric trials.
- Combination Regimen Development:Pairing thyroid hormone receptor-beta agonists with FXR modulators or ACC inhibitors addresses multiple pathogenic pathways simultaneously.
- Companion Diagnostic Integration:FibroScan-AST score and MRE-based algorithms stratify treatment responders, enabling precision pricing models.
Industry Challenges
- Hepatologist Workforce Constraints:Fellowship program output lags NAFLD prevalence growth, forcing sponsors to train gastroenterologists and endocrinologists as principal investigators.
- Real-World Evidence Generation:Post-marketing studies must reconcile histologic trial endpoints with clinically accessible biomarkers to satisfy HTA bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market |
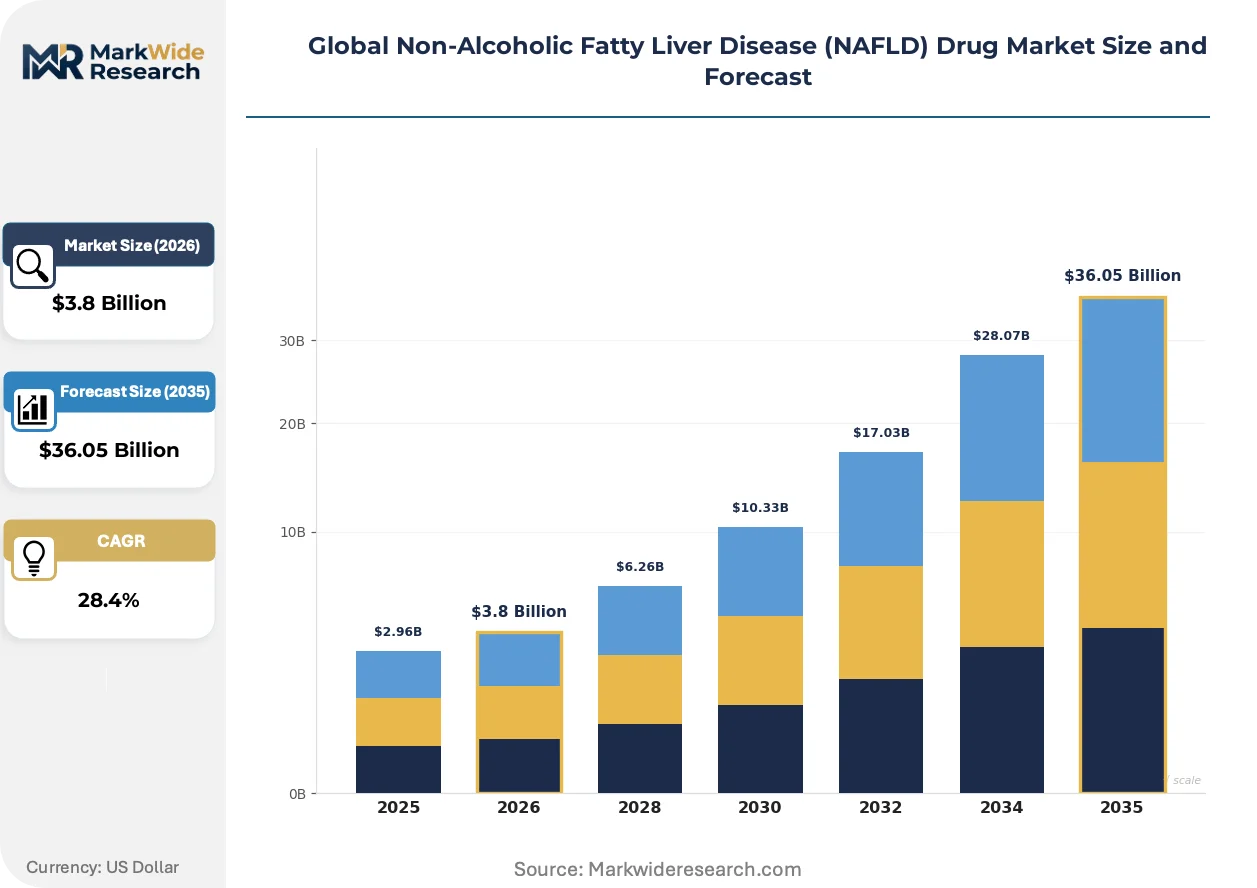
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.05 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologics, Nutraceuticals, Supplements Therapy Area: Metabolism Disorders, Hepatology, Gastroenterology, Endocrinology Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Madrigal Pharmaceuticals, Novo Nordisk, Intercept Pharmaceuticals, Inventiva, Gilead Sciences, AbbVie, Boehringer Ingelheim, Viking Therapeutics, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market Shifts & Advancements
Regulatory pressure on surrogate endpoints and payer demand for durable outcomes are reshaping how developers design Phase III programs and construct value demonstration frameworks.
Artificial intelligence-enabled histologic assessment is fragmenting traditional pathology workflows. PathAI and Paige algorithms score fibrosis and steatosis from whole-slide images, reducing inter-reader variability and accelerating trial reads. Contract research organizations adopt these platforms to compress database lock timelines, while academic medical centers deploy them for clinical quality assurance.
EU MDR imposes stricter clinical evidence requirements on in vitro diagnostics that stratify NAFLD treatment populations. Manufacturers of noninvasive fibrosis tests must now generate prospective outcome data linking biomarker thresholds to hard clinical endpoints. German and French notified bodies demand extended follow-up periods, delaying CE marking for novel diagnostic algorithms.
Patient advocacy groups now drive formulary negotiations directly with pharmacy benefit managers. The Fatty Liver Foundation and Global Liver Institute publish payer scorecards comparing access restrictions across national and regional health systems. United States employer-sponsored plans face intensified pressure to remove prior authorization barriers for metabolic liver disease therapies, particularly in self-insured populations with high diabetes comorbidity burdens.
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market Segmentation
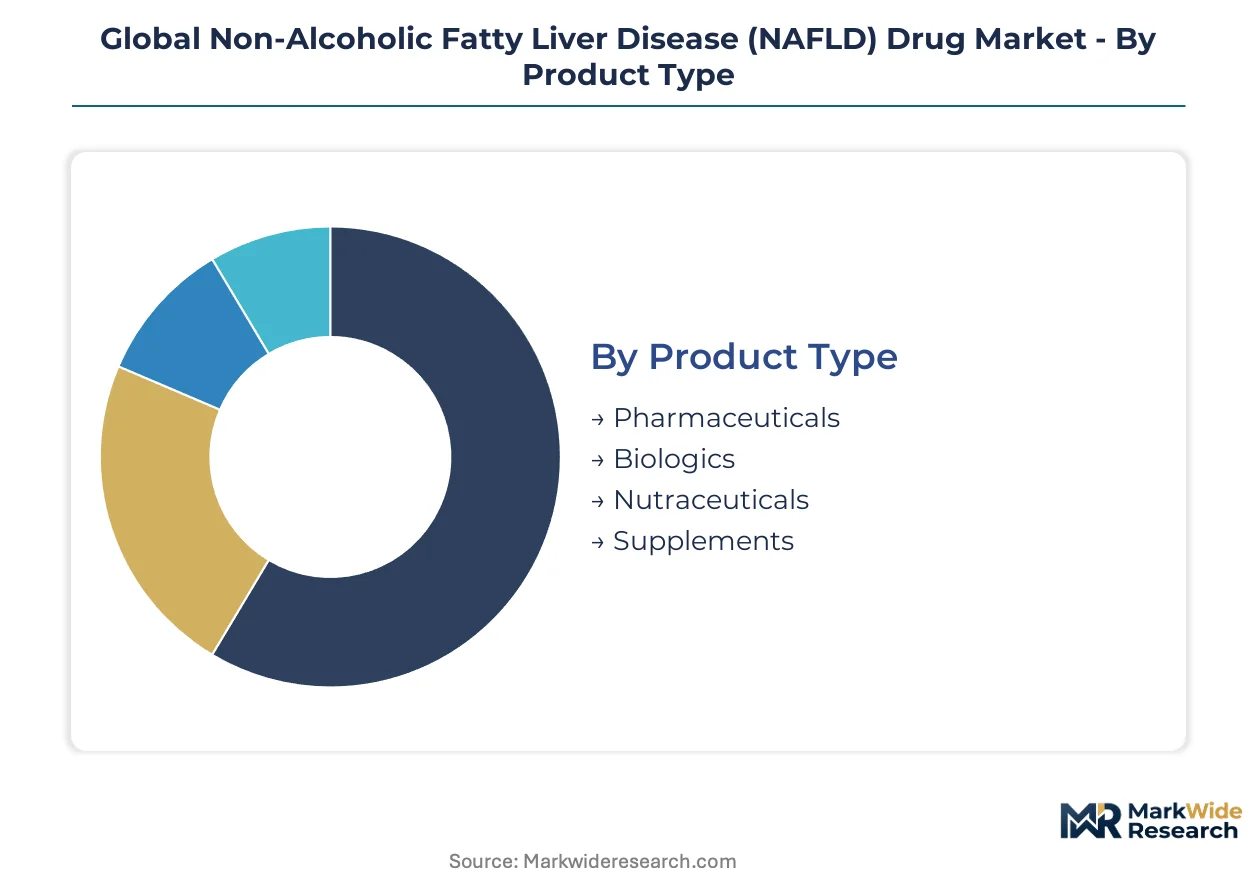
NAFLD drug segmentation reveals divergent regulatory pathways across product categories, with FDA breakthrough therapy designations favoring pharmaceuticals while EMA PRIME eligibility accelerates biologics. Therapy area fragmentation forces sponsors to navigate distinct reimbursement codes across hepatology and endocrinology practices. Delivery mode selection increasingly determines patient pool access and pricing power.
Product Type:
FDA accelerated approval pathways and EMA PRIME eligibility create asymmetric development timelines across molecular categories, compressing timelines for small-molecule pharmaceuticals while imposing extended immunogenicity surveillance on biologics.
- Pharmaceuticals:Small-molecule compounds including thyroid hormone receptor-beta agonists and FXR modulators dominate current revenue. Hepatology clinics in the United States and Germany concentrate procurement of resmetirom-class agents, though histologic endpoint requirements limit prescriber base to specialized centers with interventional radiology capacity.
- Biologics:GLP-1 receptor agonists and monoclonal antibodies targeting inflammatory fibrotic pathways represent the fastest-expanding segment. Novo Nordisk's semaglutide and Eli Lilly's tirzepatide pull metabolic endocrinology practices into NAFLD diagnosis, with demand concentrating in United States employer-sponsored plans managing diabetes comorbidity burdens.
- Nutraceuticals:Vitamin E and omega-3 formulations occupy over-the-counter channels with limited prescriber involvement.
- Supplements:Hepatoprotective botanical extracts and amino acid complexes compete outside formal reimbursement frameworks.
Pharmaceuticals handle the majority of current prescription volume; biologics are climbing the fastest on share expansion into metabolic comorbidity management.
Therapy Area:
Cost tier differentiation separates premium-priced hepatology-specialized agents from standard metabolic disease management protocols, with gastroenterology practices occupying intermediate reimbursement positioning.
- Metabolism Disorders:Endocrinology practices in the United States and United Kingdom drive GLP-1 receptor agonist adoption for NAFLD with concurrent diabetes, leveraging existing metabolic disease infrastructure and favorable formulary placement for semaglutide-class therapies.
- Hepatology:Dedicated liver disease centers in Germany, France, and the United States concentrate access to resmetirom and emerging fibrosis-modifying agents, with interventional radiology capacity determining site selection for biopsy-mandated trials.
- Gastroenterology:General GI practices bridge primary care and specialized hepatology, managing early-stage disease before fibrosis progression.
- Endocrinology:Metabolic syndrome management protocols increasingly incorporate liver biomarker surveillance, expanding treatable patient identification.
Hepatology commands premium pricing; metabolism disorders is gaining share fastest as GLP-1 expansion redefines treatment entry points.
Delivery Mode:
Application setting determines delivery preference, with oral formats dominating chronic outpatient management while injectable agents capture hospital-based metabolic comorbidity protocols.
- Oral:Once-daily tablet formulations of resmetirom and emerging FXR modulators align with patient preference for chronic administration. Primary care settings in the United States and United Kingdom favor oral agents for early-stage disease management where compliance determines real-world effectiveness.
- Injectable:Subcutaneous GLP-1 receptor agonists require weekly or biweekly administration, with tirzepatide and semaglutide formulations penetrating employer-sponsored plans and United Kingdom NHS metabolic disease pathways where nursing support infrastructure exists.
- Transdermal:Patch-based delivery remains investigational for NAFLD-specific indications with limited commercial presence.
- Inhalation:No approved inhaled therapies exist; research-stage programs target hepatic first-pass avoidance.
Oral delivery maintains volume leadership; injectable formats are expanding most quickly into metabolic comorbidity settings.
End User:
Customer type fragmentation reflects disease stage progression, with hospitals managing advanced fibrosis and compensated cirrhosis while homecare and retail channels capture maintenance therapy.
- Hospitals:Academic medical centers in the United States, Germany, and Japan concentrate interventional radiology capacity for liver biopsy and advanced fibrosis management. Mayo Clinic, Charité Berlin, and Tokyo University Hospital anchor Phase III trial enrollment and post-marketing surveillance for breakthrough-designated agents.
- Clinics:Hepatology and gastroenterology practices in the United States and France deploy vibration-controlled transient elastography for point-of-care fibrosis staging, expanding treatable pools beyond biopsy-limited academic centers.
- Homecare:Self-administered injectable therapies penetrate employer-sponsored plans with diabetes management infrastructure.
- Pharmacies:Retail channels dispense oral agents with prior authorization requirements varying across United States commercial payers and United Kingdom CCG formularies.
Hospitals concentrate advanced disease management; clinics are capturing share fastest as noninvasive biomarker validation expands treatable pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designations for resmetirom-class agents have compressed United States approval timelines, forcing European and Asian regulators to accelerate their own assessment frameworks for metabolic liver disease therapies.
United States
Employer-sponsored health plans with high diabetes comorbidity burdens drive GLP-1 receptor agonist demand for NAFLD. CMS formulary debates over non-cirrhotic coverage create access gaps before fibrosis stage F3. Mayo Clinic, Cleveland Clinic, and academic medical centers in Boston anchor Phase III trial enrollment for thyroid hormone receptor-beta agonists.
Germany
Charité Berlin and university hospitals in Munich concentrate interventional radiology capacity for liver biopsy-mandated trials. EMA PRIME eligibility compresses market access timelines for novel fibrosis-modifying agents. The country's statutory health insurance system debates histologic versus noninvasive biomarker reimbursement for emerging therapies.
Japan
PMDA accelerated approval pathways for NASH therapies align with METI industrial policy supporting domestic pharmaceutical innovation. Tokyo University Hospital and Osaka medical centers deploy vibration-controlled transient elastography for point-of-care fibrosis staging. Aging population metabolic syndrome prevalence expands treatable patient pools beyond specialized hepatology centers.
United Kingdom
NHS metabolic disease pathways incorporate GLP-1 receptor agonists for NAFLD with concurrent diabetes, leveraging existing endocrinology infrastructure. NICE technology appraisals weight histologic endpoints against real-world biomarker evidence when determining access. London and Manchester academic centers train gastroenterologists as principal investigators to address hepatologist workforce constraints.
France
ANSM fast-track procedures for breakthrough-designated liver disease agents compress regulatory review periods. Paris and Lyon hepatology practices deploy MRI-PDFF for noninvasive disease monitoring, expanding treatable pools beyond biopsy-limited academic sites. The country's national health insurance system evaluates companion diagnostic integration for precision treatment stratification.
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialized biotech firms driving novel mechanism development while large-cap pharmaceutical companies leverage metabolic disease infrastructure for commercial scale. The market structure consolidates around three strategic tiers: thyroid hormone receptor-beta specialists, GLP-1 receptor agonist incumbents with metabolic franchise extensions, and diversified hepatology players repurposing hepatitis C-era capabilities. Dominant competitive moves include strategic partnerships for combination regimen development and geographic expansion through EMA PRIME and FDA breakthrough therapy pathway exploitation.
Within the specialized biotech tier, Madrigal Pharmaceuticals and Viking Therapeutics exemplify focused mechanism development, while Novo Nordisk anchors the metabolic incumbent position through endocrinology franchise extension into liver indications.
| Leading Market Players |
|---|
| Madrigal Pharmaceuticals |
| Novo Nordisk |
| Intercept Pharmaceuticals |
| Inventiva |
| Gilead Sciences |
| AbbVie |
| Boehringer Ingelheim |
| Viking Therapeutics |
| Roche |
| Others |
Supply & Pricing Matrix
FDA breakthrough therapy designation and EMA PRIME eligibility simultaneously gate supply-side qualification for contract manufacturers and drive price differentiation between accelerated-pathway agents and standard-review therapeutics in the NAFLD market. These regulatory fast-tracks concentrate pricing power with sponsors that secure early approval, while CMOs must invest in dedicated hepatology manufacturing suites to serve this high-value segment.
Pricing Analysis
United States hepatology centers command 40-60% price premiums over European metabolic disease pathways for equivalent fibrosis-stage therapies, reflecting employer-sponsored plan generosity and prior authorization density. Three-tier pricing structure across premium biologics, standard small-molecule pharmaceuticals, and economy-positioned nutraceuticals segments the market by reimbursement code and prescriber specialty. Cost compression in oral resmetirom-class agents is intensifying as Novo Nordisk's semaglutide pulls metabolic endocrinology practices into NAFLD diagnosis with bundled diabetes-liver management protocols. Primary care settings exhibit highest price sensitivity due to formulary tier placement uncertainties, while academic medical centers with interventional radiology capacity demonstrate lowest sensitivity given restricted site selection for biopsy-mandated trials.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for active pharmaceutical ingredients sourced from Indian and Chinese API manufacturers serving the NAFLD drug pipeline. Finished dose formulation concentrates in United States, Germany, and Switzerland, with Swiss contract manufacturers drawing from Italian chemical intermediate suppliers for thyroid hormone receptor-beta agonist synthesis. Single-source vulnerability pervades the GLP-1 receptor agonist peptide supply base, where Novo Nordisk's captive production in Denmark creates dependency concentration. Distribution runs through specialty pharmacy channels for injectable metabolic comorbidity therapies, while oral agents flow through retail pharmacy networks with cold-chain requirements limited to biologic stability windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NAFLD therapeutics market rewards sponsors that control hepatologist access and interventional radiology site relationships, with fellowship program output lagging prevalence growth by a widening margin. Pipeline positioning depends on securing principal investigator networks before competitor enrollment acceleration compresses trial timelines.
For Market Incumbents: Compound hepatology infrastructure advantages by acquiring vibration-controlled transient elastography platform operators and training gastroenterologists as trial investigators to bypass workforce constraints. Defend against GLP-1 receptor agonist displacement by securing FDA combination therapy designations that anchor small-molecule agents within metabolic comorbidity protocols. Prioritize backward integration into companion diagnostic development to capture precision pricing premiums from FibroScan-AST score stratification. For New Entrants and Emerging Players: Anchor in pediatric NAFLD indications where regulatory exclusivity timelines extend and prescriber competition remains sparse relative to adult NASH saturation. Target United Kingdom and France metabolic disease pathways where NHS and ANSM fast-track procedures compress market access timelines for novel mechanisms. Pursue licensing arrangements with established GLP-1 manufacturers to embed fibrosis-modifying agents within existing endocrinology detailing infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing as multi-product cell line requirements and extended immunogenicity surveillance extend facility validation timelines. Five-to-ten year viability favors sponsors with diversified mechanism portfolios spanning thyroid hormone receptor-beta, FXR, and ACC inhibition rather than single-target dependencies. Acquisition target archetype: specialized hepatology CROs with validated AI-enabled histology platforms and established academic medical center site networks. Signal to monitor: CMS coverage determinations for non-cirrhotic NAFLD therapies as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | AI-enabled histology platforms from PathAI reduce inter-reader variability and compress database lock timelines for Phase III programs. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation for resmetirom-class agents compresses Phase III-to-approval timelines below four years. |
| Licensing Agreement | Combination regimen partnerships pair thyroid hormone receptor-beta agonists with FXR modulators to address multiple pathogenic pathways. |
| Manufacturing Scale-Up | Dedicated hepatology manufacturing suites at contract manufacturers qualify for accelerated-pathway therapeutics production. |
| Pipeline Diversification | Pediatric NAFLD indications create unlabeled use demand and extend regulatory exclusivity timelines beyond adult NASH saturation. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary fieldwork captured trial enrollment dynamics, site selection criteria, and payer access negotiation patterns across United States, German, and United Kingdom health systems. Secondary validation drew from CMS Medicare data, GPO contracts, and hospital procurement databases to triangulate bottom-up prescription volume estimates against top-down market sizing.
Variance decomposition across treatment line, dosage form, administration route, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from patient prevalence modeling, therapy penetration assumptions, and price trajectory analysis across oral and injectable delivery modes. Forecast inputs incorporated hepatologist workforce projections, noninvasive biomarker validation timelines, and companion diagnostic adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable FDA breakthrough therapy pathway availability and continued GLP-1 receptor agonist histologic endpoint demonstration; material deviation in reimbursement policy or regulatory endpoint requirements would warrant model refresh. Forecasts reflect epidemiological prevalence trajectories, prescriber specialty expansion rates, and pricing power sustainability in metabolic comorbidity settings. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market