
 Global Graves Disease Market | 2026-2036
Global Graves Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graves Disease Market Foresight
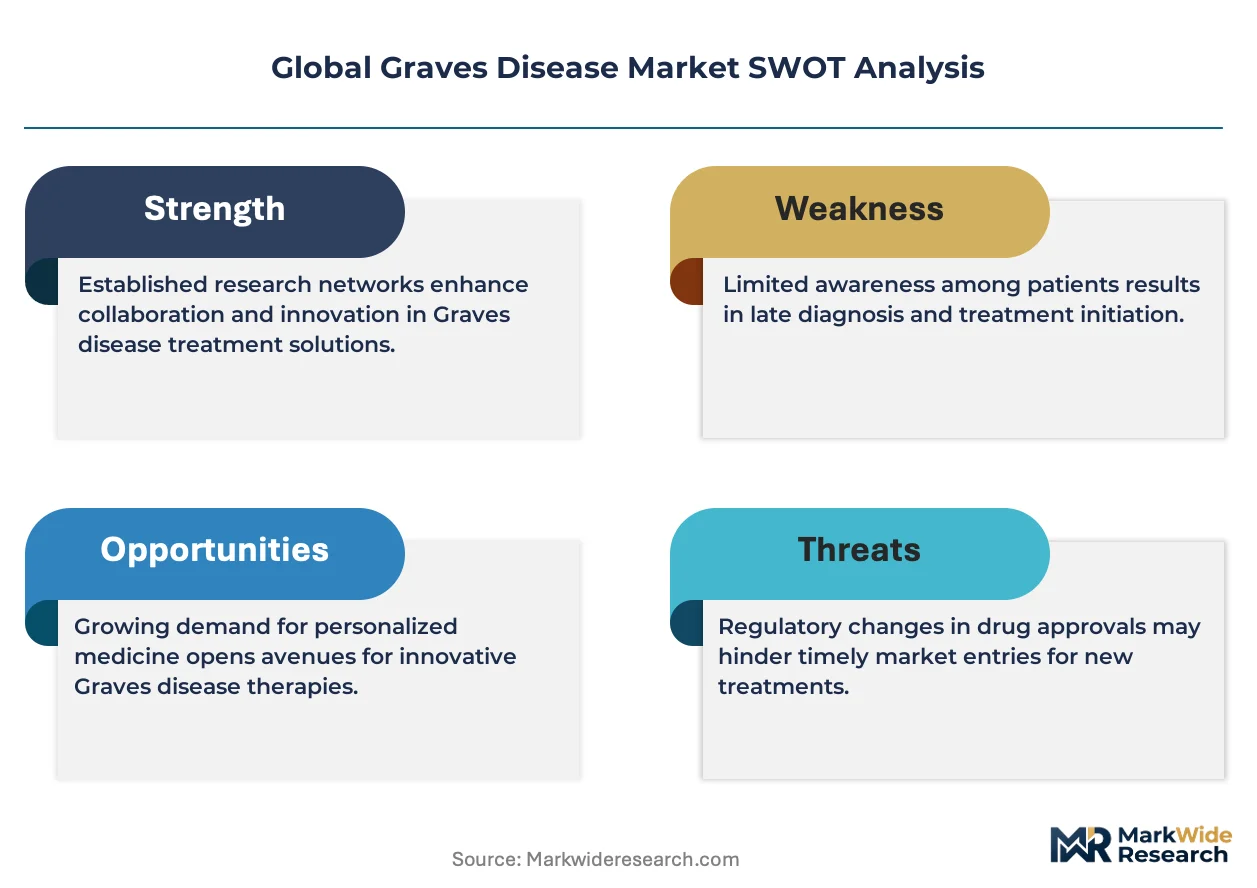
A shortage of endocrinologists trained in complex autoimmune thyroid management is unwinding access bottlenecks across major markets. Abbott Laboratories leverages its diagnostic platform dominance to anchor thyroid function testing workflows in hospital networks. F. Hoffmann-La Roche AG sustains competitive positioning through specialized immunoassay portfolios that clinicians rely upon for TSI antibody detection. Pfizer Inc. competes in the symptomatic management layer with established beta-blocker franchises that physicians prescribe alongside disease-modifying therapy.
Graves disease constitutes an autoimmune disorder characterized by thyrotropin receptor antibody production that stimulates excessive thyroid hormone synthesis, typically presenting with hyperthyroidism, orbitopathy, and dermopathy. The condition demands precise TSH receptor antibody quantification and radioactive iodine uptake assessment to guide therapeutic selection between antithyroid pharmacotherapy, radioablation, and surgical intervention. Antithyroid drugs and beta blockers occupy the mature volume base where generic competition has compressed margins, while radioactive iodine therapy commands premium positioning due to specialized nuclear medicine infrastructure requirements and radioisotope supply chain controls. Thyroidectomy segments concentrate margin pools in tertiary centers where endocrine surgeon density and postoperative calcium management protocols determine outcomes.
The FDA oversees biologics licensing for thyroid eye disease through its orphan drug and breakthrough therapy pathways, while the EMA's centralized procedure governs market access across EU member states with divergent health technology assessment timelines. Japan's PMDA maintains distinct clinical trial requirements for radioisotope therapies that manufacturers must navigate for reimbursement listing under the national health insurance system. Stakeholders must monitor evolving HTA body methodologies for ophthalmic biologics and radioiodine manufacturing capacity constraints as demand for definitive therapy options expands.
Market Dynamics
The Graves disease market pivots on biologics displacement of conventional antithyroid pharmacotherapy, with teprotumumab-class therapies for thyroid eye disease capturing margin pools previously absorbed by symptomatic management. This therapeutic shift compresses volume in mature drug segments while concentrating value in infusion centers and specialty pharmacy networks.
Growth Catalysts
- Orphan drug incentives:The FDA's orphan drug designation pathway accelerates biologics development for thyroid eye disease, reducing clinical trial burden and extending exclusivity periods for qualifying therapies.
- Diagnostic platform consolidation:Hospital networks are integrating TSI antibody quantification into automated immunoassay workflows, expanding testing access and shortening time-to-diagnosis in tertiary centers.
- Radioisotope supply controls:Specialized nuclear medicine infrastructure requirements for radioactive iodine therapy create defensive moats around established treatment centers in the United States, Germany, and Japan.
Market Restraints
- Molybdenum-99 supply concentration:Radioactive iodine therapy depends on aging research reactors in Canada, the Netherlands, and South Africa, creating single-point-of-failure risk for definitive treatment availability.
- Endocrinologist density gaps:The American Association of Clinical Endocrinology documents persistent shortages of autoimmune thyroid specialists across rural and exurban counties, throttling patient throughput.
- Biologics manufacturing complexity:Monoclonal antibody production for thyroid eye disease requires mammalian cell culture capacity that concentrates among contract manufacturers in Switzerland and Ireland.
Strategic Opportunities
- Subcutaneous formulation development:IV-to-subcutaneous conversion for teprotumumab-class therapies would shift administration from infusion centers to home health settings, expanding addressable patient populations.
- India's underserved diagnosis gap:Thyroid function testing penetration remains below 15% in tier-2 and tier-3 Indian cities, presenting whitespace for diagnostic platform deployment under CDSCO-regulated pathways.
- EMA's centralized procedure harmonization:Converging health technology assessment timelines across EU member states is compressing market access delays for ophthalmic biologics in Germany, France, and Italy.
Industry Challenges
- Postoperative calcium management protocols:Thyroidectomy outcomes depend on parathyroid preservation expertise that concentrates in high-volume endocrine surgery centers, limiting safe expansion of surgical capacity.
- Radioiodine waste disposal compliance:Nuclear medicine departments face escalating costs for radioactive waste handling under tightening EPA and state-level environmental regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graves Disease Market |
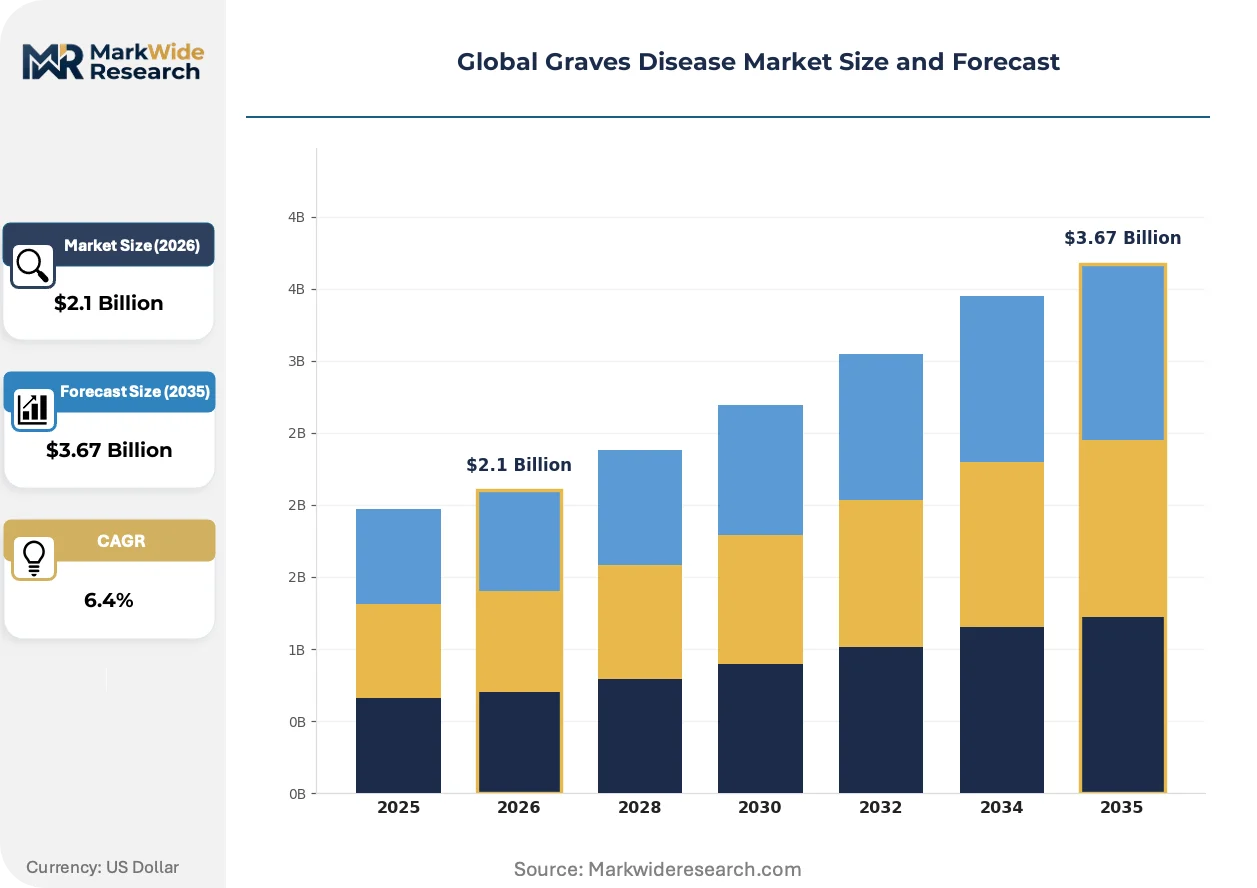
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antithyroid Drugs, Beta Blockers, Radioactive Iodine, Thyroidectomy Therapy Area: Hyperthyroidism, Thyroid Eye Disease, Goiter Management, Thyroid Nodules End User: Endocrinology Clinics, Specialized Hospitals, Outpatient Centers, Diagnostic Laboratories Delivery Mode: Oral Medication, Injectable Therapy, Radioisotope Therapy, Surgical Intervention |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Pfizer Inc., Horizon Therapeutics, Immunovant Inc., AbbVie Inc., Novartis AG, Sanofi, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graves Disease Market Shifts & Advancements
Point-of-care diagnostic technologies and subcutaneous biologics delivery are compressing treatment timelines and redistributing care from hospitals to ambulatory settings. These shifts demand reconfiguration of reimbursement and supply chain infrastructure.
Handheld TSH receptor antibody analyzers are miniaturizing laboratory-grade immunoassay performance into clinic-deployable formats. Endocrinology practices in the United States and Germany are piloting these devices to accelerate diagnostic confirmation during initial patient visits. This technology is miniaturizing the traditional referral-to-laboratory workflow, compressing time-to-treatment initiation from weeks to days and reducing patient leakage from specialist practices.
The EMA's Medical Device Regulation (MDR) is tightening clinical evidence requirements for in-vitro diagnostic devices used in autoimmune thyroid assessment. Manufacturers must now submit prospective performance studies for novel antibody quantification platforms, extending time-to-market by 18-24 months. German and French notified bodies are prioritizing review resources toward high-volume endocrine diagnostics, creating regulatory queue advantages for established immunoassay portfolios.
Hospital procurement committees are unbundling diagnostic testing from therapeutic decision support, creating separate vendor selection processes for TSI quantification versus treatment pathway algorithms. This fragmentation is disrupting integrated solution sales models that previously bundled Abbott and Roche platforms with clinical decision software. The United States exhibits the most pronounced unbundling, with IDN procurement offices demanding modular contracting for laboratory and clinical informatics components.
Global Graves Disease Market Segmentation
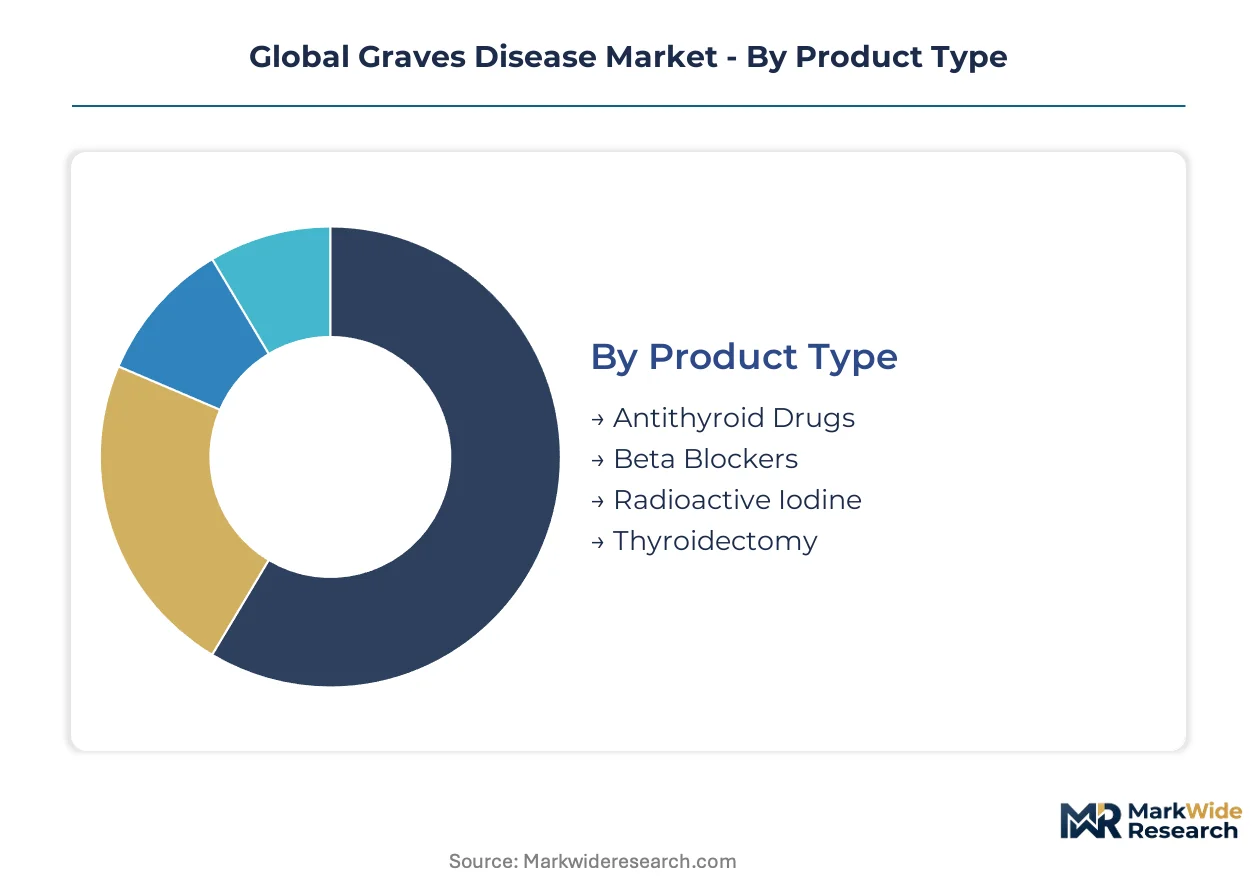
Segmentation in the Graves disease market reveals how value migrates from commoditized symptomatic management toward definitive therapy modalities and specialized diagnostic workflows. Understanding these segment boundaries helps stakeholders identify where pricing power endures versus where generic competition has eroded margins.
Product Type:
Margin pools concentrate in definitive therapy modalities that require specialized infrastructure or exclusive supply chains, while symptomatic management segments face relentless generic compression.
- Antithyroid Drugs:First-line pharmacotherapy comprising thionamide compounds that inhibit thyroid hormone synthesis through TPO enzyme blockade. Demand concentrates in Germany and Japan where endocrinologist density supports prolonged medical management protocols, though generic methimazole and propylthiouracil have collapsed price points.
- Radioactive Iodine:Definitive ablative therapy utilizing iodine-131 isotope uptake to destroy hyperfunctioning thyroid tissue. The United States and Germany anchor demand due to mature nuclear medicine infrastructure and favorable reimbursement for outpatient radioiodine administration under CMS and G-DRG frameworks.
- Beta Blockers:Symptomatic control agents addressing adrenergic hyperactivity without modifying disease course. Propranolol and atenolol prescriptions dominate volume but command minimal margin in saturated cardiovascular markets.
- Thyroidectomy:Surgical removal of thyroid gland requiring endocrine surgeon expertise and intraoperative parathyroid monitoring. Tertiary centers in the United States and Japan capture premium pricing through bundled episode payments.
The dominant share belongs to antithyroid drugs, while radioactive iodine is closing the gap fastest as definitive therapy preferences strengthen.
Therapy Area:
Application intensity varies by complication severity, with ophthalmic manifestations driving biologics investment while uncomplicated hyperthyroidism sustains mature drug volumes.
- Thyroid Eye Disease:Autoimmune orbital inflammation characterized by extraocular muscle enlargement and adipose tissue expansion behind the globe. The United States and Germany concentrate demand for teprotumumab-class biologics approved under FDA orphan drug and EMA centralized pathways.
- Hyperthyroidism:Core disease manifestation of excessive thyroid hormone production manifesting in metabolic, cardiovascular, and neuropsychiatric symptoms. Volume spreads across all major markets with treatment selection varying by patient age and comorbidity profile.
- Goiter Management:Enlarged thyroid gland therapy addressing compressive symptoms and cosmetic concerns. Japan maintains distinct surgical thresholds under PMDA guidelines compared to Western conservative management preferences.
- Thyroid Nodules:Focal thyroid lesions requiring cytological evaluation to exclude malignancy before Graves-specific therapy. Diagnostic laboratories in the United States and Germany drive ultrasound-guided fine needle aspiration volumes.
Hyperthyroidism commands the largest patient population, though thyroid eye disease is expanding most quickly through biologics penetration.
End User:
Customer type determines procurement sophistication, with hospital networks leveraging integrated diagnostics-therapeutics contracts versus independent clinics negotiating single-service agreements.
- Endocrinology Clinics:Specialist practices managing complex autoimmune thyroid cases with longitudinal care protocols. The United States and Germany exhibit highest clinic density, with American Academy of Clinical Endocrinology membership concentrated in urban corridors.
- Specialized Hospitals:Tertiary centers housing nuclear medicine departments and endocrine surgery divisions. Germany's university hospitals and Japan's national centers anchor radioiodine and thyroidectomy capacity.
- Outpatient Centers:Ambulatory facilities delivering infusion therapy and same-day surgical procedures. United States freestanding surgery centers are capturing thyroidectomy volume from inpatient settings.
- Diagnostic Laboratories:Centralized testing hubs processing TSI antibody quantification and thyroid function panels. Abbott and Roche platforms dominate hospital network contracts in the United States and Germany.
Specialized hospitals retain the dominant share, while outpatient centers are climbing the fastest as ambulatory surgical migration accelerates.
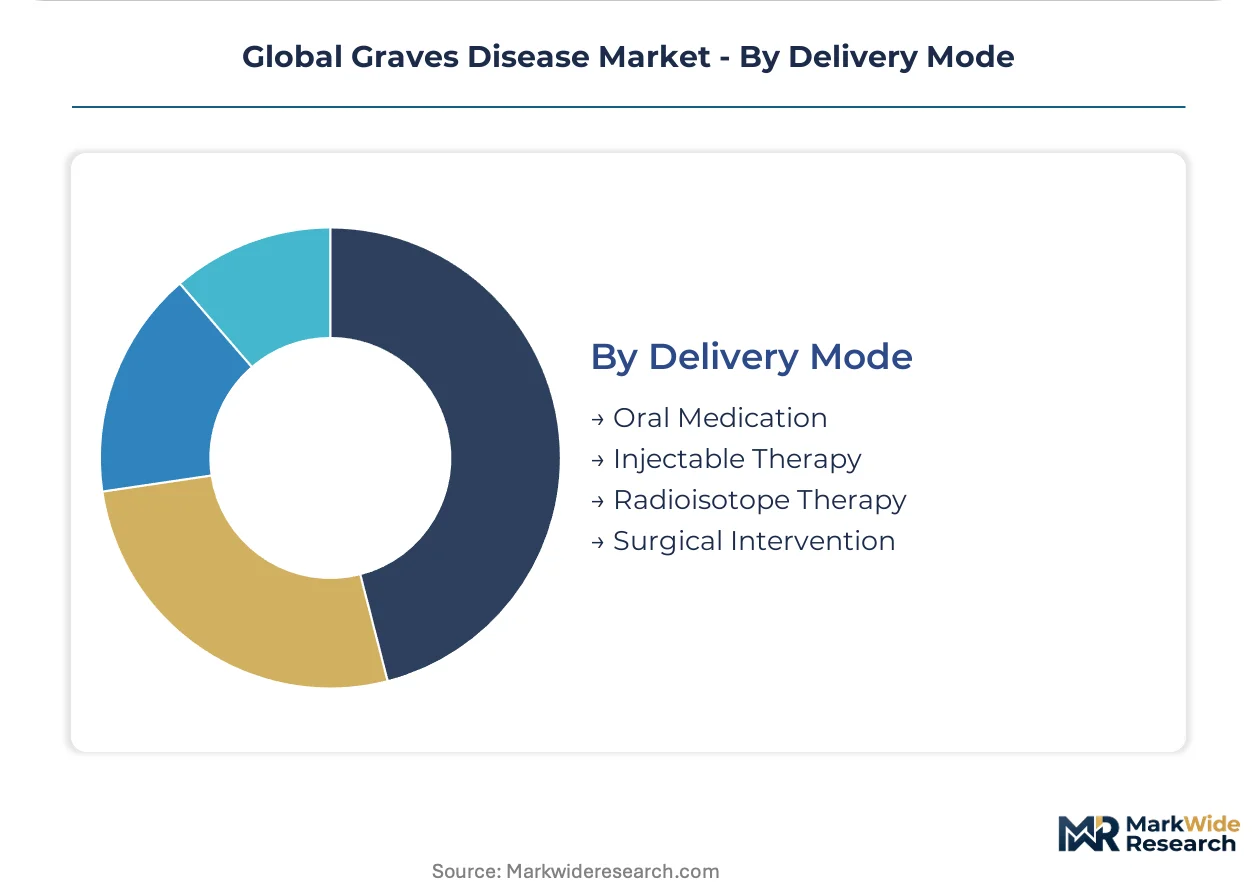
Delivery Mode:
Administration format shapes reimbursement coding and site-of-care economics, with infusion and surgical modalities commanding facility fees that oral generics cannot capture.
- Injectable Therapy:Parenteral biologics delivery for thyroid eye disease requiring infusion center infrastructure and specialty pharmacy coordination. The United States concentrates teprotumumab administration under Medicare Part B and commercial medical benefit coverage.
- Radioisotope Therapy:Oral iodine-131 administration with radioactive decay managed through nuclear medicine protocols. Germany and Japan maintain stringent PMDA and federal radiation safety requirements governing outpatient release criteria.
- Oral Medication:Tablet and capsule formulations for antithyroid drugs and beta blockers dispensed through retail pharmacy channels. Generic substitution laws in the United States and Germany drive pharmacy benefit manager formulary placement.
- Surgical Intervention:Operative thyroid removal requiring anesthesia services and inpatient or ambulatory surgical facility certification. Japan's surgical volume concentrates in designated cancer care hospitals under Ministry of Health, Labour and Welfare designation.
Oral medication holds the dominant share, though injectable therapy is gaining share fastest as biologics displace conventional ophthalmic management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes Graves disease therapies through a definitive-treatment preference, favoring radioactive iodine ablation and surgical intervention over prolonged pharmacotherapy, while Germany and Japan sustain higher antithyroid drug utilization rates under specialist-guided medical management protocols.
United States
CMS reimbursement frameworks favor outpatient radioiodine administration and bundled episode payments for thyroidectomy, concentrating definitive therapy volume in tertiary centers. The FDA's orphan drug designation pathway accelerates biologics development for thyroid eye disease. Major endocrine surgery clusters operate in Houston, Boston, and the Cleveland Clinic corridor.
Germany
University hospital networks anchor radioiodine capacity under G-DRG reimbursement, while endocrinologist density supports prolonged antithyroid drug protocols. The EMA's centralized procedure governs market access for ophthalmic biologics, with German HTA bodies influencing EU pricing benchmarks. Munich and Berlin house the highest concentration of nuclear medicine departments.
Japan
PMDA maintains distinct clinical trial requirements for radioisotope therapies, with surgical volume concentrating in designated cancer care hospitals under Ministry of Health, Labour and Welfare designation. National health insurance listing determines reimbursement for antithyroid drugs. Tokyo and Osaka metropolitan areas host the dominant endocrine surgery capacity.
United Kingdom
NICE technology appraisals govern biologics access for thyroid eye disease, creating variable availability across integrated care systems. Specialist referral networks concentrate Graves disease management in London, Manchester, and Birmingham teaching hospitals. The MHRA operates post-Brexit regulatory pathways parallel to EMA procedures.
India
Thyroid function testing penetration remains below 15% in tier-2 and tier-3 cities, presenting diagnostic whitespace under CDSCO-regulated pathways. Endocrinologist shortages in rural states throttle patient throughput. Mumbai and Delhi-NCR anchor the limited nuclear medicine infrastructure for radioiodine therapy.
Global Graves Disease Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with diagnostic platform dominance and biologics manufacturing capability determining competitive position. The market structure concentrates around three archetypes: immunoassay platform holders anchoring diagnostic workflows, biopharmaceutical developers capturing ophthalmic biologics value, and generic manufacturers serving commoditized antithyroid drug volume. Consolidation pressure operates through diagnostic-therapeutic bundling contracts and specialty pharmacy network exclusivity arrangements.
Within the diagnostic platform tier, Abbott Laboratories and F. Hoffmann-La Roche AG exemplify integrated leaders whose automated immunoassay workflows anchor TSI antibody quantification in hospital networks. Among biopharmaceutical developers, Horizon Therapeutics occupies a position representing the teprotumumab-class therapy segment that is displacing conventional ophthalmic management. Pfizer Inc. sits within the symptomatic control archetype, with established beta-blocker franchises prescribed alongside disease-modifying interventions.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Pfizer Inc. |
| Horizon Therapeutics |
| Immunovant Inc. |
| AbbVie Inc. |
| Novartis AG |
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| Others |
Supply & Pricing Matrix
FDA orphan drug designation and EMA centralized approval pathways gate both supply qualification and price differentiation simultaneously, concentrating premium positioning in therapies that clear regulatory exclusivity while generic antithyroid drugs compete on pharmacy benefit manager formularies.
Pricing Analysis
Long-term offtake contracts dominate biologics procurement for thyroid eye disease, with infusion centers negotiating bundled episode payments that capture facility fees alongside drug acquisition costs. Price differentiation rests on orphan drug exclusivity periods versus generic methimazole availability, with beta-blocker segments showing highest price sensitivity due to cardiovascular market saturation. Pricing pressure stems from pharmacy benefit manager consolidation in the United States, compressing margins in oral medication tiers.
Supply Chain Analysis
Inventory lead times for iodine-131 radioisotopes extend 4-6 weeks due to molybdenum-99 decay chains and reactor scheduling constraints in Canada and the Netherlands. Raw material dependencies center on technetium-99m generators, monoclonal antibody cell culture media, and thionamide active pharmaceutical ingredients sourced from India and China. Single-source vulnerability concentrates in aging research reactors, while distribution runs through hospital-based nuclear medicine pharmacies and specialty pharmacy networks for biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Graves disease market sits in a cyclical recovery phase as biologics penetration for thyroid eye disease displaces prior symptomatic management volumes, with orphan drug incentives and diagnostic platform consolidation driving reinvestment.
For Market Incumbents: Fortify diagnostic platform anchoring in United States hospital networks by deepening immunoassay workflow integration and securing exclusive TSI antibody quantification contracts. Expand mammalian cell culture capacity in Switzerland and Ireland ahead of teprotumumab-class demand inflection. Counter generic erosion in antithyroid segments through backward integration into active pharmaceutical ingredient supply. For New Entrants and Emerging Players: Differentiate on subcutaneous formulation development for ophthalmic biologics, converting infusion center dependence to home health administration. Target India's tier-2 and tier-3 diagnostic whitespace through CDSCO-regulated point-of-care TSH receptor antibody platforms. Pursue German university hospital procurement committees with modular diagnostic-therapeutic unbundling strategies. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing sub-segments as mammalian cell culture capacity tightens. Long-term viability favors platforms with diagnostic-therapeutic integration capabilities and orphan drug exclusivity positions. Monitor EMA Medical Device Regulation queue lengths for novel antibody quantification platforms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Biologics Conversion | Shifts administration from infusion centers to home health, expanding addressable populations. |
| Diagnostic Platform Integration | Abbott and Roche anchor TSI antibody workflows in United States hospital networks. |
| Orphan Drug Exclusivity Extension | FDA designation accelerates development timelines for thyroid eye disease therapies. |
| Radioisotope Supply Security | Reactor diversification in Canada, Netherlands, and South Africa mitigates single-point failure. |
| EMA Centralized Procedure Harmonization | Converging HTA timelines compress market access delays in Germany and France. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with endocrinologists, nuclear medicine physicians, hospital procurement managers, and specialty pharmacy directors; and secondary validation through FDA orphan drug filings, EMA centralized procedure submissions, ClinicalTrials.gov protocols, and CMS reimbursement databases. Bottom-up patient volume estimates by therapy modality triangulated against top-down pharmaceutical revenue disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions including therapy area, delivery mode, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for biologics penetration curves and diagnostic testing expansion rates. Forecast inputs incorporated radioisotope supply capacity constraints and endocrinologist density projections by metropolitan area.
The analysis sits within stated boundaries; outcomes outside continued orphan drug incentive structures or stable molybdenum-99 reactor operations would require recalibration. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market