
 Global Cancer Immunotherapies Market | 2026-2036
Global Cancer Immunotherapies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Immunotherapies Market Foresight
Next-generation bispecific antibody standards are unwinding legacy monoclonal benchmarks across the Global Cancer Immunotherapies Market. Merck & Co., Inc. leverages its pembrolizumab franchise to dominate PD-1 combination protocols across solid tumor indications. Bristol-Myers Squibb Company anchors its portfolio with dual immunotherapy regimens that integrate CTLA-4 and PD-1 blockade mechanisms. F. Hoffmann-La Roche Ltd specializes in personalized neoantigen strategies that extend its oncology pipeline into novel target spaces.
Cancer immunotherapies comprise biologic agents that harness or restore immune system recognition and destruction of malignant cells through engineered receptor binding, cytokine modulation, or adoptive cellular reprogramming. These therapeutics functionally require cold-chain distribution, sterile parenteral manufacturing, and batch-level potency validation to preserve T-cell engagement capacity and cytokine stability. Checkpoint inhibitors occupy the dominant margin pool within the product type dimension, while adoptive cell transfer represents the fastest-growing segment as manufacturing automation reduces CAR-T production cycle times. The therapy area structure shows lung cancer commanding the largest absolute patient volume, with melanoma retaining premium pricing power due to durable complete response rates in metastatic settings.
The FDA accelerates market entry through breakthrough therapy designation and priority review vouchers, while the EMA's PRIME scheme channels early scientific dialogue toward conditional marketing authorization for innovative immunotherapy modalities. WHO prequalification standards and ICH Q5D guidelines on cell substrate characterization impose upstream manufacturing rigor that filters out undercapitalized developers. Stakeholders must monitor evolving pharmacovigilance requirements for cytokine release syndrome reporting and long-term secondary malignancy surveillance as treatment durations extend across earlier disease stages.
Market Dynamics
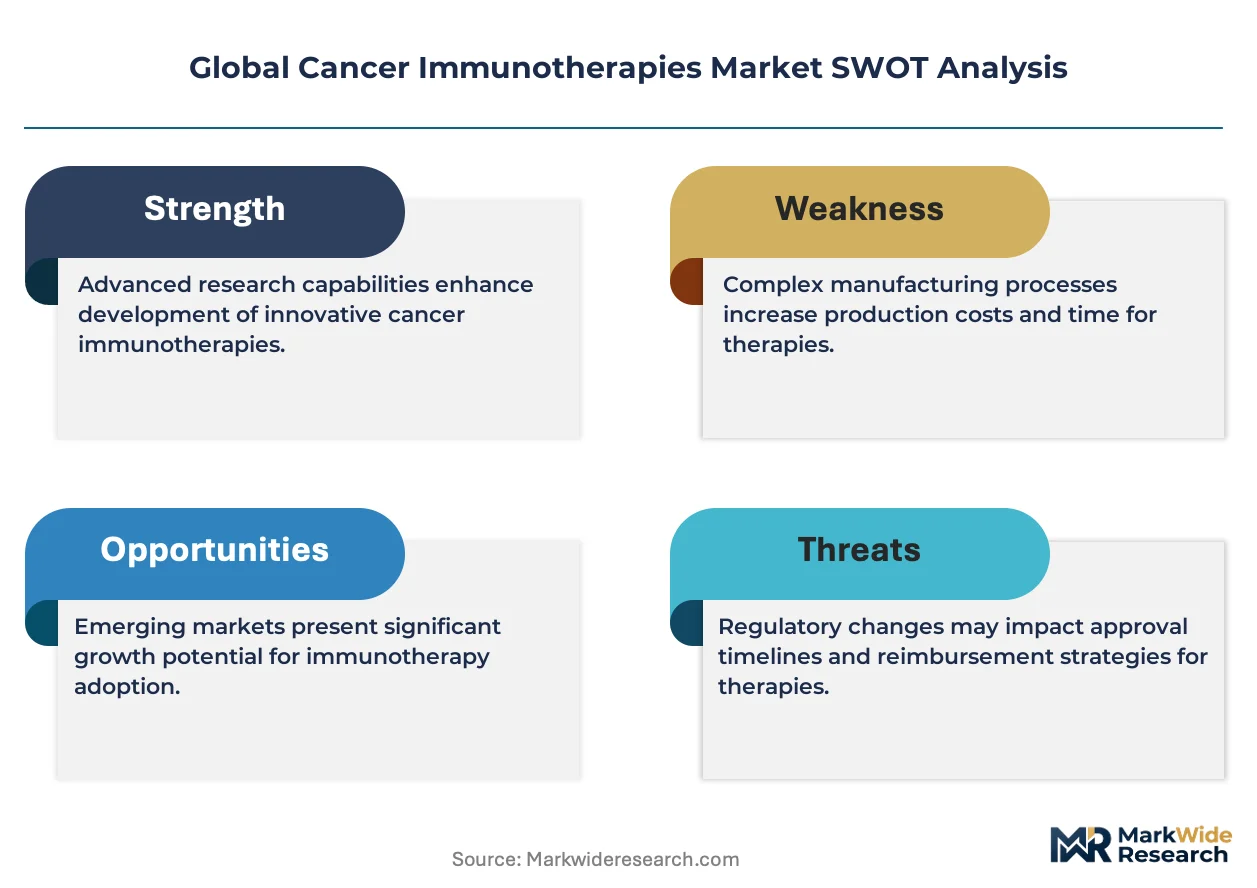
Checkpoint inhibitor protocols are compressing chemotherapy's first-line position across solid tumor indications, forcing manufacturers to restructure clinical trial investments and manufacturing capacity toward biologics.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated pathway compresses Phase II-to-approval timelines for novel immunotherapy modalities, channeling capital toward high-uncertainty biologics.
- CAR-T Manufacturing Automation:Closed-system bioreactors and vector production standardization are collapsing production cycle times from weeks to days at centralized facilities.
- Medicare Reimbursement Alignment:United States coverage policies for outpatient PD-1 administration create predictable revenue streams that sustain combination therapy development pipelines.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector manufacturing depends on a narrow base of contract suppliers concentrated in North America and Europe, creating single-source vulnerability for gene-modified cell therapies.
- Cold-Chain Infrastructure Gaps:Temperature-controlled distribution networks in India and Brazil remain underdeveloped, limiting patient access to cell therapies requiring liquid nitrogen storage.
- Cytokine Release Syndrome Liability:Severe immune-related adverse events trigger black-box warnings and restrictive Risk Evaluation and Mitigation Strategies that constrain prescribing flexibility in community oncology settings.
Strategic Opportunities
- Neoantigen Vaccine Platforms:Personalized cancer vaccines targeting patient-specific tumor mutations represent untapped white space with minimal competitive saturation in early-stage development.
- Japan's Sakigake Designation:PMDA's priority review system for regenerative medicines offers expedited market entry for first-in-class cell therapies addressing unmet oncology needs.
- Community Infusion Center Networks:Partnerships with regional chemotherapy administration sites expand PD-1 access beyond academic medical centers into suburban and rural patient populations.
Industry Challenges
- Cell Therapy Workforce Scarcity:GMP-grade aseptic processing and vector manufacturing expertise concentrates at a handful of training institutions, creating recruitment bottlenecks for commercial-scale facilities.
- Batch-to-Batch Potency Variability:Living-cell products exhibit inherent manufacturing heterogeneity that complicates release specifications and stability testing protocols.
- Real-World Evidence Integration:Post-marketing surveillance requirements for long-term secondary malignancy reporting strain pharmacovigilance infrastructure as treatment durations extend into adjuvant settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Immunotherapies Market |
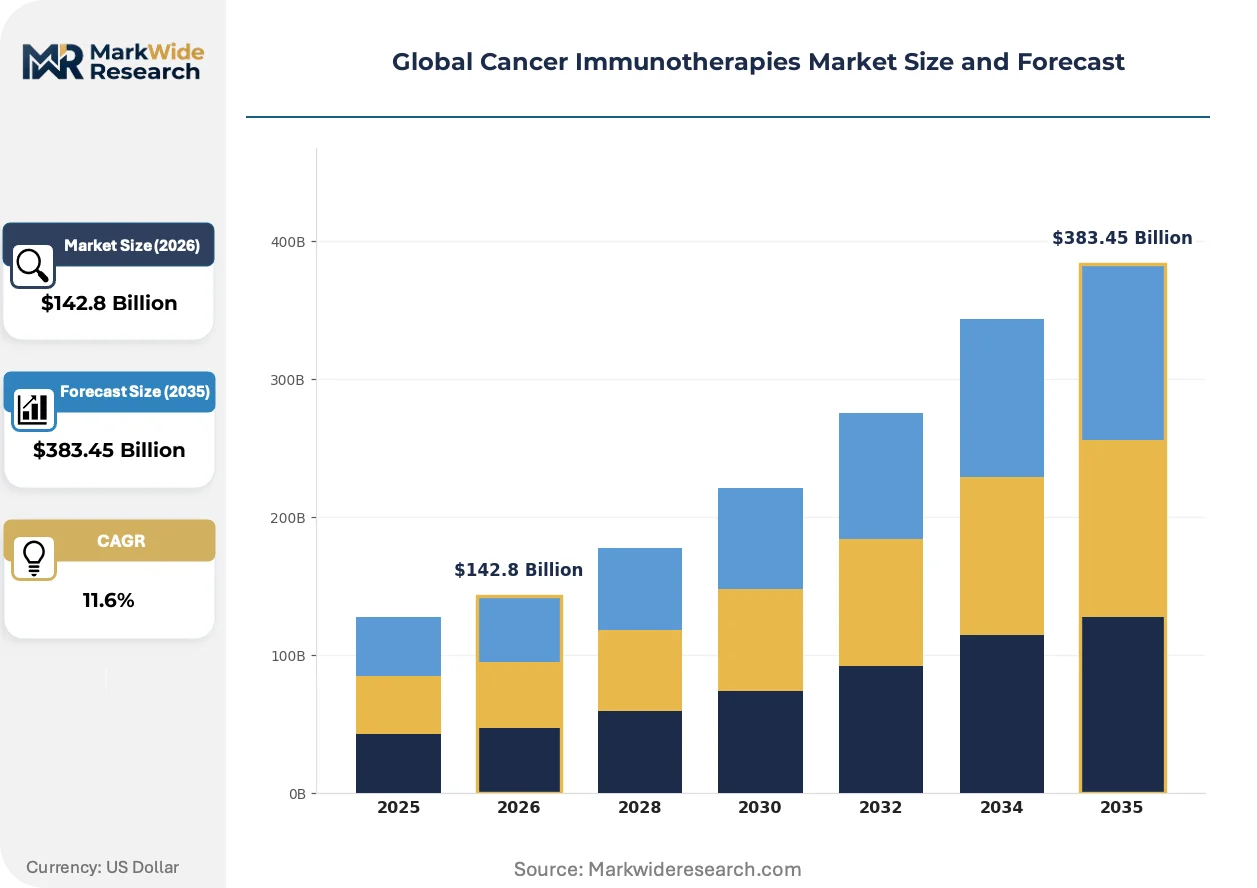
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $383.45 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Checkpoint Inhibitors, Cancer Vaccines, Adoptive Cell Transfer, Monoclonal Antibodies, Cytokines Therapy Area: Lung Cancer, Melanoma, Leukemia, Lymphoma, Brain Tumors End User: Oncology Clinics, Research Institutes, Specialized Hospitals, Diagnostic Centers Delivery Mode: Intravenous, Subcutaneous, Oral, Intratumoral, Intramuscular |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, AstraZeneca plc, Johnson & Johnson, Novartis AG, Pfizer Inc., Amgen Inc., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Immunotherapies Market Shifts & Advancements
Bispecific antibody architectures are displacing legacy monoclonal benchmarks by engaging dual tumor targets simultaneously, while regulatory frameworks adapt to accelerated development timelines for engineered cell therapies.
Next-generation T-cell engagers are fragmenting the solid tumor landscape previously resistant to immunotherapy intervention. These bispecific constructs redirect polyclonal T-cell activity against tumor-associated antigens without requiring patient-specific manufacturing. Oncology clinics in Germany and the United States are integrating these modalities into second-line protocols for lung and gastric malignancies. The technology is fragmenting competitive positioning by enabling off-the-shelf administration at price points below personalized CAR-T therapies.
The EMA's PRIME scheme is compressing scientific advice timelines for innovative immunotherapy developers seeking conditional marketing authorization. Early dialogue on manufacturing consistency and surrogate endpoint acceptability reduces regulatory risk for first-in-class submissions. Cell therapy sponsors targeting hematologic malignancies leverage this pathway most intensively, aligning CMC development with evolving quality standards before pivotal trial initiation.
Academic medical centers are consolidating purchasing authority for high-cost immunotherapy agents through centralized pharmacy and therapeutics committees. Formulary restriction mechanisms now require evidence of biomarker-directed patient selection before PD-1 or CTLA-4 blockade approval. This concentration is most visible in United States NCI-designated cancer centers, where protocol-driven prescribing aligns reimbursement with clinical trial participation metrics.
Global Cancer Immunotherapies Market Segmentation
Immunotherapy segmentation reveals divergent regulatory pathways and manufacturing requirements across modalities. Product type classification determines reimbursement coding and cold-chain infrastructure investment priorities.
Product Type:
FDA breakthrough therapy designation and EMA PRIME eligibility vary substantially across mechanism classes, shaping development capital allocation.
- Checkpoint Inhibitors:PD-1 and PD-L1 blocking antibodies dominate outpatient infusion volumes with established Medicare reimbursement codes. United States oncology clinics concentrate prescribing around pembrolizumab and nivolumab protocols for lung and melanoma indications.
- Cancer Vaccines:Personalized neoantigen platforms require patient-specific manufacturing timelines extending 12-16 weeks. Germany's Paul-Ehrlich-Institut oversees centralized quality release for mRNA-based therapeutic vaccines entering clinical trials.
- Adoptive Cell Transfer:CAR-T manufacturing automation is collapsing production cycles at centralized facilities.
- Monoclonal Antibodies:Legacy HER2 and EGFR-targeted agents retain substantial volume in combination regimens.
- Cytokines:IL-2 and interferon formulations face prescribing restrictions due to toxicity profiles.
Established volume favors checkpoint inhibitors; emerging adoption favors adoptive cell transfer.
Therapy Area:
Patient population scale and biomarker prevalence determine clinical trial feasibility and commercial addressability across malignancies.
- Lung Cancer:Non-small cell histology accounts for the largest absolute patient enrollment in PD-1 combination studies. Japan's National Cancer Center drives biomarker-directed first-line protocol adoption.
- Melanoma:High tumor mutational burden correlates with durable complete response rates, sustaining premium pricing despite smaller incident population.
- Leukemia:CD19-directed CAR-T therapies command concentrated manufacturing capacity allocation.
- Lymphoma:B-cell malignancies represent the most mature commercial cell therapy segment.
- Brain Tumors:Blood-brain barrier penetration challenges limit systemic immunotherapy efficacy.
Absolute patient volume concentrates in lung cancer; pricing power concentrates in melanoma.
End User:
Site-of-care requirements and staff training intensity segment institutional purchasing authority and reimbursement pathways.
- Oncology Clinics:Community-based infusion centers handle the majority of checkpoint inhibitor administrations with nursing staff trained in immune-related adverse event recognition.
- Specialized Hospitals:Academic medical centers monopolize CAR-T therapy delivery due to cytokine release syndrome management protocols and ICU proximity requirements.
- Research Institutes:Early-phase trial sponsors depend on NCI-designated cancer centers for patient accrual.
- Diagnostic Centers:Companion testing infrastructure determines treatment eligibility across PD-L1 and MSI-high assays.
Prescribing volume concentrates in oncology clinics; technical complexity concentrates in specialized hospitals.
Delivery Mode:
Route of administration dictates manufacturing formulation, stability requirements, and patient compliance profiles.
- Intravenous:Infusion protocols dominate checkpoint inhibitor and monoclonal antibody delivery with established nursing protocols.
- Subcutaneous:Fixed-dose formulations reduce administration time and facility capacity constraints.
- Oral:Small molecule immunomodulators offer patient convenience but face bioavailability challenges.
- Intratumoral:Direct injection modalities concentrate in melanoma and head and neck trials.
- Intramuscular:Vaccine adjuvants and cytokine depots utilize this route for sustained release.
Clinical adoption favors intravenous delivery; patient preference trends favor subcutaneous alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States payers demonstrate the lowest price elasticity for checkpoint inhibitors, while Indian and Brazilian procurement systems enforce aggressive cost-containment on biosimilar entrants. Germany and Japan occupy intermediate positions where outcome-based agreements mediate access negotiations.
United States
Medicare reimbursement codes for outpatient PD-1 administration sustain prescribing volume across community oncology networks. The FDA's breakthrough therapy designation compresses Phase II-to-approval timelines for novel biologics. Boston and San Francisco biotech clusters concentrate CAR-T manufacturing facilities and vector production capacity.
Germany
IQWiG health technology assessments determine reimbursement parity between immunotherapy and chemotherapy in first-line lung cancer protocols. The EMA's PRIME scheme channels early scientific dialogue toward conditional marketing authorization for innovative modalities. Heidelberg and Munich academic medical centers monopolize cell therapy delivery due to ICU proximity requirements.
Japan
PMDA's Sakigake designation for regenerative medicines accelerates priority review timelines for first-in-class cell therapies. National Health Insurance price premiums reward domestic clinical trial participation and manufacturing localization. Osaka and Yokohama pharmaceutical clusters house GMP-grade aseptic processing facilities for regional CAR-T supply.
China
NMPA's conditional approval pathway enables market entry based on single-arm Phase II data for hematologic malignancy indications. National Reimbursement Drug List negotiations impose annual price reduction requirements on PD-1 inhibitors. Shanghai and Suzhou biotech parks concentrate domestic checkpoint inhibitor manufacturing and biosimilar development.
India
CDSCO accelerated approval mechanisms facilitate early access to imported checkpoint inhibitors for metastatic melanoma and lung cancer indications. Government procurement through the Central Government Health Scheme imposes reference pricing against lowest-cost global suppliers. Hyderabad and Bangalore contract manufacturing organizations expand fill-finish capacity for regional immunotherapy distribution.
Global Cancer Immunotherapies Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Global Cancer Immunotherapies Market. Large-cap pharmaceutical conglomerates with established oncology franchises dominate checkpoint inhibitor development and combination protocol design. Mid-cap biotech specialists concentrate on novel target discovery and bispecific antibody engineering. Contract development and manufacturing organizations capture value through viral vector production and cell therapy process optimization. Competitive moves center on strategic partnerships for combination therapy rights and geographic licensing arrangements to access regional reimbursement networks.
Among large-cap integrated developers, Merck & Co., Inc., Bristol-Myers Squibb Company, and F. Hoffmann-La Roche Ltd occupy positions defined by PD-1 franchise scale and combination portfolio breadth. Merck & Co., Inc. exemplifies the checkpoint inhibitor archetype through pembrolizumab-driven protocol adoption. Bristol-Myers Squibb Company represents dual immunotherapy regimens integrating CTLA-4 and PD-1 blockade mechanisms. F. Hoffmann-La Roche Ltd anchors personalized neoantigen strategies extending into novel target spaces. These three entities collectively illustrate how established oncology infrastructure translates into prescribing authority across United States and European academic medical centers.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca plc |
| Johnson & Johnson |
| Novartis AG |
| Pfizer Inc. |
| Amgen Inc. |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Centralized CAR-T manufacturing at Boston and San Francisco biotech clusters generates steep scale economies that compress per-dose production costs while simultaneously concentrating pricing power among vector suppliers and contract development organizations. This capacity clustering creates asymmetric bargaining positions where multi-product facilities command premium slotting fees, forcing smaller developers toward costlier spot-market arrangements that inflate downstream therapy pricing.
Pricing Analysis
Medicare reimbursement codes dictate the pricing tier structure for outpatient PD-1 administration across United States oncology networks. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center protocols from community infusion centers and biosimilar substitution tiers. Cost compression in checkpoint inhibitor categories is intensifying because National Reimbursement Drug List negotiations in China impose annual price reduction requirements. Community oncology clinics exhibit highest price sensitivity due to thin margins on infusion services, while specialized hospitals retain lowest sensitivity through bundled research funding.
Supply Chain Analysis
Strategic stockpiling of viral vectors and plasmid DNA dominates inventory strategy as manufacturers buffer against single-source supplier disruptions in gene-modified cell therapies. Vector production concentrates in the United States, Germany, and Switzerland, with fill-finish capacity expanding at Hyderabad and Bangalore contract manufacturing organizations. Supply chain risk centers on plasmid DNA supply concentration across North American and European contract suppliers. Distribution runs through cold-chain logistics networks requiring liquid nitrogen storage infrastructure that remains underdeveloped in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CAR-T manufacturing automation represents a technological inflection compressing production cycles from weeks to days, disrupting established cost structures and competitive positioning across cell therapy modalities.
For Market Incumbents: Consolidate vector manufacturing capacity through captive supply arrangements or exclusive supplier partnerships to defend against plasmid DNA supply concentration vulnerabilities. Deepen backward integration into closed-system bioreactor technology to reduce dependency on external manufacturing slots. Lock in long-term cytokine sourcing agreements before capacity constraints intensify across GMP-grade aseptic processing facilities. For New Entrants and Emerging Players: Differentiate on neoantigen vaccine platforms where competitive saturation remains minimal and regulatory pathways through EMA PRIME scheme offer accelerated scientific dialogue. Target Japan's Sakigake designation pathway for regenerative medicines as the most penetrable regulatory entry point for first-in-class cell therapies. Pursue community infusion center partnerships as the primary go-to-market angle to bypass academic medical center formulary gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bispecific antibody engineering specialists with manufacturing-ready platforms and existing EMA scientific advice engagement. Five-to-ten year viability hinges on automation-enabled cost reduction trajectories rather than single-product approval events. Acquisition target archetype: mid-cap biotech with validated T-cell engager constructs and centralized manufacturing partnerships. The signal to watch is FDA breakthrough therapy designation velocity for solid tumor indications previously resistant to immunotherapy intervention.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Closed-system bioreactor deployment at centralized facilities collapses CAR-T production cycle times. |
| Regulatory Approval Pathway | EMA PRIME scheme channels early scientific dialogue toward conditional marketing authorization for novel modalities. |
| Licensing Agreement | Combination therapy rights partnerships expand PD-1 protocol adoption across solid tumor indications. |
| Clinical Trial Advancement | Biomarker-directed patient selection protocols align reimbursement with NCI-designated cancer center participation metrics. |
| Pipeline Diversification | Personalized neoantigen strategies extend oncology portfolios into novel target spaces beyond checkpoint inhibition. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases established baseline market sizing. Bottom-up patient population modeling and top-down revenue triangulation cross-checked segment-level estimates across the analysis window.
Segmentation dimensions modeled include product type, therapy area, end user, and delivery mode, with additional granularity across regional regulatory clusters and treatment line positioning. CAGRs were derived from trend extrapolation anchored to observable reimbursement and regulatory inflection points. Forecast inputs incorporated manufacturing automation adoption curves and biomarker testing penetration rates across lung cancer and melanoma indications.
Material uncertainties — regulatory delays in cytokine release syndrome reporting requirements, plasmid DNA supplier consolidation, and cold-chain infrastructure development timelines in emerging markets — sit outside the modeled envelope. Forecasts reflect assumptions about continued Medicare reimbursement alignment and EMA adaptive licensing framework stability. Revision becomes warranted when biosimilar substitution rates or manufacturing automation adoption cross thresholds that alter competitive cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Transient Ischemic Attack Market