
 Non-Alcoholic Steatohepatitis Drugs Pipeline Market | 2026-2036
Non-Alcoholic Steatohepatitis Drugs Pipeline Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Steatohepatitis Drugs Pipeline Market Analytics
Market Context
Small molecules are realigning product economics in the NASH pipeline as oral therapies displace injectable biologics across late-stage trials. Gilead Sciences leverages its liver disease infrastructure to sustain clinical momentum across multiple mechanism classes. Novo Nordisk anchors metabolic expertise from its diabetes franchise to compete in the GLP-1 receptor agonist segment for NASH. Madrigal Pharmaceuticals differentiates through thyroid hormone receptor-beta selectivity, a narrow mechanism that occupies a distinct position in the competitive landscape.
Technical Definition and Segment Structure
The non-alcoholic steatohepatitis drugs pipeline encompasses investigational therapeutics targeting liver inflammation and fibrosis progression in patients without significant alcohol consumption, with candidates spanning oral small molecules, injectable biologics, and combination regimens designed to modulate metabolic, inflammatory, and fibrotic pathways. The primary commercial purpose is to deliver first-in-class or best-in-class therapies for a disease with no approved pharmacological treatments, addressing a patient population exceeding hundreds of millions globally who currently rely on lifestyle intervention alone. Small molecules dominate current development activity due to manufacturing scalability and patient preference for oral administration routes, while combination therapies represent the fastest-growing segment as sponsors pursue synergistic mechanisms to address the multifactorial nature of NASH pathogenesis. Phase 3 candidates command concentrated investment attention and partnership capital, though the preclinical reservoir remains substantial as academic and biotech originators feed the early-stage pipeline.
Regulatory Framework and Outlook
The FDA's breakthrough therapy designation and accelerated approval pathways shape trial design and endpoint selection for NASH sponsors, while the EMA's parallel scientific advice process influences European development strategies. The FDA maintains stringent requirements for histological endpoints, compelling sponsors to navigate liver biopsy-dependent regulatory standards despite active exploration of non-invasive biomarker alternatives. Stakeholders must monitor the evolving surrogate endpoint debate, as regulatory acceptance of imaging-based or blood-based biomarkers would fundamentally reshape trial economics and patient recruitment feasibility across the development landscape.
Market Dynamics
The FDA's breakthrough therapy designation program is compressing clinical trial timelines and redirecting capital toward Phase 3 NASH candidates, fundamentally restructuring how sponsors sequence development milestones and prioritize histological endpoints over surrogate markers.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation reduces regulatory review periods for NASH candidates demonstrating fibrosis improvement, enabling faster market entry for first-in-class therapies.
- Biomarker Validation Initiatives:The NASH Clinical Research Network's non-invasive diagnostic standardization is expanding patient screening capacity and reducing reliance on liver biopsy recruitment bottlenecks.
- Medicare Reimbursement Expansion:Specialized liver centers in the United States are securing coverage determinations for pipeline therapy administration, creating institutional demand pull for emerging treatments.
Market Restraints
- Histological Endpoint Dependency:The FDA maintains liver biopsy requirements for primary endpoints, inflating per-patient trial costs and limiting site expansion to academic medical centers with interventional radiology capacity.
- Patient Recruitment Saturation:Competing Phase 3 programs concentrate enrollment in identical metropolitan corridors, exhausting the treatment-naive NASH population with advanced fibrosis.
- Placebo Response Variability:High spontaneous resolution rates in biopsy-diagnosed cohorts necessitate oversized control arms, diluting statistical power and extending study duration.
Strategic Opportunities
- Pediatric NASH Indications:The FDA's Rare Pediatric Disease designation creates priority review voucher eligibility for sponsors addressing the adolescent metabolic dysfunction-associated steatohepatitis population.
- Combination Regimen White Space:Pairing metabolic modulators with anti-fibrotic agents offers synergistic efficacy potential in biopsy-proven cirrhosis populations currently excluded from monotherapy trials.
- Digital Biomarker Integration:Magnetic resonance elastography and enhanced liver fibrosis score standardization is enabling decentralized trial monitoring, reducing site dependency and geographic recruitment constraints.
Industry Challenges
- Specialized Investigator Scarcity:Qualified hepatologists with interventional radiology coordination experience are concentrated in fewer than forty academic medical centers, creating site activation bottlenecks.
- Cross-Functional Integration Complexity:Sponsors must coordinate metabolic, cardiovascular, and liver safety endpoints across disparate therapeutic area teams, fragmenting development strategy and regulatory submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Steatohepatitis Drugs Pipeline Market |
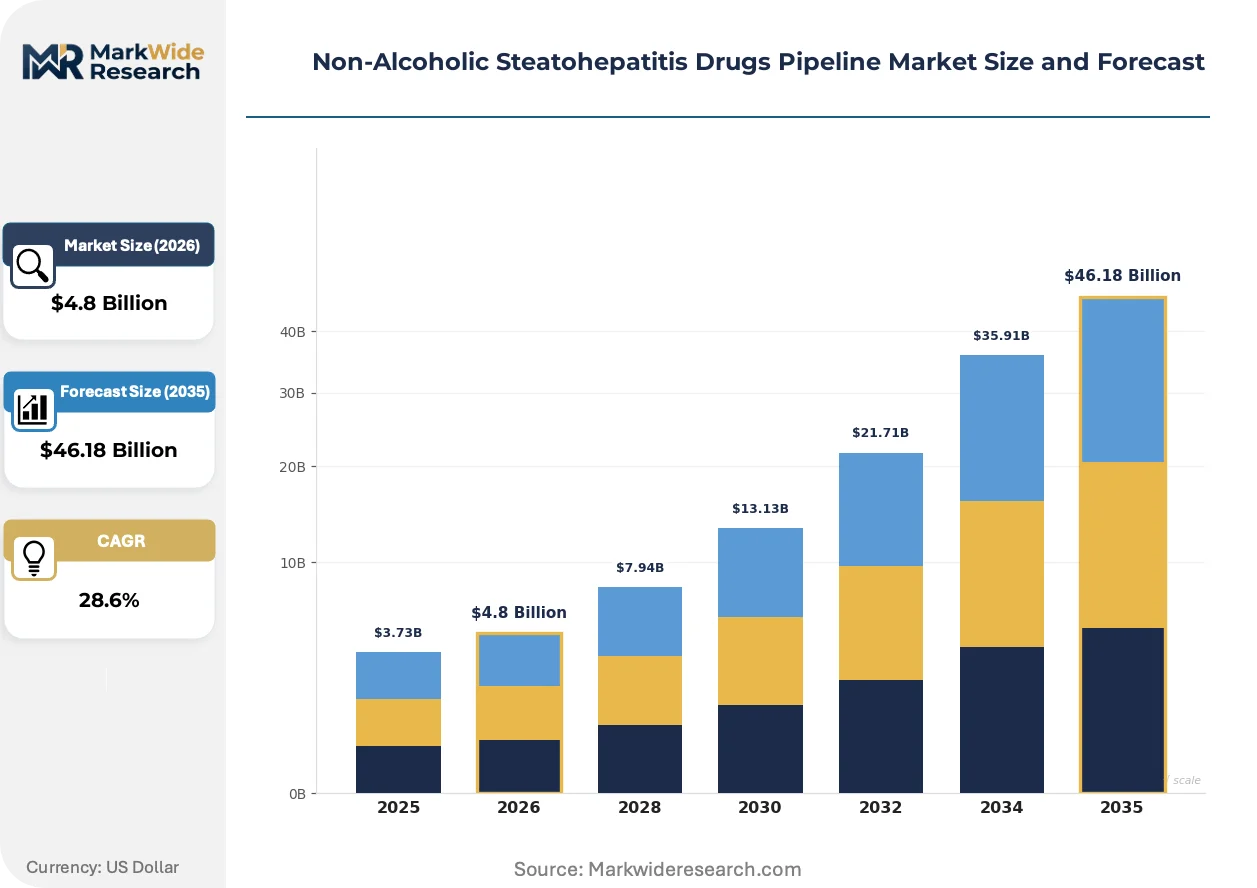
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Combination Therapies, Investigational Drugs Therapy Area: Metabolic Disorders, Liver Diseases, Gastroenterology, Endocrinology Development Stage: Preclinical, Phase 1, Phase 2, Phase 3 Administration Route: Oral, Subcutaneous, Intravenous, Transdermal |
| Companies Covered | Gilead Sciences, Inc., Novo Nordisk A/S, Intercept Pharmaceuticals, Inc., Madrigal Pharmaceuticals, Inc., Eli Lilly and Company, AbbVie Inc., Viking Therapeutics, Inventiva Pharma, Galectin Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Steatohepatitis Drugs Pipeline Market Evolving Landscape
Non-invasive diagnostic technologies are displacing histological confirmation as the primary patient identification method, while regulatory pressure mounts for surrogate endpoint acceptance and trial design innovation accelerates across mechanism classes.
Magnetic resonance imaging-proton density fat fraction technology is decentralizing NASH screening by enabling quantitative liver fat measurement without biopsy referral. Community gastroenterology practices are adopting these platforms to identify trial-eligible patients earlier in disease progression. This diffusion is compressing the diagnostic pathway and expanding addressable populations beyond tertiary referral centers.
The FDA's draft guidance on surrogate endpoints in NASH is reshaping Phase 2b trial architecture by permitting accelerated approval contingent on fibrosis improvement without concurrent NASH resolution. Sponsors are responding with adaptive trial designs that integrate imaging-based secondary endpoints. The regulatory flexibility most directly benefits programs targeting F2-F3 fibrosis populations where biopsy risk tolerance limits enrollment.
Integrated delivery networks are consolidating formulary decision-making for pipeline NASH therapies under specialty pharmacy benefit managers, displacing traditional physician-directed prescribing. This concentration shifts commercial strategy toward health economics evidence and real-world data contracts. The transformation is most advanced in United States Medicare Advantage plans with dedicated hepatology carve-outs.
Non-Alcoholic Steatohepatitis Drugs Pipeline Market Segmentation
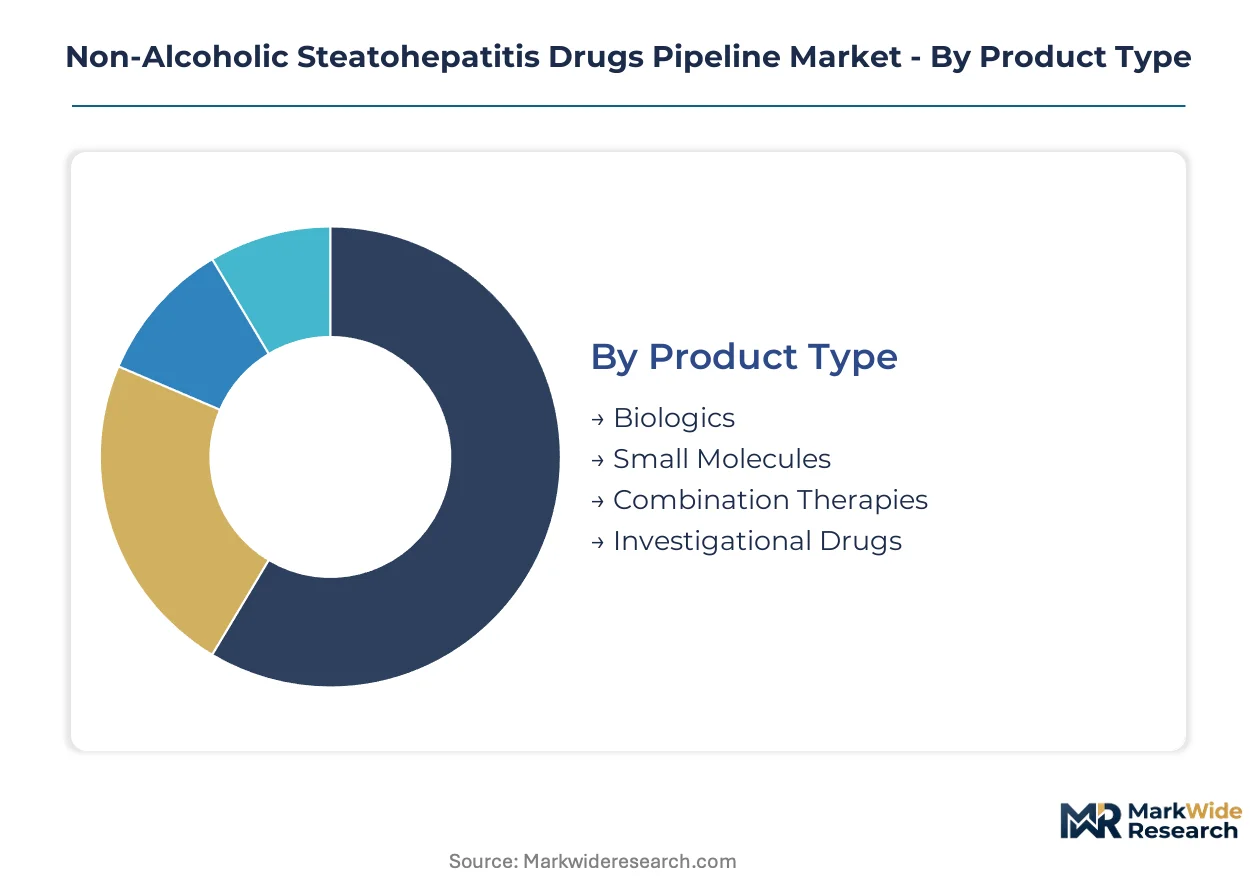
NASH drug development fragments across multiple technical and commercial dimensions. Pipeline sponsors must align mechanism class, therapeutic focus, and administration convenience to capture differentiated patient access pathways.
Product Type:
Development economics and manufacturing scalability separate sponsors in this category.
- Small Molecules:Oral bioavailability and synthetic chemistry routes enable cost-efficient scale-up at contract manufacturing organizations. Hepatology clinics in the United States prioritize oral candidates for patient compliance in chronic administration regimens.
- Biologics:Monoclonal antibodies and peptide constructs target specific inflammatory cytokines with high binding affinity. Cold-chain distribution requirements and subcutaneous injection protocols limit site activation to academic medical centers with specialized pharmacy infrastructure.
- Combination Therapies:Dual-mechanism regimens pair metabolic modulators with anti-fibrotic agents.
- Investigational Drugs:Novel chemical entities in early characterization stages.
Small molecules lead volumes today; combination therapies are gaining share fastest.
Therapy Area:
Prescriber specialty and reimbursement coding determine commercial access routes.
- Liver Diseases:Dedicated hepatology practices drive enrollment for fibrosis-targeting candidates. Medicare reimbursement for liver biopsy procedures sustains diagnostic throughput at specialized centers.
- Metabolic Disorders:Endocrinology networks with diabetes management infrastructure repurpose GLP-1 receptor agonist platforms. Patient overlap with type 2 diabetes populations expands screening efficiency.
- Gastroenterology:Community-based practices with non-invasive diagnostic capability.
- Endocrinology:Hormonal pathway modulation for metabolic dysfunction-associated steatohepatitis.
Liver diseases anchor current development investment; metabolic disorders show the steepest expansion trajectory.
Development Stage:
Capital allocation intensity and partnership timing vary sharply across maturity tiers.
- Phase 3:Registrational trials with histological endpoints command concentrated venture financing and licensing deal flow. The FDA's breakthrough therapy designation compresses regulatory review timelines for candidates demonstrating fibrosis improvement.
- Phase 2:Proof-of-concept studies generate biomarker data for mechanism validation. Adaptive trial designs integrate imaging-based secondary endpoints to reduce biopsy dependency.
- Phase 1:Safety and pharmacokinetic characterization in healthy volunteers.
- Preclinical:In vitro and animal model validation of target engagement.
Phase 3 candidates attract the largest capital commitments; Phase 2 programs are climbing the fastest in partnership activity.
Administration Route:
Patient preference and site infrastructure requirements shape competitive positioning.
- Oral:Tablet and capsule formulations eliminate cold-chain logistics and enable community pharmacy dispensing. Patient adherence metrics favor oral routes for chronic NASH management.
- Subcutaneous:Self-administered injection devices suit metabolic disorder patient populations familiar with diabetes therapy protocols.
- Intravenous:Infusion center requirements restrict access to tertiary care settings.
- Transdermal:Patch-based delivery systems in early exploration for hepatic targeting.
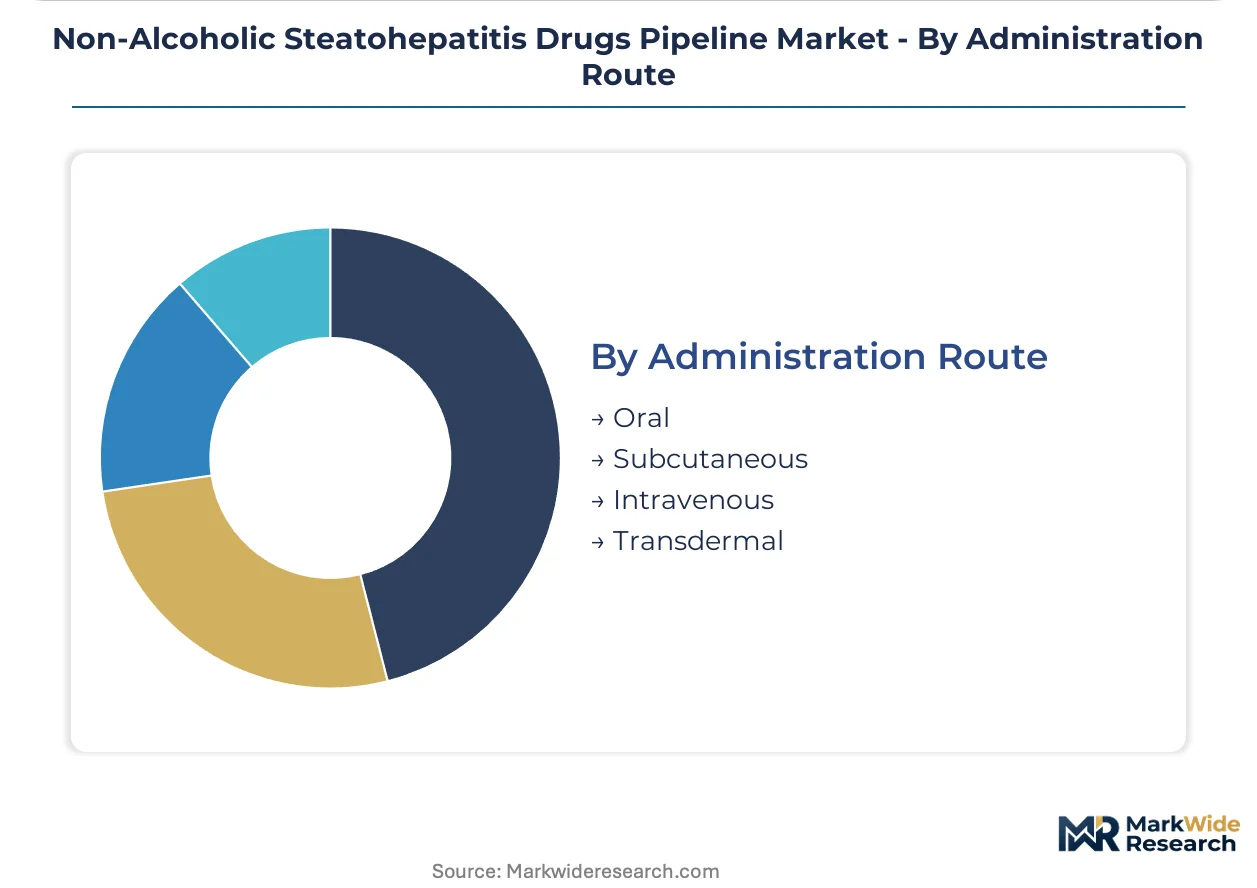
Oral administration dominates current pipeline composition; subcutaneous delivery is expanding most quickly in late-stage trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors clinical trial density for NASH pipeline development, with hepatology centers at Massachusetts General Hospital and Brigham and Women's Hospital driving Phase 3 enrollment. FDA breakthrough therapy designations concentrate sponsor investment in United States metropolitan corridors with established liver biopsy infrastructure.
United States
Medicare reimbursement policies for liver biopsy procedures sustain diagnostic throughput at specialized hepatology centers in Cleveland Clinic and Mayo Clinic networks. The FDA accelerates breakthrough therapy reviews for candidates demonstrating fibrosis improvement without NASH resolution. Philadelphia's University of Pennsylvania Health System anchors the Mid-Atlantic trial corridor with integrated interventional radiology capacity.
Germany
EMA parallel scientific advice processes shape European development strategies for NASH sponsors seeking simultaneous US-EU approval pathways. The country's statutory health insurance system creates predictable reimbursement frameworks for emerging liver therapies. Heidelberg University Hospital and Charité Berlin anchor the national hepatology trial network with standardized non-invasive diagnostic protocols.
Japan
PMDA consultation procedures for orphan drug designation attract sponsors addressing the metabolic dysfunction-associated steatohepatitis population with high diabetes comorbidity. The Ministry of Health, Labour and Welfare's Sakigake designation system compresses regulatory timelines for first-in-class NASH therapies. Tokyo's National Center for Global Health and Medicine coordinates multicenter hepatology trials across Kanto region academic medical centers.
United Kingdom
NHS England's specialized commissioning frameworks for liver disease create institutional demand pathways for pipeline therapies. The MHRA's Innovative Licensing and Access Pathway accelerates market entry for NASH candidates with breakthrough potential. London's Royal Free Hospital and King's College Hospital anchor the national hepatology trial network with established fibrosis staging expertise.
Switzerland
Swissmedic's rapid scientific advice procedures attract sponsors seeking regulatory clarity on surrogate endpoint acceptance for Phase 2b trials. The country's compulsory health insurance system ensures broad patient access to innovative liver therapies post-approval. Basel's University Hospital and Lausanne's CHUV anchor the national hepatology research network with integrated metabolic disorder clinics.
Non-Alcoholic Steatohepatitis Drugs Pipeline Market Competitive Landscape
Global majors compete with regional champions across mechanism class specialization and hepatology infrastructure access. The NASH pipeline concentrates investment among large-cap biopharmaceuticals with established liver disease franchises and mid-cap specialists with single-asset focus. Three archetypes dominate: metabolic platform extenders repurposing diabetes assets, liver-focused biotechs with narrow receptor selectivity, and diversified pharmaceuticals pursuing combination regimens. Competitive dynamics center on Phase 3 trial speed and FDA breakthrough therapy capture.
Within the metabolic platform tier, Novo Nordisk A/S and Eli Lilly and Company exemplify diabetes franchise extension into NASH indications through GLP-1 receptor agonist pathways. Madrigal Pharmaceuticals, Inc. anchors the selective mechanism specialist position with thyroid hormone receptor-beta targeting. Gilead Sciences, Inc. occupies the diversified liver disease incumbent role, leveraging decades of hepatology infrastructure across multiple mechanism classes. Each archetype represents distinct capital allocation priorities and partnership postures toward combination therapy development.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| Novo Nordisk A/S |
| Intercept Pharmaceuticals, Inc. |
| Madrigal Pharmaceuticals, Inc. |
| Eli Lilly and Company |
| AbbVie Inc. |
| Viking Therapeutics |
| Inventiva Pharma |
| Galectin Therapeutics Inc. |
| Others |
Value Network & Pricing Analysis
Interventional radiologist concentration in the Boston-Cambridge and Philadelphia corridors creates labor-cost differentials that widen pricing spreads between premium academic sites and community hepatology practices. Cold-chain logistics for biologics versus oral small-molecule distribution further stratifies cost-to-serve economics across the NASH pipeline.
Pricing Analysis
Input-cost pass-through from specialized investigator fees and liver biopsy coordination expenses shapes three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to FDA breakthrough therapy designation status and academic medical center site premiums, while standard tiers target community hepatology networks with non-invasive diagnostic capability. Pricing pressure stems from Medicare reimbursement compression for liver biopsy procedures. Community gastroenterology practices exhibit highest price sensitivity; specialized liver centers with captive patient flows demonstrate lowest.
Supply Chain Analysis
Workforce availability for GMP manufacturing of oral small molecules concentrates in Ireland, Switzerland, and the United States, while biologics production clusters in Massachusetts, North Carolina, and Puerto Rico. Active pharmaceutical ingredients for metabolic modulators draw from specialized chemical synthesis hubs in India and China. Single-source vulnerability for thyroid hormone receptor-beta agonist starting materials poses structural risk. Distribution runs through specialty pharmacy benefit managers with hepatology carve-out networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the NASH pipeline rests on substitution of liver biopsy-dependent trial designs with imaging-based endpoints, compressing per-patient costs while preserving premium pricing for first-in-class approvals.
For Market Incumbents: Acquire Phase 2b clinical assets with validated fibrosis biomarker data to backfill pipeline gaps against GLP-1 receptor agonist encroachment. Consolidate hepatology site networks through exclusive trial site agreements to lock out emerging competitors. Prioritize regulatory affairs investment in FDA surrogate endpoint qualification to accelerate approval timelines. For New Entrants and Emerging Players: Digital biomarker integration offers a technology-first wedge into decentralized trial monitoring, bypassing academic medical center bottlenecks. Target pediatric NASH indications with Rare Pediatric Disease designation eligibility, the most penetrable regulatory pathway. Pursue health economics outcomes research partnerships with Medicare Advantage plans as the primary go-to-market angle. For Investors and Strategic Acquirers: Large-cap metabolic platform extenders are the most active acquirer in this space, seeking single-asset specialists to complement diabetes franchises. Long-term viability favors selective mechanism programs with distinct receptor binding profiles over me-too metabolic modulators. Watch FDA draft guidance finalization on surrogate endpoint acceptance as the critical inflection signal for trial economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase 3 progression with histological endpoints commands venture financing and licensing deal flow. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for fibrosis-improving candidates. |
| Manufacturing Scale-Up | Oral small-molecule GMP capacity expansion in Ireland and Switzerland reduces cost-to-serve. |
| Pipeline Diversification | Combination regimen development pairs metabolic modulators with anti-fibrotic agents. |
| Licensing Agreement | Academic biotech originators feed early-stage assets to large-cap hepatology franchises. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists alongside secondary validation. Secondary sources include FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down epidemiological triangulation anchor market sizing.
Rate-of-change decomposition separates volume drivers from price evolution across the projection horizon. Segmentation dimensions encompass mechanism class, development stage, administration route, patient fibrosis stage, and regional regulatory cluster. CAGRs derive from log-linear trend fitting applied to enrollment velocity and approval probability-weighted revenue projections. Forecast inputs incorporate biomarker validation timelines and site activation capacity constraints.
The model holds under current FDA histological endpoint requirements; deviation in surrogate endpoint acceptance or breakthrough therapy designation criteria would shift trial economics and capital allocation patterns. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Retinal Drugs Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market