
 Neurology Patient Monitoring Market | 2026-2036
Neurology Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Neurology Patient Monitoring Market Intelligence
Class II and Class III device certification tiers is redrawing competitive boundaries in neurology monitoring. Medtronic leverages its vertically integrated neurosurgery portfolio to dominate implantable intracranial pressure monitoring. Natus Medical specializes in EEG and sleep diagnostic systems, anchoring its position in epilepsy monitoring centers. Koninklijke Philips competes through enterprise-wide critical care informatics that embed neurology modules into broader ICU platforms.
Neurology patient monitoring encompasses electrophysiological recording, intracranial hemodynamic sensing, and neurochemical detection systems designed for real-time assessment of central nervous system function, typically operating with sampling rates exceeding 256 Hz for EEG channels to capture epileptiform activity. These systems serve neurocritical care units, operating rooms, and ambulatory settings where delayed detection of secondary brain injury drives morbidity. Wireless monitoring and wearable devices are capturing the fastest expansion as health systems decentralize post-acute stroke and epilepsy surveillance from hospital wards to patient homes. EEG devices retain the largest installed base and deepest margin pools due to recurring electrode and software maintenance revenues, while cloud-based solutions are restructuring data architecture by enabling multi-site neurology networks to centralize interpretation.
FDA premarket notification and premarket approval pathways govern device commercialization in the United States, with recent guidance on AI-enabled diagnostic algorithms accelerating review timelines for seizure detection software. The EU Medical Device Regulation and CE marking requirements enforce clinical evidence standards for neurology monitors marketed across Europe, while Japan's PMDA maintains distinct quality management system inspections for foreign manufacturers. Stakeholders must weigh regulatory capital requirements against the pace of algorithm innovation when allocating R&D budgets across hardware and software development tracks.
Market Dynamics
Continuous EEG monitoring protocols are displacing intermittent spot-checks in neurocritical care units, compressing detection windows for secondary brain injury from hours to minutes and forcing hardware manufacturers to integrate real-time analytics at the edge.
Growth Catalysts
- FDA AI-enabled device guidance:The agency's streamlined premarket review pathways for seizure detection algorithms accelerate commercialization timelines for software-enhanced EEG systems.
- Post-acute stroke surveillance:Health systems in Germany and Japan are decentralizing monitoring from hospital wards to patient homes, creating pull for wireless wearable devices.
- Epilepsy monitoring centers:These specialized facilities require high-channel-count EEG systems with proprietary electrode arrays, generating recurring consumable revenue streams.
Market Restraints
- Silver-silver chloride electrode supply:Concentrated sourcing of conductive materials for reusable electrodes creates input cost volatility and quality consistency risks.
- EU MDR clinical evidence requirements:The Medical Device Regulation mandates extensive performance data for neurology monitors, extending certification timelines and capital requirements.
- Intracranial pressure catheter limitations:Invasive sensing carries infection risk and requires neurosurgical placement, constraining addressable patient populations.
Strategic Opportunities
- Home-based epilepsy monitoring:Underpenetrated ambulatory settings in the United States offer expansion potential for cloud-connected wearable EEG systems with automated event detection.
- EU Green Deal circularity mandates:Regulatory pressure for sustainable device lifecycle management creates advantage for manufacturers with electrode recycling programs.
- AI-EEG convergence:Machine learning pattern recognition combined with high-density electrode arrays enables predictive seizure forecasting previously unattainable with manual interpretation.
Industry Challenges
- Clinical neurophysiologist shortage:Specialized interpretation expertise for complex EEG patterns limits scalable deployment of monitoring networks.
- Legacy EMR integration:Proprietary data formats from established EEG manufacturers create friction when connecting to hospital information systems.
- ISO 13485 quality management:Medical device certification complexity for software-as-a-service models strains traditional hardware-centric quality frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurology Patient Monitoring Market |
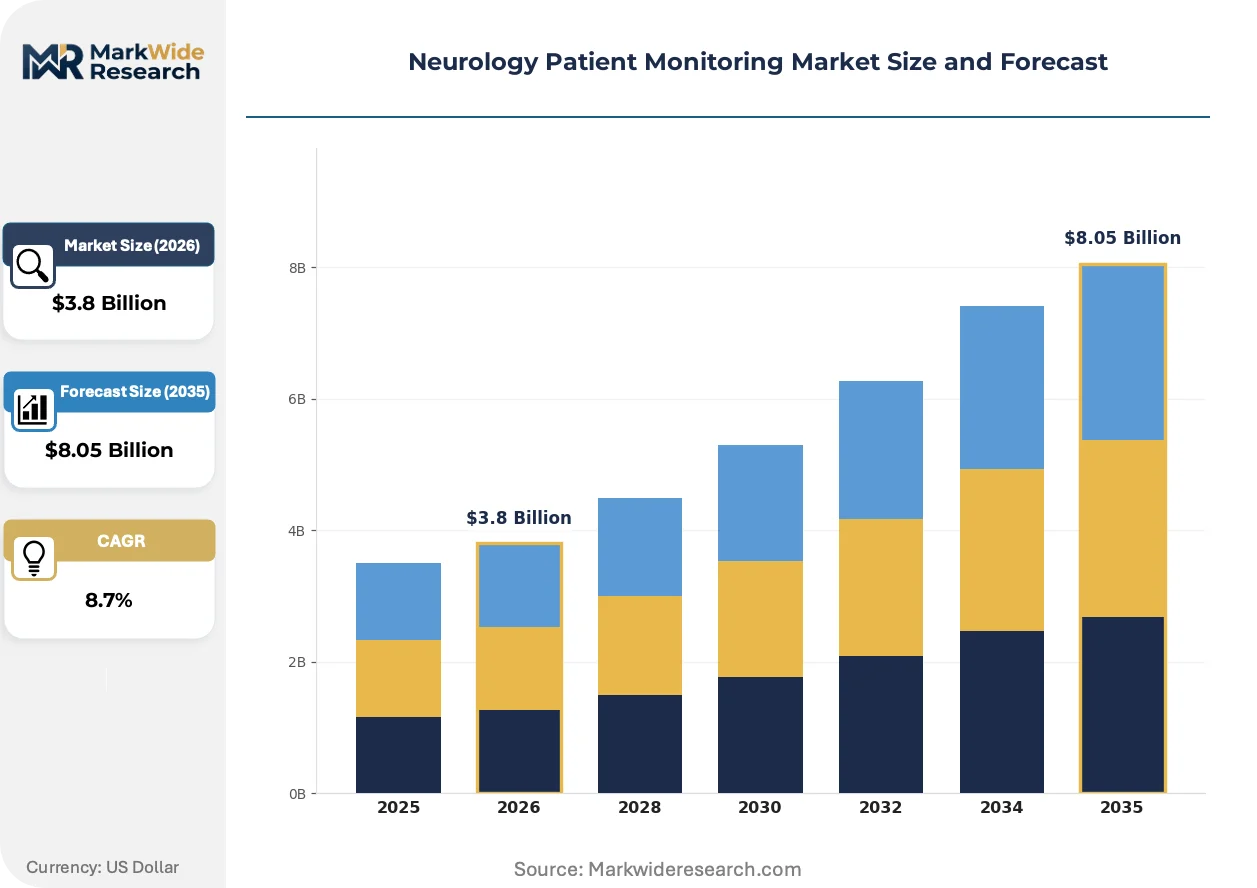
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Devices, EMG Equipment, ICU Monitors, Neurotransmitters Technology: Wireless Monitoring, Cloud-Based Solutions, Wearable Devices, Telemetry Systems End User: Hospitals, Rehabilitation Centers, Research Institutes, Home Care Application: Seizure Management, Pain Assessment, Cognitive Function Testing, Sleep Studies |
| Companies Covered | Medtronic, Natus Medical, Integra LifeSciences, Koninklijke Philips, Nihon Kohden Corporation, GE Healthcare, Raumedic AG, Sophysa, Spiegelberg GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurology Patient Monitoring Market Strategic Shifts & Innovations
Algorithm-augmented diagnostics are redistributing value capture from hardware manufacturers to software developers, while regulatory frameworks race to accommodate continuous learning systems that update post-market.
Machine learning seizure detection is bifurcating the EEG analytics landscape between cloud-based centralized interpretation and edge-deployed embedded algorithms. Academic medical centers with dedicated epilepsy units favor high-latency cloud pipelines enabling multi-site research collaboration. Community hospitals prioritize on-device inference to minimize network dependency and data sovereignty concerns. This technical split is compressing pricing power for monolithic platform vendors unable to serve both deployment models.
The EU AI Act risk classification framework imposes conformity assessment obligations on AI-enabled diagnostic software that directly influences patient treatment decisions. Neurology monitoring algorithms classified as high-risk systems face mandatory post-market performance monitoring and human oversight requirements. European manufacturers are responding by segregating AI modules into separately certifiable software components to isolate regulatory exposure.
Hospital procurement for neurocritical care platforms now weights total cost of ownership over capital expenditure, unbundling hardware acquisition from electrode supply and software maintenance contracts. Integrated delivery networks negotiate multi-year service agreements that consolidate interpretation services across affiliated facilities. This purchasing evolution is most pronounced in the United States where health system consolidation has concentrated buying power among regional mega-systems.
Neurology Patient Monitoring Market Segmentation
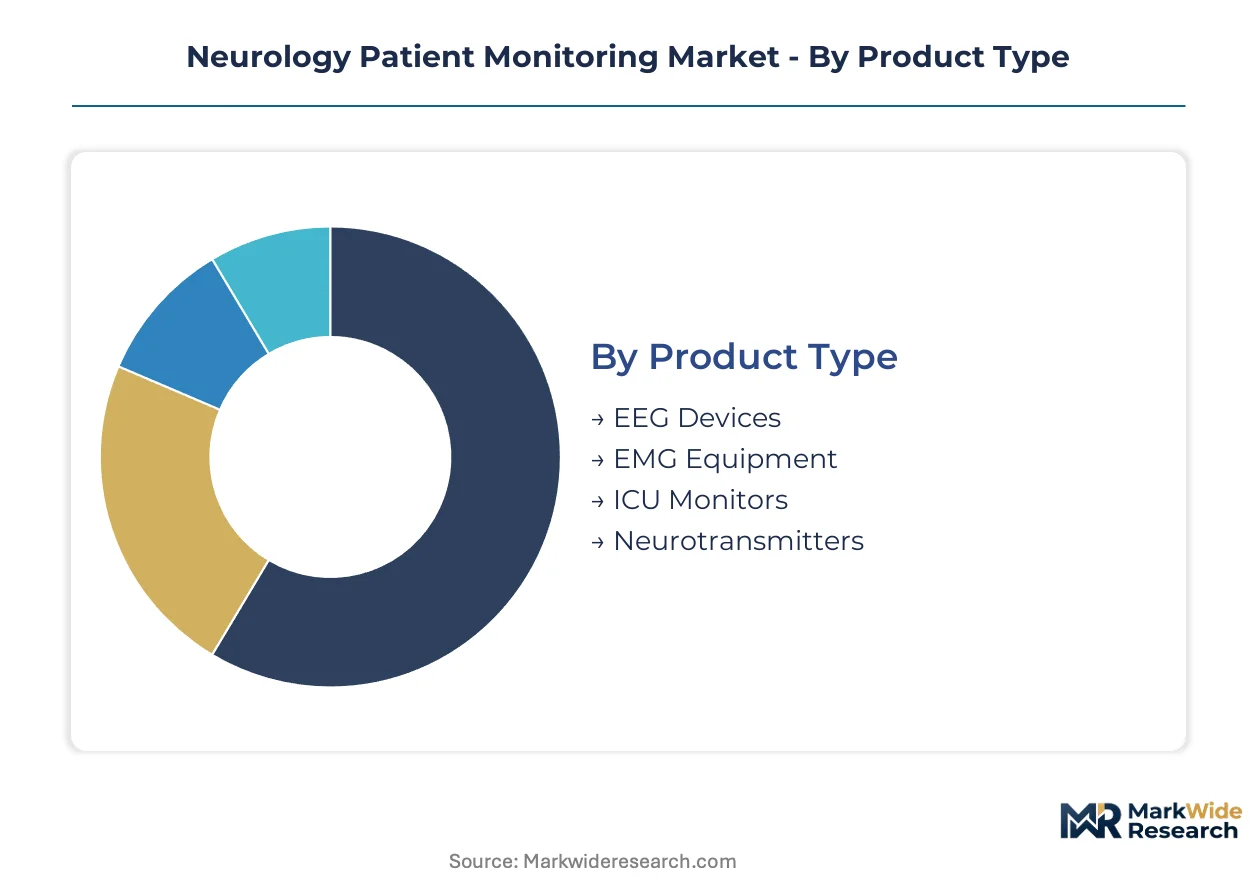
Neurology patient monitoring segments reflect divergent capital intensity and regulatory pathways. Product type stratification separates high-margin implantable hardware from recurring-revenue software services, while end-user fragmentation demands distinct go-to-market architectures across institutional and ambulatory channels.
Product Type:
Domestic production clusters in Germany and the United States dominate EEG and EMG equipment, while neurotransmitter sensing hardware relies heavily on Japanese and South Korean component imports.
- EEG Devices:Multi-channel electroencephalography systems sample cortical electrical activity at 256 Hz minimum for epileptiform detection. Demand concentrates in United States epilepsy monitoring centers and German neurocritical care units, driven by Class II FDA clearance pathways and EU MDR clinical evidence requirements that favor established manufacturers with vertically integrated electrode supply chains.
- ICU Monitors:Integrated bedside platforms combine intracranial pressure, cerebral oximetry, and continuous EEG into single displays for neurocritical care. German hospital systems and Japanese university hospitals anchor procurement volume, constrained by proprietary data formats that resist EMR integration and extend replacement cycles beyond typical medical equipment depreciation schedules.
- EMG Equipment:Electromyography systems measure peripheral nerve conduction and muscle response for neuromuscular diagnosis.
- Neurotransmitters:Microdialysis and biosensor platforms detect glutamate, lactate, and pyruvate in brain extracellular fluid.
EEG devices hold the largest share; momentum sits with ICU monitors.
Technology:
Cost tier separation distinguishes capital-intensive hardware installations from software-as-a-service models with lower upfront commitment and higher lifetime value capture.
- Cloud-Based Solutions:Centralized data architectures enable multi-site neurology networks to pool interpretation expertise across dispersed facilities. United States integrated delivery networks and German hospital alliances drive subscription revenue, accelerated by HIPAA-compliant hosting infrastructure and EU GDPR data localization requirements that favor regional cloud providers.
- Wearable Devices:Ambulatory EEG and motion sensors extend monitoring from hospital wards to patient homes for post-acute stroke and epilepsy surveillance. Japanese health ministries and German statutory insurers are expanding reimbursement codes for remote monitoring, though skin-contact biocompatibility standards and battery longevity constraints limit continuous wear duration.
- Wireless Monitoring:Radio-frequency and Bluetooth-enabled systems eliminate tethered connections for mobile patients.
- Telemetry Systems:Hardwired bedside networks remain standard for high-acuity neurocritical care where signal fidelity cannot degrade.
Telemetry systems retain dominant installed base; wearable devices are gaining share fastest.
End User:
Customer type fragmentation spans high-volume institutional purchasers with concentrated buying power and dispersed ambulatory operators with price-sensitive procurement patterns.
- Hospitals:Academic medical centers and community hospital systems command the deepest procurement budgets for multi-modal neurology platforms. United States mega-systems negotiate enterprise-wide critical care informatics contracts that embed neurology modules, while Japanese university hospitals prioritize high-channel-count EEG for research-correlated clinical care.
- Home Care:Post-acute stroke surveillance and chronic epilepsy management are decentralizing from institutional settings to patient residences. German home health services and United States Medicare Advantage plans are piloting remote patient monitoring reimbursement, contingent on FDA-cleared algorithms that automate event detection without specialist interpretation.
- Rehabilitation Centers:Skilled nursing and post-acute facilities deploy simplified monitoring for recovery assessment.
- Research Institutes:Academic neuroscience laboratories purchase high-density electrode arrays for experimental protocols.
Hospitals command the largest revenue pool; home care shows steepest expansion trajectory.
Application:
Application maturity varies by clinical evidence depth and reimbursement certainty, with well-established indications subsidizing emerging use case development.
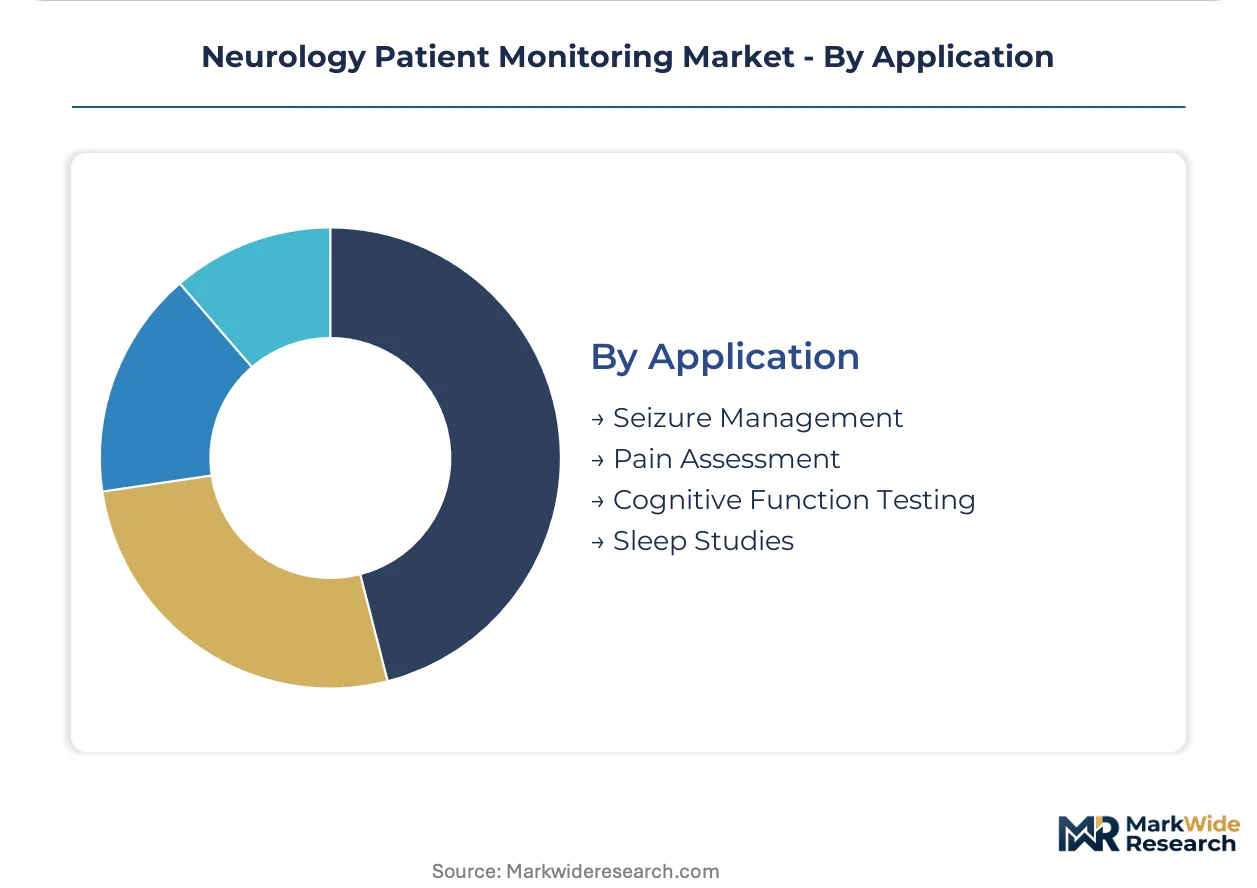
- Seizure Management:Continuous and intermittent EEG monitoring for epilepsy diagnosis and treatment optimization represents the most reimbursed indication across United States, German, and Japanese health systems. Long-term video-EEG monitoring in specialized epilepsy centers generates recurring electrode and technologist interpretation revenue that sustains manufacturer margin pools.
- Sleep Studies:Polysomnography and home sleep apnea testing leverage overlapping EEG, EMG, and respiratory sensing hardware. United States independent diagnostic testing facilities and Japanese sleep disorder centers drive demand, though reimbursement compression for routine obstructive sleep apnea diagnosis constrains pricing power for commoditized channel configurations.
- Pain Assessment:Quantitative sensory testing and evoked potential monitoring for chronic pain objectification.
- Cognitive Function Testing:EEG-based attention and memory assessment for dementia and traumatic brain injury.
Seizure management dominates revenue contribution; sleep studies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters for neurology monitoring hardware concentrate in Germany, the United States, and Japan, with component sourcing dependencies spanning South Korean semiconductors and Japanese precision sensors.
United States
Academic medical centers in Boston and Baltimore drive demand for high-channel-count EEG systems. FDA premarket notification pathways for AI-enabled seizure detection algorithms compress commercialization timelines for software developers. The Research Triangle Park corridor in North Carolina anchors neurotechnology R&D concentration.
Germany
Neurocritical care infrastructure expansion in university hospitals creates procurement pull for integrated bedside platforms. EU MDR clinical evidence requirements enforce stringent performance documentation for neurology monitors. The Baden-Württemberg medical technology cluster around Tübingen and Freiburg specializes in precision electrode manufacturing.
Japan
PMDA quality management system inspections for foreign manufacturers shape market entry strategies. Aging demographics and stroke incidence rates accelerate hospital neurology department investment. The Kansai region around Osaka hosts concentrated medical device distribution networks serving domestic hospital systems.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement eligibility for continuous EEG monitoring. MHRA post-Brexit regulatory divergence creates parallel conformity assessment requirements. London teaching hospitals pilot centralized interpretation networks for multi-site epilepsy monitoring.
South Korea
MFDS medical device approval timelines influence regional product launch sequencing. Government health technology assessment programs evaluate cost-effectiveness of neurocritical care platforms. The Seoul Capital Area concentrates domestic hospital procurement decision-making for advanced monitoring systems.
Neurology Patient Monitoring Market Key Industry Players
Concentration sits with diversified medical technology conglomerates and specialized neurodiagnostic firms. The vendor landscape exhibits tiered structure, with premium-tier players commanding integrated critical care informatics contracts and mid-tier specialists dominating electrode consumables and niche applications. Two strategic archetypes predominate: vertically integrated neurosurgery portfolio holders and modular software-as-a-service platform builders. Competitive dynamics center on M&A activity targeting AI-enabled analytics capabilities and strategic partnerships bridging hardware manufacturers with cloud infrastructure providers.
Within the diversified medical technology tier, Medtronic and Koninklijke Philips exemplify scale-driven platform strategies, while Natus Medical occupies a specialist position in electrophysiological diagnostic systems. These three anchors represent divergent approaches to value capture—implantable hardware integration, enterprise informatics embedding, and dedicated neurodiagnostic focus respectively.
| Leading Market Players |
|---|
| Medtronic |
| Natus Medical |
| Integra LifeSciences |
| Koninklijke Philips |
| Nihon Kohden Corporation |
| GE Healthcare |
| Raumedic AG |
| Sophysa |
| Spiegelberg GmbH |
| Others |
Cost & Logistics Intelligence
FDA premarket notification pathways for Class II EEG devices gate both supplier qualification and price differentiation simultaneously, with 510(k) clearance tiers separating premium multi-channel systems from economy-grade ambulatory monitors while electrode material sourcing constraints compress margin pools across certification levels.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across the neurology monitoring landscape, with high-channel-count EEG systems commanding premium positioning against economy ambulatory devices. Three-tier pricing structure across premium, standard, and economy levels reflects electrode array density, software analytics bundling, and interpretation service inclusion. Cost compression in the standard tier is intensifying because health system procurement consolidation demands unbundled hardware-acquisition models. Community hospital systems exhibit highest price sensitivity due to capital budget constraints, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes disrupt inbound logistics for Japanese precision sensors and South Korean semiconductor components essential to EEG signal processing hardware. Manufacturing concentration in Germany, the United States, and Japan draws from silver-silver chloride electrode materials, high-density interconnect substrates, and biocompatible polymers. Single-source vulnerability sits with concentrated Japanese suppliers of microelectromechanical pressure sensors for intracranial monitoring. Distribution runs through specialized medical device distributors serving hospital systems and direct enterprise contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the neurology patient monitoring landscape as post-acute surveillance decentralization creates specialized niches for wearable EEG systems and cloud-based interpretation services outside traditional hospital procurement channels.
For Market Incumbents: Shield installed base revenue through captive electrode supply agreements that lock hospital systems into recurring consumable contracts. Deepen backward integration into precision electrode manufacturing to neutralize silver-silver chloride sourcing volatility. Prioritize ISO 13485 certification investment for software-as-a-service modules to isolate regulatory exposure from hardware refresh cycles.
For New Entrants and Emerging Players: Differentiate on AI-enabled seizure forecasting algorithms that bypass specialist interpretation bottlenecks in community hospital settings. Target home-based epilepsy monitoring as the most penetrable white space, where Medicare Advantage reimbursement pilots and German statutory insurance code expansions create first-mover windows. Pursue strategic partnerships with regional cloud infrastructure providers to satisfy HIPAA and GDPR data localization requirements without capital-intensive hosting buildout.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-as-a-service neurology analytics, shifting value capture from hardware manufacturers to algorithm developers. Five-to-ten year viability favors modular platform builders with separately certifiable AI components over monolithic hardware vendors. Acquisition target archetype: specialized EEG analytics firms with FDA-cleared seizure detection algorithms and established hospital pilot programs. Signal to watch: EU AI Act high-risk system classification enforcement driving compliance cost divergence between European and non-European software developers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI-Enabled Seizure Detection | 510(k) clearance accelerates commercialization timelines for software-enhanced EEG systems against predicate devices. |
| CE Marking Pathway under EU MDR | Clinical evidence requirements enforce performance documentation that favors established manufacturers with vertically integrated supply chains. |
| Hospital System Partnership for Enterprise Informatics | Integrated delivery network contracts consolidate interpretation services across affiliated facilities, locking in multi-year revenue streams. |
| Software Companion Development for Wearable EEG | Cloud-connected ambulatory systems extend monitoring from wards to homes, capturing fastest-expansion segment in post-acute stroke surveillance. |
| Reimbursement Strategy for Remote Patient Monitoring | CPT code expansion and Medicare Advantage pilot programs determine addressable market size for home-based epilepsy management. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) databases, EU MDR notified body documentation, and hospital procurement contract filings. Clinicians, biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs specialists at device manufacturers provided operational perspective. Secondary validation drew from CMS Medicare reimbursement data, Japanese PMDA quality system inspection records, and German statutory health insurance technology assessment reports. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, technology, end user, and application dimensions.
Segmentation dimensions modeled include product type stratification, technology deployment architecture, end-user channel fragmentation, and application maturity tiers across the analysis window. CAGRs derived from installed base evolution, replacement cycle compression, and algorithm penetration curves in high-channel-count versus economy device categories. Forecast inputs incorporated electrode consumable attach rates, cloud subscription renewal patterns, and AI-enabled software upgrade adoption velocities.
Material uncertainties — FDA guidance evolution on continuous learning algorithms, EU AI Act enforcement intensity, silver electrode commodity price spikes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and health system decentralization velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Respiration Monitor Belt Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Remote Patient Monitoring Software Market