
 North America Neurology Monitoring Market | 2026-2036
North America Neurology Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Neurology Monitoring Market Outlook
Cloud-native analytics integration with legacy bedside neurology monitors is reshaping how electroencephalogram data flows from acquisition to clinical decision support. Philips Healthcare leverages its enterprise imaging infrastructure to anchor hospital-wide neurology data consolidation. GE Healthcare sustains deep installed-base relationships through modular hardware upgrades that extend the serviceable life of existing monitoring platforms. Medtronic Plc dominates the neurostimulator segment with proprietary implantable device ecosystems that generate recurring telemetry revenue streams.
Neurology monitoring encompasses the continuous or intermittent acquisition, processing, and interpretation of electrical, pressure, and metabolic signals from the central and peripheral nervous systems, typically sampling EEG signals at 256–1024 Hz with 16–32 bit resolution to detect epileptiform discharges, intracranial pressure variations, or sleep architecture disturbances. The primary commercial purpose is to enable timely clinical intervention in critical care, operative, and ambulatory settings where neurological deterioration carries high morbidity. Electroencephalogram devices occupy the largest revenue pool given their ubiquity in epilepsy monitoring units and operating rooms, while brain-computer interface technology represents the fastest-expanding frontier as locked-in syndrome patients and neurorehabilitation programs demand direct neural control pathways. Wireless monitoring systems are maturing rapidly as hospital IT departments prioritize interoperability with existing electronic health record architectures.
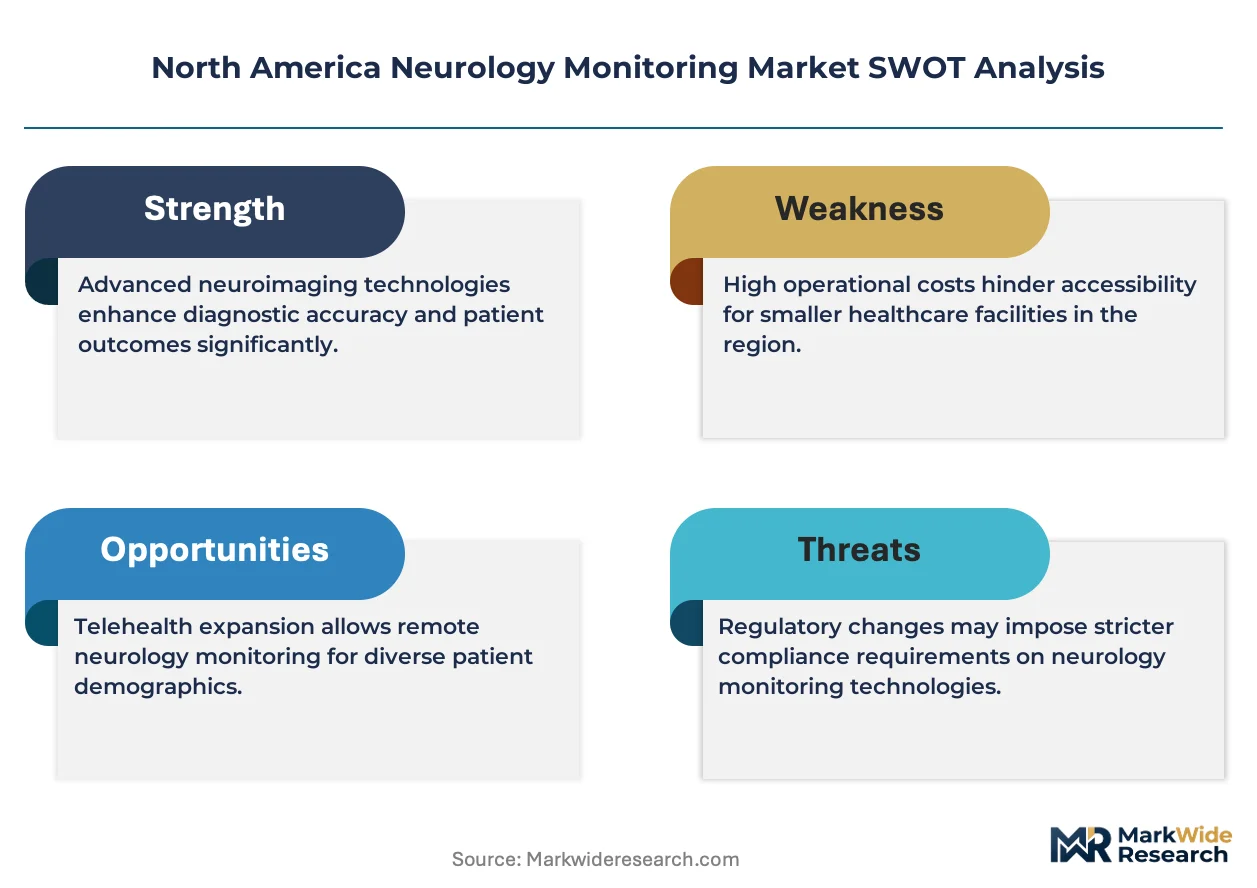
FDA 510(k) clearance pathways and Health Canada Medical Device Licensing requirements govern market entry for non-invasive neurology monitors, with FDA's Breakthrough Devices Program accelerating review for technologies addressing intractable epilepsy diagnosis. The Centers for Medicare & Medicaid Services reimbursement coding for long-term video-EEG monitoring directly shapes hospital capital allocation toward comprehensive epilepsy monitoring units. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms, as predicate device determinations for machine-learning-based seizure detection will clarify competitive positioning for emerging software-centric entrants.
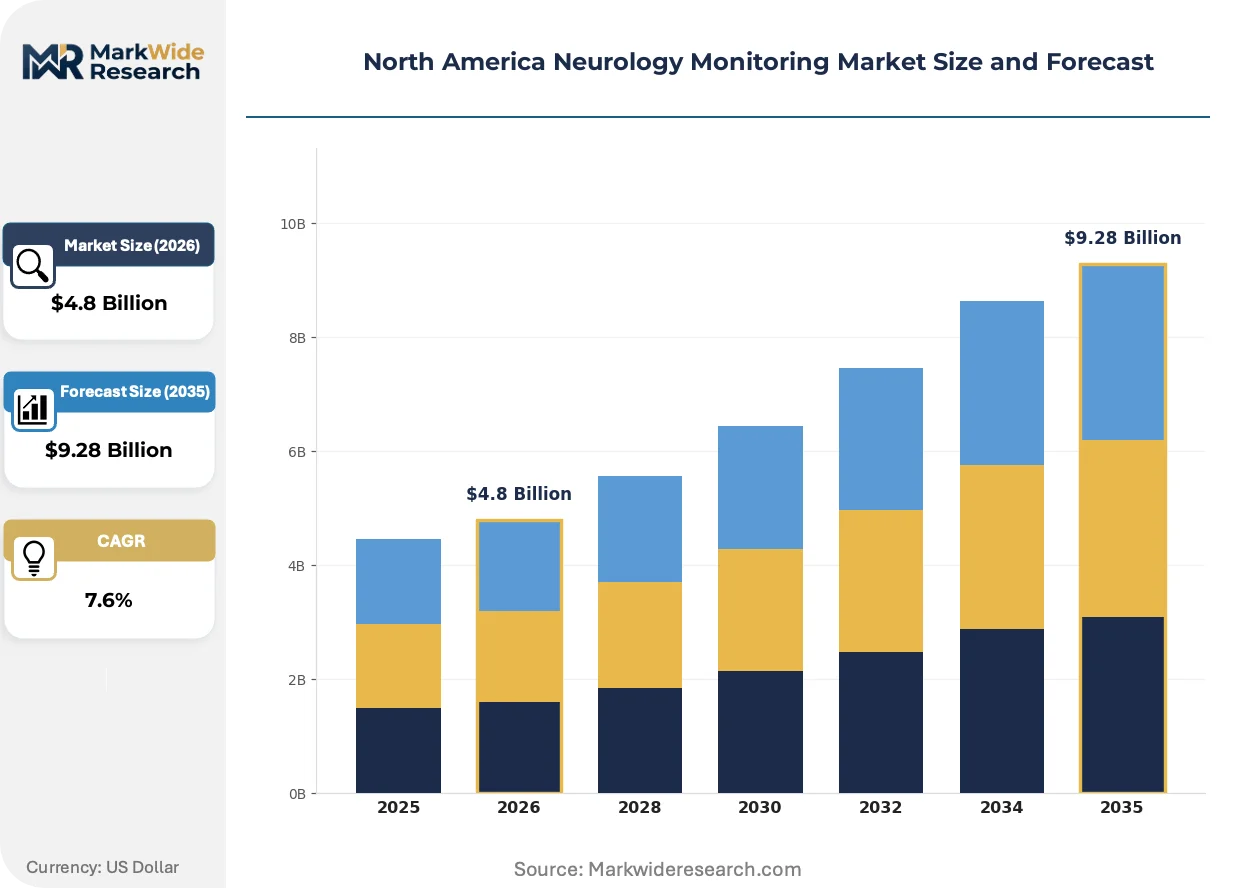
Market Dynamics
Cloud-native EEG analytics platforms are compressing the traditional hospital IT procurement cycle for neurology monitoring infrastructure, forcing vendors to restructure service delivery models around subscription-based telemetry rather than capital equipment sales.
Growth Catalysts
- FDA Breakthrough Devices Program:Accelerated review timelines for AI-enabled seizure detection algorithms compress product commercialization cycles for software-centric entrants targeting intractable epilepsy diagnosis.
- Ambulatory surgical centers:United States and Canada ASCs are expanding neurodiagnostic capabilities to capture higher-acuity cases previously routed to academic medical centers, driving demand for portable EEG systems.
- Medicaid reimbursement expansion:State-level coverage for long-term video-EEG monitoring in pediatric epilepsy cases is unlocking capital allocation for comprehensive monitoring units in community hospital settings.
Market Restraints
- Semiconductor supply concentration:Specialized analog-to-digital converters for high-resolution EEG acquisition depend on concentrated Asian foundry capacity, creating input volatility for device manufacturers.
- FDA 510(k) predicate device requirements:Machine-learning-based diagnostic algorithms face uncertain predicate determinations, extending regulatory timelines for novel software submissions.
- Wireless telemetry substitution:Consumer-grade wearable EEG headbands for sleep monitoring threaten low-end clinical device margins in ambulatory settings.
Strategic Opportunities
- Canadian provincial health systems:Ontario and Quebec are consolidating neurology service networks, creating procurement scale for enterprise-wide monitoring platform deployments.
- Brain-computer interface rehabilitation:Convergence of invasive neurostimulation with non-invasive EEG feedback loops is opening neurorehabilitation applications for stroke and spinal cord injury patients.
- CMS alternative payment models:Episode-based reimbursement for epilepsy surgery is incentivizing hospitals to invest in preoperative monitoring infrastructure to reduce readmission penalties.
Industry Challenges
- Clinical neurophysiologist shortage:Fellowship-trained epileptologists remain concentrated in major metropolitan academic centers, constraining interpretation capacity for community hospital monitoring units.
- Legacy EHR integration complexity:Bedside neurology monitors require HL7 FHIR compliance investments to achieve seamless data flow with existing hospital information architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Neurology Monitoring Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Electroencephalogram, Intracranial Pressure Monitor, Neurostimulator, Sleep Monitor End User: Hospitals, Diagnostic Laboratories, Research Institutes, Homecare Settings Application: Seizure Monitoring, Sleep Disorders, Brain Tumor Detection, Anesthesia Monitoring Technology: Wireless Monitoring, Brain-Computer Interface, Advanced Imaging, Mobile Applications |
| Companies Covered | Natus Medical, Inc., Philips Healthcare, GE Healthcare, Medtronic Plc, Nihon Kohden Corporation, Drägerwerk Ag & Co. Kgaa, Siemens Healthineers, Masimo Corporation, Compumedics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Neurology Monitoring Market Strategic Shifts
Artificial intelligence inference at the edge is restructuring how raw EEG signals transform into actionable clinical alerts, compressing the latency between seizure onset and caregiver notification while raising new questions about algorithmic liability and clinical workflow integration.
High-density dry-electrode EEG arrays are migrating from research laboratory settings into operative and emergency department environments. Anesthesiology departments at tertiary care centers in Boston and Houston are piloting these systems for intraoperative neurophysiological monitoring during cerebrovascular procedures. The shift is enabling real-time cortical mapping without conductive gel preparation, compressing setup time from fifteen minutes to under ninety seconds and expanding monitoring feasibility in time-critical surgical contexts.
Health Canada's transition toward harmonized Medical Device Single Audit Program recognition is streamlining quality system requirements for manufacturers already holding MDSAP certificates from US FDA or Brazil ANVISA audits. The policy convergence reduces redundant facility inspections for multi-market suppliers. Class III neurology implantables with telemetry components face the most significant compliance adjustments, as Canadian reviewers now demand cybersecurity documentation previously emphasized only by FDA premarket submissions.
Hospital procurement committees are unbundling neurology monitoring hardware from long-term service contracts, separating capital acquisition decisions from multi-year technical support commitments. This pattern is most visible among integrated delivery networks in Texas and California, where centralized supply chain functions now negotiate device purchases through group purchasing organizations while sourcing post-warranty maintenance through independent service organizations or in-house biomedical engineering departments.
North America Neurology Monitoring Market Segmentation
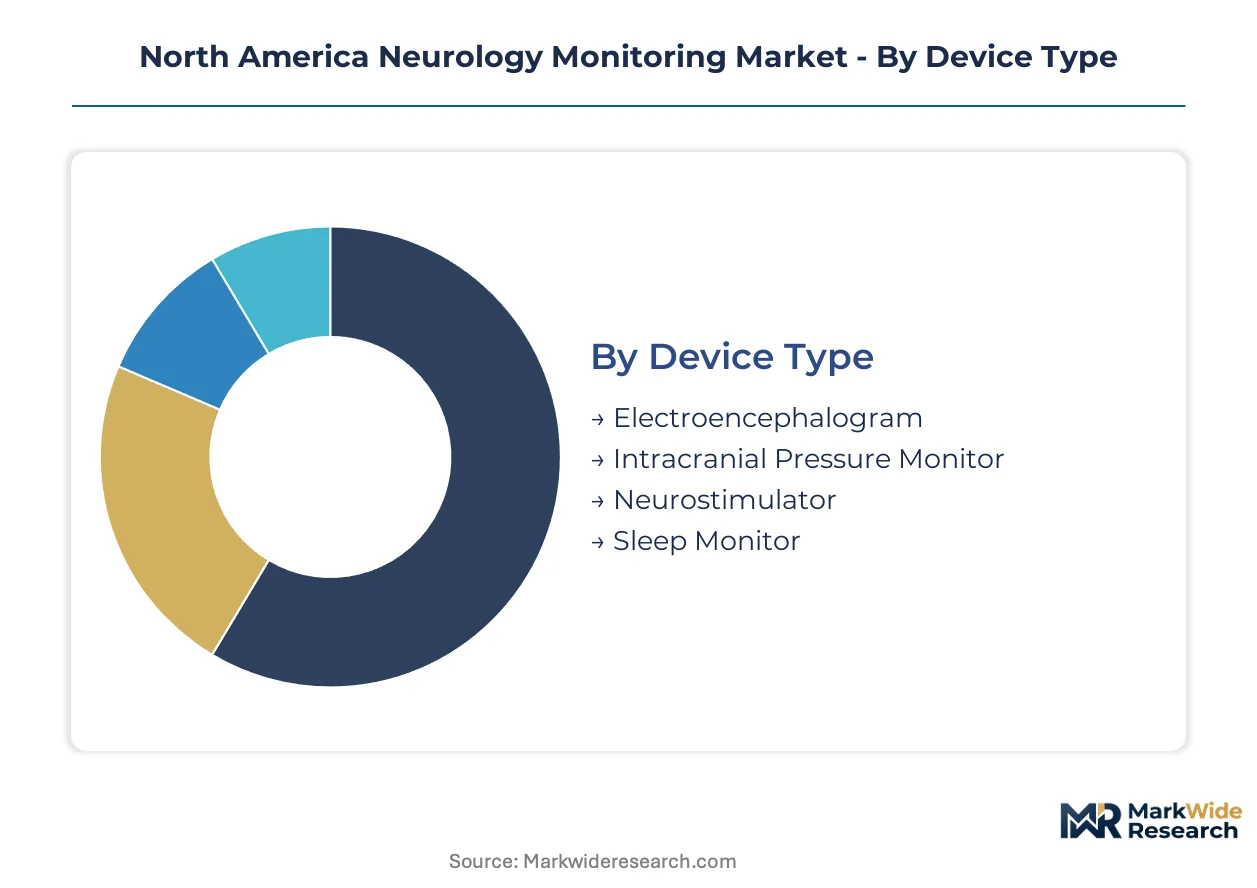
Neurology monitoring equipment spans discrete technical architectures and care settings that shape procurement patterns across North American health systems. Device specifications, reimbursement pathways, and clinical workflow integration requirements vary sharply by segment, creating differentiated competitive arenas for manufacturers.
Device Type:
Mature hardware platforms dominate hospital capital budgets while emerging modalities capture ambulatory expansion opportunities.
- Electroencephalogram:Non-invasive scalp electrodes acquire cortical electrical activity at 256–1024 Hz sampling rates. Academic medical centers in Boston, New York, and Houston drive demand for high-density arrays in epilepsy monitoring units, constrained by clinical neurophysiologist interpretation capacity.
- Intracranial Pressure Monitor:Invasive fiber-optic or strain-gauge sensors measure ventricular or parenchymal pressure in traumatic brain injury management. Neurosurgical departments at Level I trauma centers anchor procurement, with FDA 510(k) clearance timelines shaping vendor selection.
- Neurostimulator:Implantable pulse generators with telemetry-enabled remote programming.
- Sleep Monitor:Polysomnography systems and portable home sleep testing devices.
Electroencephalogram equipment handles the majority of throughput; Brain-Computer Interface represents the steepest expansion trajectory in the fastest-moving technology category.
End User:
Site-of-care migration is redistributing device specifications toward portability and simplified operation.
- Hospitals:Comprehensive neurology departments and intensive care units requiring enterprise-grade monitoring infrastructure with HL7 FHIR-compliant EHR integration. Integrated delivery networks in Texas and California concentrate procurement through group purchasing organizations.
- Diagnostic Laboratories:Centralized reference facilities processing outsourced EEG interpretation.
- Research Institutes:Academic laboratories advancing high-density dry-electrode arrays and closed-loop neurostimulation protocols.
- Homecare Settings:Ambulatory patients with remote telemetry needs for seizure detection and sleep disorder management.
Hospitals absorb the dominant share of capital expenditure; Homecare Settings is climbing fastest as reimbursement shifts toward ambulatory models.
Application:
Clinical urgency and reimbursement density determine technology investment prioritization across indication areas.
- Seizure Monitoring:Continuous video-EEG for epilepsy diagnosis and surgical candidacy assessment. CMS alternative payment models for epilepsy surgery are incentivizing preoperative monitoring infrastructure investments to reduce readmission penalties.
- Sleep Disorders:Polysomnography and home sleep apnea testing for diagnostic stratification.
- Brain Tumor Detection:Intraoperative neurophysiological monitoring during resection procedures.
- Anesthesia Monitoring:Processed EEG for depth-of-anesthesia assessment in operative settings.
Seizure Monitoring commands the largest installed base; Sleep Disorders is expanding most quickly as consumer-grade wearables create downstream clinical referral demand.
Technology:
Connectivity architecture and algorithmic capability are becoming primary vendor differentiation vectors.
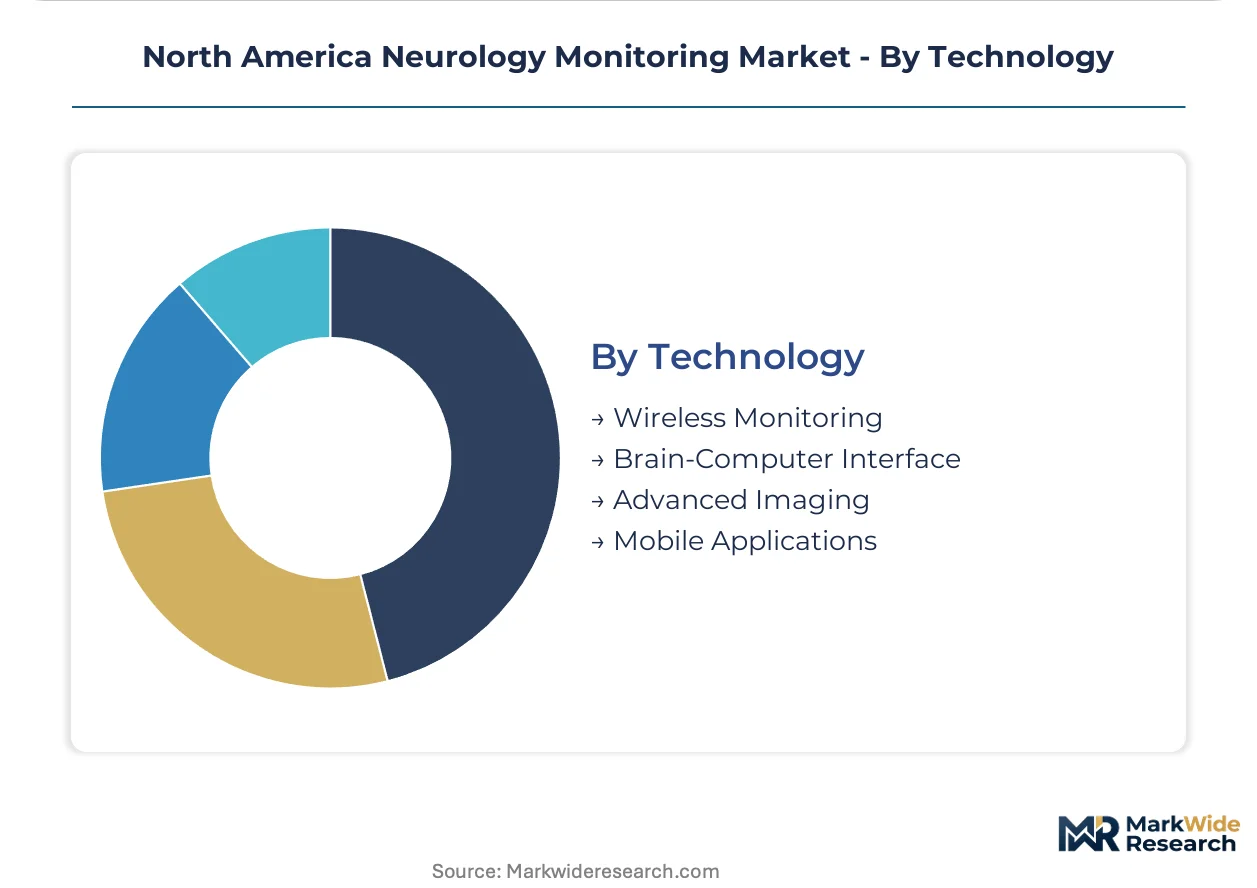
- Wireless Monitoring:Bluetooth and proprietary radio protocols enabling untethered patient mobility. Hospital IT departments in the United States prioritize interoperability with existing electronic health record architectures, constraining standalone system adoption.
- Brain-Computer Interface:Direct neural signal translation for assistive communication and neurorehabilitation. Stroke and spinal cord injury programs at tertiary centers are piloting non-invasive EEG feedback loops combined with invasive neurostimulation.
- Advanced Imaging:Functional MRI and PET integration with electrophysiological data.
- Mobile Applications:Smartphone-based patient-facing tools for symptom logging and medication adherence.
Wireless Monitoring carries the highest deployment volume; Brain-Computer Interface is gaining share fastest as locked-in syndrome and neurorehabilitation applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and ambulatory surgical centers constitute the dominant buyer archetypes across North American neurology monitoring markets, with integrated delivery networks in Texas and California concentrating purchasing power through group purchasing organizations.
United States
Academic medical centers in Boston, New York, and Houston drive adoption of advanced epilepsy and sleep disorder monitoring systems, constrained by clinical neurophysiologist interpretation capacity. FDA 510(k) clearance pathways and the Breakthrough Devices Program shape product commercialization timelines for AI-enabled diagnostic algorithms. Massachusetts General Hospital and NewYork-Presbyterian anchor high-density EEG array deployment in intraoperative neurophysiological monitoring.
Canada
Provincial health systems in Ontario and Quebec are consolidating neurology service networks, creating procurement scale for enterprise-wide monitoring platform deployments. Health Canada's Medical Device Licensing requirements and MDSAP recognition streamline quality system compliance for multi-market suppliers. Toronto's University Health Network and Montreal's McGill University Health Centre pilot closed-loop neurostimulation protocols for neurorehabilitation applications.
Mexico
Private hospital chains in Mexico City and Monterrey are expanding neurodiagnostic capabilities to capture medical tourism flows and higher-acuity domestic cases. COFEPRIS regulatory alignment with FDA standards accelerates market entry for devices already cleared in the United States. Guadalajara's technology corridor hosts emerging distributors serving northern border states and Central American markets.
North America Neurology Monitoring Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement environments, with enterprise imaging infrastructure and implantable device ecosystems representing distinct competitive moats. The market structure concentrates around diversified health technology conglomerates with deep installed-base relationships and specialized neurology device manufacturers with proprietary telemetry platforms. Three archetypes dominate: imaging-system incumbents leveraging hospital-wide data consolidation, neurostimulator specialists generating recurring revenue through remote programming, and emerging software-centric entrants targeting AI-enabled diagnostic algorithms. Competitive moves center on modular hardware upgrades extending serviceable life of existing platforms and subscription-based telemetry restructuring traditional capital equipment sales.
Within the diversified health technology tier, Philips Healthcare and GE Healthcare exemplify channel-controlling strategies anchored in enterprise imaging infrastructure and modular upgrade pathways. Medtronic Plc occupies a distinct position representing the neurostimulator specialist archetype with proprietary implantable device ecosystems. Natus Medical, Inc. and Nihon Kohden Corporation sit within the specialized neurology device manufacturer tier, with the former representing North American-focused neurodiagnostic specialists and the latter exemplifying Japanese precision instrumentation heritage in electrophysiological monitoring.
| Leading Market Players |
|---|
| Natus Medical, Inc. |
| Philips Healthcare |
| GE Healthcare |
| Medtronic Plc |
| Nihon Kohden Corporation |
| Drägerwerk Ag & Co. Kgaa |
| Siemens Healthineers |
| Masimo Corporation |
| Compumedics Limited |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in specialized analog-to-digital converter foundries across Taiwan and South Korea is forcing neurology device manufacturers to accept longer lead times and minimum order commitments, compressing margins on mid-tier EEG systems while concentrating pricing power with suppliers serving the premium implantable segment.
Pricing Analysis
Cost-plus contracts with semiconductor foundries indexed to spot wafer prices dominate component procurement, with device manufacturers passing through 60-70% of input volatility to hospital buyers via annual price adjustment clauses. Pricing stratifies across premium, standard, and economy tiers based on channel density and FDA 510(k) clearance tier. Cost compression in portable EEG systems is intensifying because consumer-grade wearable substitutes are eroding clinical device margins in ambulatory sleep monitoring. Diagnostic laboratories exhibit the highest price sensitivity due to thin interpretation margins, while academic medical centers prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Jabil, and Flex holding 70% of final assembly capacity for non-invasive neurology monitors, while specialized foundries in Taiwan, Japan, and Germany control high-resolution ADC fabrication. Raw material dependencies center on medical-grade silicon wafers, biocompatible polymers for electrode housings, and rare-earth magnets for neurostimulator pulse generators. Single-source vulnerability in 12-inch wafer supply from Taiwan creates concentrated exposure to geopolitical disruption. Distribution runs through group purchasing organizations serving integrated delivery networks, with independent service organizations capturing post-warranty maintenance revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American neurology monitoring sits in early-cycle expansion as brain-computer interface applications migrate from research settings into reimbursable neurorehabilitation protocols, with CMS alternative payment models for epilepsy surgery creating durable infrastructure demand.
For Market Incumbents: Pre-empt software-centric entrants by acquiring FDA Breakthrough Device designation for AI-enabled seizure detection algorithms before predicate device determinations solidify competitive moats. Defend installed-base relationships through modular hardware upgrades extending serviceable life of existing EEG platforms, while backward integration into cloud-native analytics development reduces dependency on third-party telemetry vendors facing cybersecurity compliance headwinds from Health Canada.
For New Entrants and Emerging Players: Build out white-space positions in Canadian provincial health system consolidations, where Ontario and Quebec are sourcing enterprise-wide monitoring platforms without legacy vendor lock-in. Target ambulatory surgical centers in Texas and California with portable, gel-free EEG systems that compress setup time below two minutes. Pursue GPO contracts through independent service organization partnerships rather than direct hospital sales force investment.
For Investors and Strategic Acquirers: Capital is best deployed toward neurostimulator specialists with proprietary telemetry ecosystems generating recurring remote programming revenue, as these assets command premium multiples due to implantable device switching costs. Long-term viability hinges on FDA 510(k) clearance velocity and CMS reimbursement coding expansion. The signal to watch is Health Canada's MDSAP cybersecurity documentation requirements, which will filter acquisition targets based on compliance infrastructure maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses commercialization timelines for AI-enabled seizure detection algorithms. |
| Hospital System Partnership | Enterprise-wide deployments with integrated delivery networks in Texas anchor recurring telemetry revenue. |
| Software Companion Development | Cloud-native analytics integration with legacy bedside monitors extends hardware serviceable life. |
| Reimbursement Strategy | CMS alternative payment models for epilepsy surgery incentivize preoperative monitoring infrastructure. |
| CE Marking Pathway | Health Canada MDSAP recognition streamlines quality system compliance for multi-market suppliers. |
Study Parameters
Desk research of FDA 510(k) clearance databases, Health Canada Medical Device Licensing records, and CMS reimbursement coding precedents preceded structured interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and clinical neurophysiologists at academic medical centers in Boston, Houston, and Toronto. Secondary validation drew from SEC 10-K filings of diversified health technology conglomerates, hospital procurement databases, and GPO contract award disclosures. Bottom-up unit economics triangulated against top-down market sizing across device type, end user, and technology segmentation dimensions.
Assumptions held fixed include FDA 510(k) predicate device determination timelines and CMS reimbursement coding stability, while variables tested included semiconductor supply chain disruption scenarios and Health Canada MDSAP implementation pace. The analytical framework modeled volume and value outputs across the projection horizon by device architecture, care setting, and connectivity protocol. CAGRs derived from regression analysis of historical capital equipment procurement cycles and ambulatory surgical center expansion trajectories. Industry-specific inputs included clinical neurophysiologist fellowship graduation rates and hospital IT department HL7 FHIR compliance investment schedules.
Practitioners should monitor FDA guidance on artificial intelligence-enabled diagnostic algorithms and Health Canada cybersecurity documentation requirements for early signals of regulatory timeline compression or expansion. Forecasts reflect assumptions regarding reimbursement stability and supply chain normalization that could revise materially under sustained semiconductor shortage or CMS coding restriction scenarios. Quarterly review of GPO contract award flows and provincial health system RFP issuance patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Intracranial Aneurysm Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Neurology Software Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Cluster Headache Syndrome Market
Neurology
Bell Palsy Treatment Market
Neurology
South Korea Neurology Devices Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
Moyamoya Disease Market
Neurology
3D Neuroscience Market
Neurology
India Neurology Devices Market
Neurology
Hydrocephalus Market
Neurology
Narcolepsy Treatment Market
Neurology
Global Acoustic Neuroma Market