
 Global Skin Tears Treatment Market | 2026-2036
Global Skin Tears Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Skin Tears Treatment Market Intelligence
Advanced silicone-adhesive specifications is unwinding outdated acrylic-based standards across skin tears treatment portfolios. Smith & Nephew plc leverages its R&D intensity to develop conformable dressings for fragile epidermis. Cardinal Health Inc. anchors North American distribution through direct-to-facility logistics networks. Coloplast A/S specializes in hydrocolloid platforms tailored to geriatric wound environments.
Skin tears treatment encompasses sterile wound dressings, barrier films, and tissue adhesives engineered for partial-thickness injuries on aged or compromised skin, typically manufactured with vapor-permeable polyurethane backings and low-adhesion contact layers to prevent secondary trauma during removal. Foam dressing and silicone gel sheet segments lead value generation due to extended wear times and reduced dressing-change frequency in long-term care settings. Alginate and hydrogel categories occupy faster-growing niches where exuding or dehydrated wound beds require adaptive moisture management.
FDA 510(k) clearance pathways and the EU MDR clinical evaluation requirements shape product development timelines and market access costs for manufacturers seeking multi-regional registration. Japan's PMDA and the EU AI Act's emerging clinical decision-support rules will influence how dressing selection algorithms integrate into electronic health records. Stakeholders must monitor regulatory divergence between FDA's predicate-device framework and MDR's stricter clinical evidence demands when prioritizing R&D allocation and geographic launch sequencing.
Market Dynamics
Silicone-adhesive dressings are compressing acrylic-based standards as long-term care facilities prioritize trauma-free removal protocols for fragile geriatric skin. This materials transition is reshaping procurement specifications, R&D allocation, and regulatory submission strategies across wound care portfolios.
Growth Catalysts
- Aging demographics in Japan, Germany, and the United States:Expanding elderly populations create sustained demand for specialized wound care in institutional settings. Long-term care facilities now specify advanced dressings in tender documents.
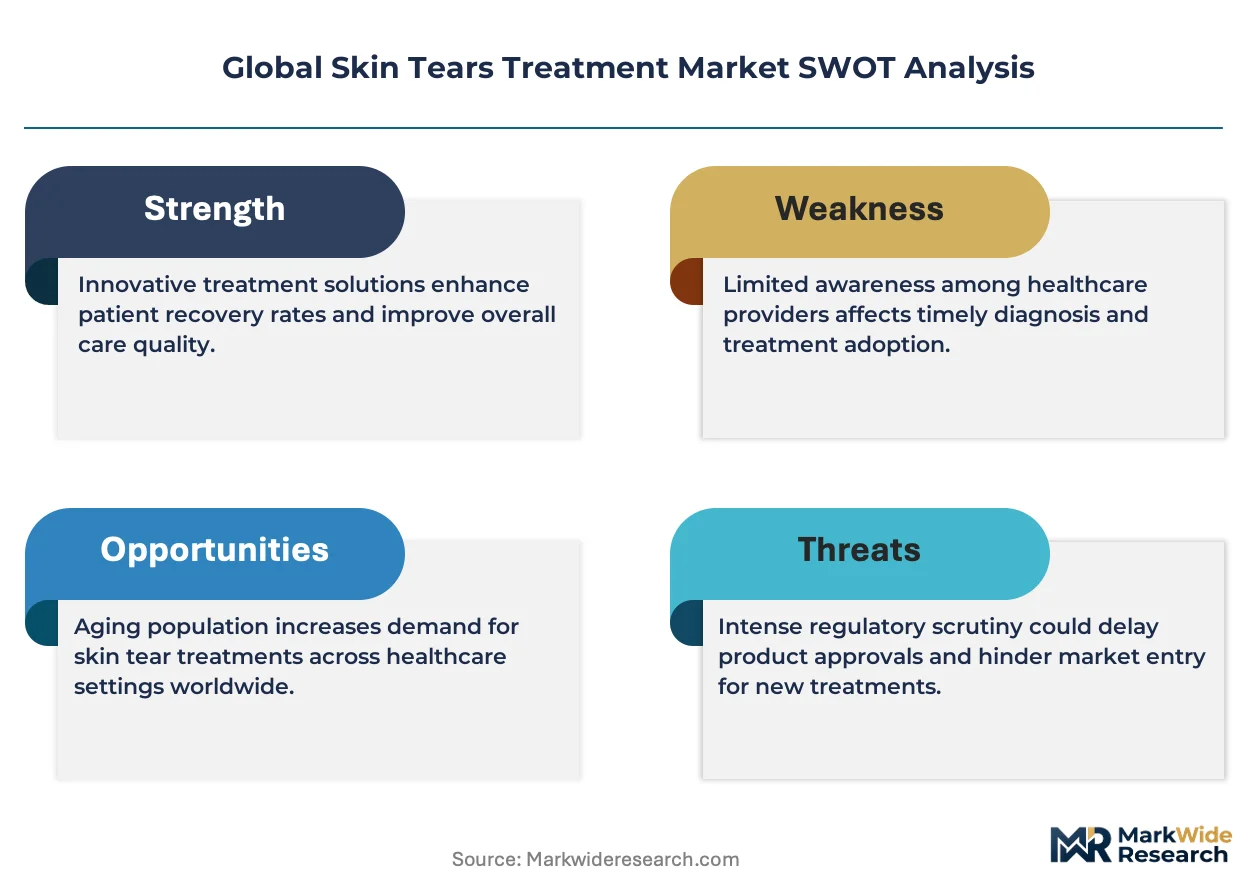
- EU MDR clinical evidence requirements:Stricter post-market surveillance mandates elevate barrier-to-entry for antimicrobial and silicone-based products. Incumbent manufacturers with established clinical data portfolios capture share from smaller competitors.
- Extended wear-time technologies:Vapor-permeable polyurethane backings with low-adhesion contact layers reduce dressing-change frequency. Nursing labor cost savings drive facility-level adoption.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone suppliers in Germany and Japan control feedstock for advanced adhesive layers. Price volatility in organosilicon compounds compresses dressing margins.
- EU MDR clinical evaluation costs:Small and mid-sized manufacturers face disproportionate burden for clinical evidence generation. Market consolidation accelerates as undercapitalized players exit.
- Acrylic adhesive substitution in price-sensitive channels:Standard hydrocolloids retain share in emerging markets where reimbursement does not differentiate silicone performance. Procurement offices prioritize unit cost over total wound-care cost.
Strategic Opportunities
- Underpenetrated long-term care infrastructure in India:Private eldercare chains in Maharashtra and Karnataka are upgrading wound care protocols. Early-mover manufacturers can establish specification relationships before tender standardization.
- Convergence of moisture-responsive hydrogels with antimicrobial silver:Adaptive dressings for exuding wounds address unmet need in diabetic skin tear management. Product development pipelines in South Korea and Switzerland target this white space.
- Japan's PMDA fast-track pathway for geriatric-focused devices:Priority review designation accelerates market access for dressings with elderly-specific clinical data. Sponsors with Japan-centric trial designs capture first-mover advantage.
Industry Challenges
- Specialized wound-care nurse certification timelines:Advanced dressing application protocols require trained personnel. Long-term care facilities in the United States face recruitment gaps for certified wound ostomy continence nurses.
- Legacy electronic health record integration:Dressing selection algorithms must interface with fragmented hospital IT systems. Software validation for clinical decision-support tools delays deployment under EU AI Act emerging requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Skin Tears Treatment Market |
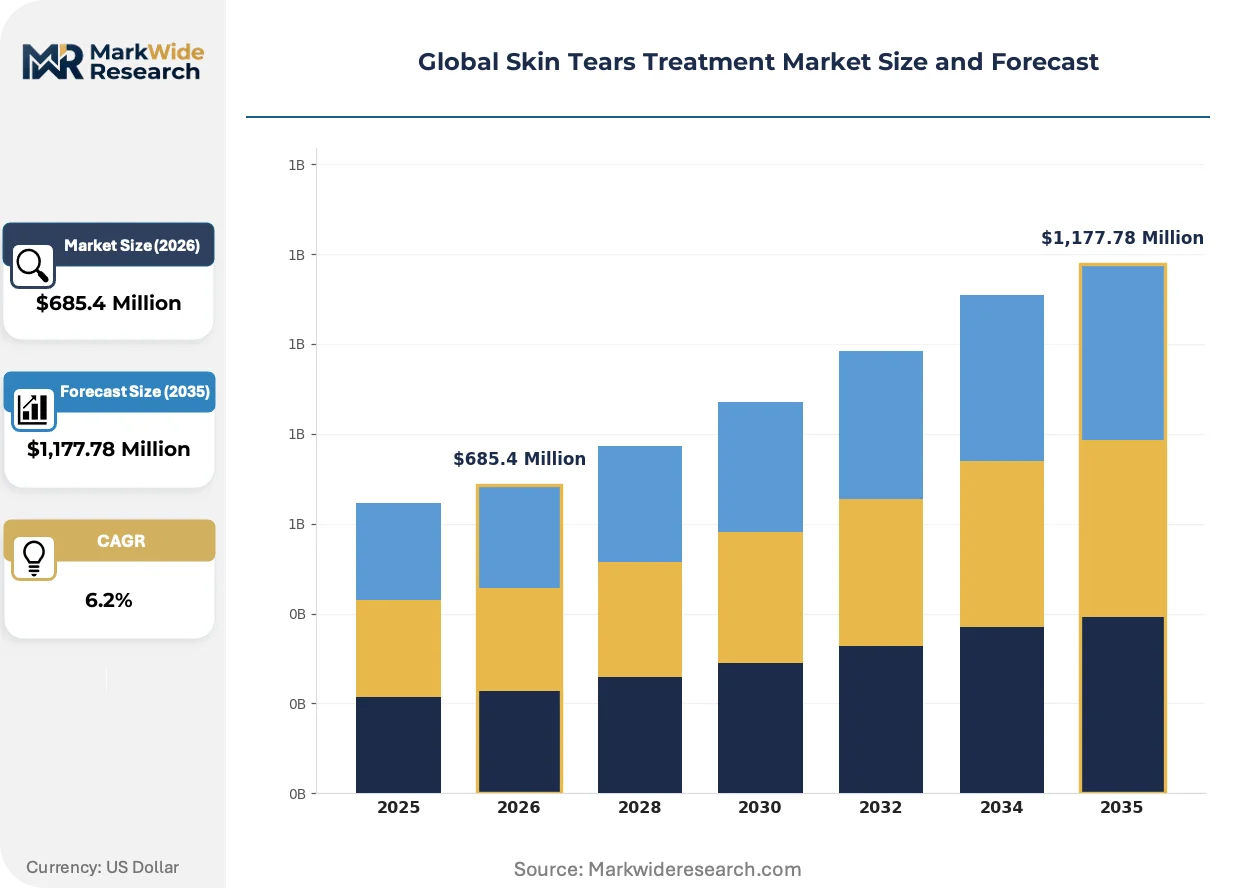
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Foam Dressing, Alginate, Silicone Gel Sheet, Film Dressing, Hydrocolloid Application: Hospice Care, Long-Term Care, Acute Care, Home Healthcare, Rehabilitation Centers, Geriatric Wards End User: Specialty Clinics, Nursing Facilities, Ambulatory Surgical Centers, Assisted Living Facilities, Private Practices Distribution Channel: Pharmacies, Hospitals, Online Retailers, Medical Supply Distributors, Direct Sales |
| Companies Covered | Solventum Corporation, Smith & Nephew plc, Cardinal Health Inc., ConvaTec Group plc, Molnlycke Health Care, Coloplast A/S, Hollister Inc., 3M Company, Covalon Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Skin Tears Treatment Market Strategic Shifts & Innovations
Materials science advances and regulatory recalibration are converging to redefine performance benchmarks in skin tear management. Manufacturers now compete on clinical evidence depth rather than commodity pricing.
Silicone gel sheets with patterned micro-structures are supplanting flat-sheet designs in European long-term care procurement. German and Dutch facility networks specify conformable dressings that adapt to anatomical contours. This specification shift is compressing standard foam dressing margins while expanding addressable market for premium-tier products.
EU MDR post-market clinical follow-up requirements are extending product lifecycle costs for antimicrobial dressings. Manufacturers must commit to ongoing safety surveillance rather than one-time premarket submissions. Silicone-based portfolios with existing clinical data repositories in Germany and France face lower incremental compliance burden than new market entrants.
Long-term care procurement offices are consolidating vendor relationships around single-source contracts with outcome guarantees. Group purchasing organizations in the United States now bundle dressing supply with staff training and wound-healing rate commitments. This contractual evolution is visible in California and Texas, where multi-facility operators negotiate enterprise-level agreements replacing transactional purchasing.
Global Skin Tears Treatment Market Segmentation
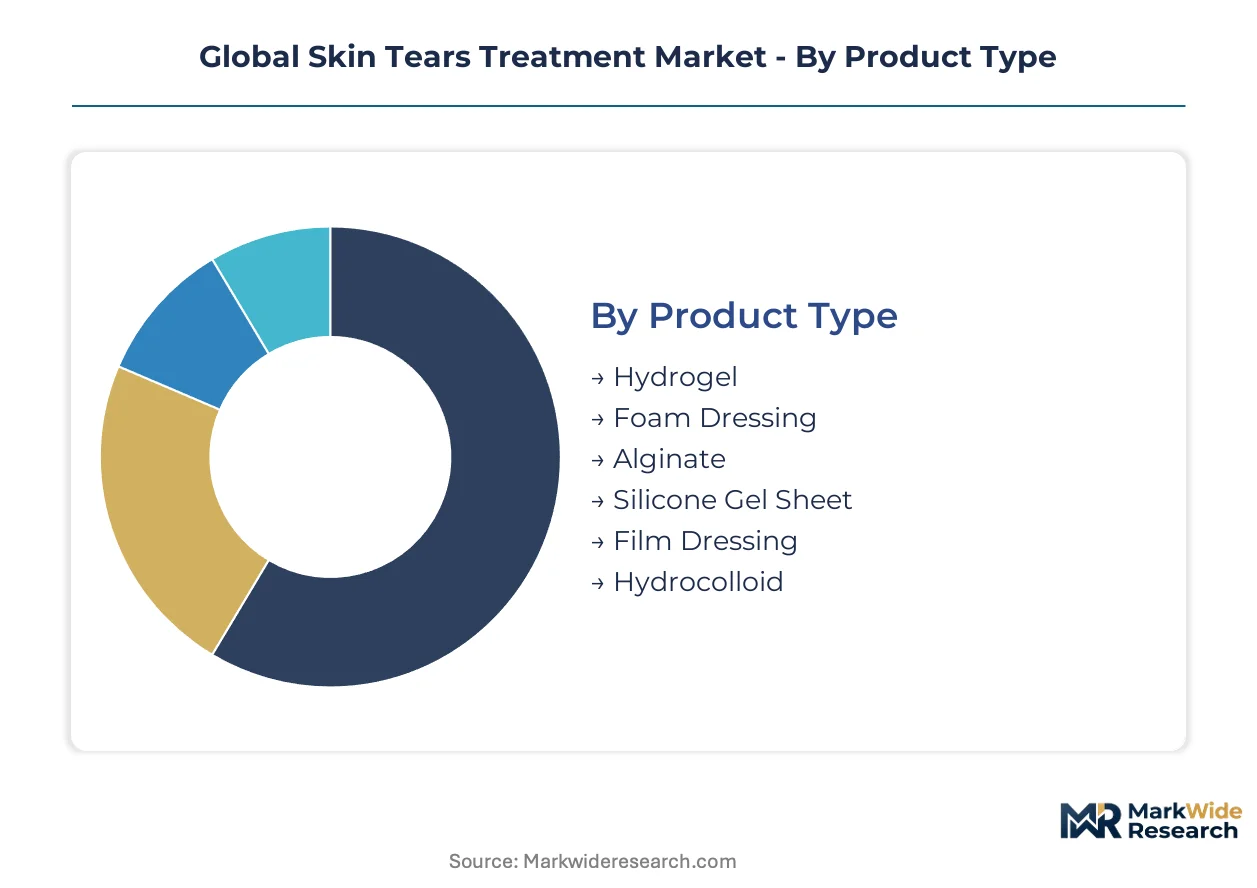
Segmentation in skin tears treatment reveals how material science innovations and care-setting economics create divergent growth trajectories across product categories. Procurement specifications in long-term care facilities now differentiate segments by wear-time performance and removal trauma risk rather than unit cost alone.
Product Type:
Silicone-adhesive platforms face intensifying substitution pressure from advanced hydrogel composites in exuding wound applications, while acrylic-based hydrocolloids retreat to price-sensitive channels.
- Foam Dressing:Vapor-permeable polyurethane constructions with multi-layer absorption cores manage moderate exudate in institutional settings. Demand concentrates in German and United States long-term care networks where extended wear protocols reduce nursing labor burden. Reimbursement codes in these markets explicitly reward reduced dressing-change frequency.
- Silicone Gel Sheet:Soft-solid polydimethylsiloxane matrices with patterned micro-structures conform to anatomical contours without adhesive trauma. Japanese geriatric wards and Dutch facility networks specify these for fragile epidermis cases where secondary injury prevention outweighs material cost premiums.
- Hydrogel:Cross-linked polymer networks with adaptive moisture donation target dehydrated wound beds in hospice environments.
- Alginate:Calcium-sodium fiber dressings derived from brown seaweed address heavy exudate through gel-forming ion exchange.
- Film Dressing:Thin polyurethane membranes with acrylic adhesive perimeter secure IV sites and superficial tears in acute care.
- Hydrocolloid:Gelatin-pectin-carboxymethylcellulose matrices retain share in emerging markets where procurement prioritizes unit economics over total wound-care cost.
Foam dressing anchors the volume base while silicone gel sheet gains share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive acute care protocols from labor-optimized long-term care environments, with reimbursement intensity determining technology penetration depth.
- Long-Term Care:Skilled nursing facilities and residential care homes generate concentrated demand for multi-day wear dressings with simplified application protocols. California and Texas multi-facility operators negotiate enterprise supply agreements bundling product with staff training and outcome guarantees.
- Acute Care:Hospital-based wound services prioritize rapid healing metrics and infection control in shorter patient stays. German DRG-based reimbursement accelerates adoption of antimicrobial-integrated platforms despite premium pricing.
- Hospice Care:Comfort-focused protocols in end-of-life settings emphasize pain minimization over healing velocity.
- Home Healthcare:Dispensing through visiting nurse services requires patient-friendly application without specialized training.
- Rehabilitation Centers:Post-acute recovery facilities balance mobility restoration with wound protection.
- Geriatric Wards:Hospital-based elderly care units face staffing ratios that limit dressing-change capacity.
Long-term care commands the dominant revenue share while home healthcare climbs the fastest as aging-in-place policies redirect patient volume.
End User:
Customer-type concentration around institutional procurement offices creates volume aggregation effects that reshape manufacturer channel strategy and pricing architecture.
- Nursing Facilities:Medicaid-reimbursed skilled nursing operations in the United States drive standardized tender specifications across multi-state operator networks. Group purchasing organizations consolidate vendor relationships around single-source contracts with healing-rate commitments.
- Assisted Living Facilities:Residential care settings with lower acuity mix adopt simplified dressing protocols for resident-managed or family-assisted application. Maharashtra and Karnataka private eldercare chains in India upgrade wound care standards ahead of regulatory harmonization.
- Specialty Clinics:Wound care centers with certified nurse specialists prescribe advanced modalities.
- Ambulatory Surgical Centers:Same-day procedure settings require rapid-application products.
- Private Practices:Individual physician offices rely on distributor relationships for inventory management.
Nursing facilities anchor procurement volume while assisted living facilities expand most quickly as residential care substitutes for institutional placement.
Distribution Channel:
Supply concentration among specialized medical distributors creates margin pressure on manufacturers while direct sales models capture premium accounts with training-intensive products.
- Medical Supply Distributors:Cardinal Health and similar operators maintain North American logistics networks with direct-to-facility delivery and inventory management services. These intermediaries aggregate demand across hundreds of facilities to negotiate manufacturer rebates.
- Direct Sales:Manufacturer field forces serve large multi-facility operators with customized protocol development and staff certification programs. Smith & Nephew and Coloplast deploy clinical specialists to support silicone-adhesive adoption in European long-term care networks.
- Hospitals:Central supply departments within integrated delivery networks standardize formularies.
- Pharmacies:Retail and long-term care pharmacy chains handle lower-acuity home use cases.
- Online Retailers:E-commerce platforms serve direct-to-consumer demand for maintenance supplies.
Medical supply distributors control the broadest reach while direct sales captures the highest-margin accounts with outcome-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty silicone feedstock production clusters in Germany and Japan concentrate supply for advanced adhesive layers. These manufacturing hubs shape regional competitive dynamics through feedstock access and clinical evidence generation capacity.
United States
Medicaid-reimbursed skilled nursing facilities in California and Texas drive enterprise-level procurement contracts bundling dressings with outcome guarantees. FDA 510(k) clearance pathways enable faster market access for predicate-device submissions. Cardinal Health anchors North American distribution through direct-to-facility logistics networks serving multi-state operator clusters.
Germany
DRG-based hospital reimbursement accelerates antimicrobial-integrated dressing adoption despite premium pricing. EU MDR clinical evaluation requirements elevate barriers for new entrants without established clinical data portfolios. Organosilicon compound suppliers in the Rhine-Ruhr industrial region control medical-grade silicone feedstock for advanced adhesive manufacturing.
Japan
PMDA fast-track designation for geriatric-focused devices accelerates market access for sponsors with elderly-specific trial data. Aging demographics in Tokyo and Osaka metropolitan areas expand the institutional patient pool for specialized wound care. Smith & Nephew deploys clinical specialists to support silicone-adhesive specification in Kanto region long-term care networks.
India
Private eldercare chains in Maharashtra and Karnataka upgrade wound care protocols ahead of regulatory harmonization. CDSCO medical device registration timelines shape manufacturer launch sequencing for premium-tier products. Mumbai and Bangalore facility networks represent early-mover opportunities before tender standardization consolidates vendor relationships.
Netherlands
Dutch long-term care procurement networks specify conformable silicone gel sheets with patterned micro-structures for anatomical adaptation. EU MDR post-market clinical follow-up obligations extend lifecycle costs for antimicrobial portfolios. Eindhoven region manufacturing clusters supply vapor-permeable polyurethane backings to European dressing assemblers.
Global Skin Tears Treatment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the skin tears treatment market. Incumbent manufacturers with established clinical data repositories capture share from smaller competitors facing disproportionate EU MDR compliance burdens. Three archetypes dominate: diversified medical technology conglomerates with wound care divisions, specialized wound care pure-plays with silicone expertise, and distribution-anchored health systems integrators. Consolidation accelerates as undercapitalized players exit, while remaining competitors pursue geographic expansion and portfolio diversification to defend position.
Among diversified medical technology conglomerates, 3M Company and Smith & Nephew plc exemplify archetypes combining materials science depth with multi-regional regulatory expertise. Specialized wound care pure-plays include Molnlycke Health Care and Coloplast A/S, occupying positions defined by silicone-adhesive specialization and geriatric-focused product development. Solventum Corporation represents the spin-off archetype, with corporate structure suggesting concentrated wound care commitment distinct from parent-organization resource allocation patterns.
| Leading Market Players |
|---|
| Solventum Corporation |
| Smith & Nephew plc |
| Cardinal Health Inc. |
| ConvaTec Group plc |
| Molnlycke Health Care |
| Coloplast A/S |
| Hollister Inc. |
| 3M Company |
| Covalon Technologies Ltd. |
| Others |
Cost & Logistics Intelligence
Silicone-adhesive substitution for acrylic-based dressings simultaneously shifts supply geography toward German and Japanese organosilicon clusters while compressing margins on legacy hydrocolloid lines. This materials transition concentrates pricing power with specialty chemical feedstock suppliers and forces procurement offices to rebalance total-cost-of-ownership calculations against unit-price metrics.
Pricing Analysis
EU MDR dictates the pricing tier structure across antimicrobial and silicone-based portfolios, separating premium-certified products with established clinical data repositories from standard-tier alternatives facing elevated compliance burdens. Price differentiation rests on certification grade and volume scale, with German and United States long-term care networks commanding enterprise-level discounts through outcome-guarantee contracts. Cost compression in acrylic-based segments intensifies because emerging market procurement prioritizes unit economics over wear-time performance. Nursing facilities in Medicaid-reimbursed skilled nursing operations exhibit highest price sensitivity, while Japanese geriatric wards demonstrate lowest sensitivity due to PMDA fast-track premium positioning.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for vapor-permeable polyurethane backings sourced from Eindhoven-region manufacturers. Geographic supply concentrates in Germany, Japan, and the Netherlands, with organosilicon compound production anchored in the Rhine-Ruhr industrial region and specialty silicone processing clustered in Kanto. Raw material dependencies include medical-grade polydimethylsiloxane, calcium-sodium alginate fibers, and cross-linked hydrogel polymers. Single-source vulnerability in German silicone feedstock creates structural risk for dressing assemblers lacking qualified secondary suppliers. Distribution runs through Cardinal Health's direct-to-facility logistics networks in North America and specialized medical distributors aggregating multi-facility demand across European procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in staff training and wound-healing outcome guarantees expand faster than hardware revenues as United States group purchasing organizations bundle supply contracts with clinical protocol certification. This recurring-revenue layer captures margin premiums unavailable in transactional dressing sales.
For Market Incumbents: Secure clinical data repositories in Germany and France to lower incremental EU MDR post-market surveillance burdens relative to new entrants. Expand backward integration into medical-grade silicone feedstock to reduce exposure to organosilicon price volatility from Rhine-Ruhr suppliers. Capacity addition in Japanese Kanto region manufacturing clusters captures PMDA fast-track designation advantages for geriatric-focused device submissions. For New Entrants and Emerging Players: Staff training protocol gaps in underpenetrated Indian long-term care chains represent immediate white-space targets before tender standardization consolidates vendor relationships. Private eldercare facilities in Maharashtra and Karnataka offer most penetrable geography due to upgrading wound care standards ahead of CDSCO harmonization. Direct sales model with clinical specialist deployment outperforms distributor-dependent approaches for silicone-adhesive specification in European networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturers with established clinical evidence portfolios and EU MDR compliance infrastructure. Long-term viability over the projection horizon rests on regulatory data assets rather than commodity manufacturing scale. Acquisition target archetype includes specialized wound care pure-plays with silicone expertise and incomplete geographic coverage. The signal to watch is exit acceleration among undercapitalized mid-tier players facing disproportionate clinical evaluation cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Data Repository Expansion | Established safety databases in Germany and France reduce post-market surveillance costs for antimicrobial portfolios. |
| Japan PMDA Fast-Track Designation Pursuit | Geriatric-specific trial designs accelerate market access in Tokyo and Osaka metropolitan facility networks. |
| Direct-to-Facility Logistics Network Buildout | Cardinal Health's North American model demonstrates inventory management services capture multi-state operator contracts. |
| Silicone-Adhesive R&D Intensification | Patterned micro-structure development differentiates conformable dressings in Dutch and German procurement specifications. |
| Outcome-Guarantee Contract Structuring | California and Texas enterprise agreements bundle healing-rate commitments with supply to secure multi-year revenue visibility. |
Research Approach
Cross-validation between wound care clinician interviews and hospital procurement database analysis anchors the qualitative findings in observable tender behavior and reimbursement coding patterns. Primary fieldwork engaged long-term care facility administrators, certified wound ostomy continence nurses, biomedical engineers, and group purchasing organization contract managers across the United States, Germany, and Japan. Secondary validation drew from FDA 510(k) filings, EUDAMED device registrations, CMS Medicare claims data, and Japanese MHLW reimbursement fee schedules. Bottom-up demand modeling triangulated against top-down market sizing from regulatory submission volumes and distributor shipment aggregates.
Sensitivity analysis across alternative demographic trajectories and regulatory implementation timelines tests forecast robustness for the analysis window. The quantitative framework segments by product type, application setting, end-user category, and distribution channel, with regional regulatory clusters as an additional modeled dimension. CAGRs derive from fitted growth curves calibrated to historical adoption rates in comparable wound care categories. Industry-specific inputs include nursing labor cost indices, long-term care bed capacity expansion plans, and silicone feedstock price series from German chemical industry associations.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR post-market surveillance regimes, and Japan PMDA geriatric device prioritization; material policy shifts would require re-modeling. Specific risks that could revise projections include EU AI Act implementation affecting dressing selection algorithm deployment, sudden feedstock supply disruptions from Rhine-Ruhr organosilicon producers, and Medicaid reimbursement rate adjustments in United States skilled nursing settings. Recalibration cycles align with material shifts in regulatory guidance, procurement standardization milestones, and clinical evidence publication patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Ultrasound Skin Cleaners Market
Skincare
Global Scar Removal Treatment Market
Skincare
Europe Functional Cosmetics Market
Skincare
Tinted Sunscreen Market
Skincare
Ampoule Cream Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Africa Cosmeceutical Market
Skincare
Skin Care Supplements Market
Skincare
Sensitive Skin Care Products Market
Skincare
Skin Barrier Market
Skincare
Global Skin Rejuvenation Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Bangladesh Skin Care Products Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
South Korea Anti-Acne Dermal Patch Market