
 Global Anaesthesia Monitoring Devices Market | 2026-2036
Global Anaesthesia Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anaesthesia Monitoring Devices Market Foresight
A shift from single-source to multi-source component procurement is broadening supply options for original equipment manufacturers. Medtronic leverages its vertically integrated sensor manufacturing to control quality across the patient monitoring stack. GE Healthcare anchors its position through deep installed-base relationships in integrated delivery networks. Shenzhen Mindray Bio-Medical Electronics competes aggressively on cost-engineered platforms tailored to emerging hospital systems.
Anaesthesia monitoring devices comprise integrated electronic systems that measure, display, and alarm on physiological parameters including end-tidal carbon dioxide, inspired oxygen concentration, bispectral index values, and invasive blood pressure during surgical sedation. These systems typically incorporate multi-parameter modules sampling at 250-500 Hz, with alarm latency under 10 seconds, to prevent hypoxic events and awareness under anaesthesia. Capnography equipment and bispectral index monitors command premium positioning due to their direct linkage to reimbursed safety protocols in tertiary hospitals. Vital signs monitors occupy the highest unit volume tier but face margin compression from standardized multi-parameter designs. Wireless connectivity and data integration platforms represent the fastest-expanding technology layer as perioperative information systems demand seamless electronic health record interoperability.
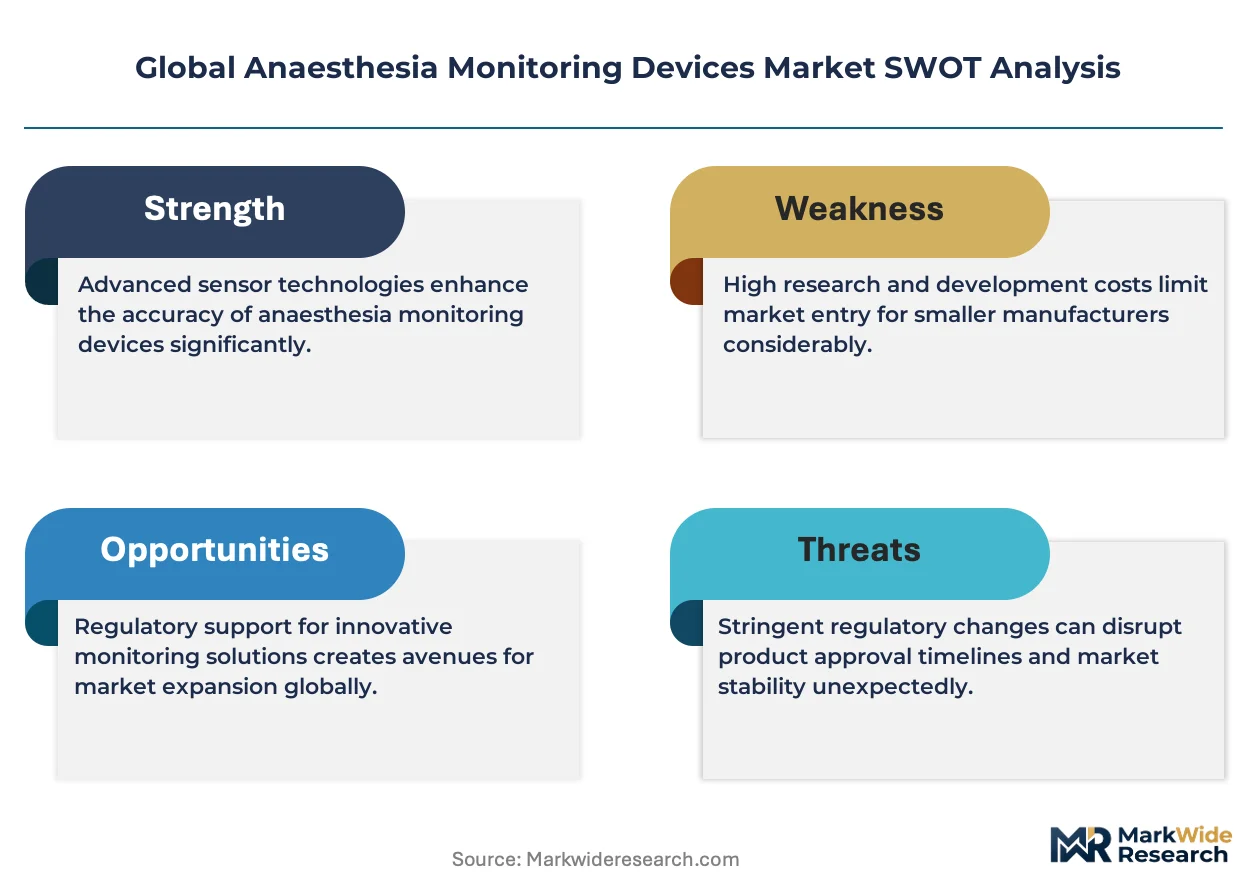
The FDA enforces 510(k) and premarket approval pathways with escalating cybersecurity documentation for networked anaesthesia workstations, while the EU MDR requires renewed clinical evidence and notified body recertification for legacy devices. ISO 80601-2-55 and IEC 60601-1 third editions govern electromagnetic compatibility and alarm system performance, creating compliance barriers for smaller manufacturers lacking dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving software-as-a-medical-device classifications and post-market surveillance mandates that will reshape product lifecycle economics and service revenue models.
Market Dynamics
Real-time electronic health record integration is compressing procurement cycles for anaesthesia monitoring systems, as hospitals in the United States, Germany, and China demand seamless perioperative data flows that legacy siloed devices cannot deliver.
Growth Catalysts
- FDA 510(k) cybersecurity mandates:Networked workstation requirements are accelerating replacement demand across United States integrated delivery networks seeking compliant infrastructure.
- Ambulatory surgical center expansion:China's investment in same-day surgery facilities is pulling compact, multi-parameter monitors into newly constructed outpatient suites.
- Bispectral index protocol adoption:Tertiary hospitals in Germany are embedding depth-of-anaesthesia monitoring into reimbursed safety bundles, standardizing BIS-capable hardware purchases.
Market Restraints
- EU MDR recertification costs:Legacy device renewal requirements are forcing smaller European manufacturers to withdraw mid-tier monitors from circulation.
- Sensor supply concentration:Capnography infrared source manufacturing clusters in East Asia create single-point vulnerability for original equipment producers.
- Electromagnetic compatibility testing:IEC 60601-1 third edition validation timelines extend product development cycles by eight to fourteen months for wireless-enabled platforms.
Strategic Opportunities
- Software-as-a-medical-device pathways:Algorithm-only upgrades for existing hardware installations open recurring revenue streams without capital equipment replacement.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting contract assembly partnerships for cost-engineered vital signs monitors.
- Wireless connectivity modules:Integration with cloud-based perioperative information systems enables predictive maintenance contracts in United States hospital networks.
Industry Challenges
- Clinical engineer scarcity:Biomedical technician shortages in emerging hospital systems delay installation and validation of multi-parameter workstations.
- ISO 80601-2-55 alarm fatigue mitigation:Customization requirements for threshold programming extend commissioning timelines and strain field service teams.
- Interoperability protocol fragmentation:Competing health data standards between proprietary perioperative platforms force redundant integration engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anaesthesia Monitoring Devices Market |
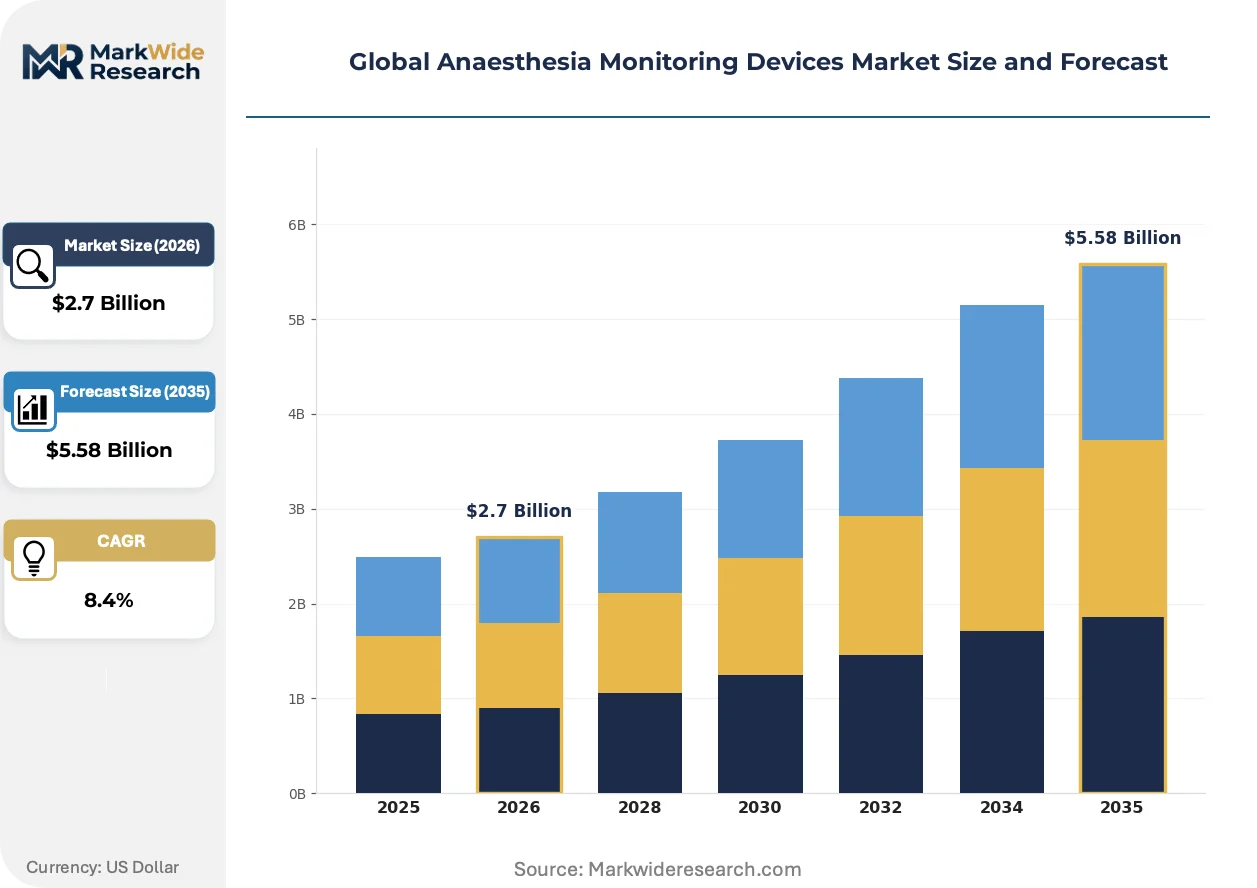
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $5.58 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Vital Signs Monitors, Electroencephalogram Devices, Capnography Equipment, Bispectral Index Monitors Technology: Non-Invasive Sensors, Invasive Sensors, Wireless Connectivity, Alarm & Notification Systems, Data Integration Platforms Application: General Surgery, Obstetrics, Dental Procedures, Outpatient Surgery, Emergency Care End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories |
| Companies Covered | Medtronic, GE Healthcare, Koninklijke Philips N.V., Drägerwerk AG & Co. KGaA, Masimo Corporation, Nihon Kohden Corporation, Shenzhen Mindray Bio-Medical Electronics, Becton, Dickinson and Company, Fisher & Paykel Healthcare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anaesthesia Monitoring Devices Market Shifts & Advancements
Modular hardware architectures and algorithm-driven analytics are redefining how anaesthesia monitoring systems capture, process, and transmit physiological data across surgical workflows.
Multi-parameter integration platforms are consolidating discrete capnography, pulse oximetry, and BIS modules into unified sampling architectures. United States academic medical centers are deploying these consolidated systems to reduce cable clutter and centralize alarm management. The technology is compressing vendor footprint requirements while elevating software licensing revenue relative to hardware sales.
EU MDR post-market surveillance mandates are tightening clinical evidence requirements for legacy anaesthesia workstations seeking recertification. Manufacturers must now submit periodic safety update reports and real-world performance data to notified bodies. German and French tertiary hospitals are prioritizing vendors with established quality management systems capable of sustained regulatory documentation.
Outcome-based service agreements are displacing traditional capital purchase models in United States integrated delivery networks. Per-procedure monitoring fees bundle hardware, maintenance, and software updates into predictable operational expenditures. This shift concentrates vendor selection authority within health system procurement committees rather than individual department heads.
Global Anaesthesia Monitoring Devices Market Segmentation
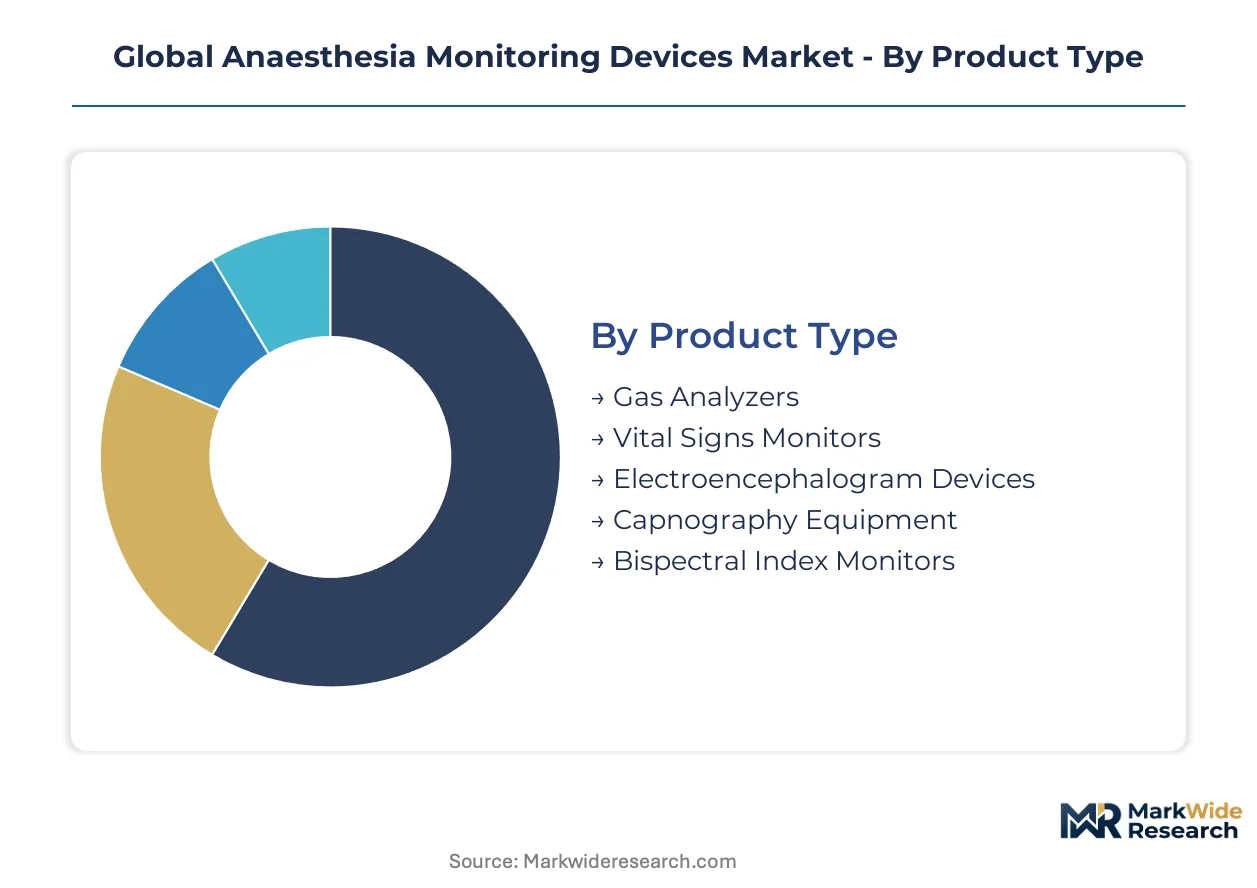
Segmentation in anaesthesia monitoring devices reveals how regulatory pathways and clinical workflows fragment procurement decisions. Hospital buyers weight FDA 510(k) clearance status differently across product categories, while ambulatory settings prioritize compact form factors over multi-parameter depth.
Product Type:
Certification burden varies sharply across this category: capnography and bispectral index devices face Class II FDA scrutiny with cybersecurity documentation, while vital signs monitors navigate streamlined 510(k) pathways.
- Gas Analyzers:Infrared and paramagnetic sensing technologies measure inspired and expired oxygen, nitrous oxide, and volatile anaesthetic concentrations. United States academic medical centers specify these for research-intensive operating suites where precise agent quantification supports pharmacokinetic studies.
- Vital Signs Monitors:Multi-parameter platforms integrating pulse oximetry, non-invasive blood pressure, and temperature sampling dominate unit shipments. China's county-level hospitals absorb volume here as standardized designs compress per-unit pricing below premium specialized alternatives.
- Electroencephalogram Devices:Processed EEG hardware for depth-of-anaesthesia assessment requires specialized electrode placement training. German tertiary centers embed these into reimbursed neuromonitoring protocols.
- Capnography Equipment:Sidestream and mainstream CO2 detection systems with waveform display. United States emergency departments mandate these for procedural sedation safety.
- Bispectral Index Monitors:Proprietary algorithm-based consciousness tracking using frontotemporal electrode arrays. Tertiary hospitals in Germany and the United States standardize these for high-risk cardiac and neurosurgical cases.
Leading the category by volume: Vital Signs Monitors. Growing fastest: Bispectral Index Monitors.
Technology:
Cost tier stratification separates mature sensor hardware from emerging software-layer revenue models, with wireless modules commanding premium positioning against established invasive alternatives.
- Non-Invasive Sensors:Pulse oximetry and capnography probes using optical and infrared detection without vascular access. India's expanding ambulatory surgical network drives volume absorption for disposable finger clip and nasal cannula designs.
- Invasive Sensors:Arterial line transducers and pulmonary artery catheters requiring sterile insertion. United States cardiac surgery suites maintain installed base despite shift toward less invasive hemodynamic monitoring.
- Wireless Connectivity:Bluetooth and Wi-Fi enabled data transmission to perioperative information systems. United States integrated delivery networks specify these for seamless electronic health record integration.
- Alarm & Notification Systems:Configurable threshold detection with escalating auditory and visual alerts. EU MDR mandates for alarm fatigue mitigation are extending development timelines for manufacturers targeting European hospitals.
- Data Integration Platforms:Middleware architectures bridging device output to hospital information systems. Cloud-based deployments are climbing fastest as United States health systems adopt subscription service models.
Highest margin capture: Data Integration Platforms. Steepest expansion trajectory: Wireless Connectivity.
Application:
Customer type differentiation separates high-acuity inpatient settings from cost-sensitive outpatient environments, with reimbursement protocols determining hardware specification intensity.
- General Surgery:Open and laparoscopic procedures requiring continuous multi-parameter monitoring across induction, maintenance, and emergence phases. United States hospital operating rooms specify full-capability workstations here.
- Obstetrics:Labour epidural and caesarean section sedation with maternal-fetal dual monitoring requirements. China's maternal health infrastructure investments are pulling compact monitors into provincial hospital delivery suites.
- Dental Procedures:Conscious sedation for oral surgery with lighter monitoring depth. Ambulatory settings in Germany prioritize portable capnography for office-based anaesthesia safety.
- Outpatient Surgery:Same-day procedures demanding rapid turnover and minimal footprint. China's county-level surgical centers specify streamlined vital signs monitors for cost containment.
- Emergency Care:Trauma and critical intervention contexts requiring ruggedized, rapid-deployment equipment. United States emergency departments mandate capnography for all intubated patients per procedural safety protocols.
Primary revenue concentration: General Surgery. Gaining share fastest: Outpatient Surgery.
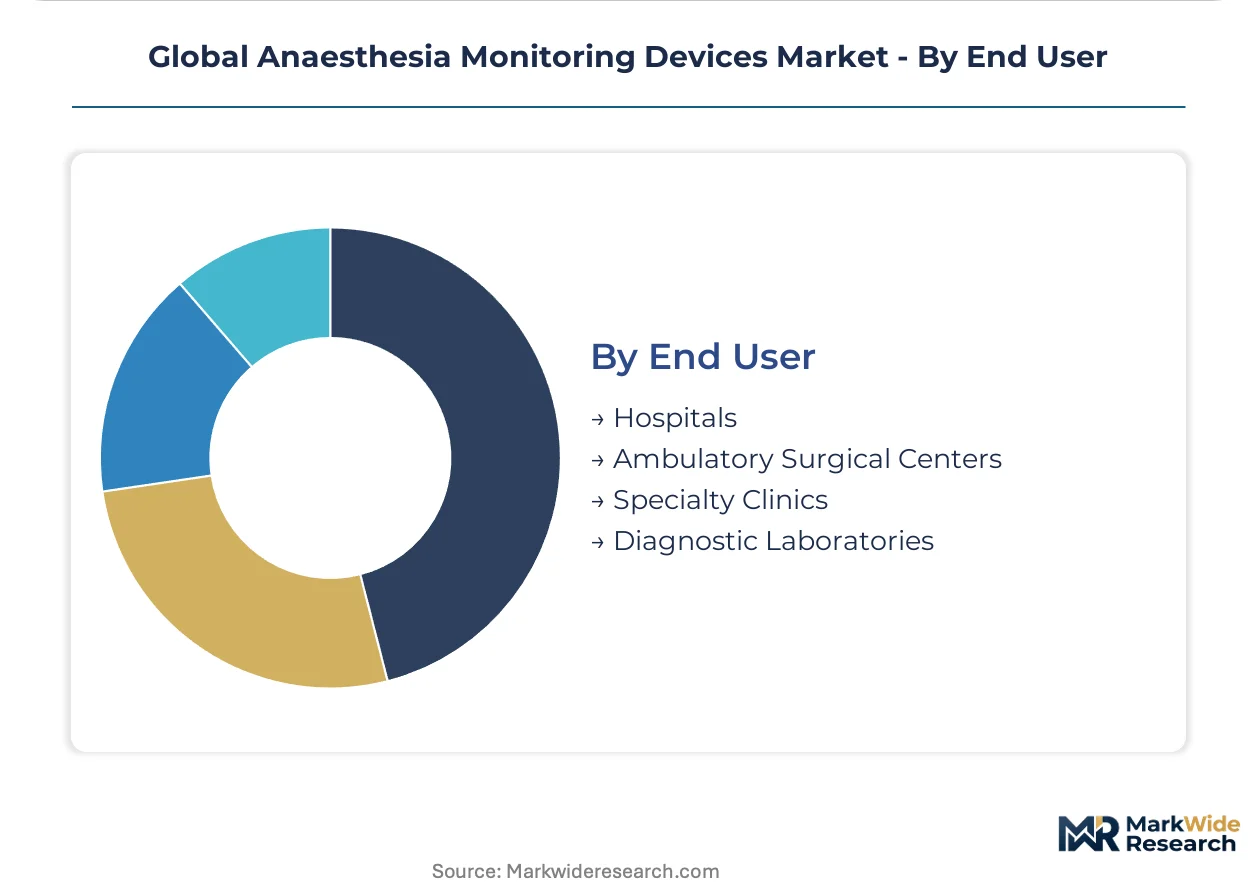
End User:
Supply concentration clusters around hospital procurement committees with centralized vendor management, while fragmented clinic purchasing sustains mid-tier manufacturer participation.
- Hospitals:Tertiary and secondary inpatient facilities with 24-hour surgical capacity. United States integrated delivery networks consolidate purchasing authority across multi-facility systems, favouring vendors with comprehensive service infrastructure.
- Ambulatory Surgical Centers:Same-day procedure facilities requiring compact, rapid-turnover equipment. China's expansion of day surgery units is absorbing cost-optimized monitor shipments from domestic and regional manufacturers.
- Specialty Clinics:Gastroenterology, pain management, and ophthalmology settings with procedure-specific monitoring needs. German outpatient endoscopy centers specify portable capnography for propofol sedation safety.
- Diagnostic Laboratories:Minor procedural sedation for imaging-guided interventions. Limited penetration due to lighter anaesthesia depth requirements and alternative monitoring approaches.
Dominant volume share: Hospitals. Expanding most quickly: Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian sensor manufacturing clusters supply infrared sources and optical components that feed assembly lines across Germany, the United States, and China. Hospital infrastructure investments and regulatory recertification timelines shape procurement velocity in each national market.
United States
Integrated delivery networks consolidate purchasing authority across multi-facility systems, demanding FDA 510(k) cleared devices with cybersecurity documentation for networked workstations. The FDA mandates escalating premarket validation for Class II anaesthesia devices. Boston and Minneapolis medical device corridors host service infrastructure supporting installed-base relationships.
Germany
Tertiary hospitals embed bispectral index monitoring into reimbursed safety bundles, standardizing BIS-capable hardware purchases. The EU MDR requires renewed clinical evidence and notified body recertification for legacy devices. Baden-Württemberg and Bavaria concentrate manufacturing quality management systems capable of sustained regulatory documentation.
China
County-level hospitals absorb volume shipments of standardized vital signs monitors as maternal health infrastructure investments pull compact monitors into provincial delivery suites. The NMPA governs medical device registration under evolving cybersecurity standards. Shenzhen and Beijing clusters anchor domestic manufacturing of cost-engineered platforms.
India
Ambulatory surgical network expansion drives disposable sensor absorption for non-invasive monitoring designs. The PLI scheme for medical devices attracts contract assembly partnerships for cost-engineered monitors. Maharashtra and Gujarat host emerging domestic manufacturing capacity for vital signs platforms.
Japan
Aging surgical infrastructure generates replacement demand for multi-parameter workstations with wireless connectivity modules. The PMDA enforces stringent post-market surveillance aligned with international harmonization. Tokyo-Osaka medical device corridors concentrate quality management expertise for regulatory compliance.
Global Anaesthesia Monitoring Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and installed-base service infrastructure. The vendor landscape organizes into three tiers: diversified conglomerates with vertical sensor manufacturing control, integrated health technology platforms with deep delivery network relationships, and cost-engineered specialists targeting emerging hospital systems. Consolidation pressure intensifies as cybersecurity documentation requirements and EU MDR recertification costs force portfolio rationalization. Dominant competitive moves include strategic partnerships for software-as-a-medical-device pathways and geographic expansion through contract manufacturing alliances.
Among diversified health technology conglomerates, Medtronic and GE Healthcare exemplify contrasting strategic positions. Medtronic leverages vertically integrated sensor manufacturing to control quality across the patient monitoring stack. GE Healthcare anchors its position through deep installed-base relationships in integrated delivery networks. Shenzhen Mindray Bio-Medical Electronics occupies a distinct tier as a cost-engineered platform specialist targeting emerging hospital systems in China and adjacent markets.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Drägerwerk AG & Co. KGaA |
| Masimo Corporation |
| Nihon Kohden Corporation |
| Shenzhen Mindray Bio-Medical Electronics |
| Becton, Dickinson and Company |
| Fisher & Paykel Healthcare Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into infrared sensor manufacturing anchors Medtronic's supply position and pricing power, enabling premium positioning for capnography modules while compressing margins for competitors sourcing from East Asian contract manufacturers. This captive production structure insulates against component volatility but concentrates cost exposure in semiconductor foundry access.
Pricing Analysis
Warranty and field service bundling separates premium-tier anaesthesia workstations from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance status and cybersecurity documentation depth. Cost compression in economy vital signs monitors is intensifying because Chinese domestic manufacturers absorb volume with stripped-down feature sets. Ambulatory surgical centers in India exhibit highest price sensitivity; United States academic medical centers show lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Memphis anchor hub-and-spoke patterns for spare parts and consumable sensors. Manufacturing concentrates in China, Germany, and the United States for final assembly, with East Asian clusters feeding infrared sources and optical components. The network draws from semiconductor foundries in Taiwan, precision plastics in Germany, and cable assemblies in Mexico. Single-source vulnerability in capnography infrared emitters creates structural risk. Distribution runs through manufacturer-direct service teams for premium installations and third-party medical distributors for mid-tier volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-grade semiconductor foundry capacity constraints prop pricing power for manufacturers with captive supply arrangements or long-term foundry commitments.
For Market Incumbents: Cement installed-base relationships through predictive maintenance contracts and software-as-a-medical-device upgrade pathways. Deepen backward integration into pulse oximetry and capnography sensor manufacturing to defend against emerging Chinese cost-engineered platforms. Prioritize EU MDR quality management system investments to sustain legacy device recertification timelines. For New Entrants and Emerging Players: Capture India's ambulatory surgical center expansion through PLI scheme contract manufacturing partnerships. Target Germany's dental sedation safety protocols with portable capnography units below premium workstation price points. Pursue white-label distribution through European third-party medical device distributors lacking proprietary monitoring portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified health technology conglomerates seeking perioperative data integration capabilities. Five-to-ten-year viability hinges on software-layer recurring revenue attachment rates exceeding hardware replacement cycles. Monitor FDA cybersecurity guidance evolution as inflection indicator for replacement demand velocity in United States integrated delivery networks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Submission | Networked workstation clearance accelerates replacement cycles in United States hospital systems. |
| EU MDR Recertification Pathway | Legacy device renewal sustains European market access against withdrawal of smaller competitors. |
| Hospital System Partnership | Integrated delivery network sole-source agreements lock out rival vendors across multi-facility footprints. |
| Software Companion Development | Algorithm-only upgrades for existing hardware generate recurring revenue without capital equipment sales. |
| Reimbursement Strategy | Bispectral index protocol inclusion in German safety bundles standardizes BIS-capable hardware procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across biomedical engineers, hospital purchasing committee members, GPO contracts managers, and anaesthesiology department heads. FDA 510(k) databases, EU MDR notified body documentation, NMPA registration filings, and hospital procurement databases supplied secondary validation. Bottom-up equipment shipment tracking and top-down healthcare expenditure allocation were triangulated against manufacturer-reported segment revenues.
Data-stream reconciliation across product type, technology layer, application setting, and end-user facility tier generated volume and value outputs across the projection horizon. CAGRs were derived from segmented growth rate differentials weighted by base-year revenue shares. Forecast inputs incorporated ambulatory surgical center construction pipelines, regulatory recertification timelines, and software-as-a-medical-device adoption curves.
The model holds under stable regulatory clearance timelines and continuous semiconductor supply; deviation in foundry capacity allocation or cybersecurity mandate acceleration would shift replacement demand patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Remote Electrocardiogram Monitoring Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Global Biomedical Sensor Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Mobile Heart Monitoring Market