
 Europe Electroencephalography Devices Market | 2026-2036
Europe Electroencephalography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electroencephalography Devices Market Foresight
The capability gap between high-R&D specialists and assembly-oriented vendors is collapsing as software-defined architectures commodify hardware margins. Brain Products GmbH leverages its academic channel dominance to sustain premium positioning in cognitive research installations. Natus Medical anchors its European presence through neurodiagnostic center partnerships across France and Italy. Medtronic competes on integrated care pathway solutions that extend beyond raw EEG acquisition into surgical planning ecosystems.
Electroencephalography devices measure electrical activity via scalp electrodes, typically capturing 0.5–100 Hz signals across 16–256 channels for clinical and research interpretation. These systems serve primary purposes in epilepsy diagnosis, sleep staging, and brain-computer interface development where millisecond temporal resolution exceeds structural imaging modalities. Portable devices now lead volume shipments as ambulatory monitoring replaces inpatient observation for routine diagnostics. Wireless systems represent the fastest-expanding segment, though traditional devices retain margin concentration in intraoperative and intensive care settings where electromagnetic interference resilience remains non-negotiable. Software solutions increasingly capture value through AI-assisted spike detection and automated sleep scoring algorithms.
The EU Medical Device Regulation (MDR) and CE marking framework impose escalating clinical evidence burdens on EEG manufacturers, particularly for novel brain-computer interface applications. Germany's national pharmaceutical regulator, BfArM, coordinates with EMA on software-as-medical-device classifications that affect cloud-based delivery modes. REACH compliance constrains electrode material selections, pushing substitution away from legacy silver-silver chloride formulations. Stakeholders must monitor how MDR notified body capacity bottlenecks delay market access for innovative wearable systems.
Market Dynamics
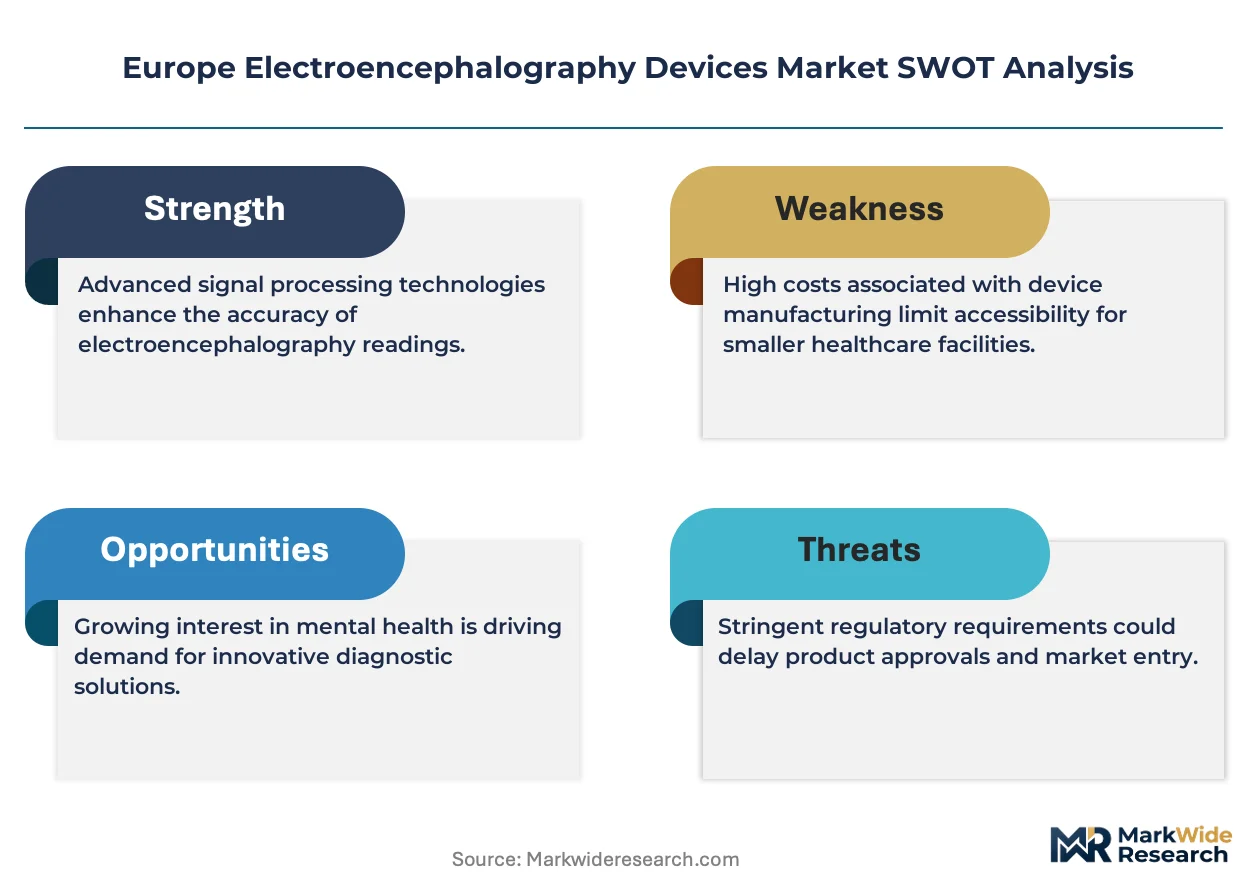
The EU Medical Device Regulation (MDR) is compressing hardware margins by forcing manufacturers toward software-defined architectures and higher clinical evidence burdens, collapsing the traditional capability gap between premium research specialists and assembly-oriented vendors.
Growth Catalysts
- MDR Clinical Evidence Requirements:Tighter CE marking frameworks push neurodiagnostic centers toward higher-fidelity EEG systems that capture superior signal quality for regulatory submissions.
- Ambulatory Monitoring Expansion:Sleep disorder clinics across Germany and France are replacing inpatient observation with portable wireless devices, accelerating volume shipments in outpatient channels.
- Silver-Silver Chloride Substitution:REACH compliance constraints on electrode materials are driving R&D investment into biocompatible alternatives that reduce patient skin irritation during extended monitoring.
Market Restraints
- Notified Body Capacity Bottlenecks:MDR implementation has created severe backlogs in CE marking reviews, delaying market access for innovative wearable systems by 12-18 months.
- Electromagnetic Interference Vulnerability:Wireless EEG systems face persistent signal degradation in intraoperative and intensive care settings where surgical equipment generates substantial RF noise.
- Cloud Infrastructure Dependency:Software-as-medical-device classifications under BfArM-EMA coordination create jurisdictional complexity for AI-assisted diagnostic platforms hosted on cross-border servers.
Strategic Opportunities
- Brain-Computer Interface Development:Cognitive research installations in the Netherlands and Switzerland are pioneering non-invasive neural control systems for motor-impaired patients, opening premium hardware demand.
- AI-Assisted Spike Detection:Automated epilepsy diagnostic algorithms are creating software revenue streams that decouple value capture from electrode hardware sales.
- Neurosurgical Planning Integration:EEG data is converging with functional MRI and neuronavigation systems to create bundled care pathway solutions that extend vendor relationships beyond acquisition hardware.
Industry Challenges
- Electrophysiology Technician Shortage:Specialized training requirements for scalp electrode placement and artifact recognition limit deployment velocity in community hospital networks.
- Legacy System Interoperability:Proprietary data formats from established EEG manufacturers block seamless integration with emerging hospital information systems and research databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electroencephalography Devices Market |
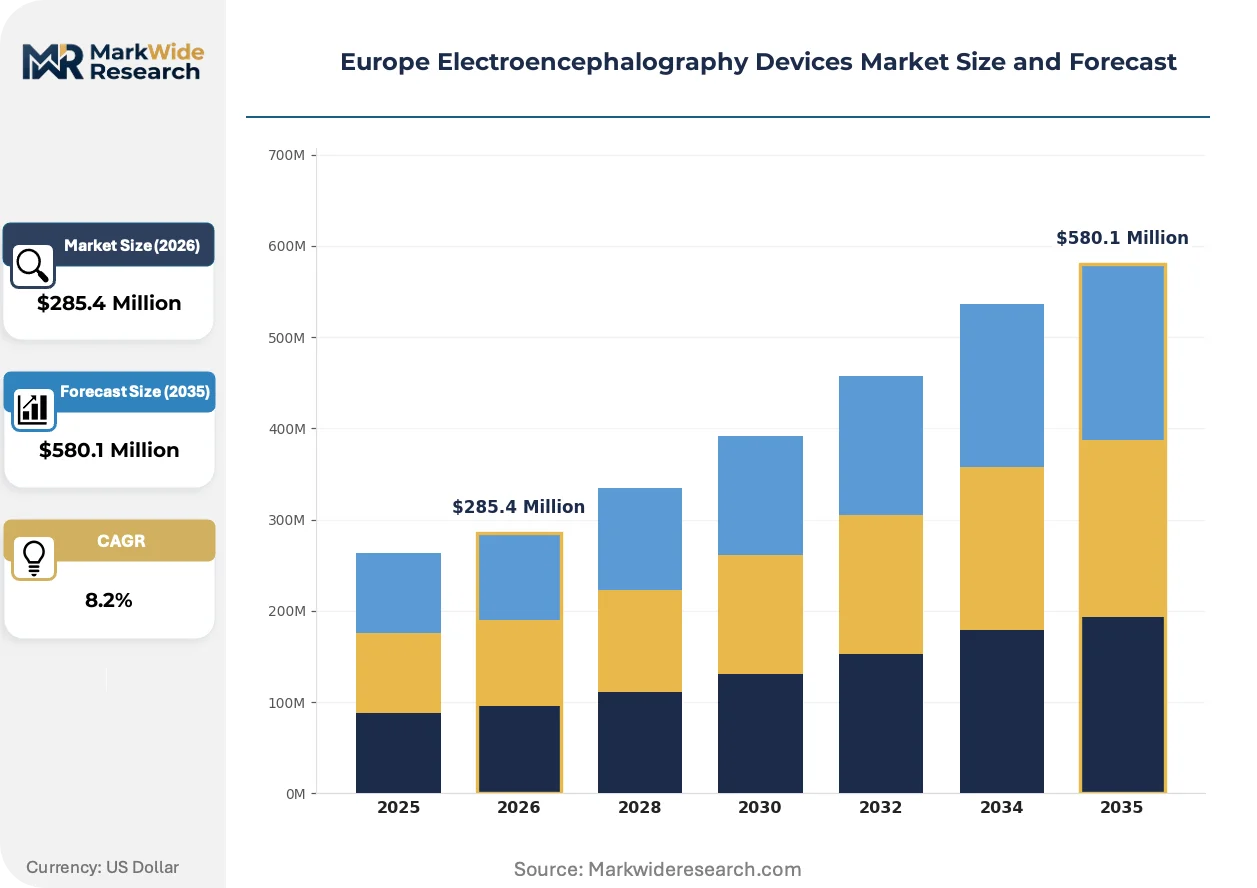
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $580.1 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Traditional Devices, Wireless Systems, Software Solutions Application: Sleep Disorders, Epilepsy Monitoring, Cognitive Research, Brain-Computer Interface End User: Hospitals, Research Laboratories, Neurodiagnostic Centers, Clinics Delivery Mode: Cloud-Based, On-Premises, Hybrid, Remote Monitoring |
| Companies Covered | Brain Products GmbH, Natus Medical, Inc., Medtronic, Nihon Kohden America, Inc., ANT Neuro, Compumedics Ltd., g.tec medical engineering GmbH, Neurosoft, Lifelines neuro, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electroencephalography Devices Market Shifts & Advancements
Dry electrode arrays and capacitive sensing technologies are displacing traditional gel-based conductive interfaces, while regulatory pressure accelerates software-centric business models that commodify acquisition hardware.
Capacitive EEG sensors eliminate skin preparation and conductive gel application, reducing setup time from 45 minutes to under 5 minutes in clinical environments. Sleep laboratories across the United Kingdom and Nordic countries are piloting these systems for home-based polysomnography. The technology is decomposing the service revenue model of neurodiagnostic centers by enabling patient self-application and remote monitoring.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on machine learning algorithms embedded in EEG diagnostic software. Manufacturers must now maintain technical documentation and human oversight protocols for automated seizure detection systems. High-risk neural interface applications face the strictest scrutiny, pushing vendors toward explainable AI architectures that satisfy notified body reviewers.
Hospital procurement departments are consolidating neurodiagnostic equipment purchasing through centralized framework agreements that bundle EEG hardware with maintenance and software upgrade commitments. Academic medical centers in Germany and France are leading this transition, displacing transactional equipment sales with multi-year service relationships. This restructuring concentrates vendor selection authority within supply chain functions rather than individual department clinicians.
Europe Electroencephalography Devices Market Segmentation
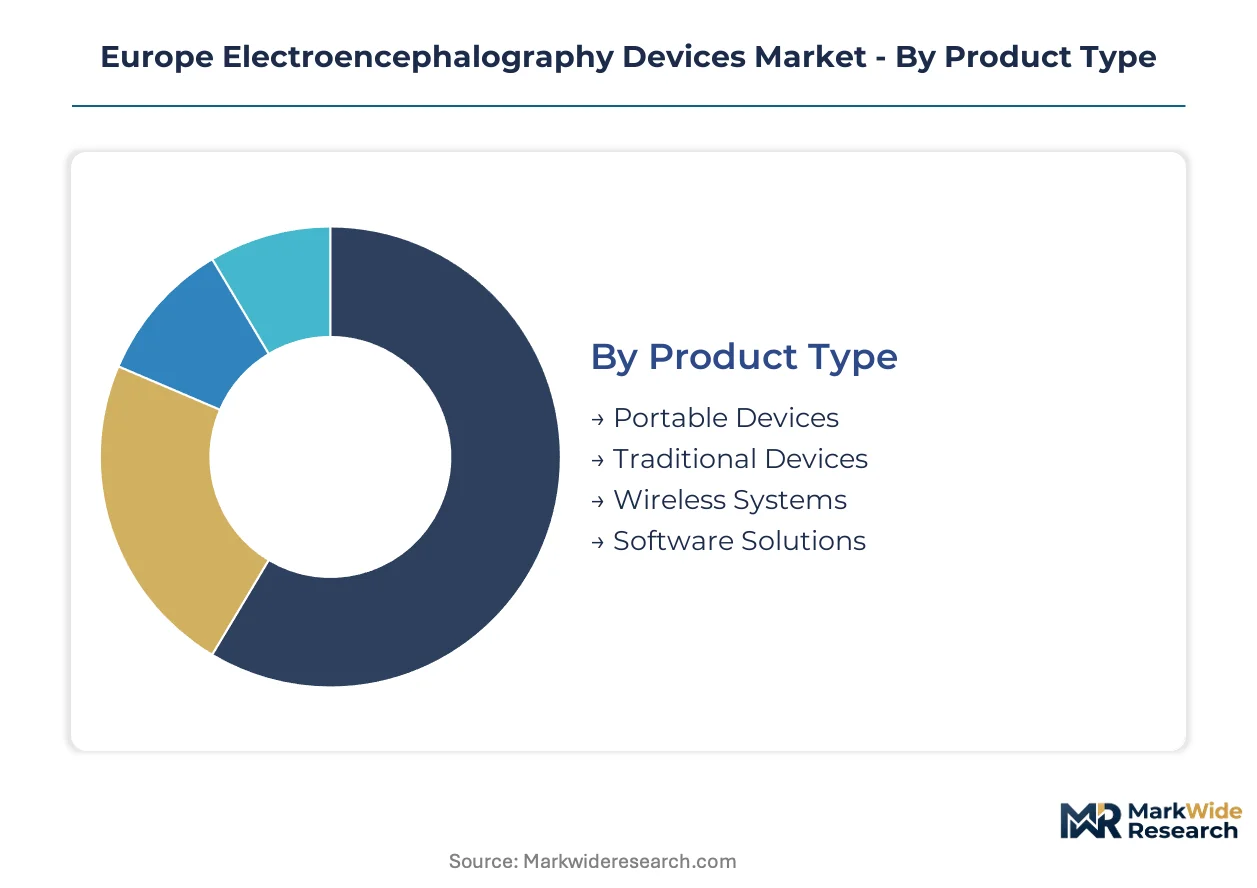
EEG device segmentation in Europe reflects divergent regulatory pathways under the EU MDR, where software-as-medical-device classifications create distinct compliance burdens across hardware and algorithmic offerings. Understanding these segment boundaries helps vendors allocate R&D investment between acquisition platforms and diagnostic automation layers.
Product Type:
CE marking requirements under the EU MDR differentiate stationary systems from wearable configurations, with wireless architectures facing heightened electromagnetic compatibility scrutiny during notified body review.
- Portable Devices:Battery-powered units with 16-32 channel configurations dominate ambulatory epilepsy monitoring across Germany's outpatient neurology networks. French sleep disorder clinics are replacing inpatient observation with these systems, accelerating volume shipments through retail pharmacy distribution channels.
- Wireless Systems:Bluetooth and proprietary RF transmission architectures eliminate tethering constraints for home-based polysomnography. The Netherlands and Nordic sleep laboratories are piloting these for patient self-application, though intraoperative deployment remains limited by electromagnetic interference from surgical equipment.
- Traditional Devices:Hardwired 64-256 channel systems with galvanic isolation maintain margin concentration in German university hospital intensive care units where signal fidelity is non-negotiable.
- Software Solutions:AI-assisted spike detection and automated sleep staging algorithms are capturing recurring revenue through cloud-based delivery under BfArM-EMA software-as-medical-device coordination.
Established volume favors traditional devices; emerging adoption favors wireless systems.
Application:
Clinical indication determines reimbursement coding and therefore procurement budget allocation across European hospital networks.
- Sleep Disorders:Polysomnography and home sleep apnea testing represent the highest procedure volume indication, with British and Swedish national health services expanding ambulatory diagnostic coverage.
- Epilepsy Monitoring:Long-term video-EEG telemetry for seizure localization commands premium pricing in French and Italian comprehensive epilepsy centers, where surgical candidacy determination justifies extended inpatient observation.
- Cognitive Research:High-density EEG for neuroscience applications concentrates in Dutch and Swiss academic installations, funded through European Research Council grants rather than clinical reimbursement.
- Brain-Computer Interface:Non-invasive motor control systems for paralyzed patients are gaining notified body attention under the EU AI Act's high-risk neural interface classification.
Reimbursement stability favors epilepsy monitoring; research funding volatility favors cognitive research.
End User:
Purchasing authority and technical staffing requirements segment the customer base across institutional categories.
- Neurodiagnostic Centers:Specialized facilities across Germany and France consolidate EEG interpretation expertise, creating concentrated demand for high-channel-count systems and technician training services.
- Hospitals:German hospital networks are centralizing neurodiagnostic procurement through framework agreements that bundle hardware with multi-year maintenance commitments, displacing departmental autonomy.
- Research Laboratories:Academic medical centers in France and the Netherlands prioritize open-source compatibility and raw data export for multi-modal neuroimaging integration.
- Clinics:Community neurology practices in the United Kingdom are adopting portable devices for first-line diagnostic screening, constrained by electrophysiology technician availability.
Contract concentration favors hospitals; margin premium favors neurodiagnostic centers.
Delivery Mode:
Data residency requirements and cybersecurity frameworks are fragmenting deployment architectures across European jurisdictions.
- Cloud-Based:Centralized algorithm processing enables continuous model updates for AI-assisted diagnostics, though BfArM-EMA jurisdictional complexity creates compliance friction for cross-border server hosting.
- Remote Monitoring:Real-time telemetry for home-based epilepsy observation is expanding fastest in British and Nordic markets with established digital health infrastructure.
- On-Premises:Air-gapped installations persist in German military and security-sensitive research facilities with classified data handling protocols.
- Hybrid:Edge processing with cloud backup balances latency requirements against scalability, gaining traction in French university hospital networks.
Regulatory clarity favors on-premises; scalability economics favor cloud-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European neurodiagnostic procurement. German hospital networks prioritize signal fidelity over acquisition cost, while British NHS trusts and Italian regional health authorities face acute budget compression that favors portable wireless configurations.
Germany
University hospital networks in Munich and Heidelberg drive demand for high-channel-count systems in epilepsy surgery planning. BfArM coordinates with EMA on software-as-medical-device classifications that constrain cloud-based AI diagnostics. The Baden-Württemberg research corridor anchors Brain Products GmbH's academic channel dominance in cognitive neuroscience installations.
United Kingdom
NHS England's sleep disorder diagnostic expansion is accelerating ambulatory monitoring adoption across community neurology practices. MHRA's post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment pathways for wearable systems. The Oxford-Cambridge-London golden triangle concentrates high-density EEG research funded through UK Research and Innovation grants.
France
Comprehensive epilepsy centers in Paris and Lyon command premium pricing for long-term video-EEG telemetry in surgical candidacy determination. ANSM enforces stringent clinical evidence requirements for novel brain-computer interface applications under the EU AI Act. The Île-de-France hospital procurement consortium is centralizing neurodiagnostic equipment purchasing through multi-year framework agreements.
Netherlands
Academic medical centers in Amsterdam and Utrecht prioritize open-source compatibility for multi-modal neuroimaging integration. EMA's centralized procedure for high-risk neural interfaces affects Dutch BCI startups seeking CE marking. The Eindhoven Brainport region is pioneering non-invasive motor control systems for paralyzed patients through European Research Council funding.
Switzerland
Swissmedic's streamlined review timelines attract BCI developers seeking faster market access than EU MDR notified body queues permit. The ETH Zurich-University Hospital Zurich nexus concentrates high-density EEG research for brain-computer interface applications. Basel's pharmaceutical-industry spillover is driving demand for neurophysiological biomarker platforms in clinical trial endpoints.
Europe Electroencephalography Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European EEG device supply. Premium research specialists and assembly-oriented vendors are converging as software-defined architectures erode traditional hardware differentiation. Two archetypes dominate: academic-channel specialists leveraging university relationships, and integrated care pathway vendors bundling hardware with surgical planning ecosystems. Competitive moves center on M&A for AI diagnostic capabilities and strategic partnerships with neurodiagnostic center chains.
Within the academic-channel tier, Brain Products GmbH exemplifies premium positioning through cognitive research installations. Natus Medical anchors presence through neurodiagnostic center partnerships across Southern Europe. Medtronic occupies a position on the integrated care pathway vector, extending relationships beyond acquisition hardware into surgical planning ecosystems.
| Leading Market Players |
|---|
| Brain Products GmbH |
| Natus Medical, Inc. |
| Medtronic |
| Nihon Kohden America, Inc. |
| ANT Neuro |
| Compumedics Ltd. |
| g.tec medical engineering GmbH |
| Neurosoft |
| Lifelines neuro |
| Others |
Supply & Pricing Matrix
EU MDR compliance gates simultaneously constrain supplier qualification and stratify price tiers across European EEG procurement, with notified body bottlenecks extending lead times for premium-certified systems while budget-constrained buyers retreat to standard configurations. German university hospitals absorb these premiums for surgical-grade fidelity, whereas British NHS trusts and Italian regional authorities prioritize wireless ambulatory systems that trade channel density for unit accessibility.
Pricing Analysis
Multi-year service and software upgrade contracts now generate lifetime value exceeding hardware margins, with German hospital networks leading framework agreements that bundle maintenance, AI algorithm subscriptions, and technician training into recurring revenue streams. Pricing stratifies across premium research installations, standard clinical configurations, and economy-tier portable screening units, with differentiation driven by channel count and MDR certification tier. Cost compression in the standard tier intensifies as assembly-oriented vendors match hardware specifications of established specialists. British community neurology practices exhibit highest price sensitivity, while French comprehensive epilepsy centers tolerate premium positioning for surgical planning integration.
Supply Chain Analysis
Strategic stockpiling of silver-silver chloride alternatives and semiconductor components characterizes vendor inventory management as REACH compliance deadlines and chip allocation constraints disrupt electrode and acquisition board availability. Manufacturing concentrates in Germany, Switzerland, and the Netherlands, with precision sensor fabrication anchored in the Baden-Württemberg and Eindhoven corridors. Raw material dependencies span biocompatible electrode substrates, analog-to-digital converters, and medical-grade polymers. Single-source vulnerability in specialized amplifier chip supply creates exposure to foundry allocation decisions. Distribution runs through neurodiagnostic center procurement consortia and hospital group purchasing organizations that consolidate vendor selection authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through MDR certification and notified body relationships constructs defensive moats that extend payback periods for new entrant capital deployment. Switching costs in hospital framework agreements and technician training ecosystems further protect incumbent positioning.
For Market Incumbents: Fortify channel control through exclusive neurodiagnostic center partnerships that embed training and maintenance dependencies, while deepening backward integration into electrode material production to offset REACH-driven input cost volatility. Invest in explainable AI architectures that satisfy EU AI Act conformity requirements ahead of notified body precedent. Prioritize acquisition of automated spike detection software specialists to decouple revenue from hardware shipment cycles.
For New Entrants and Emerging Players: Differentiate on capacitive dry electrode architectures that eliminate technician-dependent setup friction, targeting British and Nordic sleep laboratory networks with patient self-application value propositions. Exploit underpenetrated community neurology screening in the United Kingdom where NHS diagnostic expansion outpaces electrophysiology technician supply. Pursue direct-to-clinic distribution bypassing hospital procurement centralization.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward algorithmic diagnostic platforms with high-risk neural interface classifications already navigated. Long-term viability favors vendors with software-as-medical-device revenue streams and established notified body relationships spanning the analysis window. Target acquisition archetypes include BCI startups with Swissmedic fast-track experience and AI diagnostic firms with BfArM technical documentation precedent. Watch for MDR notified body capacity expansion as inflection indicator for innovative wearable system market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Notified body pre-submission engagement compresses MDR review timelines for wireless architectures. |
| Hospital System Partnership | Framework agreements with German procurement consortia lock out competitor access through multi-year maintenance bundling. |
| Software Companion Development | AI-assisted spike detection algorithms generate recurring revenue independent of electrode hardware replacement cycles. |
| Backward Integration into Electrodes | In-house production of biocompatible sensor substrates insulates margins from REACH-driven silver-silver chloride substitution costs. |
| Reimbursement Strategy | Coding alignment with NHS England sleep disorder expansion accelerates ambulatory monitoring adoption in community settings. |
Research Methodology
Initial hypotheses were tested against primary input from hospital biomedical engineers, neurodiagnostic center technical directors, GPO contracts managers, and EEG system procurement committees and refined through secondary validation against EMA MDR guidance documents, BfArM software-as-medical-device classifications, NHS procurement databases, and European Research Council funding disclosures. Bottom-up demand modeling across product type, application, end user, and delivery mode segments triangulated against top-down market sizing from manufacturer shipment data and national health service diagnostic procedure volumes.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within segmentation dimensions spanning product architecture, clinical indication, institutional purchasing authority, and data residency requirements. CAGRs derive from logistic diffusion curves fitted to ambulatory monitoring substitution rates and AI diagnostic software adoption patterns, with cross-validation against historical elasticity in German hospital capital expenditure cycles and British NHS technology assessment timelines.
The analysis sits within stated boundaries; outcomes outside sustained MDR notified body capacity, REACH compliance cost trajectories, and EU AI Act enforcement consistency would require recalibration. Forecasts embed assumptions regarding reimbursement stability for epilepsy monitoring and sleep disorder diagnostics. Revision becomes warranted when BfArM-EMA jurisdictional coordination on cross-border cloud hosting crosses regulatory clarity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Walking Aids Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Spectacle Lens Market
Medical Devices
Slip Disc Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Diode Laser Hair Removal Equipment Market