
 Global Patient Positioning System Market | 2026-2036
Global Patient Positioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Positioning System Market Foresight
Ambulatory surgical centers is broadening the end-use base for patient positioning equipment as outpatient procedure volumes rise across North America and Western Europe. Stryker Corporation leverages its integrated operating room portfolio to dominate premium surgical table configurations. Hill-Rom Holdings, Inc. anchors its position through deep channel relationships with hospital purchasing networks. Getinge AB differentiates via infection control compatibility across its positioning product lines.
Patient positioning systems encompass mechanical, air-filled, gel-based, electronic, and foam-based platforms engineered to stabilize patients during surgery, imaging, or therapy while preventing pressure injuries. Electronic adjustment platforms integrate motor-driven articulation with load sensors enabling real-time pressure mapping. Surgical procedures command the largest application segment due to procedural volume and table replacement cycles. Air-filled systems represent the fastest-growing technology category as hospitals prioritize dynamic pressure redistribution for bariatric and immobile patients.
The FDA governs powered positioning devices under 21 CFR 892, while the EU MDR requires clinical evidence for Class IIa and above patient support equipment. ISO 13485 certification shapes supplier qualification across hospital procurement frameworks. Stakeholders must monitor how Japan's PMDA aligns its QMS requirements with MDR equivalency agreements to anticipate export pathway complexity.
Market Dynamics
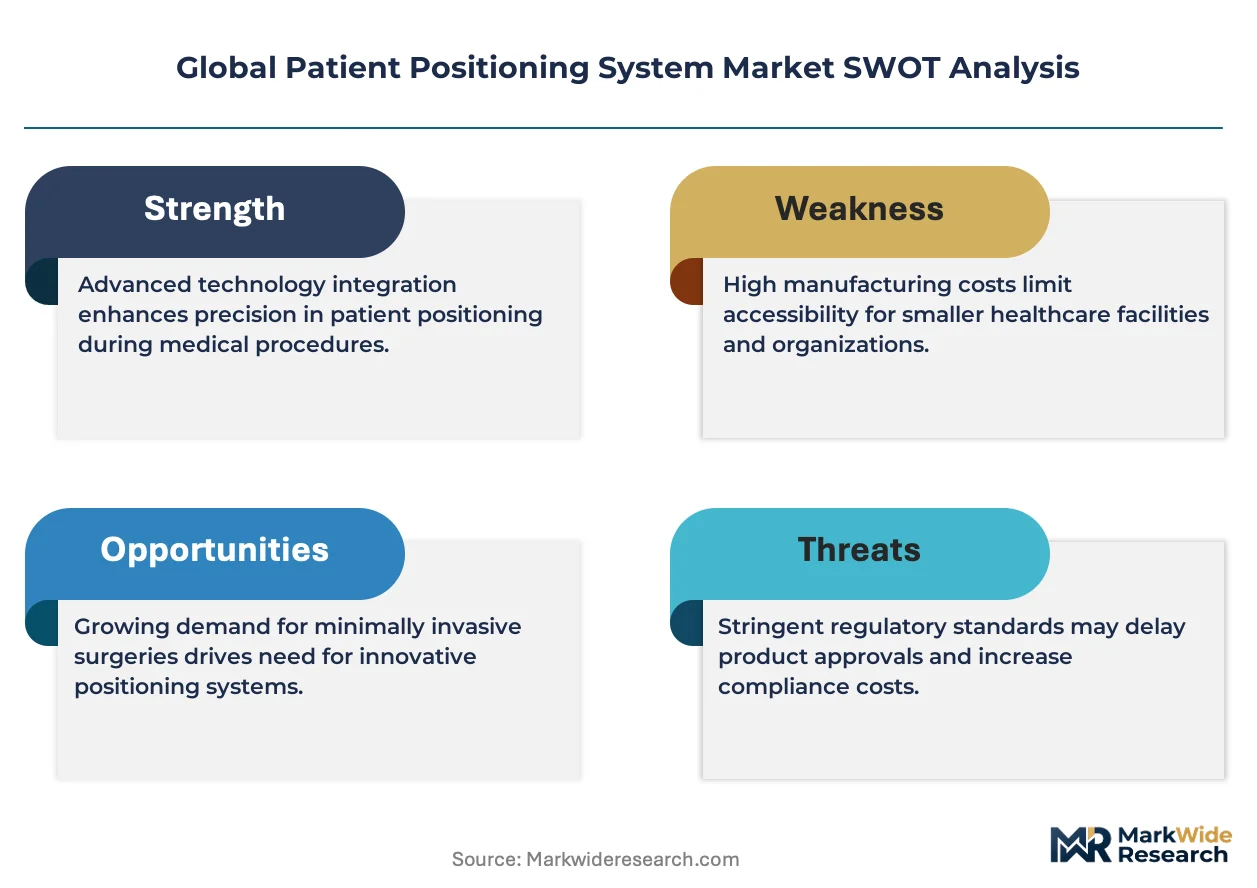
The FDA's tightened 21 CFR 892 classification for powered positioning platforms is compressing approval timelines and forcing manufacturers to front-load clinical evidence packages, redrawing competitive entry barriers across the surgical table segment.
Growth Catalysts
- EU MDR clinical evidence mandates:Class IIa and above patient support equipment now requires robust technical documentation, elevating quality standards that filter into procurement specifications across German university hospitals and Nordic healthcare systems.
- Air-filled dynamic pressure redistribution:Bariatric surgery volume expansion in the United States and Western Europe is accelerating replacement of static foam platforms with sensor-integrated air-cell systems that prevent pressure injuries in immobilized patients.
- Ambulatory surgical center expansion:Outpatient procedure migration in North America is broadening the installed base for compact, multi-position platforms designed for same-day discharge workflows.
Market Restraints
- Stainless steel and aluminum price volatility:Surgical table frame material costs fluctuate with energy-intensive smelting operations concentrated in China and Russia, compressing margin buffers for European fabricators.
- Motor and actuator supply concentration:Precision linear motion components for electronic adjustment platforms source predominantly from German and Japanese suppliers, creating single-source vulnerability for North American OEMs.
- Reusable gel pad substitution:Disposable single-use positioning accessories are displacing capital-intensive gel-based systems in cost-constrained hospital budgets, threatening aftermarket revenue streams.
Strategic Opportunities
- Japan PMDA-MDR equivalency pathway:Alignment of Japanese quality management system requirements with European standards is streamlining export certification for positioning equipment manufacturers seeking access to Tokyo's metropolitan hospital networks.
- Hybrid operating room integration:Convergence of intraoperative imaging with motor-driven articulation tables is opening specification slots for vendors capable of real-time pressure mapping synchronized with C-arm positioning.
- Direct-to-facility digital distribution:Bypassing traditional group purchasing organizations through e-procurement platforms is emerging as a channel for mid-tier manufacturers to access independent surgical centers in Australia and Canada.
Industry Challenges
- ISO 13485 audit backlog:Certification body capacity constraints are extending quality management system renewal timelines, delaying product launches for suppliers dependent on updated scope extensions.
- Legacy hydraulic system integration:Retrofitting motor-driven articulation into existing surgical suites requires electrical infrastructure upgrades that prolong installation cycles and strain hospital facilities budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Positioning System Market |
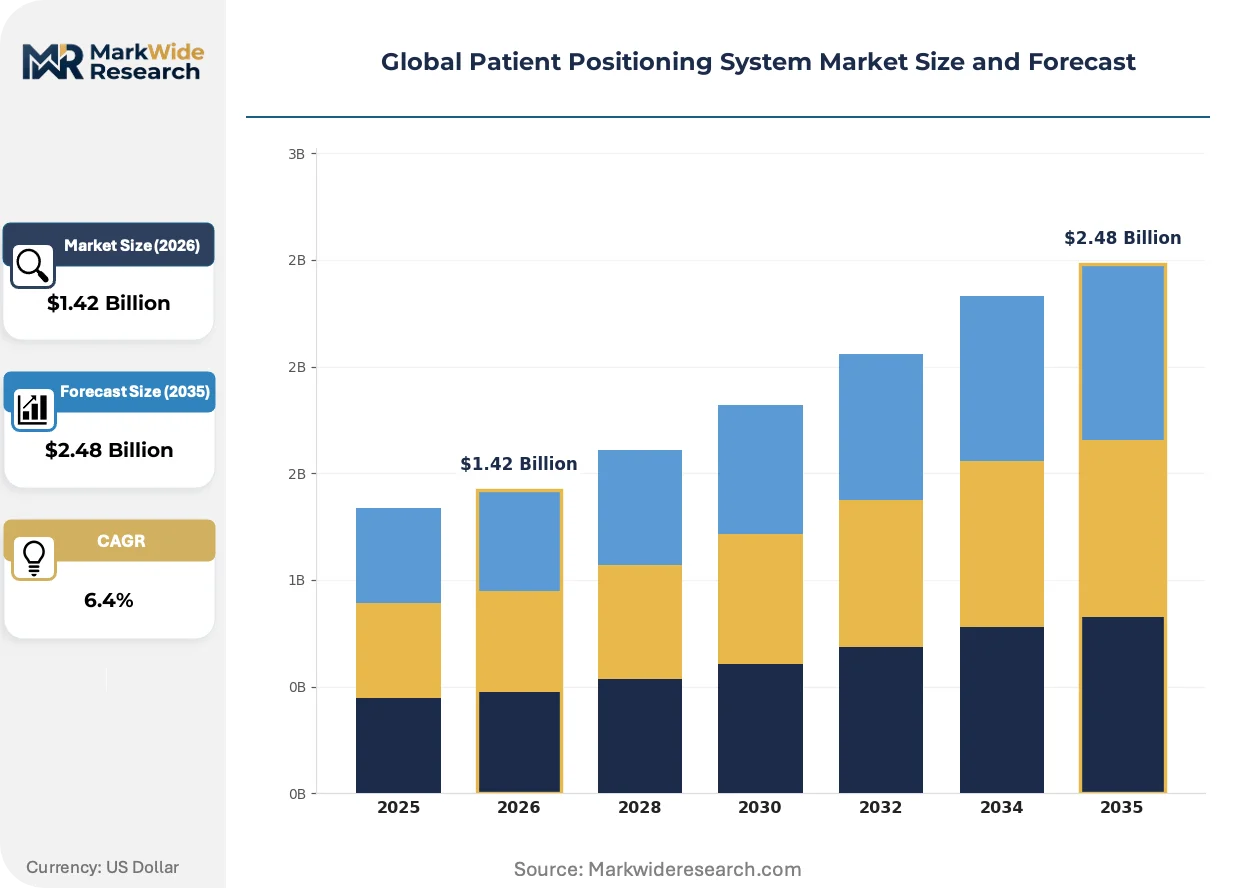
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bariatric Positioning Systems, Mobility Positioners, Pressure Redistribution Devices, Posture Correctors, Support Surfaces Application: Surgical Procedures, Physiotherapy, Emergency Care, Diagnostic Imaging, Long-Term Care End User: Hospitals, Rehabilitation Centers, Ambulatory Surgical Centers, Nursing Facilities, Home Healthcare Providers Technology: Mechanical Systems, Air-Filled Systems, Gel-Based Systems, Electronic Adjustment Platforms, Foam-Based Solutions |
| Companies Covered | Stryker Corporation, Hill-Rom Holdings, Inc., Medtronic, STERIS plc, Getinge AB, Mizuho OSI, Skytron, LLC, Medline Industries, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Positioning System Market Shifts & Advancements
Sensor-embedded pressure mapping is converging with surgical workflow software to create real-time patient risk dashboards, compressing the gap between positioning hardware and perioperative data systems.
Motor-driven articulation platforms with integrated load-cell arrays are consolidating control architectures across the premium surgical table segment. German university hospitals and Nordic integrated delivery networks are specifying these systems for bariatric and neurosurgical suites. The technology is consolidating vendor relationships by bundling pressure redistribution, imaging compatibility, and workflow connectivity into single-source procurement decisions.
EU MDR transitional provisions for legacy device certificates are compressing the window for Class IIa patient support equipment recertification. Manufacturers must resubmit technical documentation with expanded clinical evidence or withdraw products from European Economic Area markets. Air-filled positioning systems with novel pressure-cell geometries face the steepest compliance burden, as notified bodies classify dynamic redistribution mechanisms as requiring new clinical investigation.
Hospital capital committees are unbundling after-sales service contracts from equipment purchases, forcing positioning system vendors to compete on discrete maintenance and upgrade pricing. Independent service organizations are capturing calibration and preventive maintenance revenue previously captive to OEM service networks. This disintermediation is most visible in United States health systems with centralized biomedical engineering departments managing multi-vendor fleets across distributed hospital networks.
Global Patient Positioning System Market Segmentation
Patient positioning systems fragment across four intersecting dimensions that determine procurement priorities. Product type and technology choices shape capital expenditure cycles, while application specificity and end-user scale dictate service contract structures and upgrade pathways.
Product Type:
Customization intensity varies sharply across this category, from standardized pressure pads to fully configurable bariatric platforms engineered for individual patient anthropometrics.
- Bariatric Positioning Systems:Reinforced load-bearing frames accommodate patients exceeding standard weight thresholds. German university hospitals and Nordic integrated delivery networks are retrofitting operating suites with these systems as bariatric surgery volumes climb.
- Pressure Redistribution Devices:Dynamic air-cell or gel-based surfaces prevent pressure injuries during prolonged immobilization. Demand concentrates in long-term care facilities managing diabetic and immobile patient populations where pressure ulcer prevention is a CMS quality metric.
- Mobility Positioners:Articulated supports for patient transfer and limb positioning.
- Posture Correctors:Adjustable frameworks for spinal alignment during rehabilitation.
- Support Surfaces:Base layers for mattress and table integration.
Leading the category by volume: Pressure Redistribution Devices. Growing fastest: Bariatric Positioning Systems.
Application:
Procedure reimbursement rates and facility throughput requirements create tiered demand intensity across clinical settings.
- Surgical Procedures:Motor-driven articulation tables with integrated imaging compatibility dominate capital budgets. Ambulatory surgical centers in the United States are prioritizing compact multi-position platforms for same-day discharge workflows.
- Diagnostic Imaging:MRI-compatible and radiolucent positioning platforms enable intraoperative imaging without patient repositioning. Hybrid operating room installations in Japan and Germany are specifying synchronized C-arm articulation tables.
- Physiotherapy:Adjustable treatment tables for musculoskeletal rehabilitation.
- Emergency Care:Rapid-deployment stretchers and immobilization devices for trauma stabilization.
- Long-Term Care:Pressure redistribution mattresses and positioning aids for chronic care facilities.
Surgical Procedures commands the largest revenue pool. Diagnostic Imaging shows the steepest expansion trajectory as hybrid OR investments accelerate.
End User:
Purchasing authority and capital cycle timing differentiate institutional buyers from distributed care providers.
- Hospitals:Centralized procurement committees negotiate multi-year service contracts bundled with premium surgical table purchases. United States health systems with biomedical engineering departments are unbundling maintenance contracts to capture independent service organization pricing.
- Ambulatory Surgical Centers:Outpatient procedure migration is broadening demand for compact positioning equipment with rapid turnover capability. These facilities prioritize lease financing over capital purchase to preserve liquidity.
- Rehabilitation Centers:Therapy-focused positioning for functional recovery programs.
- Nursing Facilities:Cost-constrained procurement of pressure injury prevention equipment.
- Home Healthcare Providers:Lightweight, portable positioning aids for domiciliary care.
Hospitals retain dominant procurement volume. Ambulatory Surgical Centers are gaining share fastest as outpatient surgery expands.
Technology:
Supply chain concentration for precision components creates technology-tier dependency on German and Japanese actuator suppliers.
- Electronic Adjustment Platforms:Motor-driven articulation with load-cell arrays and real-time pressure mapping. EU MDR clinical evidence mandates are compressing approval timelines for these Class IIa devices, elevating entry barriers.
- Air-Filled Systems:Dynamic pressure-cell geometries redistribute load across bariatric and immobile patients. FDA 21 CFR 892 classification updates are tightening submission requirements for powered platforms in this category.
- Mechanical Systems:Manual hydraulic or crank-adjusted platforms for cost-sensitive installations.
- Gel-Based Systems:Viscoelastic polymer pads facing substitution pressure from single-use disposables.
- Foam-Based Solutions:Static cushioning for basic pressure management applications.
Electronic Adjustment Platforms lead technology investment. Air-Filled Systems are climbing the fastest as dynamic pressure redistribution displaces static foam.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech special economic zones in Costa Rica and Puerto Rico are channeling capital toward surgical equipment manufacturing, concentrating supply chain investment near major North American hospital networks while EU MDR compliance deadlines accelerate facility certification in Ireland and the Netherlands.
United States
Ambulatory surgical centers in Texas and Florida are retrofitting operating suites with compact positioning platforms as outpatient procedure volumes climb. FDA's tightened 21 CFR 892 classification is compressing approval timelines for powered surgical tables. The Dallas-Fort Worth metroplex anchors distribution networks serving ASC chains across the Southwest.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are specifying integrated pressure redistribution systems for bariatric and neurosurgical suites. EU MDR clinical evidence mandates for Class IIa patient support equipment are elevating procurement specifications across German purchasing networks. The Stuttgart industrial corridor concentrates precision actuator manufacturing for electronic adjustment platforms.
Japan
Metropolitan hospital networks in Tokyo and Osaka are prioritizing hybrid operating room installations with synchronized C-arm articulation tables. PMDA alignment with MDR equivalency agreements is streamlining export certification pathways for European positioning equipment manufacturers. The Nagoya medical device cluster is expanding capacity for MRI-compatible platform fabrication.
China
Tier-3 hospitals in Jiangsu and Zhejiang provinces are replacing legacy hydraulic tables with motor-driven articulation platforms. NMPA medical device registration requirements are extending clinical trial timelines for imported electronic positioning systems. The Suzhou industrial park hosts joint-venture manufacturing for air-filled pressure redistribution devices.
United Kingdom
NHS trusts in Greater London and the Midlands are unbundling after-sales service contracts from surgical table purchases to capture independent service organization pricing. MHRA post-Brexit regulatory autonomy is diverging from EU MDR implementation timelines for legacy device recertification. The Cambridge medical technology cluster is developing sensor-embedded pressure mapping software for perioperative risk dashboards.
Global Patient Positioning System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operating room portfolios commanding premium positioning while component suppliers capture recurring aftermarket revenue. The market structure concentrates around three tiers: full-system vendors bundling hardware with software connectivity, mid-tier fabricators competing on discrete maintenance pricing, and regional specialists serving national hospital procurement frameworks. Dominant competitive moves include strategic partnerships for imaging compatibility certification and geographic expansion through distributor acquisition in Asia-Pacific markets.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic exemplify full-system integration archetypes, while Hill-Rom Holdings, Inc. represents the channel-relationship-dependent tier. Getinge AB occupies a position emphasizing infection control compatibility across positioning product lines, reflecting how European vendors differentiate through clinical workflow integration rather than standalone hardware specifications.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom Holdings, Inc. |
| Medtronic |
| STERIS plc |
| Getinge AB |
| Mizuho OSI |
| Skytron, LLC |
| Medline Industries |
| Smith & Nephew |
| Others |
Supply & Pricing Matrix
Precision actuator engineering talent concentrated in Stuttgart and Nagoya creates labor-cost differentials that widen pricing-tier spreads between premium electronic adjustment platforms and commodity mechanical systems.
Pricing Analysis
Short lead-time premiums command pricing spreads across the surgical table segment, with German university hospitals paying elevated rates for rapid delivery of motor-driven articulation platforms while spot inventory of hydraulic legacy systems trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates sensor-embedded pressure mapping systems from basic mechanical platforms and refurbished equipment. Cost compression in the mid-tier segment is intensifying because stainless steel and aluminum price volatility erodes fabricator margins. Ambulatory surgical centers exhibit highest price sensitivity due to lease financing constraints, while integrated delivery networks in Nordic healthcare systems demonstrate lowest sensitivity through bundled multi-year service contracts.
Supply Chain Analysis
Domestic-content mandates in China's NMPA medical device registration framework are reshaping sourcing patterns for air-filled pressure redistribution systems, compelling joint-venture manufacturing in Suzhou industrial parks. Precision linear motion components draw from Germany, Japan, and South Korea, with sensor arrays and load-cell arrays resting on Taiwanese semiconductor fabrication. Single-source vulnerability concentrates in German and Japanese actuator suppliers, exposing North American OEMs to disruption risk. Distribution runs through hospital purchasing networks and group purchasing organizations, with direct-to-facility digital distribution emerging for independent surgical centers in Australia and Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patient positioning system market sits in a technology-transition phase, with electronic adjustment platforms displacing legacy hydraulic systems across hospital capital budgets.
For Market Incumbents: Anticipate margin compression from independent service organizations capturing calibration revenue by unbundling after-sales contracts and investing in ISO 13485 certification scope extensions to accelerate EU MDR compliance timelines for Class IIa devices. For New Entrants and Emerging Players: Begin with compact multi-position platforms targeting ambulatory surgical centers in Texas and Florida, where outpatient procedure migration creates white-space demand; pursue direct-to-facility digital distribution to bypass entrenched group purchasing organization channels. For Investors and Strategic Acquirers: Re-rating potential sits with sensor-embedded pressure mapping software developers given convergence with perioperative data systems; long-term viability hinges on hybrid operating room integration capability, with PMDA-MDR equivalency pathway completion as the inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR 892 Submission Pathway | Tightened classification rules compress approval timelines for powered positioning platforms. |
| EU MDR Clinical Evidence Package | Class IIa recertification mandates elevate quality standards across German purchasing networks. |
| Hospital System Partnership | Integrated delivery networks in Nordic healthcare systems consolidate vendor relationships. |
| Software Companion Development | Real-time pressure mapping dashboards converge positioning hardware with perioperative data systems. |
| Reimbursement Strategy | CMS quality metrics for pressure ulcer prevention drive demand for dynamic air-cell systems. |
Research Methodology
Multi-period observation of surgical procedure volumes, regulatory submission timelines, and hospital capital expenditure cycles anchored the trend analysis, supplemented by interviews with biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and perioperative nurses. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, hospital procurement databases, and CMS Medicare cost reports. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, application, end user, and technology dimensions.
Input-output matrix framing connected procedure volume forecasts to equipment replacement cycles, with CAGRs derived from regression analysis across the projection horizon. Segmentation dimensions modeled include product customization intensity, surgical specialty requirements, facility scale tiers, and regional regulatory clusters. Forecast inputs incorporated bariatric surgery volume trajectories and hybrid operating room installation pipelines.
Regulatory timeline delays, raw material price volatility, and supply chain disruption are the dominant revision risks to the analytical framework. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Multiparameter Patient Monitoring System Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market