
 Intracranial Stents Total Addressable Market | 2026-2036
Intracranial Stents Total Addressable Market Size, Share, and Industry Trends Forecast 2026-2036
Intracranial Stents Total Addressable Market Intelligence
Hospital procurement of intracranial stents is tilting toward bundled contract arrangements with integrated device vendors. Medtronic leverages its broad neurovascular portfolio to sustain multi-year supply agreements with academic medical centers. Stryker competes through specialized sales teams that navigate complex catheterization lab purchasing committees. Abbott Laboratories anchors its position via differentiated delivery system designs that reduce procedural variability.
Intracranial stents are implantable tubular scaffolds, typically laser-cut from nitinol or cobalt-chromium alloys, designed to maintain cerebral vessel patency after endovascular intervention for aneurysm or stenosis. These devices function primarily to prevent stroke recurrence by reinforcing weakened arterial walls and redirecting blood flow away from pathological sacculations. Self-expanding stents occupy the dominant share of product type revenue due to their conformability in tortuous intracranial anatomy, while bioabsorbable materials represent the fastest-growing material category as clinicians seek to eliminate permanent foreign body retention. Hospitals command the largest end user segment by procedure volume, though specialty centers are capturing margin pools through focused cerebrovascular programs that command premium reimbursement.
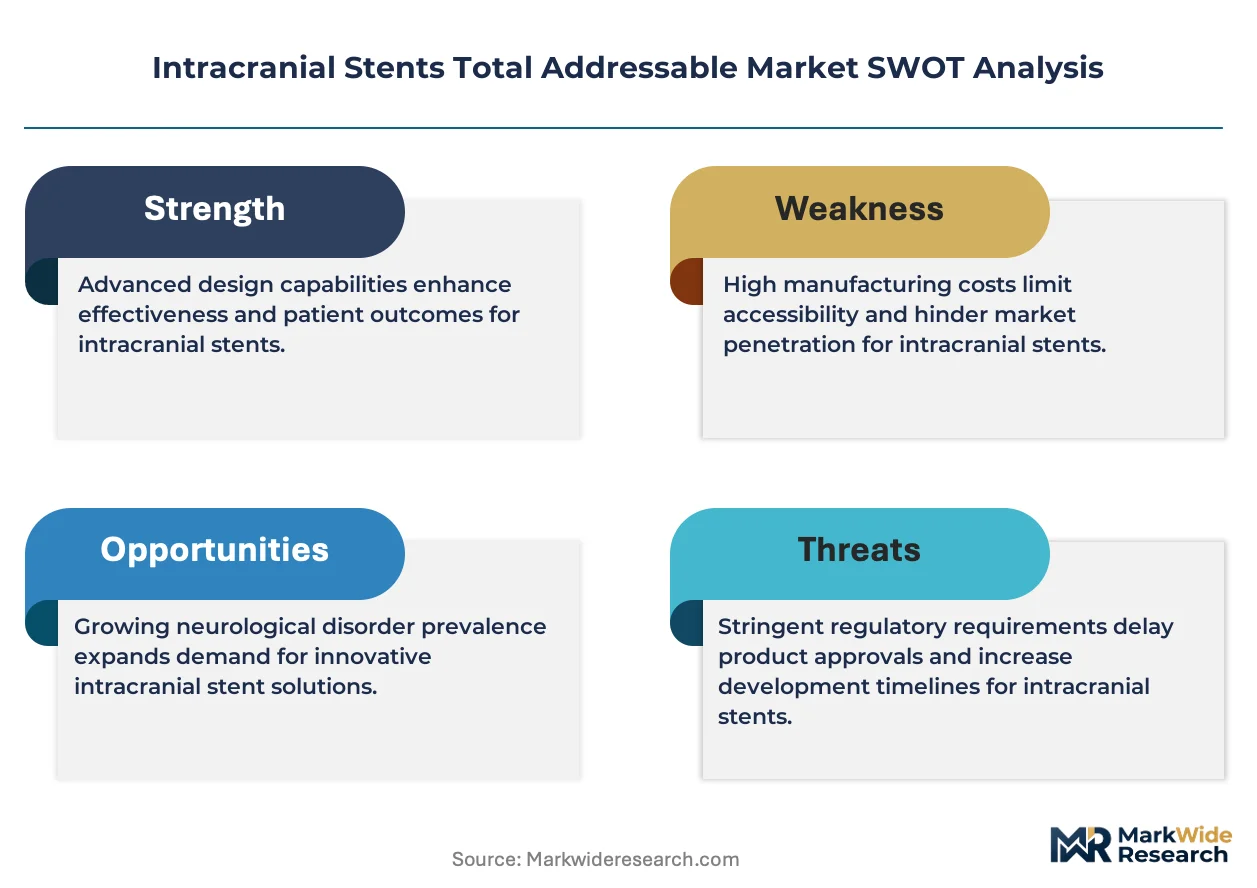
The FDA maintains stringent premarket approval requirements under 21 CFR 882 for intracranial stent devices, while the EU MDR imposes enhanced clinical evidence standards through notified body conformity assessments. Japan's PMDA requires local clinical trials for novel neurovascular implants, creating staggered market entry timelines across major regulatory jurisdictions. Stakeholders must monitor evolving real-world evidence requirements that increasingly determine post-market surveillance obligations and competitive access speed.
Market Dynamics
Hospital procurement committees are consolidating vendor relationships around integrated neurovascular portfolios, forcing device manufacturers to bundle stent delivery systems with embolization coils and aspiration catheters rather than compete on standalone implant pricing.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for intracranial stents addressing unmet stroke prevention needs accelerate commercial timelines and de-risk development investments for novel scaffold geometries.
- Germany's Diagnosis-Related Group Reimbursement:Established reimbursement codes for endovascular aneurysm repair procedures sustain procedural volumes at academic stroke centers and community hospitals alike.
- Nitinol laser-cutting advances:Improved manufacturing tolerances enable thinner strut profiles that enhance vessel wall apposition in tortuous cerebral anatomy without sacrificing radial force.
Market Restraints
- Platinum-iridium alloy cost volatility:Marker band materials face supply concentration from South African mining operations, creating input cost unpredictability for radiopaque stent designs.
- Japan PMDA local trial mandates:Novel neurovascular implants require domestic clinical evidence generation, adding years to market entry timelines compared with FDA or CE mark pathways.
- Flow diversion catheters:Endoluminal flow disruption devices substitute for traditional stent-assisted coiling in wide-neck aneurysm cases, compressing addressable volume for intraluminal scaffolds.
Strategic Opportunities
- Brazil ANVISA harmonization:Emerging regulatory alignment with FDA standards creates expedited entry pathways for stent manufacturers seeking Latin American expansion beyond established North American and European positions.
- Bioabsorbable magnesium alloys:Temporary scaffold materials that dissolve post-healing eliminate long-term foreign body risks and open pediatric and young-adult indications currently contraindicated for permanent implants.
- Telestroke network integration:Rural hospital hub-and-spoke models for acute stroke care expand eligible patient catchment areas, driving demand for transferable neurointerventional device platforms.
Industry Challenges
- Neurointerventionalist training pipelines:Fellowship programs produce fewer qualified operators than procedural volume growth requires, creating utilization bottlenecks at expanding stroke centers.
- EU MDR technical documentation:Enhanced clinical evidence requirements for Class III implantable devices demand retrospective registry builds and prospective post-market studies that strain smaller manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intracranial Stents Total Addressable Market |
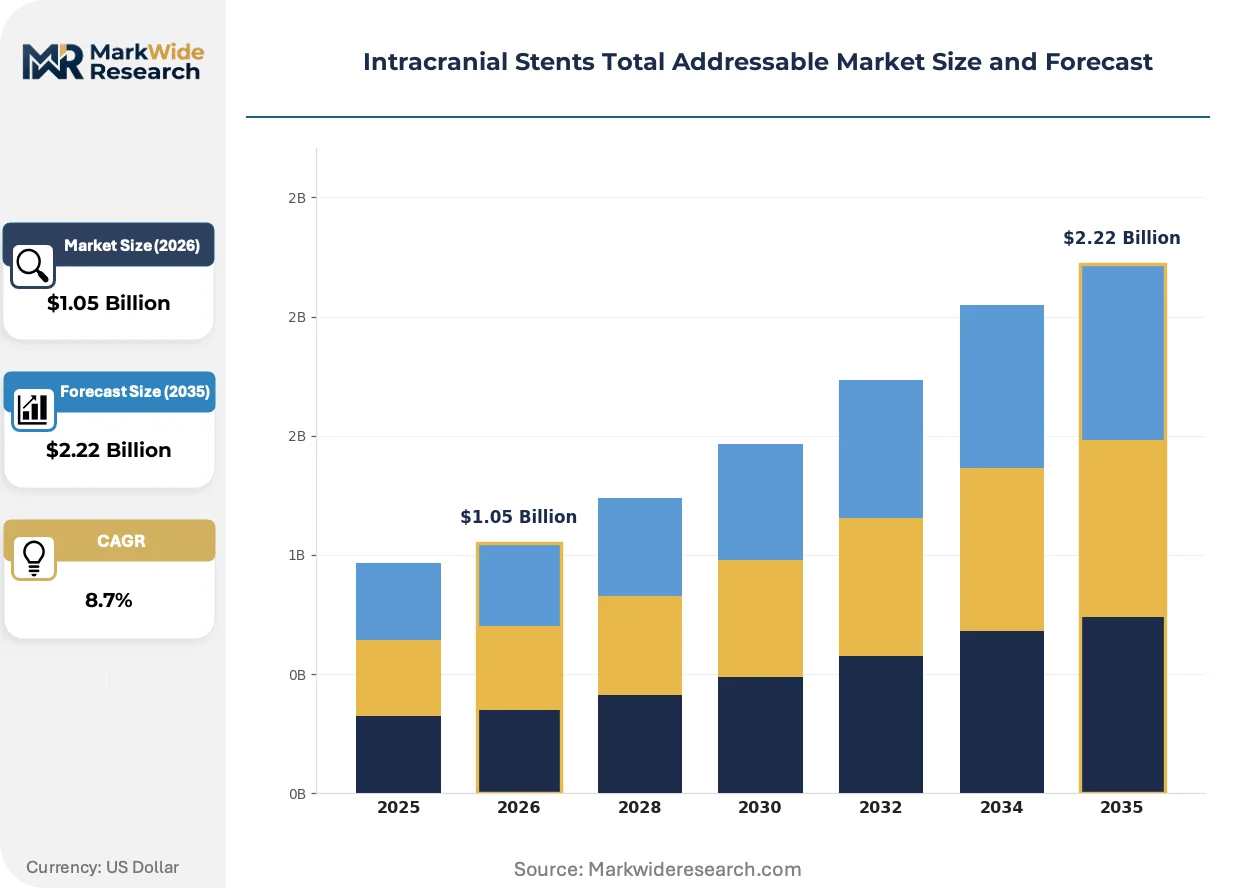
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-expanding Stents, Balloons, Coils, Catheters Application: Aneurysm Treatment, Arteriovenous Malformation, Ischemic Stroke, Carotid Artery Disease End User: Hospitals, Outpatient Clinics, Research Facilities, Specialty Centers Material: Metal, Polymer, Bioabsorbable, Coated |
| Companies Covered | Medtronic, Stryker, Johnson & Johnson, Abbott Laboratories, Terumo Corporation, MicroPort Scientific Corporation, Boston Scientific Corporation, Acandis GmbH, DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intracranial Stents Total Addressable Market Strategic Shifts & Innovations
Device architecture is converging toward adaptive platforms that modulate mechanical properties along the stent length, responding to heterogeneous vessel wall stress distributions rather than treating intracranial arteries as uniform cylindrical conduits.
Laser-cut nitinol stents with differential cell geometry are hybridizing with drug-eluting surface technologies adapted from coronary applications. Academic medical centers in the United States are piloting these dual-function platforms for recurrent intracranial stenosis cases. The convergence is compressing development timelines for bioengineered vascular scaffolds by leveraging established coating infrastructure from cardiology supply chains.
EU MDR notified body conformity assessments are tightening evidentiary standards for neurovascular implants through enhanced scrutiny of long-term patency data. Manufacturers must now submit systematic literature reviews and patient-level registry outcomes rather than relying on predicate device equivalence. Self-expanding stent product lines face the steepest compliance burden due to their dominant market position and extensive legacy device histories requiring retrospective safety documentation.
Catheterization lab purchasing committees are unbundling device procurement from procedure reimbursement, separating implant costs from physician and facility fees. Integrated delivery networks in Germany are consolidating vendor contracts across multiple hospital sites to extract volume-based discounts. This behavioral shift is most visible in North Rhine-Westphalia, where three-hospital systems now negotiate multi-year supply agreements covering entire neurovascular device categories rather than individual product lines.
Intracranial Stents Total Addressable Market Segmentation
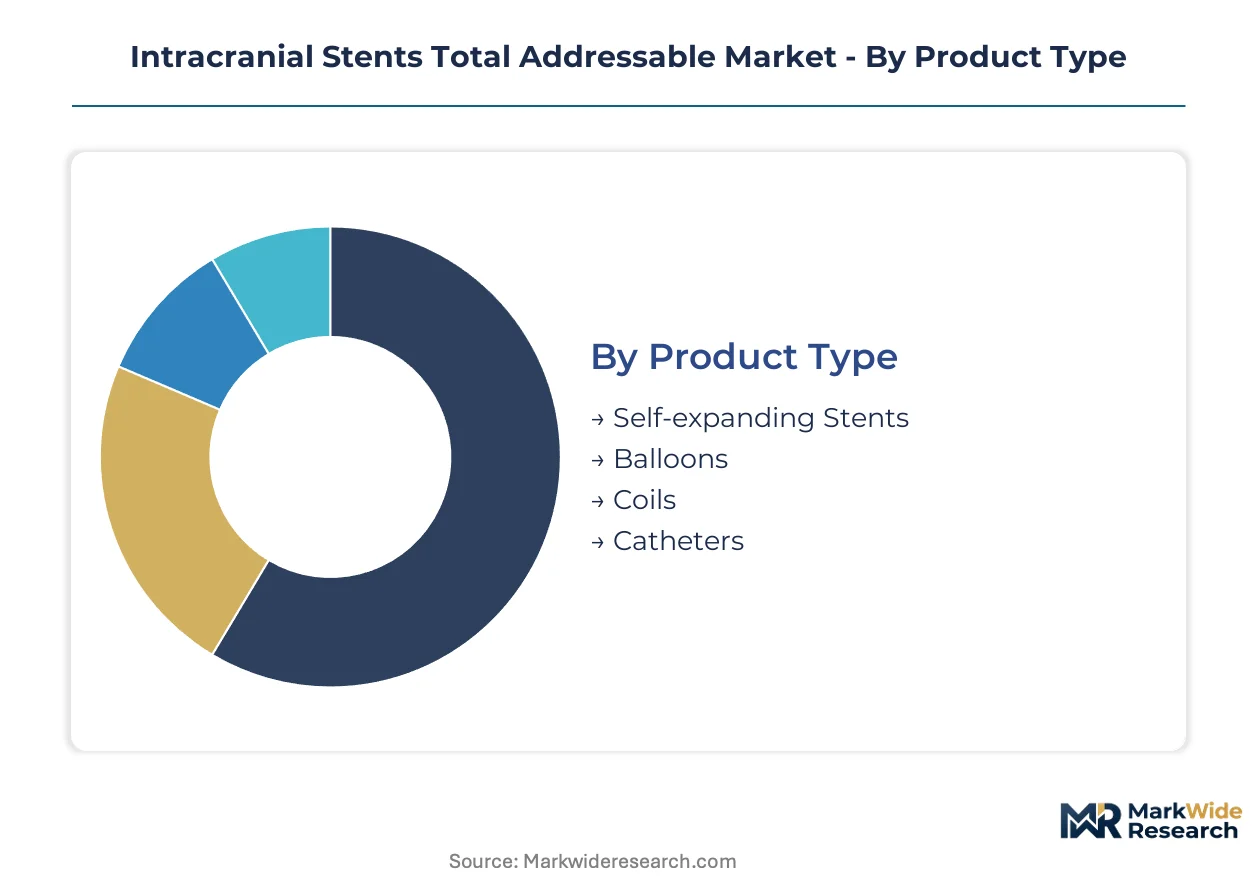
Intracranial stent procurement patterns diverge sharply across clinical settings and anatomical targets. Manufacturers must align product architectures with distinct reimbursement pathways and procedural workflows that govern each segment's purchasing behavior.
Product Type:
Cost tier differentiation separates premium self-expanding platforms from commoditized delivery accessories.
- Self-expanding Stents:Laser-cut nitinol scaffolds deploy radial force against vessel walls without balloon inflation. Academic stroke centers in the United States concentrate demand for these devices due to tortuous intracranial anatomy requiring conformable apposition.
- Balloons:Compliant and semi-compliant dilation catheters predilate stenotic lesions and post-dilate deployed stents. German Diagnosis-Related Group reimbursement bundles favor their use in carotid artery interventions at high-volume community hospitals.
- Coils:Platinum embolization devices occlude aneurysm sacs independently or alongside stent scaffolding.
- Catheters:Delivery sheaths and microcatheters enable device navigation through cerebral vasculature.
Self-expanding stents hold installed capacity. Catheters are rotating up the share rankings.
Application:
Volume concentration follows the geographic distribution of aging demographics and stroke incidence patterns.
- Aneurysm Treatment:Wide-neck saccular aneurysms require stent-assisted coiling or flow diversion. Japanese stroke centers generate concentrated procedural volume due to elevated intracranial aneurysm prevalence in elderly populations.
- Ischemic Stroke:Intracranial atherosclerotic disease demands stent revascularization when medical therapy fails. United States comprehensive stroke centers drive adoption following updated guidelines expanding endovascular eligibility windows.
- Arteriovenous Malformation:Congenial vascular tangles occasionally require stent deployment for nidal compartmentalization.
- Carotid Artery Disease:Extracranial stenosis treatment overlaps with coronary intervention techniques and device platforms.
Aneurysm treatment holds installed capacity. Ischemic stroke applications are rotating up the share rankings.
End User:
Customer type determines purchasing committee composition and contract negotiation leverage.
- Hospitals:Integrated delivery networks consolidate neurovascular procurement across catheterization labs, emergency departments, and intensive care units. United States academic medical centers command multi-year supply agreements through bundled device categories.
- Specialty Centers:Dedicated cerebrovascular institutes capture premium reimbursement through focused physician staffing and procedure concentration. German outpatient stroke units in North Rhine-Westphalia exemplify this model.
- Outpatient Clinics:Ambulatory surgical centers perform select diagnostic and minor interventional procedures.
- Research Facilities:Translational medicine institutes evaluate novel scaffold materials and drug-eluting platforms.
Hospitals hold installed capacity. Specialty centers are rotating up the share rankings.
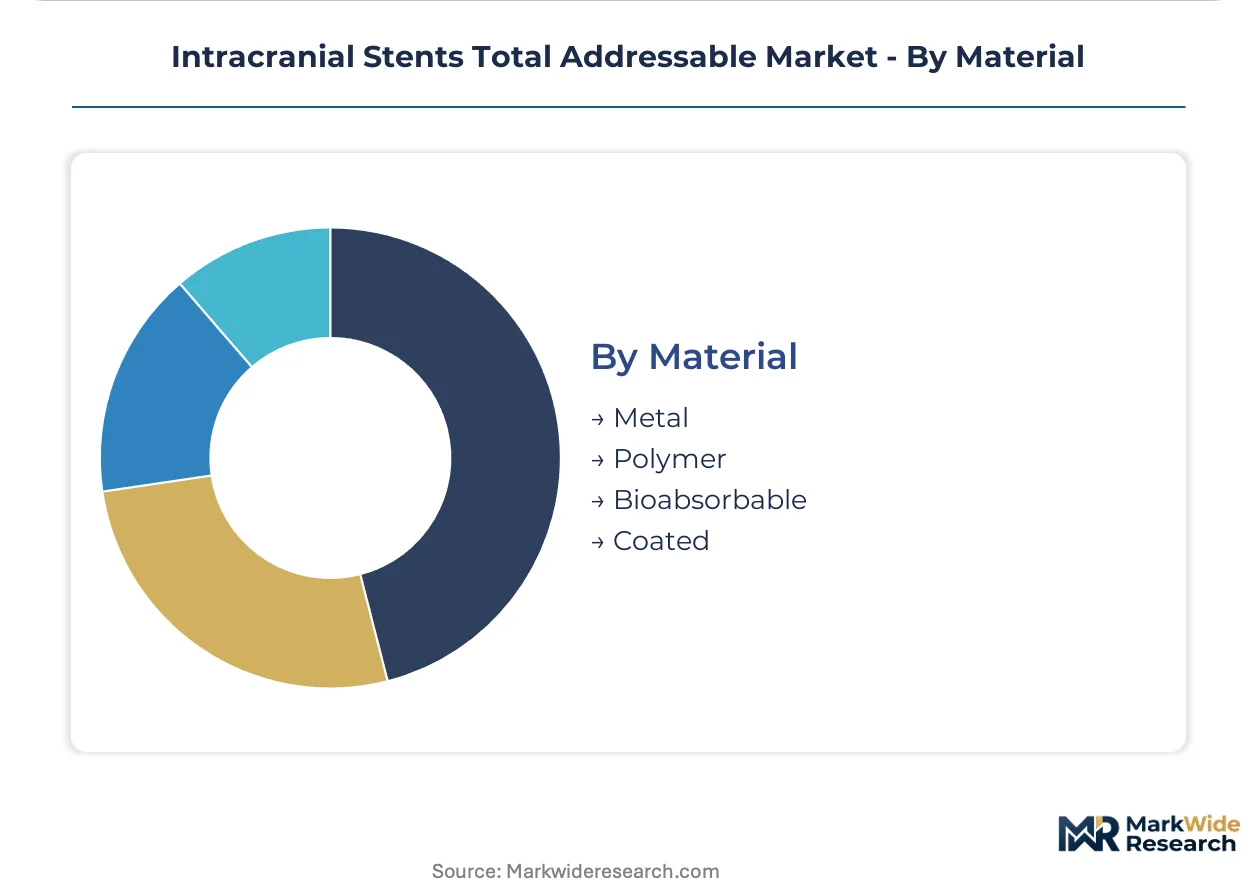
Material:
Supply concentration for raw inputs shapes margin structures and technology roadmaps.
- Metal:Nitinol and cobalt-chromium alloys dominate permanent scaffold manufacturing. South African platinum-iridium mining concentration creates marker band cost volatility for radiopaque designs.
- Bioabsorbable:Magnesium and polymer alloys dissolve post-healing, eliminating long-term foreign body risks. Pediatric and young-adult indications currently contraindicated for permanent implants represent the steepest expansion trajectory.
- Polymer:Synthetic matrices serve as temporary structural elements or drug-eluting reservoirs.
- Coated:Surface modifications deliver antiproliferative agents adapted from coronary drug-eluting stent platforms.
Metal holds installed capacity. Bioabsorbable materials are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German stroke centers while Japanese procurement faces extended regulatory timelines that compress margin capture. The United States sustains procedural volume leadership through established reimbursement corridors.
United States
Comprehensive stroke centers in Boston and Houston drive self-expanding stent adoption through expanded endovascular eligibility windows. FDA breakthrough device designations accelerate commercial timelines for novel scaffold geometries. The Cleveland Clinic anchors multi-hospital supply agreements that bundle neurovascular portfolios across catheterization labs.
Germany
Diagnosis-Related Group reimbursement codes sustain procedural volumes at academic centers in North Rhine-Westphalia and Bavaria. EU MDR notified body assessments impose enhanced clinical evidence standards for Class III implants. Munich-based stroke units command premium reimbursement through focused cerebrovascular programs.
Japan
Elevated intracranial aneurysm prevalence in elderly populations generates concentrated procedural volume at Tokyo and Osaka stroke centers. PMDA mandates domestic clinical trials for novel neurovascular implants, adding years to market entry. Kanto region academic hospitals pilot drug-eluting surface technologies adapted from coronary platforms.
China
Expanding neurointerventional capabilities in Shanghai and Beijing teaching hospitals drive demand for conformable nitinol scaffolds. NMPA regulatory harmonization with international standards creates expedited review pathways for established device geometries. Yangtze River Delta medical centers consolidate vendor relationships around integrated delivery systems.
Brazil
ANVISA regulatory alignment with FDA standards opens expedited entry pathways for manufacturers seeking Latin American expansion. São Paulo stroke centers develop hub-and-spoke telestroke networks that expand eligible patient catchment. Southeast Brazil academic hospitals anchor regional training pipelines for neurointerventional specialists.
Intracranial Stents Total Addressable Market Key Industry Players
Integrated neurovascular conglomerates and specialized cerebrovascular device firms split the market between bundled portfolio offerings and focused scaffolding expertise. The vendor base concentrates around manufacturers with captive nitinol processing capabilities and established catheterization lab relationships. Diversified medtech conglomerates and pure-play neurovascular specialists represent the dominant strategic archetypes. Competitive positioning depends on multi-year supply agreement penetration and regulatory approval velocity across FDA, CE mark, and PMDA jurisdictions.
Within the integrated conglomerate tier, Medtronic and Stryker exemplify portfolio breadth strategies that bundle stent delivery systems with embolization coils and aspiration catheters. Abbott Laboratories occupies a differentiated position through specialized delivery system designs that reduce procedural variability in tortuous cerebral anatomy. These three anchors represent distinct approaches to hospital procurement committee navigation.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Abbott Laboratories |
| Terumo Corporation |
| MicroPort Scientific Corporation |
| Boston Scientific Corporation |
| Acandis GmbH |
| DePuy Synthes |
| Others |
Cost & Logistics Intelligence
South African platinum-iridium mining concentration for radiopaque marker bands feeds directly into margin compression for nitinol stent manufacturers, with downstream pricing power pooling at German integrated delivery networks that negotiate multi-year bundled contracts.
Pricing Analysis
Configured-to-order pricing for patient-specific stent geometries commands substantial premiums over standard catalog configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery system complexity and clinical indication breadth. Price differentiation hinges on FDA breakthrough designation status and procedural training bundling. Cost compression in standard self-expanding platforms is intensifying because catheterization lab purchasing committees now unbundle device procurement from facility fees. Community hospitals in the United States exhibit highest price sensitivity; academic stroke centers in Germany show lowest.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for nitinol feedstock and laser-cutting equipment. Manufacturing draws from United States, Germany, and China for nitinol alloy processing, with South Africa and Russia supplying platinum-group metals for radiopacity. Raw material dependencies center on nickel-titanium shape memory alloys, cobalt-chromium tubing, and platinum-iridium marker bands. Single-source vulnerability concentrates in South African mining operations for radiopaque elements. Distribution runs through integrated delivery networks and specialized neurovascular distributors serving catheterization labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow diversion catheters pose acute substitution risk to traditional intraluminal stent-assisted coiling, forcing incumbents to defend procedural volume through integrated portfolio positioning.
For Market Incumbents: Harden market position by deepening backward integration into captive nitinol laser-cutting capabilities that reduce dependency on third-party scaffold manufacturers. Secure multi-year supply agreements with academic stroke centers before EU MDR compliance costs eliminate smaller competitors. Vertical integration into delivery system manufacturing protects margin pools against catheterization lab unbundling trends. For New Entrants and Emerging Players: Pursue bioabsorbable magnesium alloy platforms for pediatric and young-adult indications currently contraindicated for permanent implants. Brazil's ANVISA-FDA harmonization offers the most penetrable regulatory pathway for Latin American market establishment. Target telestroke network hubs in Southeast Brazil and China's Yangtze River Delta with transferable neurointerventional device platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play neurovascular specialists lacking integrated coil and catheter portfolios. Long-term viability over the coming decade rests on regulatory approval velocity across FDA, CE mark, and PMDA jurisdictions. Watch for FDA breakthrough device designation announcements as inflection indicators for portfolio acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Build | Retrospective registry assembly satisfies notified body scrutiny for Class III implantable devices. |
| Hospital System Partnership | Multi-year supply agreements with Cleveland Clinic-type academic anchors lock out competitors. |
| Reimbursement Strategy | Germany's Diagnosis-Related Group codes sustain procedural volumes at community hospitals. |
| Software Companion Development | Procedural planning algorithms reduce variability in tortuous intracranial anatomy navigation. |
| CE Marking Pathway | Enhanced clinical evidence standards compress competitive access speed for legacy device lines. |
Research Approach
Operator-level perspectives from neurointerventionalists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against FDA 510(k) and PMA filings, EU MDR notified body assessment records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling triangulated with top-down manufacturer revenue estimates.
Scenario-bracketing around regulatory approval timelines and reimbursement pathway stability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, material, and regional regulatory cluster. CAGRs derived from procedure volume growth trajectories, pricing trend assumptions, and technology substitution curves. Forecast inputs incorporated neurointerventionalist training pipeline constraints and EU MDR compliance burden estimates.
Sensitivities concentrate around PMDA trial mandate durations, platinum-iridium cost volatility, and flow diversion catheter adoption curves. Forecasts reflect documented assumptions regarding regulatory harmonization progress and reimbursement code maintenance. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Implants Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Artificial Eye Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Contraceptive Rings Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Wearable ECG Sensor Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Injection Pen Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market