

Respiration Monitor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Respiration Monitor Belt Market Insights
Project finance for distributed diagnostic equipment is fragmenting the competitive landscape for respiration monitor belts, lowering capital barriers for regional distributors and specialty manufacturers. Medtronic leverages its vertically integrated supply chain to sustain pricing power across hospital procurement channels. Koninklijke Philips anchors its position through R&D intensity in wireless biosignal processing. ResMed specializes in sleep-disorder applications, occupying a defensible niche in home-based respiratory diagnostics.
A respiration monitor belt is a wearable thoracic or abdominal strap incorporating electromechanical sensors—typically piezoelectric films, strain gauges, or respiratory inductance plethysmography coils—that transduce chest wall motion into calibrated respiratory waveforms for clinical or athletic assessment. The device quantifies tidal volume, respiratory rate, and breathing pattern irregularities, serving pulmonologists, sleep technicians, and sports scientists who require ambulatory or bedside respiratory monitoring without invasive instrumentation. Wireless belt configurations lead the product type landscape by enabling continuous data streaming to cloud-based analytics platforms, while textile-integrated belts represent the fastest-growing segment as manufacturers embed conductive yarns directly into elastic garments to improve patient comfort during extended monitoring sessions. Acoustic sensor technology commands premium positioning in neonatal units where non-contact respiratory surveillance minimizes skin irritation in premature infants.
FDA 510(k) clearance requirements shape product development timelines and clinical validation burdens for manufacturers targeting the United States, while EU MDR conformity assessments under Notified Body supervision determine market access across European member states. Japan's PMDA enforces stringent electrical safety and biocompatibility standards for wearable medical devices, creating additional compliance layers for exporters. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payors recalibrate coverage policies for ambulatory respiratory diagnostics.
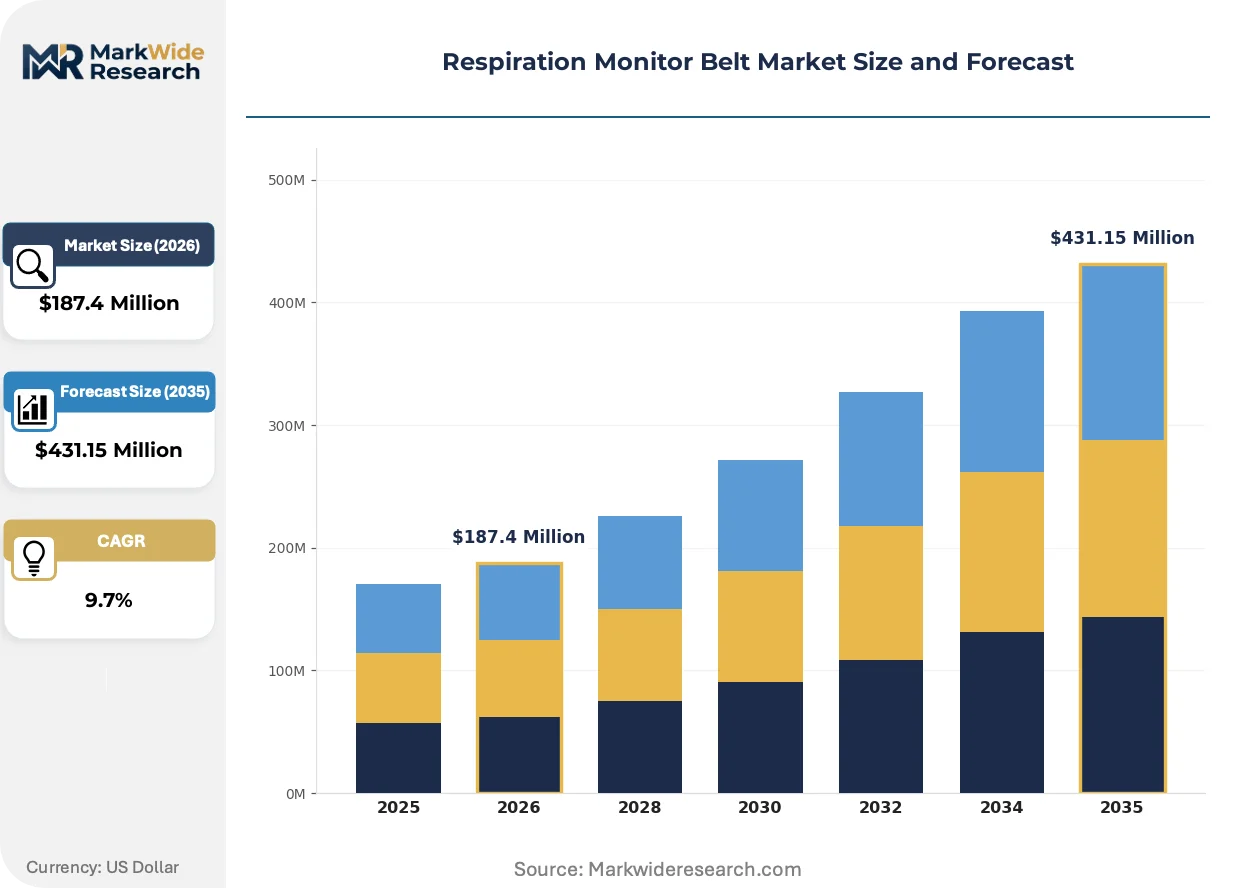
Market Dynamics
Wireless biosignal streaming and textile-integrated conductive yarns are compressing hardware margins while expanding addressable use cases beyond clinical settings into athletic performance and home-based chronic disease management.
Growth Catalysts
- EU MDR conformity assessments:Germany's sleep clinics are expanding diagnostic capacity under Notified Body supervision, mandating certified respiratory monitoring equipment for apnea screening protocols.
- Respiratory inductance plethysmography coils:These sensors enable non-invasive tidal volume quantification in neonatal intensive care, driving replacement demand for legacy contact-based systems.
- Japan's aging care infrastructure:METI promotional programs for home-monitoring technologies are accelerating deployment of ambulatory belts in community-based elder care settings.
Market Restraints
- Piezoelectric film supply concentration:Asian specialty polymer manufacturers control critical raw material inputs, exposing downstream belt producers to input cost volatility and allocation risk.
- PMDA electrical safety validation:Japan's biocompatibility and electromagnetic compatibility testing extends product development timelines by 8-14 months for wearable medical device entrants.
- Optical respiratory monitoring:Camera-based contactless systems threaten substitution in low-acuity settings where clinical-grade precision is not mandatory.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are creating localized production hubs for export-oriented respiratory monitoring equipment.
- Cloud-native analytics platforms:Integration of belt hardware with AI-driven sleep scoring algorithms opens recurring software revenue streams alongside device sales.
- Sports science laboratories:Athletic performance facilities in Australia and the United Kingdom are adopting thoracic strain gauges for respiratory muscle training protocols.
Industry Challenges
- FDA 510(k) predicate device strategy:Manufacturers face narrowing pathways for substantial equivalence claims as predicate devices incorporate increasingly divergent sensor architectures.
- Legacy hospital IT integration:Belt data streaming protocols require middleware development to interface with entrenched electronic health record systems and bedside monitor networks.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiration Monitor Belt Market Trends and Innovations
Continuous miniaturization of electromechanical transducers and algorithmic advancement in artifact rejection are enabling clinically valid respiratory monitoring in environments previously considered technically hostile.
Textile-integrated conductive yarn architectures are embedding respiratory inductance plethysmography coils directly into elastic garment structures. Sleep technicians in tertiary care centers are adopting these configurations for overnight polysomnography studies. The elimination of discrete sensor housings is rendering obsolete conventional strap-and-buckle belt assemblies that generate pressure artifacts during position changes.
EU MDR Article 10 technical documentation requirements are mandating clinical performance validation for Class IIa wearable devices. Notified Bodies in Germany and the Netherlands are enforcing stricter biocompatibility testing protocols for prolonged skin contact materials. Manufacturers targeting European sleep clinic procurement channels are restructuring quality management systems to accommodate unannounced audits and post-market surveillance obligations.
Hospital procurement committees are unbundling hardware acquisition from data analytics subscriptions, treating respiratory belts as commodity peripherals rather than integrated diagnostic systems. Group purchasing organizations in the United States are consolidating vendor lists around wireless platforms with open API architectures. This purchasing pattern compression is most visible in integrated delivery networks seeking to standardize respiratory monitoring infrastructure across multi-site sleep center operations.
Respiration Monitor Belt Market Segmentation
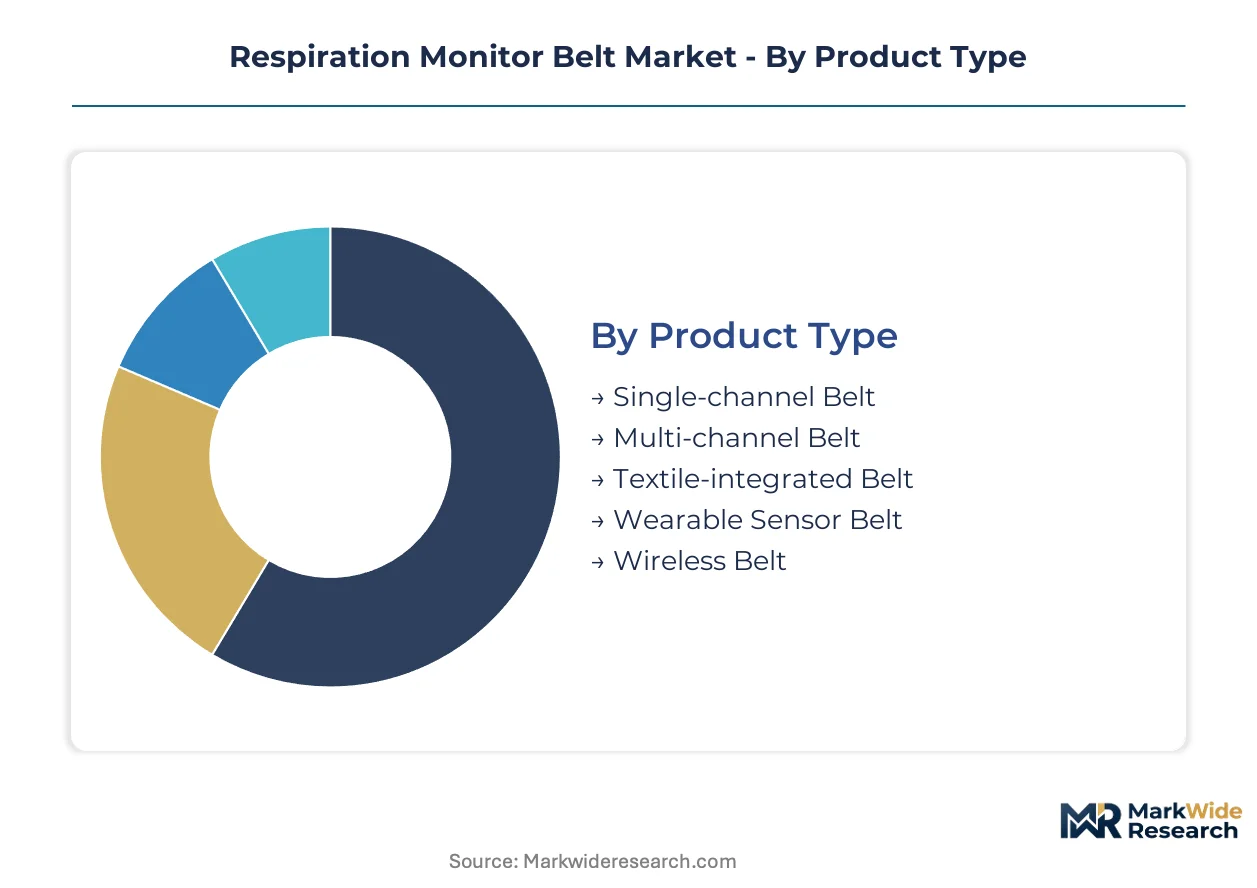
Respiration monitor belt manufacturers configure product portfolios across sensor architectures, clinical settings, and patient populations. Segment-specific regulatory pathways and reimbursement codes determine commercial viability for each configuration.
Product Type:
Cost tier stratification separates disposable single-use configurations from capital-intensive multi-parameter systems.
- Wireless Belt:Bluetooth Low Energy and proprietary RF protocols stream respiratory waveforms to cloud analytics platforms. Sleep clinics in Germany prioritize these configurations for overnight polysomnography studies under EU MDR certification requirements.
- Textile-integrated Belt:Conductive yarns embed respiratory inductance plethysmography coils directly into elastic garment structures. METI promotional programs in Japan are accelerating deployment in community-based elder care settings where patient comfort during extended monitoring is paramount.
- Single-channel Belt:Thoracic or abdominal strain measurement for basic respiratory rate monitoring in occupational health screenings.
- Multi-channel Belt:Simultaneous thoracoabdominal displacement quantification for precise tidal volume estimation in pulmonary rehabilitation.
- Wearable Sensor Belt:Consumer-grade form factors with limited clinical validation for athletic performance tracking applications.
Wireless configurations hold installed capacity. Textile-integrated designs are rotating up the share rankings.
Technology:
Application environment dictates sensor selection — neonatal units demand non-contact methods while sports laboratories prioritize mechanical robustness.
- Respiratory Inductance Plethysmography:Oscillating electrical currents in conductive coils transduce cross-sectional area changes of the rib cage and abdomen. Neonatal intensive care units specify these systems to eliminate skin contact pressure in premature infant monitoring.
- Acoustic Sensors:Piezoelectric microphones detect tracheal breath sounds through clothing layers. FDA 510(k) clearance timelines extend for these non-contact architectures due to novel predicate device requirements.
- Piezoelectric:Ceramic film elements generate voltage proportional to mechanical deformation in high-volume disposable belts.
- Capacitance-based:Electrode proximity sensing enables garment-integrated designs with washability for home-based chronic disease management.
- Strain Gauge:Metallic foil resistance changes quantify belt tension variation in sports science laboratories conducting respiratory muscle training protocols.
Respiratory inductance plethysmography dominates high-acuity installations. Acoustic sensors are climbing the fastest in neonatal applications.
Application:
Customer workflow integration determines whether belts serve diagnostic, therapeutic, or wellness endpoints.
- Sleep Apnea Diagnosis:Overnight respiratory effort monitoring combined with oxygen saturation and airflow measurement. EU MDR Article 10 technical documentation mandates clinical performance validation for Class IIa wearable devices in European sleep clinic procurement channels.
- Athletic Performance Tracking:Ventilatory threshold detection during graded exercise testing. Sports science institutes in Australia specify thoracic strain gauge configurations for respiratory muscle training protocols.
- Pulmonary Rehabilitation:Ambulatory monitoring of breathing pattern efficiency during exercise prescription in pulmonary care centers.
- Infant Respiratory Monitoring:Apnea and bradycardia surveillance in neonatal units where contactless methods minimize skin integrity compromise.
- Stress Assessment:Respiratory rate variability analysis for occupational health services evaluating autonomic nervous system function.
Sleep apnea diagnosis holds installed capacity. Athletic performance tracking is rotating up the share rankings.
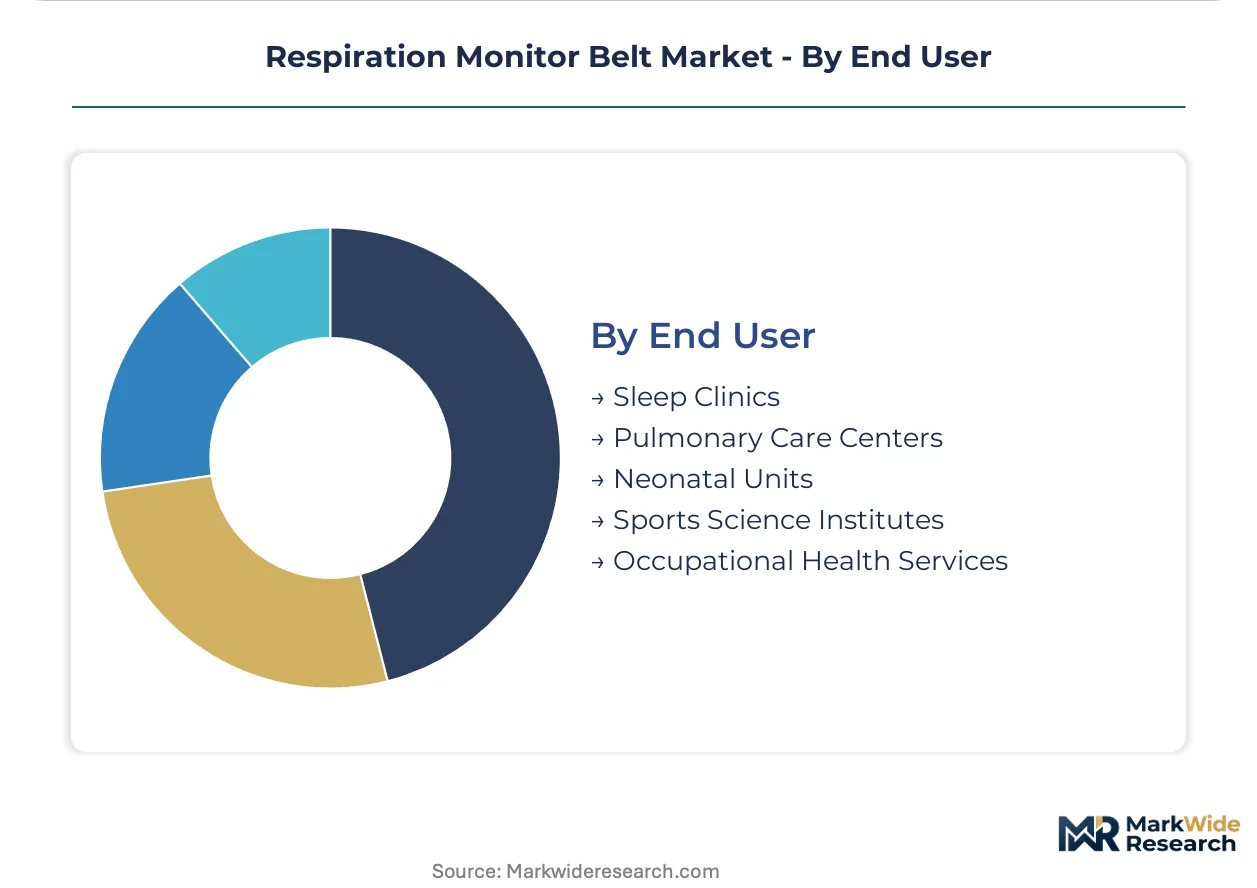
End User:
Procurement authority and reimbursement access separate institutional purchasers from direct-to-consumer channels.
- Sleep Clinics:Tertiary care polysomnography suites and community diagnostic facilities. Group purchasing organizations in the United States consolidate vendor lists around wireless platforms with open API architectures for multi-site standardization.
- Neonatal Units:Intensive care nurseries and step-down facilities. PMDA electrical safety and biocompatibility testing in Japan extends product development timelines for wearable medical device entrants targeting this segment.
- Pulmonary Care Centers:Outpatient clinics managing chronic obstructive pulmonary disease and interstitial lung disease.
- Sports Science Institutes:University laboratories and professional team facilities conducting respiratory physiology research.
- Occupational Health Services:Corporate wellness programs and military fitness assessment centers.
Sleep clinics hold installed capacity. Neonatal units are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sleep clinics extract pricing premiums through EU MDR-certified procurement channels, while Indian distributors compete on hardware margins under PLI scheme manufacturing incentives.
United States
Sleep center consolidation across integrated delivery networks drives standardization demand for wireless respiratory monitoring platforms. FDA 510(k) clearance timelines extend development cycles for novel sensor architectures. The Cleveland Clinic and Mayo Clinic networks anchor multi-site procurement contracts for polysomnography equipment.
Germany
Notified Body supervision under EU MDR Article 10 mandates clinical performance validation for Class IIa wearable devices in tertiary care sleep clinics. TÜV SÜD and DEKRA certification requirements reshape quality management systems for prolonged skin contact materials. The Munich-Berlin corridor concentrates diagnostic equipment distribution networks serving Central European sleep medicine centers.
Japan
METI promotional programs for home-monitoring technologies accelerate deployment in community-based elder care infrastructure. PMDA electrical safety and biocompatibility testing extends product development timelines by 8-14 months for wearable medical device entrants. Osaka-Kobe manufacturing clusters specialize in piezoelectric film production for textile-integrated belt configurations.
India
PLI scheme incentives for medical devices create localized production hubs for export-oriented respiratory monitoring equipment. CDSCO regulatory harmonization with IMDRF standards streamlines market entry pathways for multinational manufacturers. Gujarat and Karnataka industrial corridors attract contract manufacturing investments from global diagnostic equipment brands.
Australia
Sports science institutes specify thoracic strain gauge configurations for respiratory muscle training protocols in athletic performance facilities. TGA conformity assessment procedures align with EU MDR technical documentation requirements for wearable medical devices. Melbourne and Sydney university laboratories anchor research partnerships for ventilatory threshold detection technologies.
Respiration Monitor Belt Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying electromechanical transducers and conductive yarn substrates. Market structure consolidates around vertically integrated medical device conglomerates with hospital procurement channel access, while mid-cap textile-technology firms fragment the garment-integrated segment. Three archetypes dominate: diversified diagnostic equipment manufacturers, sleep-disorder specialists, and sports-science instrumentation providers. Competitive moves center on backward integration into sensor manufacturing and cloud-native analytics platform development.
Within the diversified diagnostic tier, Medtronic and Koninklijke Philips occupy positions representing integrated supply chain control and wireless biosignal processing R&D intensity respectively. ResMed exemplifies the sleep-disorder specialist archetype, anchoring home-based respiratory diagnostics through defensible niche positioning. These three entities collectively represent the pricing-power concentration visible across hospital procurement channels and sleep clinic vendor consolidation patterns.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips |
| Siemens Healthineers |
| GE HealthCare |
| Nihon Kohden |
| OMRON Healthcare |
| ResMed |
| Smiths Medical |
| Vernier |
| Others |
Pricing and Supply Chain Analysis
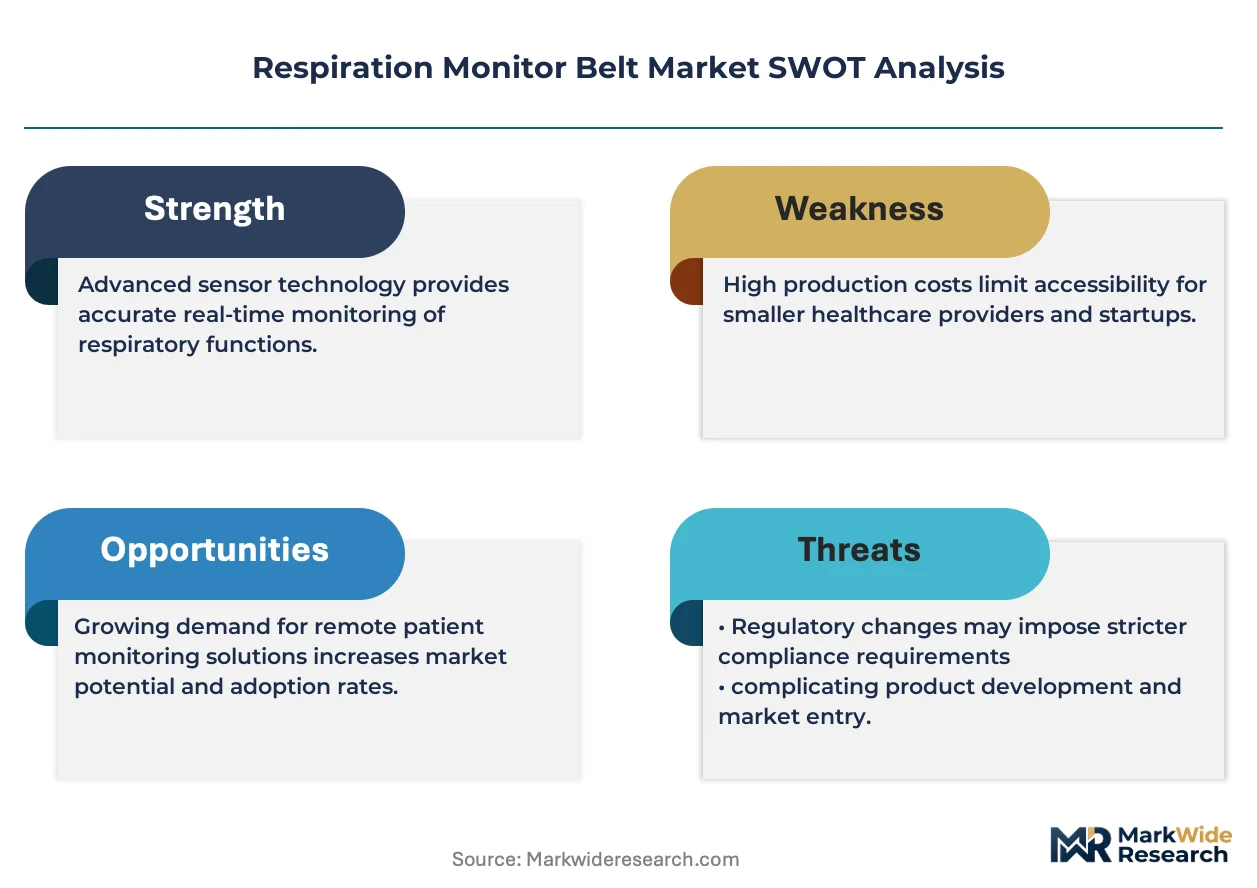
Single-source dependency on Asian specialty polymer manufacturers for piezoelectric film substrates exposes downstream belt producers to simultaneous input cost volatility and allocation rationing, compressing hardware margins while forcing tiered pricing stratification across clinical-grade certified and uncertified configurations.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers based on FDA 510(k) clearance status and wireless platform integration depth. Price differentiation hinges on EU MDR Notified Body certification tier and volume scale through group purchasing organization contracts. Pricing pressure stems from optical respiratory monitoring substitution in low-acuity settings. Sleep clinics in integrated delivery networks exhibit lowest price sensitivity; occupational health services face acute margin compression.
Supply Chain Analysis
Extended payment terms from Japanese textile-integrated belt manufacturers to conductive yarn suppliers signal working capital strain across upstream tiers. Manufacturing concentrates in Japan, Germany, and India under PLI scheme incentives. Critical inputs encompass piezoelectric ceramic films, respiratory inductance plethysmography coils, and silver-coated conductive fibers. Single-source vulnerability pervades Asian polymer substrate sourcing. Distribution runs through hospital procurement channels, GPO vendor lists, and direct-to-sleep-clinic sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of validated wireless biosignal processing engineers constrains platform development velocity, privileging incumbents with captive R&D benches while elevating acquisition premiums for mid-cap textile-technology firms possessing garment-integrated sensor architectures.
For Market Incumbents: Pre-empt optical respiratory monitoring substitution by embedding AI-driven artifact rejection algorithms into cloud-native analytics platforms. Capture backward integration into piezoelectric film production to neutralize Asian supply concentration. Fortify EU MDR Article 10 technical documentation capabilities before Notified Body audit intensity escalates. For New Entrants and Emerging Players: Build out sports science laboratory channels in Australia and the United Kingdom where thoracic strain gauge demand outpaces established vendor coverage. Exploit India's PLI scheme manufacturing incentives for export-oriented production hub establishment. Pursue direct-to-sports-institute sales models bypassing hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: EU MDR Article 10 enforcement reshapes the acquisition landscape toward targets with pre-validated Class IIa quality management systems. Long-term viability centers on software-hardware hybrid revenue models with recurring analytics subscriptions. Monitor FDA 510(k) predicate device pathway narrowing as inflection signal for regulatory-compliant asset scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Notified Body pre-submission meetings with TÜV SÜD accelerate EU MDR Article 10 compliance timelines. |
| Hospital System Partnership | Multi-site sleep center standardization contracts with Cleveland Clinic-type networks lock out competing vendors. |
| Software Companion Development | AI-driven sleep scoring algorithms bundled with belt hardware generate recurring SaaS revenue streams. |
| Backward Integration into Sensors | In-house piezoelectric film production neutralizes Asian supply concentration and input cost volatility. |
| Reimbursement Strategy | CPT code alignment with remote patient monitoring coverage policies unlocks Medicare billing pathways. |
Research Methodology
Operator-level perspectives from sleep clinic biomedical engineers, hospital GPO contracts managers, textile-integrated sensor R&D directors, and neonatal intensive care unit clinicians anchored the qualitative base. Secondary validation drew from FDA 510(k) clearance databases, EU MDR Notified Body technical documentation filings, METI home-monitoring program announcements, and CMS remote patient monitoring reimbursement bulletins. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Scenario-bracketing around PMDA electrical safety validation timeline extensions and EU MDR audit intensity variations framed the projection horizon across the analysis window. Segmentation dimensions encompassed sensor architecture, product type tier, clinical application setting, and end-user procurement authority. CAGRs derived from logistic adoption curve fitting to historical wireless medical device penetration patterns. Forecast inputs incorporated METI promotional program budget trajectories and CDSCO regulatory harmonization progress.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified diagnostic conglomerates or sudden PMDA guidance shifts would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.