
 Remote Patient Monitoring Software Market | 2026-2036
Remote Patient Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Patient Monitoring Software Market Insights
Hospital systems is pivoting toward outpatient chronic care models, expanding procurement of remote patient monitoring software for post-discharge patient cohorts. Teladoc Health leverages its virtual care infrastructure to embed monitoring modules within existing clinician workflows. Medtronic anchors its position through device-to-cloud integration, pairing cardiac implants with proprietary analytics platforms. Philips Healthcare competes on enterprise-scale deployments across multi-hospital networks in North America and Western Europe.
Remote patient monitoring software encompasses digital platforms that collect, transmit, and analyze physiologic data from patients outside traditional clinical settings, typically integrating with FDA-cleared devices through Bluetooth, cellular, or Wi-Fi protocols to enable real-time or near-real-time clinical decision support. Its primary purpose is to extend care team visibility into patient status between visits, reducing acute events and enabling early intervention. Wearable Devices and Integrated Solutions command the largest current revenue pools, with Integrated Solutions capturing disproportionate margin as health systems seek unified electronic health record connectivity rather than point solutions. Cloud Computing underpins the fastest-expanding architecture segment, as providers prioritize elastic infrastructure over on-premises deployments that require dedicated IT maintenance.
FDA Software as a Medical Device guidance and HIPAA security rule enforcement shape product development requirements, mandating encryption standards and audit trails that elevate engineering costs for new entrants. The European Medical Device Regulation imposes additional conformity assessment burdens on platforms that process data from Class IIa or higher connected devices. Stakeholders must monitor evolving reimbursement granularity from CMS and comparable national payers, as coding specificity determines whether health systems can recover software subscription costs through patient billing.
Market Dynamics
Medicare reimbursement code expansion for remote physiologic monitoring is restructuring procurement economics for hospital systems, converting software subscriptions from discretionary IT spend into revenue-generating clinical infrastructure.
Growth Catalysts
- CPT 99457-99458 reimbursement codes:CMS payment structures now compensate providers for remote monitoring analysis time, accelerating software adoption across accountable care organizations.
- Bluetooth Low Energy 5.3 protocols:Enhanced power efficiency extends wearable battery life from days to weeks, reducing patient drop-off in chronic disease programs.
- Post-acute care networks:Hospital systems building outpatient chronic care models require integrated monitoring platforms for congestive heart failure and diabetes patient cohorts.
Market Restraints
- HIPAA security rule compliance:Encryption standards and audit trail requirements elevate engineering costs for new entrants by mandating dedicated security infrastructure.
- FDA 510(k) clearance timelines:Software as a Medical Device pathways impose 12-18 month validation periods that compress early-mover advantages for algorithm updates.
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud control elastic compute supply, exposing health systems to vendor lock-in and egress cost volatility.
Strategic Opportunities
- Rural health clinic penetration:Federally qualified health centers in underserved counties lack IT staffing for on-premises deployments, creating demand for fully managed SaaS models.
- AI-driven risk stratification:Machine learning models processing continuous glucose and blood pressure streams enable predictive intervention before acute events.
- Behavioral health integration:Depression and anxiety screening modules embedded in cardiac monitoring platforms address comorbidity gaps in existing siloed systems.
Industry Challenges
- Interoperability certification backlog:HL7 FHIR integration testing with Epic and Cerner EHR systems delays go-live dates by 4-6 months for new market entrants.
- Clinical workflow redesign:Nursing staff require retraining to incorporate monitoring alerts into existing triage protocols without alert fatigue degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Patient Monitoring Software Market |
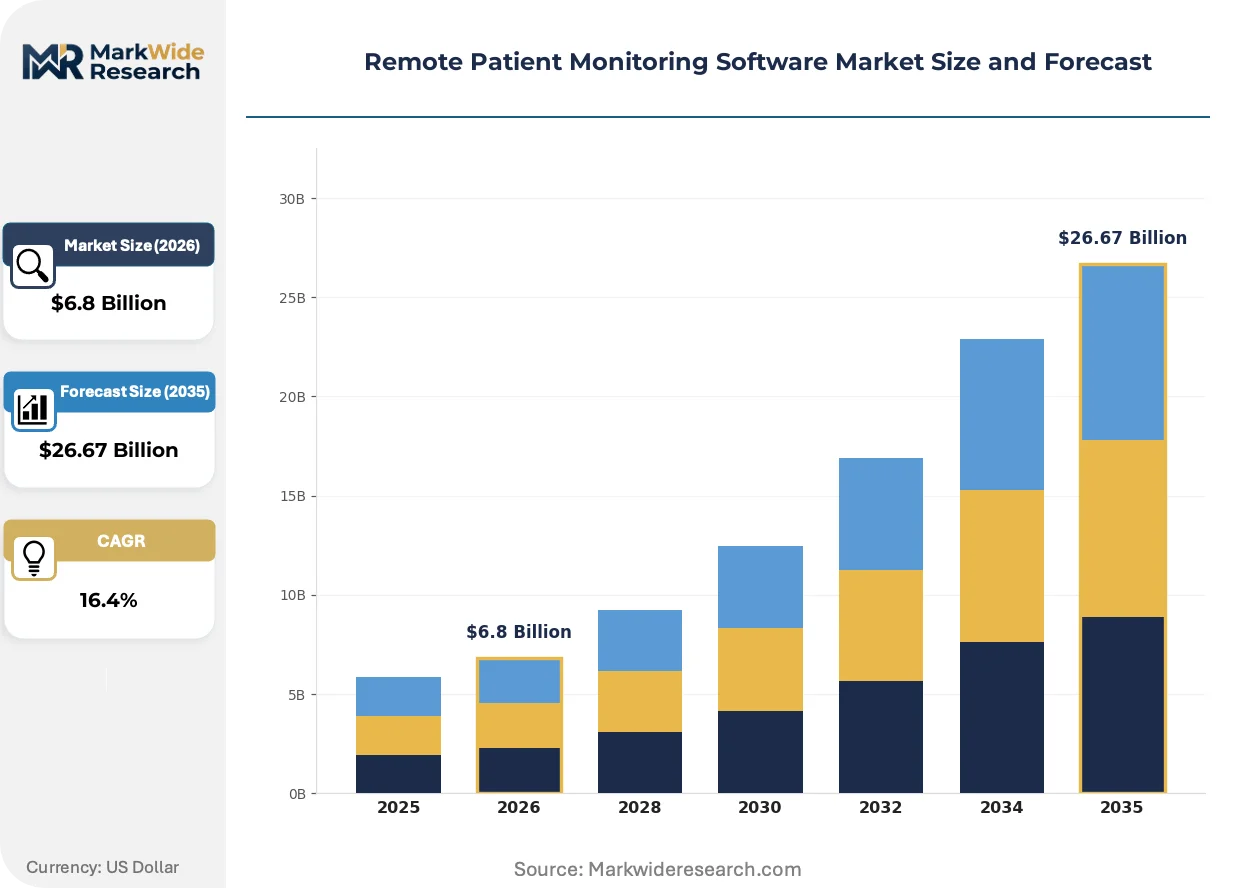
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Web-Based Platforms, Integrated Solutions End User: Healthcare Providers, Patients, Insurance Companies, Caregivers Technology: IoT Solutions, Cloud Computing, Big Data Analytics, Telemedicine Application: Chronic Disease Management, Vital Signs Monitoring, Medication Adherence, Patient Engagement |
| Companies Covered | Teladoc Health, Medtronic, GE Healthcare, Siemens Healthineers, Philips Healthcare, BioIntelliSense, OMRON Healthcare, Capsule Technologies, Nihon Kohden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Patient Monitoring Software Market Trends and Innovations
Remote patient monitoring software is undergoing architectural transformation as cloud-native platforms displace legacy client-server installations and artificial intelligence layers embed directly at the edge.
Continuous glucose monitoring data streams are converging with insulin dosing algorithms in closed-loop systems. Pediatric endocrinology departments at academic medical centers are piloting these integrations ahead of broader endocrinology adoption. The structural compression of manual glucose logging and phone-based coaching is eliminating intermediate data interpretation steps between patient and prescriber.
The European Medical Device Regulation's Class IIa conformity assessment requirements for platforms processing connected device data are elevating quality management system rigor. Software vendors must now maintain technical documentation and post-market surveillance comparable to hardware manufacturers. Cardiology monitoring platforms face the steepest compliance burden given their processing of implantable device telemetry.
Health system purchasing committees now mandate unified EHR connectivity rather than accepting point solutions requiring separate clinician portals. Integrated platforms capturing data from multiple physiologic parameters command preference over single-modality vendors. This consolidation pressure is most visible in Medicare Advantage plan networks seeking to reduce vendor management overhead across distributed provider groups.
Remote Patient Monitoring Software Market Segmentation
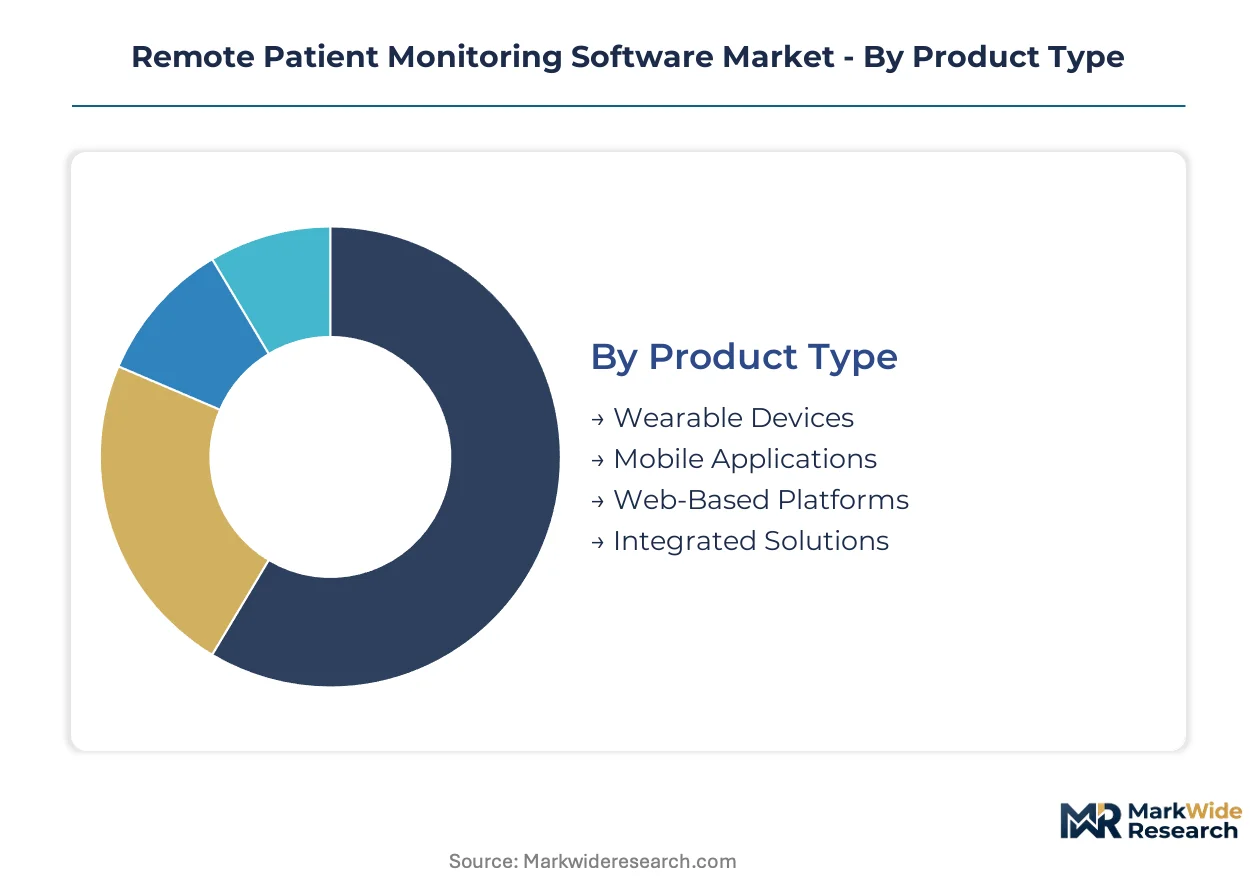
Remote patient monitoring software vendors structure product portfolios around four intersecting dimensions: delivery modality, clinical user, underlying infrastructure, and disease-specific use case. Each axis carries distinct margin profiles and regulatory requirements that shape vendor resource allocation and partnership strategies.
Product Type:
Wearable Devices and Integrated Solutions anchor current procurement volumes, with deployment patterns diverging sharply between standalone pilots and enterprise health system rollouts.
- Wearable Devices:Continuous glucose monitors, pulse oximeters, and cardiac event recorders transmit physiologic data via Bluetooth Low Energy protocols. Hospital systems in the United States deploy these for post-discharge congestive heart failure cohorts where Medicare reimbursement codes offset device costs.
- Integrated Solutions:Unified platforms embedding EHR connectivity, clinical decision support, and billing module integration command premium pricing. Health systems prioritize these over point solutions to reduce nursing staff training burden and alert fatigue.
- Mobile Applications:Patient-facing smartphone apps handle symptom logging, medication reminders, and secure messaging with care teams. These serve as the entry tier for Federally Qualified Health Centers lacking IT infrastructure for heavier deployments.
- Web-Based Platforms:Browser-accessible dashboards enable caregiver and family member visibility into patient status. Demand concentrates in rural counties where broadband limitations complicate native app distribution.
Mature deployment sits with Integrated Solutions. Newer deployment is concentrated in Wearable Devices as sensor costs decline and battery life extends.
End User:
Procurement authority and reimbursement capture determine which stakeholder group drives purchasing decisions across accountable care organizations and Medicare Advantage networks.
- Healthcare Providers:Hospital systems and physician practices acquire monitoring platforms to reduce 30-day readmission penalties and capture remote physiologic monitoring billable hours. Epic and Cerner EHR integration certifications gate vendor eligibility.
- Insurance Companies:Payers deploy monitoring software to identify high-risk members for care management intervention. UnitedHealth and CVS Aetna have built proprietary platforms or acquired vendors to control data flows.
- Patients:Direct-to-consumer subscription models bypass institutional procurement, particularly for fertility tracking and fitness-adjacent cardiac monitoring. These carry higher churn and lower clinical validation standards.
- Caregivers:Family member access portals serve dementia and aging-in-place populations. Adult children in multigenerational households drive adoption where formal home health services are unavailable.
Revenue concentration favors Healthcare Providers. Fastest expansion is occurring in Insurance Companies as risk-bearing entities internalize monitoring capabilities.
Technology:
Infrastructure choices determine scalability, security compliance burden, and integration complexity with existing clinical systems.
- Cloud Computing:Elastic AWS, Azure, and Google Cloud deployments dominate new health system contracts, displacing on-premises installations that require dedicated hospital IT staffing. HIPAA Business Associate Agreements and encryption standards elevate vendor qualification thresholds.
- IoT Solutions:Edge computing architectures process data locally on gateways or wearables before cloud transmission. These reduce latency for critical alerts in cardiac monitoring and enable limited functionality during connectivity outages.
- Big Data Analytics:Machine learning models processing continuous physiologic streams enable predictive risk stratification. Academic medical centers pilot these for sepsis early warning and diabetic ketoacidosis prevention ahead of broader deployment.
- Telemedicine:Synchronous video integration with asynchronous monitoring data creates unified virtual care workflows. Teladoc and Amwell bundle these capabilities to differentiate from standalone monitoring vendors.
Established infrastructure relies on Cloud Computing. Steepest expansion trajectory belongs to Big Data Analytics as FDA 510(k) pathways clarify for Software as a Medical Device algorithms.
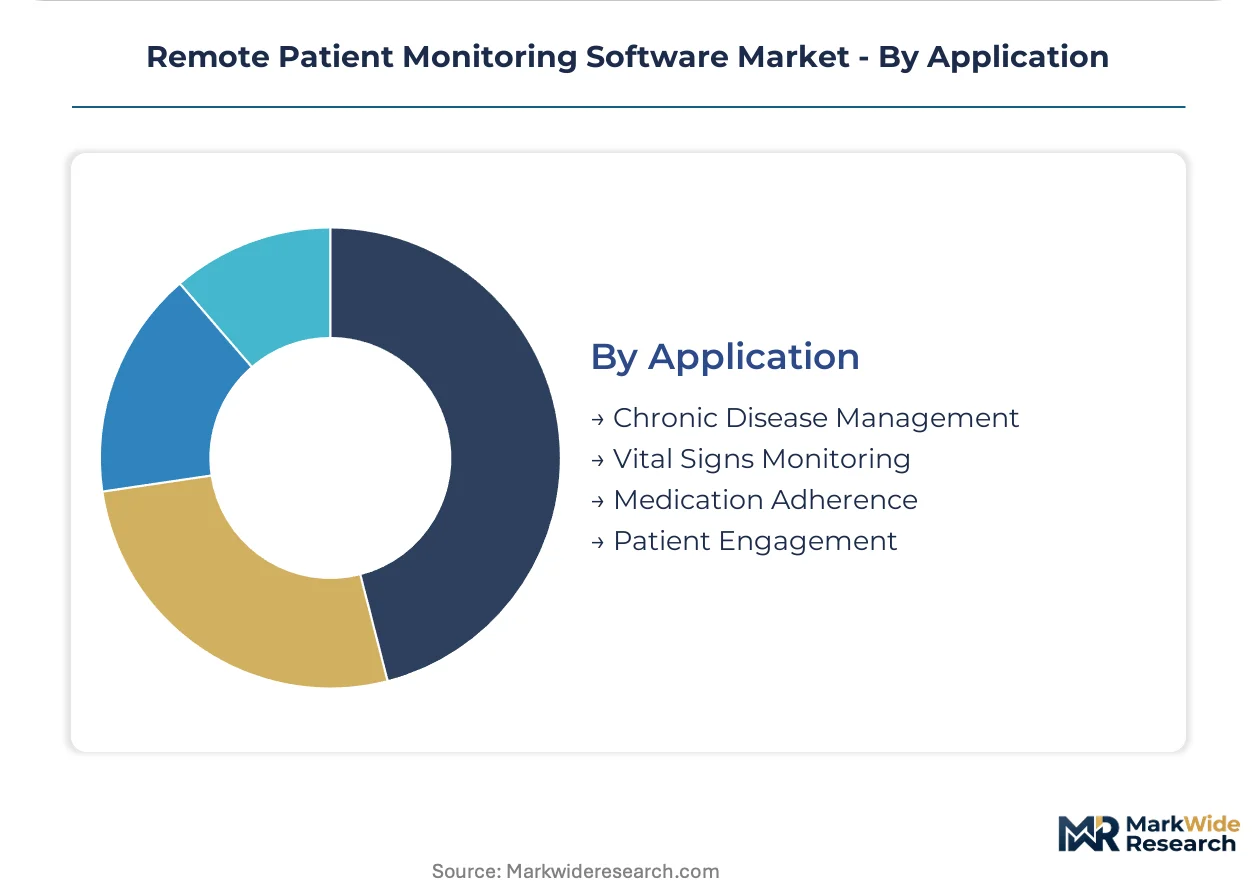
Application:
Clinical use cases vary in data complexity, intervention urgency, and reimbursement specificity, shaping vendor specialization and health system prioritization.
- Chronic Disease Management:Diabetes, hypertension, and heart failure programs generate the largest patient volumes and most mature outcome evidence. CMS reimbursement codes specifically target these conditions, creating direct revenue linkage for provider adoption.
- Vital Signs Monitoring:Continuous temperature, respiratory rate, and blood oxygen tracking expanded during respiratory virus seasons. Hospital-at-home programs now standardize these for early discharge eligibility.
- Medication Adherence:Smart pill bottles and ingestion sensors address polypharmacy in elderly populations. Pharmacy benefit managers embed these in value-based contracts with pharmaceutical manufacturers.
- Patient Engagement:Gamification, education modules, and automated coaching improve self-management behaviors. These serve as retention tools for Medicare Advantage plans competing on Star Ratings.
Programmatic maturity centers on Chronic Disease Management. Emerging deployment is accelerating in Vital Signs Monitoring as hospital-at-home reimbursement frameworks stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones across the United States concentrate health system procurement of remote patient monitoring infrastructure, while comparable special economic zones in Germany and Singapore accelerate vendor development centers. Medicare reimbursement expansion in the US and MDR compliance timelines in Europe are restructuring regional deployment priorities.
United States
Hospital systems in Qualified Opportunity Zones accelerate software procurement to capture CPT 99457-99458 reimbursement for remote physiologic monitoring. FDA 510(k) clearance pathways for Software as a Medical Device mandate encryption standards that elevate vendor qualification thresholds. The Boston-Cambridge cluster anchors development of cardiac monitoring analytics platforms processing implantable device telemetry.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia pilot closed-loop insulin dosing systems integrating continuous glucose monitoring data streams. The European Medical Device Regulation's Class IIa conformity assessment requirements impose quality management system burdens comparable to hardware manufacturers. Berlin-Brandenburg hosts EMA-aligned regulatory consulting firms specializing in post-market surveillance documentation.
United Kingdom
NHS Integrated Care Systems in Greater London and the Midlands contract for unified EHR connectivity to reduce nursing staff training burden across distributed provider groups. MHRA guidance on Software as a Medical Device aligns with MDR implementation timelines, compressing validation periods for algorithm updates. The Cambridge-Oxford corridor concentrates AI-driven risk stratification pilots for sepsis early warning systems.
Japan
PMDA consultation pathways for SaMD algorithms clarify as academic medical centers in Kanto and Kansai regions pilot predictive intervention models for diabetic ketoacidosis prevention. METI subsidies for digital health infrastructure accelerate cloud-native platform adoption displacing legacy client-server installations. The Tokyo-Osaka corridor anchors enterprise-scale deployments across multi-hospital networks seeking elastic compute infrastructure.
India
Federally qualified health centers in Maharashtra and Karnataka procure fully managed SaaS models lacking IT staffing for on-premises deployments. CDSCO medical device rules for software-based products impose quality management requirements that filter new market entrants. The Bangalore-Hyderabad corridor concentrates development centers for Bluetooth Low Energy protocol optimization extending wearable battery life.
Remote Patient Monitoring Software Market Competitive Landscape
Top-tier vendors anchor enterprise health system contracts, while mid-tier specialists occupy niche disease-specific segments and point-solution vendors compete on price-sensitive Federally Qualified Health Center deployments. The market structures around three strategic archetypes: device-to-cloud integrators leveraging proprietary hardware telemetry, virtual care platforms embedding monitoring within synchronous workflows, and pure-play analytics vendors processing multi-parameter physiologic streams. Dominant competitive moves include strategic partnerships with EHR vendors for HL7 FHIR certification and geographic expansion into rural health clinic networks lacking IT infrastructure.
Among US-based health technology conglomerates, Teladoc Health exemplifies the virtual care platform archetype, Medtronic anchors the device-to-cloud integration tier, and Philips Healthcare occupies a position within enterprise-scale deployment specialists. These three represent distinct strategic vectors: Teladoc leverages existing clinician workflow infrastructure, Medtronic pairs cardiac implants with proprietary analytics, and Philips competes on multi-hospital network rollouts across North American and Western European markets.
| Leading Market Players |
|---|
| Teladoc Health |
| Medtronic |
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| BioIntelliSense |
| OMRON Healthcare |
| Capsule Technologies |
| Nihon Kohden |
| Others |
Pricing and Supply Chain Analysis
Cloud-native software engineering talent concentration in Bangalore and Hyderabad feeds labor-cost differentials that widen pricing-tier spreads between premium enterprise deployments and economy SaaS offerings for Federally Qualified Health Centers.
Pricing Analysis
Short lead-time premiums for FDA 510(k) cleared Software as a Medical Device platforms command substantial markups over uncertified alternatives awaiting validation. Three-tier pricing structure across premium, standard, and economy levels segments by EHR integration depth and clinical decision support sophistication. Cost compression in the economy tier intensifies because AWS egress fees and HIPAA Business Associate Agreement overhead compress margins for new entrants. Federally Qualified Health Centers exhibit highest price sensitivity, while integrated delivery networks negotiating enterprise contracts prioritize interoperability certification over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for Bluetooth Low Energy chipsets mandate multi-supplier qualification across Nordic Semiconductor, Texas Instruments, and Silicon Labs to mitigate single-source vulnerability. Hardware supply concentrates in Taiwan for sensor fabrication, China for printed circuit board assembly, and Malaysia for final device integration. Cloud infrastructure draws from AWS, Azure, and Google Cloud data centers, creating hyperscaler concentration risk. Tariff exposure on Chinese-manufactured wearables elevates landed costs for device-dependent platforms. Distribution runs through medical device distributors, direct health system contracts, and pharmacy benefit manager channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
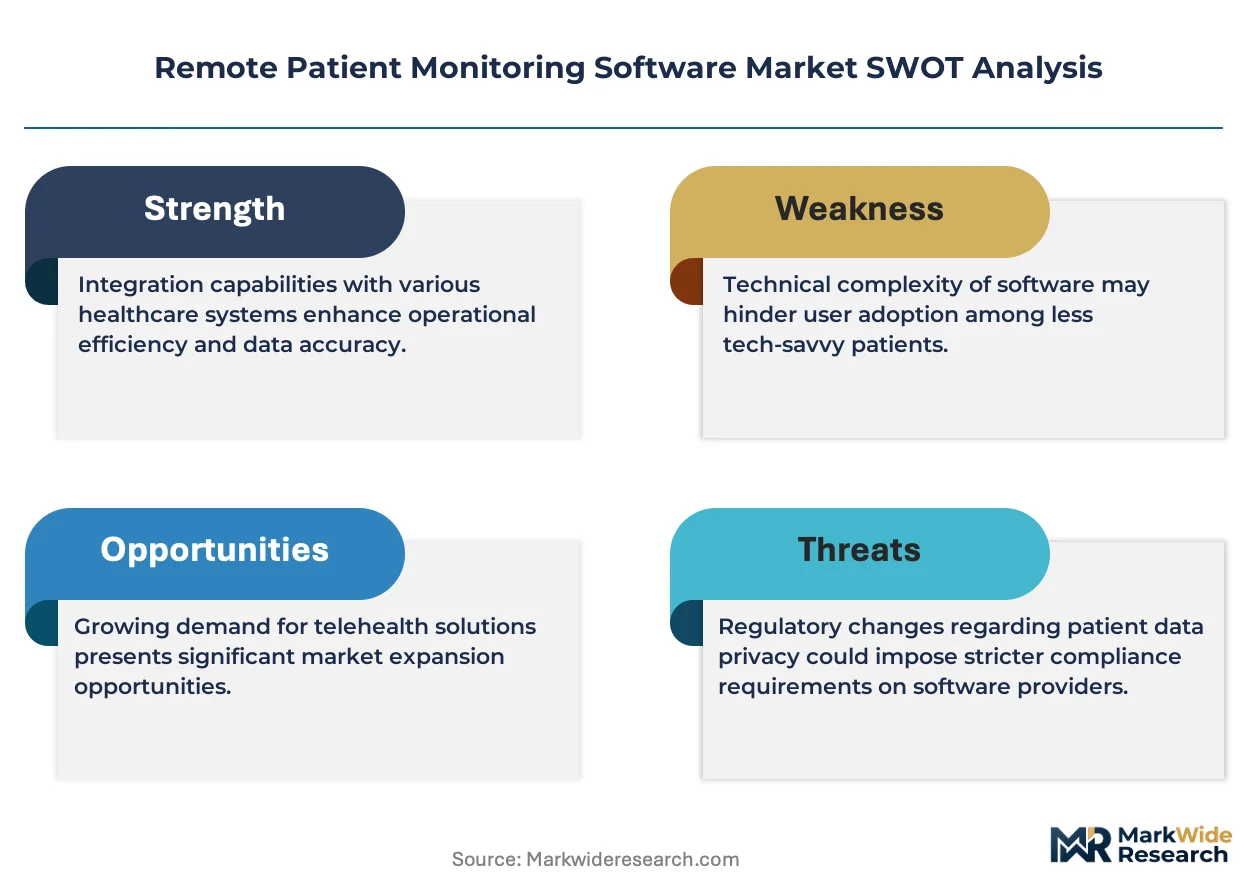
This market reads as a cost-of-compliance story where FDA Software as a Medical Device guidance and HIPAA security rule enforcement erect barrier-to-entry moats favoring incumbent vendors with established quality management systems.
For Market Incumbents: Extend EHR connectivity certification breadth across Epic and Cerner installations to defend against pure-play analytics vendors threatening workflow integration. Deepen backward integration into Bluetooth Low Energy protocol optimization to capture battery-life extension value. Prioritize HL7 FHIR integration investment as the priority lever against interoperability backlog delays compressing new entrant go-live timelines. For New Entrants and Emerging Players: Direct-to-clinician digital channels bypass health system purchasing committee gatekeepers for behavioral health integration modules addressing comorbidity gaps. Rural health clinic networks in Qualified Opportunity Zones represent the most penetrable segment given IT staffing constraints favoring fully managed SaaS models. Target Federally Qualified Health Centers with mobile application entry tiers requiring minimal infrastructure commitment. For Investors and Strategic Acquirers: Re-rating potential sits with AI-driven risk stratification vendors given FDA 510(k) pathway clarification for predictive algorithms processing continuous physiologic streams. Long-term viability favors platforms with established hospital system partnerships and recurring subscription revenue anchored to Medicare reimbursement code stability. Watch CMS coding granularity expansion as the inflection signal determining whether software subscription costs recover through patient billing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Software as a Medical Device validation compresses early-mover advantages for algorithm updates. |
| Hospital System Partnership | Epic and Cerner EHR integration certifications gate vendor eligibility for enterprise contracts. |
| Geographic Expansion | Rural health clinic networks lacking IT infrastructure create demand for fully managed SaaS models. |
| Platform Integration | Unified EHR connectivity reduces nursing staff training burden and alert fatigue degradation. |
| Reimbursement Strategy | CPT 99457-99458 coding specificity determines cost recovery through remote physiologic monitoring billing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at Software as a Medical Device vendors. FDA 510(k) databases, CMS Medicare reimbursement code documentation, hospital procurement databases, and hyperscaler capex disclosures provided validation layers. Bottom-up patient volume modeling and top-down health system IT spending estimates were triangulated to cross-check segment allocations.
Granularity-level modeling deployed patient cohort projections at the disease-condition level, technology infrastructure at the deployment-architecture level, and end-user segmentation at the procurement-authority level across the analysis window. CAGRs were derived from fitted growth curves calibrated to Medicare reimbursement expansion trajectories and FDA clearance pipeline velocity. Forecast inputs incorporated Bluetooth Low Energy protocol adoption curves and cloud infrastructure elasticity pricing trends.
Inputs from FDA pre-submission meeting records and CMS coding guidance were available through the study window; gaps in real-time health system purchasing committee deliberations introduce uncertainty bands around enterprise contract timing assumptions. Forecasts reflect documented assumptions regarding reimbursement code stability and regulatory pathway duration. A model refresh is warranted upon material change in CMS remote physiologic monitoring reimbursement granularity or FDA SaMD algorithm validation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market