
 Asia-Pacific Hemodynamic Monitoring Market | 2026-2036
Asia-Pacific Hemodynamic Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hemodynamic Monitoring Market Outlook
Hospital procurement concentration is hardening across Asia-Pacific tertiary care networks as public health systems consolidate vendor contracts for hemodynamic platforms. Edwards Lifesciences Corporation anchors its position through specialized catheter-based monitoring technologies. Medtronic leverages integrated digital health infrastructure to sustain competitive relevance. Abbott Laboratories differentiates via compact, point-of-care hemodynamic diagnostics designed for high-acuity settings.
Hemodynamic monitoring encompasses the real-time measurement of blood flow, pressure, and oxygen delivery parameters through invasive arterial lines, pulmonary artery catheters, or non-invasive bioimpedance and ultrasound methods, typically operating with pressure transducer accuracy within ±2 mmHg and sampling frequencies exceeding 250 Hz to guide circulatory management in perioperative and critical care environments. Non-invasive monitors occupy expanding share in cost-sensitive Asian markets where catheter-related complication avoidance drives purchasing criteria, while invasive monitors retain margin concentration in cardiac surgery suites across Japan and Australia. Continuous monitoring systems represent the fastest-growing product configuration as health systems prioritize uninterrupted data streams for sepsis and shock protocols.
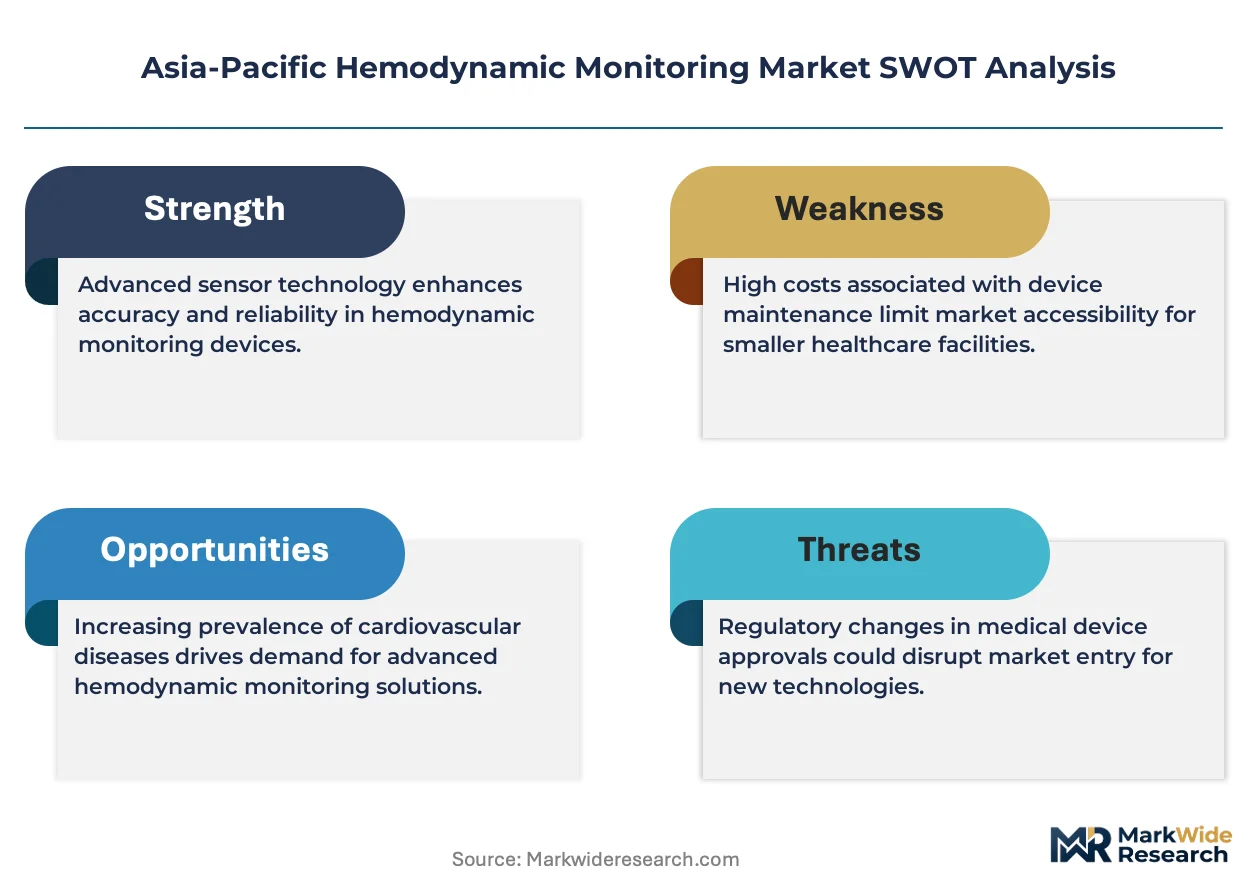
Japan's PMDA enforces rigorous clinical evidence requirements for hemodynamic device approvals, while China's NMPA streamlines innovation pathways under revised Class III medical device regulations and Australia's TGA mandates post-market surveillance for implantable pressure sensors. These frameworks elevate compliance costs for entrants but reinforce quality thresholds that benefit established manufacturers with dedicated regulatory affairs teams. Stakeholders must weigh reimbursement evolution against capital expenditure cycles as public hospital budgets across Southeast Asia recalibrate post-pandemic.
Market Dynamics
Hospital procurement consolidation across China, India, and Japan is compressing vendor margins while elevating technical compliance requirements for hemodynamic platform suppliers.
Growth Catalysts
- China's NMPA Class III pathway streamlining:Accelerated registration timelines for innovative hemodynamic devices reduce time-to-market for manufacturers with robust clinical dossiers.
- Sepsis protocol standardization:Tertiary care networks in India mandate continuous hemodynamic surveillance in ICUs, institutionalizing catheter and non-invasive monitor deployment.
- Pulmonary artery catheter miniaturization:Advances in microsensor fabrication enable safer insertion profiles, expanding addressable patient populations beyond cardiac surgery suites.
Market Restraints
- Pressure transducer supply concentration:Japanese and German component suppliers dominate high-precision sensor manufacturing, exposing assemblers to input bottlenecks.
- Japan PMDA clinical evidence thresholds:Extensive domestic trial requirements for Class IV devices delay product launches by 18-24 months versus comparable NMPA timelines.
- Non-invasive bioimpedance substitution:Cost-sensitive hospitals in Southeast Asia increasingly favor ultrasound-based cardiac output monitoring over invasive catheter systems.
Strategic Opportunities
- Indonesia's hospital modernization program:Public sector capital allocation for critical care infrastructure creates first-mover advantages for integrated monitoring platform vendors.
- AI-enabled predictive analytics convergence:Machine learning algorithms layered atop continuous hemodynamic streams enable early shock detection, commanding premium pricing.
- Vietnam's private hospital expansion:Ho Chi Minh City and Hanoi medical corridors attract foreign direct investment, opening distribution partnerships for mid-tier device manufacturers.
Industry Challenges
- Perfusionist and critical care technician scarcity:Specialized training programs in the Philippines and Thailand fail to match ICU bed expansion rates, constraining effective device utilization.
- Legacy EMR integration complexity:Proprietary data protocols from established IT vendors block seamless hemodynamic data flow into hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hemodynamic Monitoring Market |
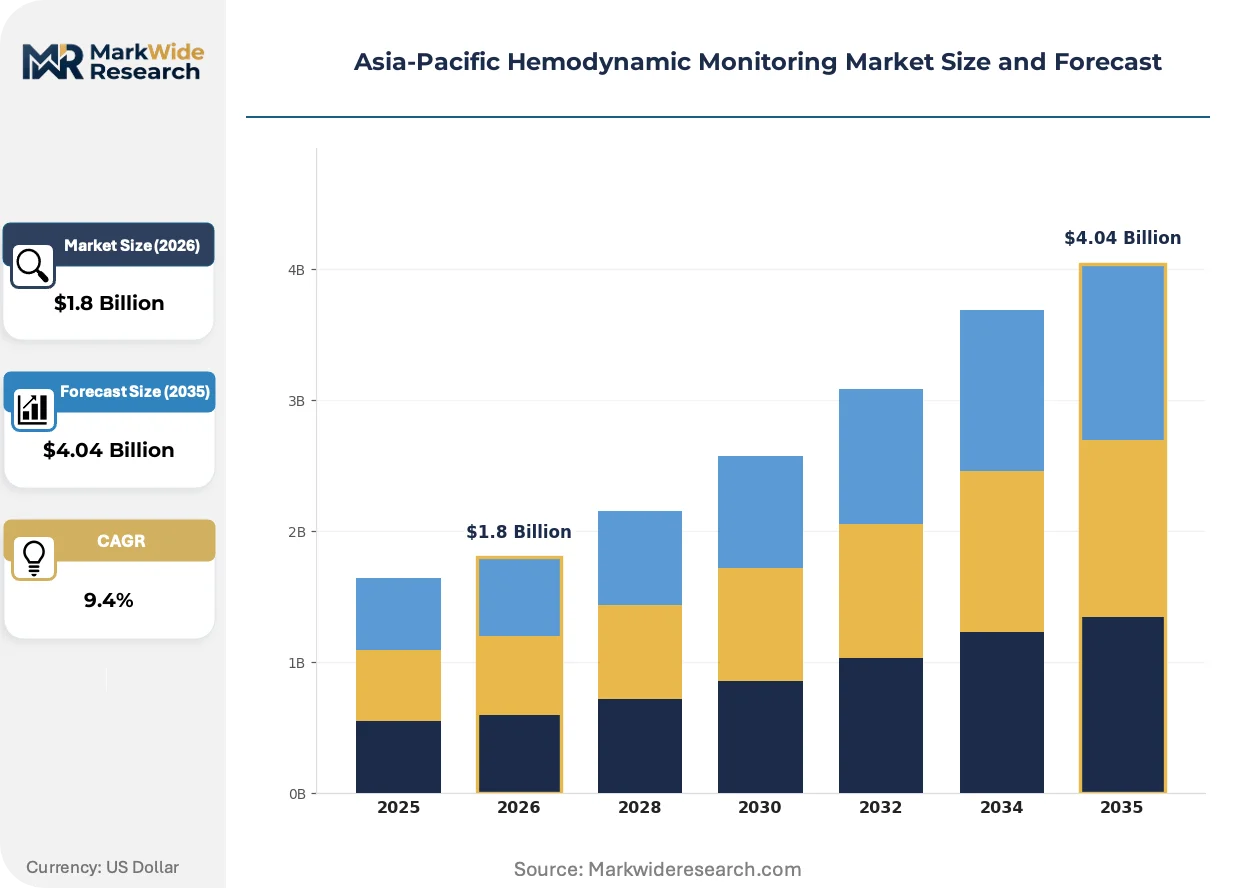
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Monitors, Non-invasive Monitors, Continuous Monitoring Systems, Portable Monitors End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Technology: Ultrasound, Pressure Sensors, Fiber-optic Systems, Electrical Impedance Application: Cardiac Surgery, Critical Care, Trauma Care, Anesthesia Monitoring |
| Companies Covered | ICU Medical, Medtronic, Edwards Lifesciences Corporation, Abbott Laboratories, Baxter International, GE Healthcare, Koninklijke Philips NV, Siemens Healthineers, Getinge AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hemodynamic Monitoring Market Strategic Shifts
Digital health infrastructure investment is reconfiguring how hemodynamic data is captured, transmitted, and monetized across Asia-Pacific acute care settings.
Non-invasive cardiac output monitoring is overtaking pulmonary artery catheterization in cost-constrained environments. Bioimpedance and ultrasonic Doppler systems now deliver stroke volume variation accuracy within 10% of invasive reference methods. Tier-two Chinese hospitals and Indian district medical centers adopt these platforms aggressively, compressing addressable revenue per bed while expanding total install bases.
Australia's TGA post-market surveillance mandate for implantable pressure sensors is tightening adverse event reporting obligations. Manufacturers must maintain real-world performance registries, elevating compliance overhead. Cardiac surgery suites in Sydney and Melbourne medical centers now prioritize suppliers with established pharmacovigilance infrastructure over pure technology differentiation.
Public hospital procurement in Southeast Asia is fragmenting into modular contracting. Equipment vendors face unbundled tenders separating hardware, disposable catheters, and software subscriptions. Malaysian and Thai health authorities pilot outcome-linked payment structures where monitor performance guarantees influence contract awards, rewarding suppliers with predictive maintenance capabilities and local technical support density.
Asia-Pacific Hemodynamic Monitoring Market Segmentation
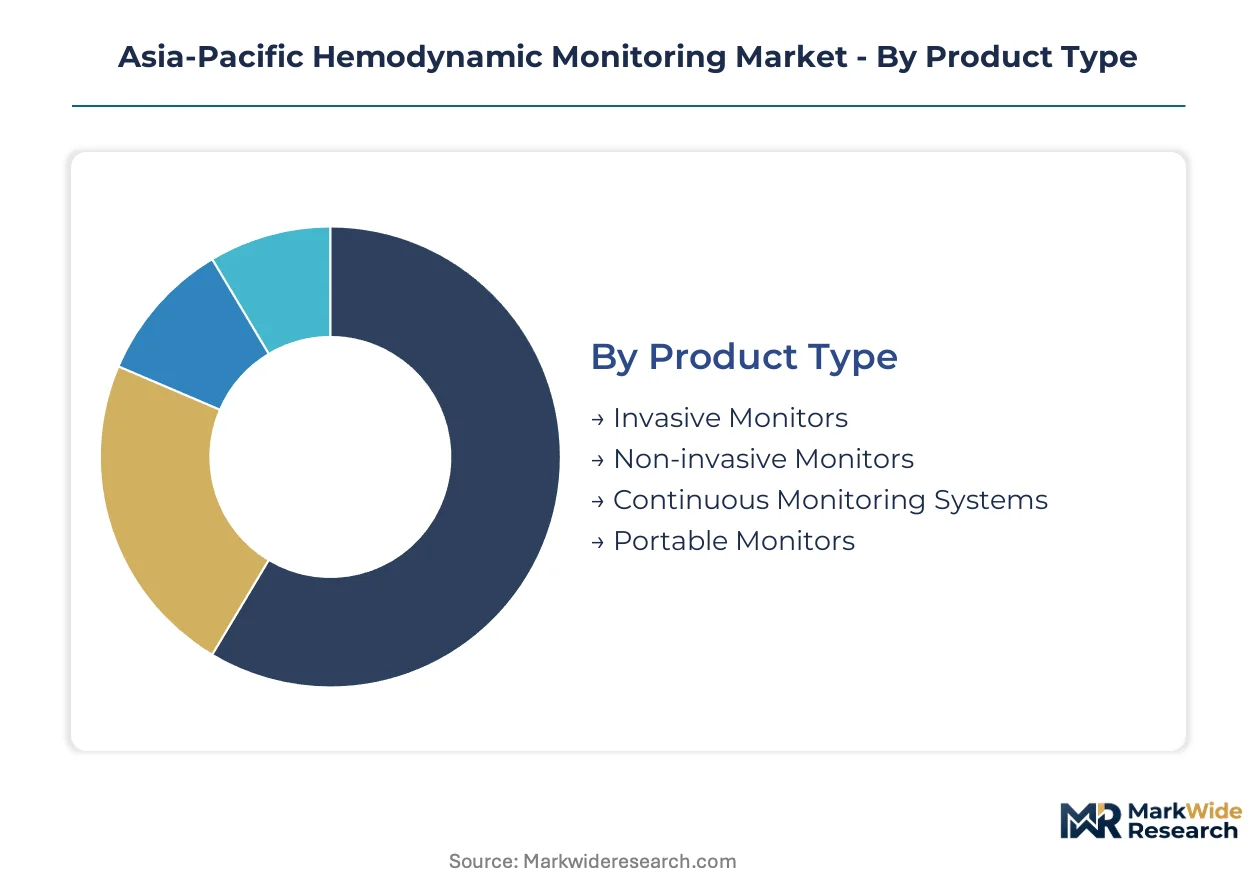
Segmentation of the Asia-Pacific hemodynamic monitoring market reveals distinct technology-performance tiers that align with varying clinical acuity levels and capital expenditure capacities across tertiary networks. Product architecture, end-user infrastructure, and sensing modality each create discrete competitive battlegrounds with divergent margin profiles.
Product Type:
Technology sophistication and catheter invasiveness define the product architecture axis, with sensor miniaturization and wireless data transmission capabilities separating premium platforms from standard configurations.
- Continuous Monitoring Systems:These platforms integrate multi-parameter sensing with automated alarm protocols and EMR connectivity, sampling hemodynamic variables at frequencies exceeding 250 Hz. China's tier-one cities and India's metropolitan hospital clusters concentrate procurement as sepsis protocols mandate uninterrupted circulatory surveillance.
- Invasive Monitors:Pulmonary artery catheters and arterial line systems deliver gold-standard pressure transduction accuracy within ±2 mmHg through intravascular sensor placement. Japan's cardiac surgery suites and Australia's tertiary centers sustain demand despite complication risks, valuing precision over cost minimization.
- Non-invasive Monitors:Bioimpedance and ultrasonic Doppler systems enable stroke volume assessment without vascular access, appealing to Southeast Asian district hospitals prioritizing catheter-related infection avoidance.
- Portable Monitors:Battery-powered compact units facilitate inter-hospital transfer and emergency department triage across Vietnam's expanding private hospital corridor.
Leading the category by volume: Invasive Monitors. Growing fastest: Continuous Monitoring Systems.
End User:
Capital intensity and clinical workflow integration requirements segment demand across facility types, with procurement authority residing in centralized health system purchasing departments or fragmented private operator networks.
- Hospitals:Tertiary care networks in China, India, and Japan consolidate vendor contracts for platform standardization, leveraging volume commitments to compress unit pricing while demanding predictive maintenance service bundling.
- Home Care:Remote monitoring adoption accelerates in Australia's urban periphery and Japan's aging rural prefectures, though reimbursement pathways remain unsettled across most Asia-Pacific jurisdictions.
- Ambulatory Surgical Centers:Same-day procedure volumes in Thailand's medical tourism hubs and Malaysia's urban corridors drive demand for rapid-setup non-invasive platforms.
- Clinics:Primary care facilities in Indonesia's hospital modernization program and Philippine provincial networks represent latent demand pending infrastructure investment cycles.
Hospitals command the dominant revenue share. Home Care exhibits the steepest expansion trajectory as post-acute surveillance protocols proliferate.
Technology:
Sensing modality selection hinges on accuracy requirements, operator training availability, and consumable cost structures that vary dramatically across invasive and non-invasive approaches.
- Pressure Sensors:MEMS-based transducers and fiber-optic pressure elements enable direct intravascular measurement with thermal drift compensation, dominating cardiac surgery suites where precision justifies catheterization risks.
- Ultrasound:Transthoracic and transesophageal Doppler systems calculate cardiac output from blood velocity profiles, gaining traction in China's tier-two hospitals where specialist shortages limit invasive procedure volumes.
- Electrical Impedance:Thoracic bioimpedance monitors estimate stroke volume from voltage fluctuations across chest electrodes, offering lowest capital entry point for Indian district medical centers.
- Fiber-optic Systems:Photonic pressure sensing eliminates electrical interference in MRI suites and high-electromagnetic environments, commanding niche premiums in Japan's advanced imaging centers.
Pressure Sensors anchor installed base volumes. Ultrasound is climbing the fastest as image-guidance familiarity spreads among critical care trainees.
Application:
Clinical indication severity and reimbursement weighting determine technology selection, with perioperative monitoring commanding premium pricing relative to emergency department screening applications.
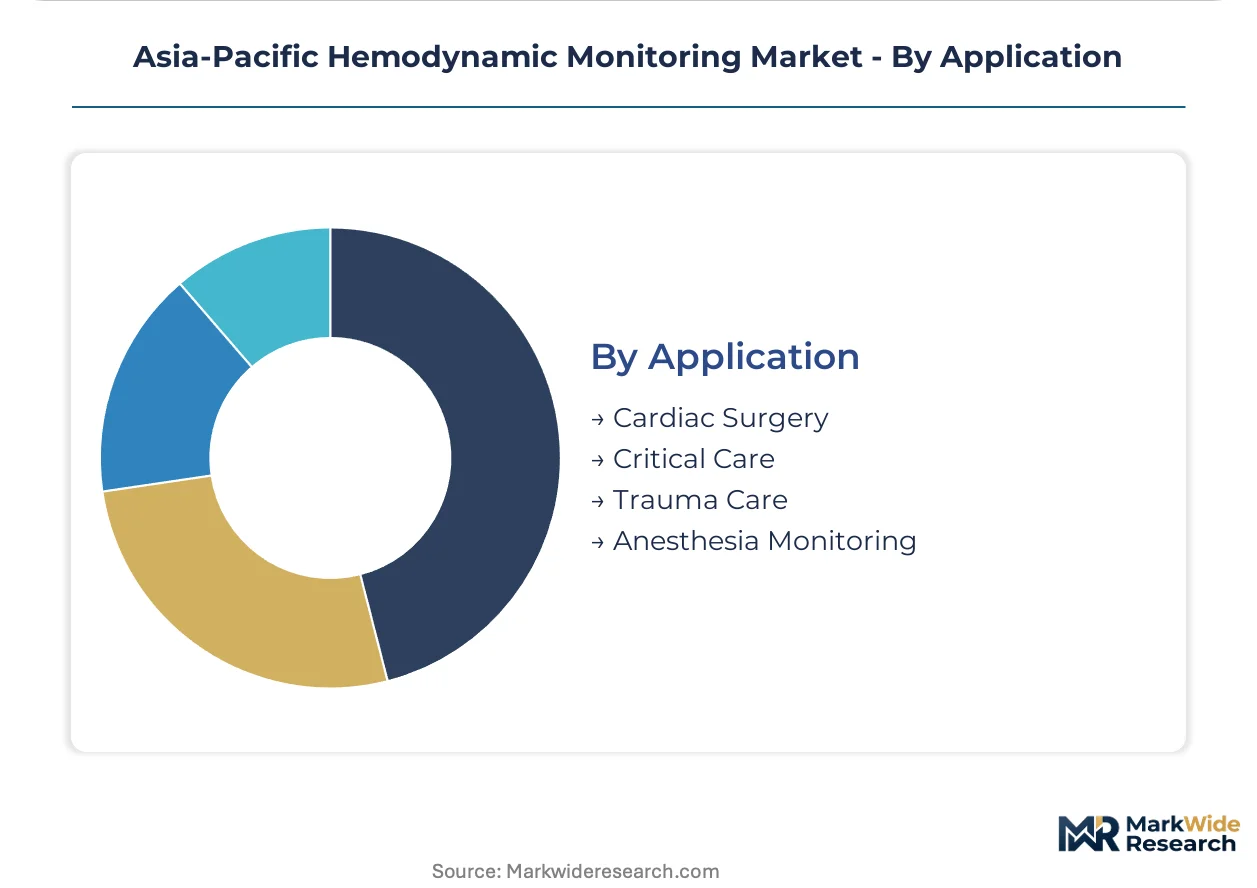
- Critical Care:ICU-based shock management protocols in India's tertiary networks and China's provincial hospitals institutionalize continuous invasive monitoring, with sepsis bundles mandating hemodynamic optimization targets.
- Cardiac Surgery:Cardiopulmonary bypass and valve replacement procedures in Japan's university hospitals and Australia's metropolitan centers require pulmonary artery catheterization for comprehensive hemodynamic profiling.
- Trauma Care:Emergency department resuscitation bays in Vietnam's Ho Chi Minh City medical corridor and Thailand's trauma centers prioritize rapid non-invasive assessment for hemodynamically unstable patients.
- Anesthesia Monitoring:Operating theater integration in Indonesia's modernizing public hospitals drives demand for automated blood pressure and cardiac output trending during major abdominal and orthopedic procedures.
Critical Care leads procedural volume concentration. Cardiac Surgery maintains the highest revenue intensity per monitored case.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement authority across Asia-Pacific is hardening around tertiary care networks in China, India, and Japan. Public health system consolidation is compressing vendor margins while elevating technical compliance thresholds for hemodynamic platform suppliers.
China
Tier-one city hospital clusters in Beijing, Shanghai, and Guangzhou are driving concentrated demand for continuous monitoring systems as sepsis protocols mandate uninterrupted circulatory surveillance. NMPA's streamlined Class III medical device registration pathways under revised regulations are accelerating time-to-market for manufacturers with robust clinical dossiers. The Yangtze River Delta medical corridor is prioritizing integrated digital health infrastructure for hemodynamic data transmission.
Japan
Cardiac surgery suites in Tokyo and Osaka university hospitals sustain premium demand for invasive pulmonary artery catheterization despite complication risks. PMDA enforces rigorous domestic clinical evidence requirements for Class IV device approvals that delay product launches by 18-24 months versus comparable NMPA timelines. The Kansai region's metropolitan medical centers are prioritizing suppliers with established pharmacovigilance infrastructure over pure technology differentiation.
India
Metropolitan hospital clusters in Delhi-NCR, Mumbai, and Bangalore are institutionalizing continuous hemodynamic surveillance in ICUs through mandated sepsis bundles. CDSCO regulatory frameworks for Class C and D medical devices are elevating quality thresholds that benefit established manufacturers with dedicated regulatory affairs teams. Tamil Nadu's tertiary care networks are consolidating vendor contracts for platform standardization while demanding predictive maintenance service bundling.
Australia
Tertiary cardiac surgery centers in Sydney and Melbourne require comprehensive hemodynamic profiling for cardiopulmonary bypass procedures. TGA mandates post-market surveillance for implantable pressure sensors, tightening adverse event reporting obligations and elevating compliance overhead for manufacturers. New South Wales and Victoria medical centers are maintaining real-world performance registries to satisfy pharmacovigilance requirements.
Vietnam
Private hospital expansion in Ho Chi Minh City and Hanoi medical corridors is attracting foreign direct investment and opening distribution partnerships for mid-tier device manufacturers. The country's national pharmaceutical regulator is developing medical device registration frameworks aligned with ASEAN harmonization initiatives. Emergency department resuscitation bays in Ho Chi Minh City trauma centers are prioritizing rapid non-invasive assessment platforms for hemodynamically unstable patients.
Asia-Pacific Hemodynamic Monitoring Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positions in sensor technology and imaging integration. The vendor base concentrates around catheter-based monitoring platforms, integrated digital health infrastructure, and compact point-of-care diagnostics. Three strategic archetypes dominate: diversified medical technology conglomerates with critical care portfolios, cardiovascular-focused device specialists with hemodynamic depth, and imaging-system incumbents leveraging ultrasound familiarity. Competitive moves center on AI-enabled predictive analytics convergence and modular contracting unbundling of hardware, disposables, and software subscriptions.
Within the cardiovascular-focused tier, Edwards Lifesciences Corporation and Abbott Laboratories represent specialized catheter-based and point-of-care diagnostic positions respectively. Among diversified medical technology conglomerates, Medtronic exemplifies integrated digital health infrastructure deployment. These three anchors occupy distinct competitive vectors—precision invasive monitoring, compact high-acuity diagnostics, and connected care platforms—without overlapping core technology claims.
| Leading Market Players |
|---|
| ICU Medical |
| Medtronic |
| Edwards Lifesciences Corporation |
| Abbott Laboratories |
| Baxter International |
| GE Healthcare |
| Koninklijke Philips NV |
| Siemens Healthineers |
| Getinge AB |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement consolidation across China's tier-one cities and India's metropolitan clusters is forcing manufacturers to unbundle hardware, disposable catheters, and software subscriptions into modular contracts that compress unit margins while elevating service bundling requirements.
Pricing Analysis
Volume concentrates in invasive monitors while margins accrete to continuous monitoring systems with integrated predictive analytics. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled platforms with EMR connectivity from basic bioimpedance units and refurbished catheter systems. Pricing pressure stems from Southeast Asian district hospitals substituting ultrasound-based cardiac output monitoring for invasive catheter systems. Public tertiary networks in China and India exhibit highest price sensitivity; Japan's cardiac surgery suites demonstrate lowest sensitivity, prioritizing precision and pharmacovigilance infrastructure over cost minimization.
Supply Chain Analysis
ISO 13485 and NMPA Class III certification requirements gate component sourcing for pressure transducers and fiber-optic sensors, limiting qualified suppliers to Japanese and German precision manufacturers. High-precision MEMS fabrication concentrates in Japan, Germany, and the United States; disposable catheter assembly draws from Malaysia, Thailand, and China's medical device zones. Single-source vulnerability runs through Japanese sensor suppliers dominating ±2 mmHg accuracy specifications. Distribution runs through hospital group purchasing organizations in China and India, direct tenders in Japan, and distributor networks in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive production of pressure transducers and MEMS sensors to escape component bottlenecks and capture margin upstream.
For Market Incumbents: Cement platform stickiness through predictive maintenance service bundling and EMR integration depth that locks out non-invasive substitute technologies. Acquire or develop in-house MEMS sensor production to reduce dependence on Japanese and German component suppliers. Expand regulatory affairs teams in Beijing and Tokyo to compress NMPA and PMDA approval timelines versus emerging competitors. For New Entrants and Emerging Players: NMPA's streamlined Class III pathway in China opens a window for compact non-invasive monitors targeting tier-two hospitals where specialist shortages limit invasive procedure volumes. Focus initial penetration on Vietnam's private hospital corridor in Ho Chi Minh City and Hanoi, where foreign direct investment is expanding critical care infrastructure without entrenched vendor relationships. Partner with local distributors possessing established biomedical engineering service networks rather than building direct sales infrastructure. For Investors and Strategic Acquirers: The window for entry favors cardiovascular-focused device specialists with hemodynamic depth and established regulatory dossiers over diversified conglomerates lacking critical care concentration. Target acquisition profiles include mid-tier ultrasound monitoring developers with AI algorithm pipelines and established CE marking or NMPA registration progress. Watch for inflection upon Indonesia's hospital modernization program capital allocation announcements, which will signal demand acceleration for integrated monitoring platforms.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Predictive Analytics Development | Machine learning algorithms layered atop continuous hemodynamic streams enable early shock detection commanding premium pricing in sepsis protocols. |
| NMPA Class III Registration Acceleration | Streamlined innovation pathways reduce time-to-market for manufacturers with robust clinical dossiers targeting China's tier-one cities. |
| MEMS Sensor Backward Integration | In-house production of pressure transducers escapes Japanese and German supplier concentration and captures upstream margin. |
| Hospital System Partnership Expansion | Direct relationships with China's tertiary care networks and India's GPOs secure volume commitments and platform standardization. |
| Software Subscription Unbundling | Modular contracting separates hardware, disposable catheters, and predictive analytics subscriptions to align with procurement fragmentation. |
Study Parameters
Hospital procurement databases, NMPA and PMDA regulatory filings, and GPO contract registries formed the secondary backbone, supplemented by customs records tracking pressure transducer and catheter imports across China, India, Japan, and Southeast Asia. Primary interviews with biomedical engineers, hospital purchasing committee members, critical care clinicians, and GPO contracts managers validated demand assumptions and pricing dynamics. Bottom-up install base modeling and top-down healthcare expenditure allocation triangulated market sizing across continuous, invasive, and non-invasive product configurations.
Historical trendline analysis of hospital capital expenditure cycles and medical device procurement patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated product architecture, end-user facility type, sensing modality technology, and clinical application acuity. CAGRs derived from weighted average of equipment replacement cycles, ICU bed expansion rates, and sepsis protocol adoption curves. Forecast inputs included regulatory approval velocity differentials between NMPA and PMDA pathways and AI algorithm validation timelines for predictive hemodynamic analytics.
The model assumes a particular technology adoption path; alternative pathways for non-invasive bioimpedance and ultrasound cardiac output monitoring would alter the outlook if accuracy validation closes the gap with invasive reference methods. Forecasts reflect assumptions regarding hospital budget recovery trajectories post-pandemic and sustained NMPA pathway streamlining. A model refresh is warranted upon material change in Indonesia's hospital modernization program capital allocation or Japanese PMDA evidence requirement modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Asthma Monitoring Devices Market