
 Asia Pacific Wireless Healthcare Market | 2026-2036
Asia Pacific Wireless Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wireless Healthcare Market Outlook
The Asia Pacific wireless healthcare sector is rebalancing between premium integrated systems and commodity-grade monitoring hardware. Huawei Technologies Co., Ltd. leverages its 5G infrastructure dominance to anchor hospital-grade connectivity platforms across Chinese provinces. GE HealthCare competes through specialized imaging-to-cloud architectures that sustain R&D intensity in diagnostic-grade wearables.
Wireless healthcare encompasses medical-grade data transmission, remote diagnostics, and patient monitoring through radio-frequency networks, Bluetooth Low Energy, and cellular protocols operating at sub-6 GHz and millimeter-wave spectra. The primary commercial purpose is enabling continuous physiological surveillance without tethered infrastructure. Wearable Devices and Remote Monitoring Systems command the deepest margin pools where FDA-equivalent clearance and clinical validation create pricing power, while Telehealth Solutions extend fastest across lower-tier cities as broadband penetration deepens. Cloud-Based delivery dominates enterprise hospital contracts, though Hybrid Solutions gain traction where data sovereignty requirements fragment storage architecture.
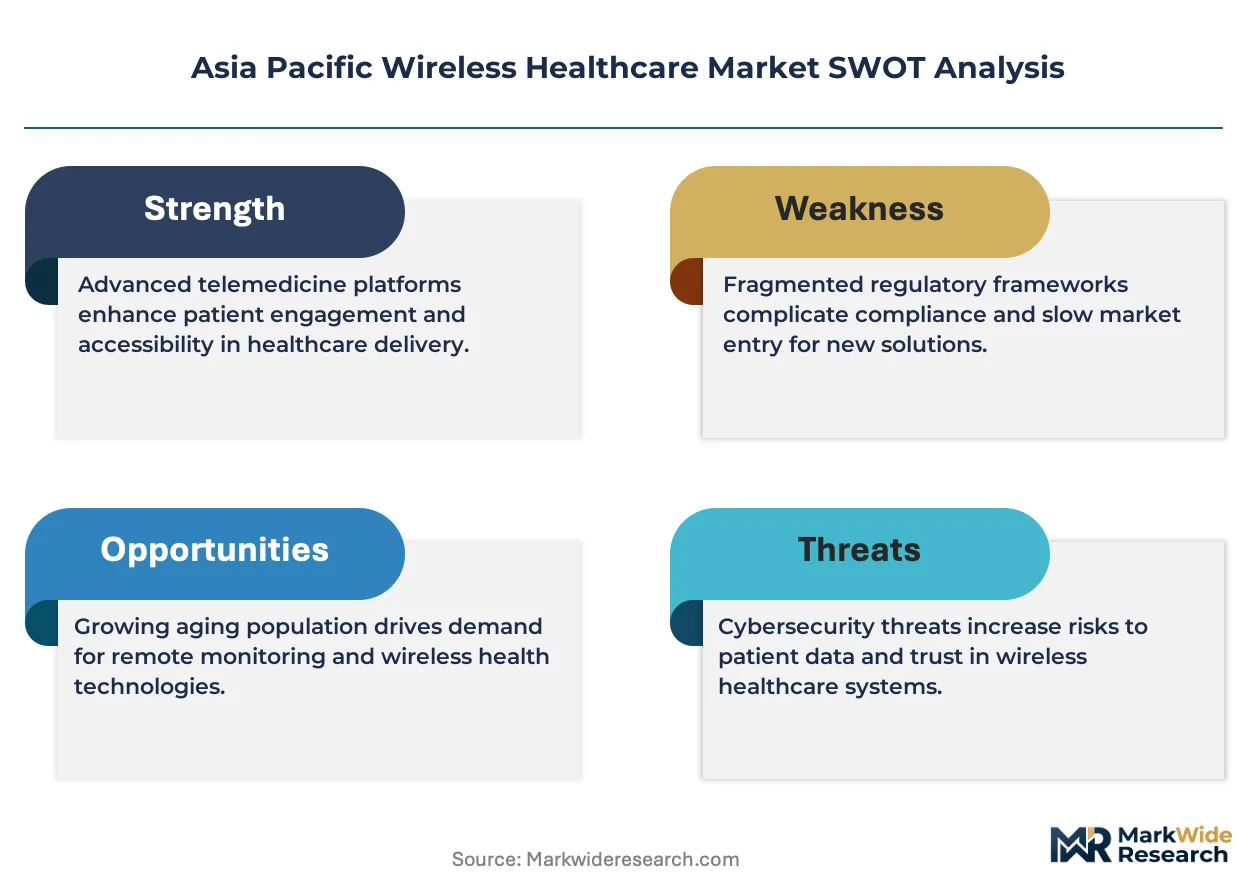
Japan's PMDA and South Korea's MFDS enforce device safety and software validation standards that shape product registration timelines across Northeast Asia, while India's CDSCO accelerates digital therapeutics approvals under revised medical device rules. China's NMPA and MIIT jointly govern connected health data flows through GB standards and cybersecurity provisions that condition market access for foreign platforms. Stakeholders must monitor which regulatory pathway—pre-market approval versus post-market surveillance—emerges as the binding constraint for AI-enabled diagnostic tools.
Market Dynamics
5G infrastructure deployment by national telecom operators is compressing latency thresholds for real-time diagnostic transmission, forcing hospital procurement cycles to synchronize with network rollout timelines rather than traditional capital budgeting seasons.
Growth Catalysts
- China's MIIT hospital digitization mandates:Provincial health commissions must achieve connected device penetration targets by fixed deadlines, creating procurement pull-through for wireless monitoring hardware.
- India's CDSCO accelerated digital therapeutics pathway:Revised medical device rules compress software validation timelines, enabling faster market entry for algorithm-driven diagnostic tools.
- Bluetooth Low Energy 5.3 adoption:Wearable manufacturers leverage improved power efficiency to extend continuous glucose monitoring duration without patient intervention.
Market Restraints
- Millimeter-wave spectrum licensing costs:National regulators in Southeast Asia impose fees that inflate total cost of ownership for rural hospital connectivity deployments.
- GB standards compliance burden:China's NMPA and MIIT jointly enforce data localization requirements that fragment cloud architecture and duplicate infrastructure spend.
- Semiconductor foundry concentration in Taiwan:Wireless medical device OEMs face allocation risk for sub-6 GHz RF front-end components during supply shocks.
Strategic Opportunities
- Indonesia's tier-3 city hospital networks:Java and Sumatra provincial health systems lack wired infrastructure, creating first-mover advantage for cellular-based remote monitoring.
- AI-enabled predictive analytics:Machine learning models trained on continuous vital sign streams enable early sepsis detection in ICU settings without additional hardware.
- Vietnam's public-private partnership framework:Ministry of Health incentives for telehealth infrastructure reduce capital barriers for foreign platform operators.
Industry Challenges
- Clinical validation workforce scarcity:Biostatisticians capable of designing FDA-equivalent equivalence trials for wireless diagnostics command premium compensation across Shanghai and Singapore.
- Interoperability with legacy HL7 v2 systems:Hospital IT departments in Japan's prefectural medical centers struggle to integrate BLE-enabled devices with decades-old electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wireless Healthcare Market |
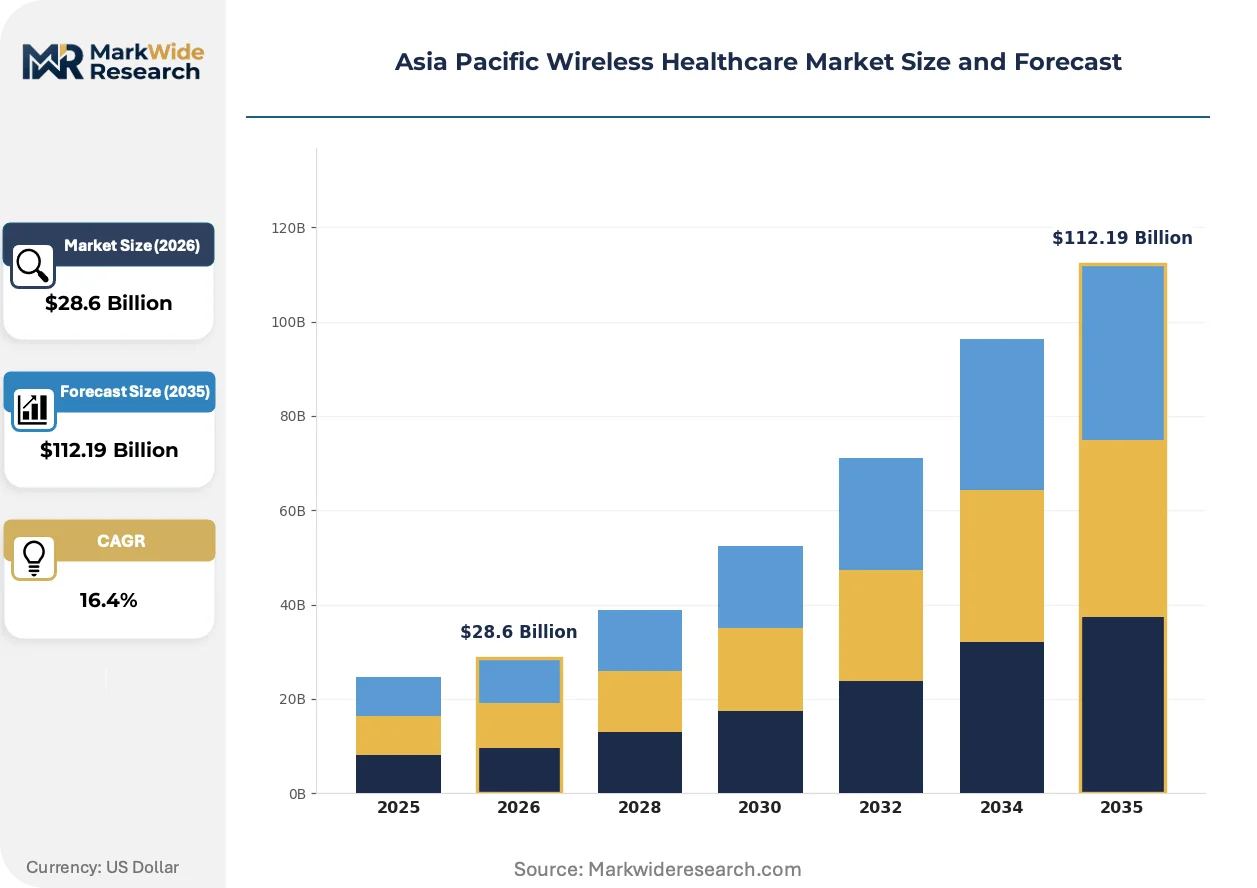
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Telehealth Solutions, Mobile Health Apps, Remote Monitoring Systems Delivery Mode: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Platforms End User: Hospitals, Patients, Clinics, Healthcare Providers Application: Chronic Disease Management, Fitness Tracking, Emergency Response, Health Monitoring |
| Companies Covered | Huawei Technologies Co., Ltd., GE HealthCare, Qualcomm Technologies Inc., Medtronic plc, Siemens Healthineers, Koninklijke Philips NV, Philips Healthcare, Cisco Systems Inc., Samsung Electronics Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wireless Healthcare Market Strategic Shifts
Edge computing architectures are migrating analytical workloads from centralized cloud servers to bedside processing units, reducing dependency on uninterrupted connectivity for critical care applications.
Millimeter-wave 5G is overtaking sub-6 GHz as the preferred spectrum for high-resolution imaging transmission in Chinese tertiary hospitals. Radiologists at Peking Union Medical College Hospital now receive uncompressed MRI slices within seconds rather than minutes. This compression of diagnostic turnaround time is collapsing the historical trade-off between image fidelity and transmission speed.
Japan's PMDA has tightened software as a medical device (SaMD) validation requirements for AI diagnostic algorithms, extending pre-market review timelines by four to six months. Domestic manufacturers are responding by front-loading clinical evidence collection during development rather than post-hoc submission. Korean competitors under MFDS jurisdiction face similar documentation burdens but benefit from faster parallel track reviews.
Hospital procurement committees are unbundling device hardware from cloud service subscriptions, forcing vendors to price connectivity separately from capital equipment. Australian public hospital networks pioneered this separation, and the model has spread to New Zealand and Singapore within eighteen months. Vendors now compete on annual data transmission fees rather than upfront device margins.
Asia Pacific Wireless Healthcare Market Segmentation
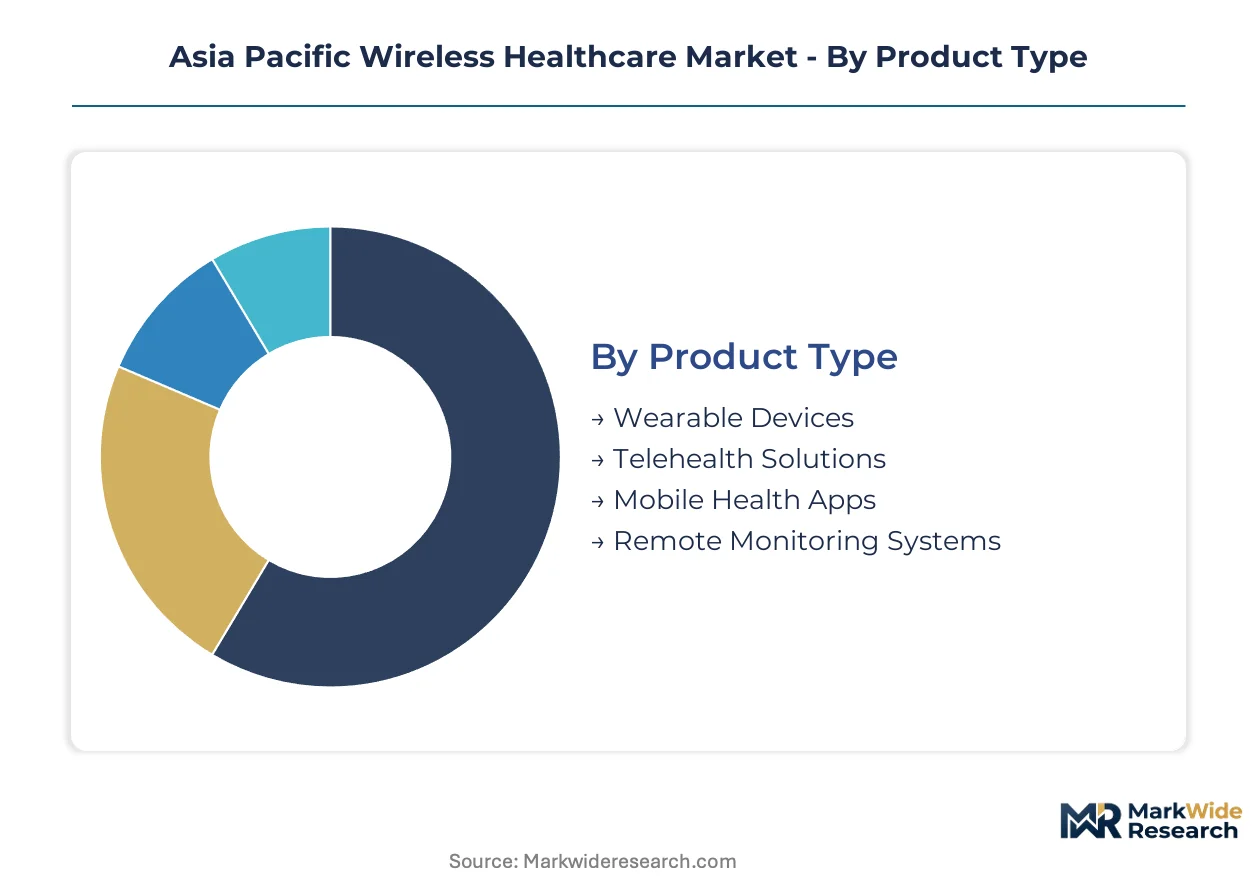
Wireless healthcare markets fragment across four distinct dimensions that shape procurement patterns and margin structures differently. Product type determines hardware versus software revenue mix, while delivery mode governs data sovereignty compliance costs. End user concentration and application specificity further condition pricing power and clinical validation requirements.
Product Type:
Standardization dominates consumer-facing hardware, whereas hospital-grade equipment demands extensive customization for institutional workflows.
- Remote Monitoring Systems:Continuous physiological surveillance platforms integrate BLE 5.3, sub-6 GHz cellular, and millimeter-wave transmission protocols. China's provincial hospital digitization mandates under MIIT are pulling procurement volume for ICU-grade bedside units with edge computing capabilities.
- Wearable Devices:Skin-adhesive biosensors and wrist-worn monitors capture ECG, SpO2, and glucose data streams. India's CDSCO accelerated pathway is compressing validation timelines for algorithm-driven diagnostic wearables targeting tier-2 and tier-3 city deployments.
- Telehealth Solutions:Video consultation platforms with integrated diagnostic device compatibility. Vietnam's Ministry of Health public-private partnership incentives reduce capital barriers for foreign platform operators entering provincial networks.
- Mobile Health Apps:Smartphone-based medication adherence and symptom tracking applications. Japan's PMDA tightened SaMD validation requirements extend pre-market review timelines by four to six months for algorithm-enabled diagnostic features.
Leading the category by volume: Remote Monitoring Systems. Expanding most quickly: Wearable Devices.
Delivery Mode:
Cost tier separation runs deepest here, with cloud subscriptions commanding premium recurring revenue against capital-heavy on-premises installations.
- Cloud-Based:Centralized data lakes with API connectivity to hospital EHR systems. Australia's public hospital networks pioneered unbundled pricing that separates hardware from annual transmission fees, now spreading to New Zealand and Singapore.
- Hybrid Solutions:Split architectures keeping PHI on local servers while analytics run in distributed cloud nodes. China's NMPA and MIIT joint data localization requirements under GB standards fragment storage architecture and duplicate infrastructure spend.
- On-Premises:Fully air-gapped deployments for maximum data sovereignty. Indonesia's tier-3 city hospital networks in Java and Sumatra lack reliable connectivity, sustaining demand for standalone systems.
- Mobile Platforms:Lightweight deployments optimized for smartphone and tablet endpoints. South Korea's MFDS parallel track review system enables faster software updates than Japan's sequential PMDA process.
Dominating revenue contribution: Cloud-Based. Gaining share fastest: Hybrid Solutions.
End User:
Customer type maturity varies sharply, with hospital procurement committees driving standardization while patient-direct channels reward feature differentiation.
- Hospitals:Enterprise contracts spanning thousands of connected beds with 99.99% uptime SLAs. Peking Union Medical College Hospital now receives uncompressed MRI slices via millimeter-wave 5G within seconds, collapsing diagnostic turnaround time.
- Clinics:Smaller-scale deployments prioritizing interoperability with legacy HL7 v2 EHR systems. Japan's prefectural medical centers struggle to integrate BLE-enabled devices with decades-old electronic health record architectures.
- Healthcare Providers:Physician group practices and home health agencies. India's rural hospital networks across Maharashtra and Karnataka are accelerating remote patient monitoring adoption without wired infrastructure.
- Patients:Direct-to-consumer purchases bypassing institutional procurement. Bluetooth Low Energy 5.3 power efficiency improvements extend continuous glucose monitoring duration without patient intervention.
Generating highest absolute revenue: Hospitals. Showing steepest adoption curve: Healthcare Providers.
Application:
Volume concentration aligns with chronic disease prevalence, while margin accrues to emergency applications where latency tolerance approaches zero.
- Chronic Disease Management:Longitudinal tracking of diabetes, hypertension, and cardiovascular conditions through connected devices. Continuous vital sign streams enable AI-enabled predictive analytics for early sepsis detection in ICU settings without additional hardware.
- Emergency Response:Real-time location tracking and automated alert systems for cardiac events. 5G network rollouts by national telecom regulators enable real-time transmission of high-resolution diagnostic imaging to emergency departments.
- Health Monitoring:General wellness tracking for preventive care programs. Singapore's integrated health clusters are deploying population-scale connected monitoring for elderly fall detection.
- Fitness Tracking:Consumer-oriented activity and biometric monitoring. Australian and New Zealand health insurers are experimenting with premium discounts tied to verified fitness data sharing.
Commanding largest installed base: Chronic Disease Management. Climbing the fastest: Emergency Response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors wireless healthcare deployment through its integrated hospital digitization corridors, where municipal health commissions synchronize 5G infrastructure with connected medical device procurement at scale.
China
Provincial hospital networks across Guangdong and Jiangsu drive bulk purchasing of ICU-grade remote monitoring systems under MIIT digitization mandates. NMPA and MIIT jointly enforce GB standards for data localization that fragment cloud architectures. Beijing-Tianjin-Hebei corridor hosts concentrated R&D activity for edge computing bedside units.
Japan
Prefectural medical centers in Kansai and Chubu prioritize interoperability investments for legacy HL7 v2 EHR systems. PMDA tightened SaMD validation requirements extend pre-market review timelines for AI diagnostic algorithms. Tokyo's academic medical centers lead clinical validation workforce development for equivalence trial design.
India
Rural hospital networks across Maharashtra and Karnataka accelerate remote patient monitoring adoption without wired infrastructure. CDSCO's revised medical device rules compress software validation timelines for algorithm-driven diagnostic tools. Bangalore's health technology cluster concentrates wearable device development for tier-2 and tier-3 city deployments.
South Korea
Seoul Capital Area health systems deploy millimeter-wave 5G for real-time diagnostic imaging transmission. MFDS parallel track review system enables faster software updates than sequential regulatory processes. Busan-Ulsan corridor manufactures sub-6 GHz RF front-end components for regional device OEMs.
Australia
Public hospital networks in New South Wales and Victoria pioneered unbundled pricing that separates hardware from annual data transmission fees. TGA oversight shapes software validation requirements for connected therapeutic devices. Sydney's integrated health clusters extend population-scale elderly monitoring programs.
Asia Pacific Wireless Healthcare Market Competitive Environment
Premium-margin players sit above commodity-margin players across the certification-grade spectrum, with FDA-equivalent clearance and clinical validation creating pricing power at the top. The vendor base concentrates around three strategic archetypes: telecommunications infrastructure providers leveraging 5G dominance, specialized medical technology developers with imaging-to-cloud architectures, and diversified electronics conglomerates with component-scale advantages. Dominant competitive moves include strategic partnerships between connectivity providers and hospital systems, plus portfolio diversification into edge computing hardware.
Within the infrastructure-provider tier, Huawei Technologies Co., Ltd. exemplifies telecommunications-anchored platform development, while GE HealthCare occupies a position representing specialized diagnostic-grade system integration. Among diversified technology conglomerates, Samsung Electronics Co., Ltd. sits within the component-scale manufacturing archetype. These three entities represent distinct competitive vectors: network infrastructure ownership, clinical validation depth, and semiconductor supply chain control.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| GE HealthCare |
| Qualcomm Technologies Inc. |
| Medtronic plc |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Philips Healthcare |
| Cisco Systems Inc. |
| Samsung Electronics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Provincial hospital procurement committees across Guangdong and Jiangsu drive volume-based contract structures that compress margins for hardware vendors while elevating recurring SaaS revenue streams. China's MIIT digitization mandates synchronize bulk purchasing timelines, forcing suppliers to absorb upfront certification costs in exchange for multi-year connectivity subscriptions.
Pricing Analysis
Uptime-guarantee pricing anchors enterprise hospital contracts, with 99.99% SLA commitments commanding premium positioning against standard-tier offerings. Certification-grade differentiation separates FDA-equivalent cleared devices from commodity monitoring hardware, while customization depth for institutional workflows adds further price stratification. Cost compression in the standard tier intensifies as domestic Chinese manufacturers scale BLE 5.3 production, though premium diagnostic-grade equipment retains pricing power. Public hospital networks exhibit highest price sensitivity due to fixed provincial budgets, whereas private tertiary hospitals prioritize performance guarantees over unit economics.
Supply Chain Analysis
RF front-end engineering talent scarcity in Shanghai and Shenzhen constrains expansion velocity for sub-6 GHz component manufacturers. Taiwan, South Korea, and mainland China concentrate semiconductor foundry capacity for medical-grade wireless chipsets, drawing from gallium arsenide substrates, advanced packaging substrates, and precision RF filters. Single-source vulnerability runs through Taiwan-based wafer fabrication for millimeter-wave modules. Distribution runs through authorized medical device distributors with NMPA registration credentials, bypassing general electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific wireless healthcare is consolidating around platform-scale players as China's GB standards compliance burden squeezes sub-scale foreign vendors from provincial procurement pools.
For Market Incumbents: Acquire edge computing hardware capabilities to anchor bedside analytical workloads and reduce cloud dependency. Lock in multi-year provincial hospital contracts under MIIT digitization deadlines before compliance costs escalate. Defensive positioning requires deepening clinical validation workforce in Tokyo and Singapore as PMDA and MFDS documentation burdens extend review timelines. For New Entrants and Emerging Players: Enter via Indonesia's tier-3 city hospital networks in Java and Sumatra, where wired infrastructure gaps create first-mover cellular deployment opportunities. Target Vietnam's public-private partnership telehealth incentives for reduced capital barrier entry. Lead with AI-enabled predictive analytics for sepsis detection, requiring no incremental hardware investment from cash-constrained rural facilities. For Investors and Strategic Acquirers: The window for entry favors specialized imaging-to-cloud architects with existing FDA-equivalent clearance portfolios. Long-term viability hinges on regulatory pathway diversification across NMPA, PMDA, and MFDS jurisdictions. Watch CDSCO's digital therapeutics approval velocity as the inflection signal for algorithm-driven diagnostic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures multi-year provincial procurement slots under China's MIIT digitization mandates. |
| CE Marking Pathway | Unlocks premium hospital access across Australia's TGA-governed public network tenders. |
| Software Companion Development | Enables AI-enabled sepsis detection without hardware retrofit in India's rural ICUs. |
| Reimbursement Strategy | Positions continuous glucose monitors for national health insurance coverage in South Korea. |
| Strategic Partnership | Combines Huawei's 5G infrastructure with GE HealthCare's imaging-to-cloud architectures. |
Study Parameters
Hospital procurement databases, GPO contracts, and CMS Medicare-equivalent data across Asia Pacific formed the secondary backbone for market sizing validation. Primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with regulatory filing analysis from NMPA, PMDA, CDSCO, and MFDS to triangulate bottom-up device shipment estimates against top-down healthcare IT spending forecasts.
Historical trendline analysis of connected medical device adoption across Chinese provincial hospital networks established baseline penetration rates. Segmentation modeling incorporated product type, delivery mode, end user concentration, and application specificity dimensions throughout the forecast period. CAGRs derived from regression analysis of 5G infrastructure rollout timelines correlated with procurement cycle synchronization patterns, with edge computing adoption curves and AI diagnostic algorithm validation timelines serving as industry-specific adjustment inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply shock scenarios or abrupt GB standards enforcement shifts. Projections reflect documented assumptions regarding network infrastructure deployment schedules and regulatory pathway stability. Material deviation in MIIT mandate deadlines or Taiwan foundry allocation disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Global Biomedical Sensor Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market
Patient Monitoring
Multi-Item Patient Monitor Market