
 Home Care Monitoring and Diagnostics Market | 2026-2036
Home Care Monitoring and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Home Care Monitoring and Diagnostics Market Analysis
Direct-to-patient distribution is rewriting how diagnostic hardware reaches end users, bypassing traditional hospital procurement and shortening replenishment cycles. Abbott Diagnostics leverages its vertically integrated sensor manufacturing to control supply continuity for glucose monitoring strips. Philips Healthcare anchors its position through dedicated home care service networks that bundle device installation with clinician training. Omron Healthcare differentiates via pharmacy-centric retail placement that captures hypertensive patient traffic at point of prescription.
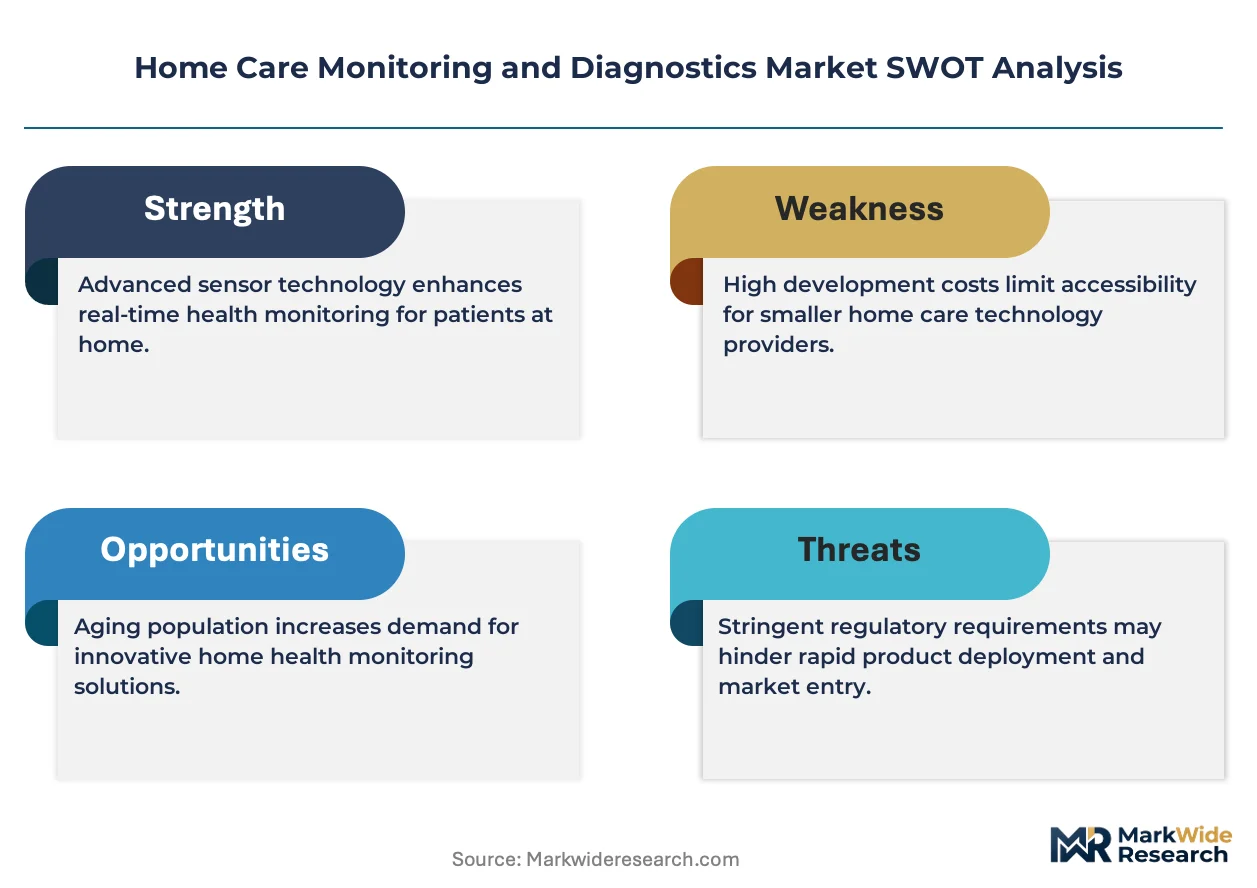
Home care monitoring and diagnostics encompasses portable and connected devices that measure physiological parameters—blood glucose, blood pressure, cardiac rhythm, oxygen saturation—using electrochemical sensors, photoplethysmography, or impedance-based methods, with data transmission to clinicians via encrypted wireless protocols. Its primary purpose is to shift acute care surveillance from institutional settings to residential environments, reducing emergency department utilization. Wearable devices and remote monitoring systems command the dominant revenue share due to recurring consumable revenue and subscription-based data services. Diagnostic kits retain stable demand in regions with limited broadband penetration where asynchronous testing outperforms real-time connectivity. Telehealth solutions represent the fastest-expanding margin pool as platforms integrate AI triage and automated escalation protocols.
FDA Software as a Medical Device frameworks and HIPAA interoperability standards shape product architecture, data governance, and liability exposure for manufacturers entering the home channel. The EU MDR and GDPR impose parallel conformity and privacy obligations on devices distributed across European member states. Stakeholders must monitor evolving reimbursement codes that determine whether home monitoring costs fall to insurers, patients, or integrated delivery networks.
Market Dynamics
Medicare reimbursement codes for remote therapeutic monitoring have created direct payment infrastructure that pulls acute care surveillance into residential settings, compressing traditional hospital-centric procurement cycles and rewiring how diagnostic hardware reaches end users.
Growth Catalysts
- Remote Patient Monitoring Platforms:Chronic disease management programs in home health agencies are expanding adoption of connected physiological measurement devices.
- FDA Software as a Medical Device Pathways:Accelerated clearance frameworks are shortening product commercialization timelines for algorithm-driven diagnostic tools.
- United States Demand Concentration:Direct-to-patient distribution models are bypassing hospital procurement and shortening replenishment cycles for consumable sensors.
Market Restraints
- Sensor Manufacturing Concentration:Electrochemical glucose strip production depends on vertically integrated manufacturers controlling substrate and enzyme supply continuity.
- Broadband Infrastructure Gaps:Real-time data transmission fails in regions with limited connectivity, forcing reliance on asynchronous diagnostic kits.
- EU MDR Conformity Costs:Parallel GDPR privacy obligations and medical device regulation impose certification burdens on European distribution.
Strategic Opportunities
- AI Triage Integration:Telehealth platforms are converging with automated escalation protocols to capture the fastest-expanding margin pool in home monitoring.
- Pharmacy-Centric Retail Placement:Hypertensive patient traffic at point of prescription creates capture opportunities for blood pressure device manufacturers.
- Encrypted Wireless Protocol Adoption:HIPAA interoperability standards are mandating data governance upgrades that favor compliant platform vendors.
Industry Challenges
- Clinician Training Requirements:Device installation and patient onboarding demand specialized field service networks that strain operational scale.
- Legacy System Integration:Electronic health record interoperability gaps complicate data flow from home devices to institutional care teams.
- Consumable Revenue Model Pressure:Subscription-based data services require sustained patient adherence that operational support infrastructure must maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Care Monitoring and Diagnostics Market |
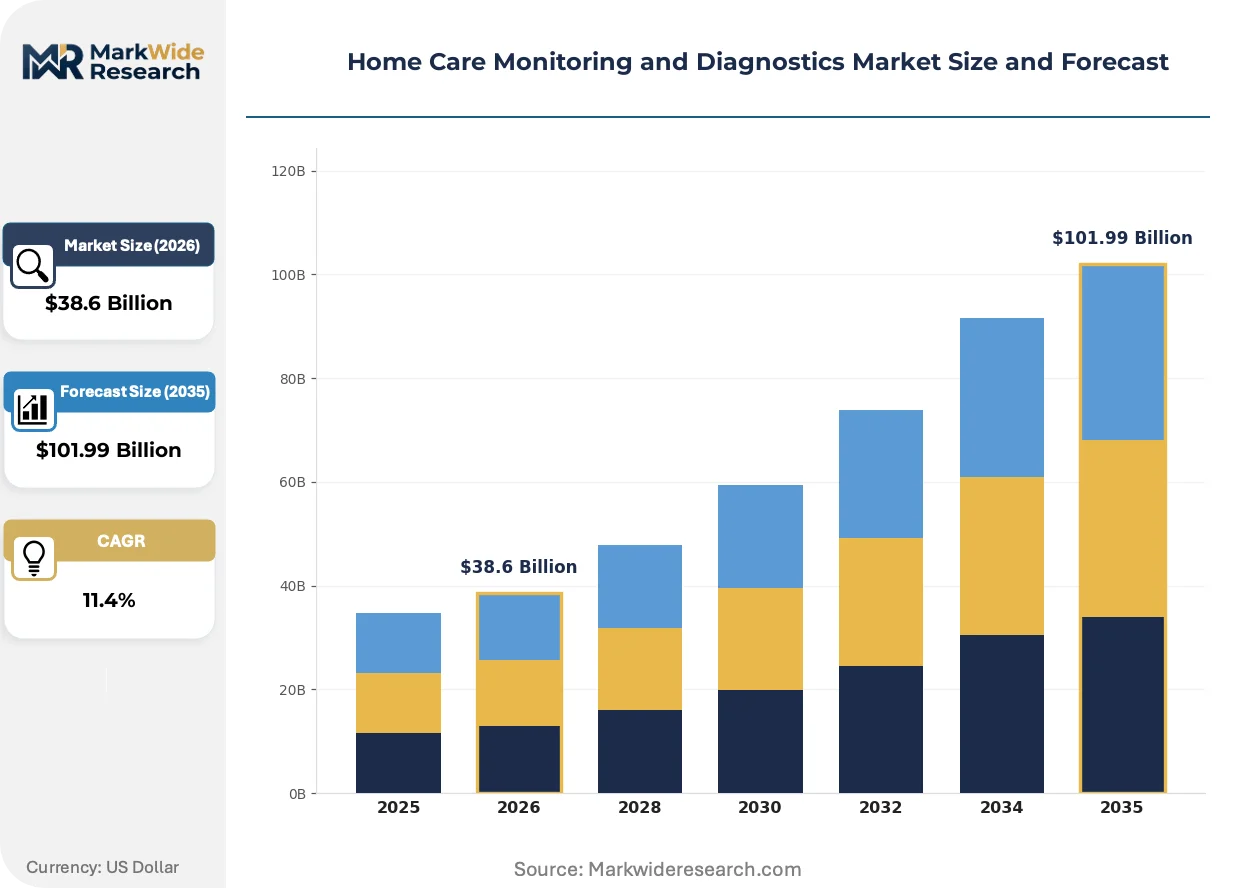
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring Systems, Diagnostic Kits, Telehealth Solutions End User: Patients, Caregivers, Healthcare Providers, Home Health Agencies Technology: Wireless Technology, IoT Solutions, Mobile Applications, Telemedicine Platforms Service Type: Data Analysis, Consultation Services, Technical Support, Training Services |
| Companies Covered | Abbott Diagnostics, Philips Healthcare, Roche Diagnostics, Omron Healthcare, Johnson & Johnson, Medtronic, F. Hoffmann-La Roche Ltd., Siemens Healthineers, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Care Monitoring and Diagnostics Market Emerging Trajectories
Photoplethysmography and impedance-based sensing methods are converging with machine learning inference at the edge, compressing the latency between physiological event detection and clinical response while redistributing diagnostic authority from centralized labs to distributed home environments.
Multi-parameter wearable patches are hybridizing optical and electrical sensing modalities to capture simultaneous cardiac rhythm, oxygen saturation, and blood pressure signals from single-site skin contact. Home health agencies with chronic disease management contracts are piloting these devices for post-acute cardiac monitoring. This convergence is hybridizing the traditional separation between discrete diagnostic instruments and continuous surveillance platforms, collapsing multiple revenue streams into unified subscription offerings.
The EU AI Act and FDA Software as a Medical Device frameworks are imposing algorithmic transparency requirements on diagnostic algorithms that triage patient data. Manufacturers must document training data provenance and performance validation across demographic subgroups. Class II device submissions for AI-enabled home diagnostics are experiencing elongated review timelines as regulators establish precedent for autonomous clinical decision support.
Hospital procurement departments are unbundling after-sales service from device acquisition, forcing manufacturers to price installation, training, and technical support as separate line items. Integrated delivery networks in competitive metropolitan markets are driving this disintermediation to reduce total cost of ownership. This purchasing pattern is most visible in United States markets where Medicare Advantage plans capitate home monitoring expenditures and demand granular cost accounting.
Home Care Monitoring and Diagnostics Market Segmentation
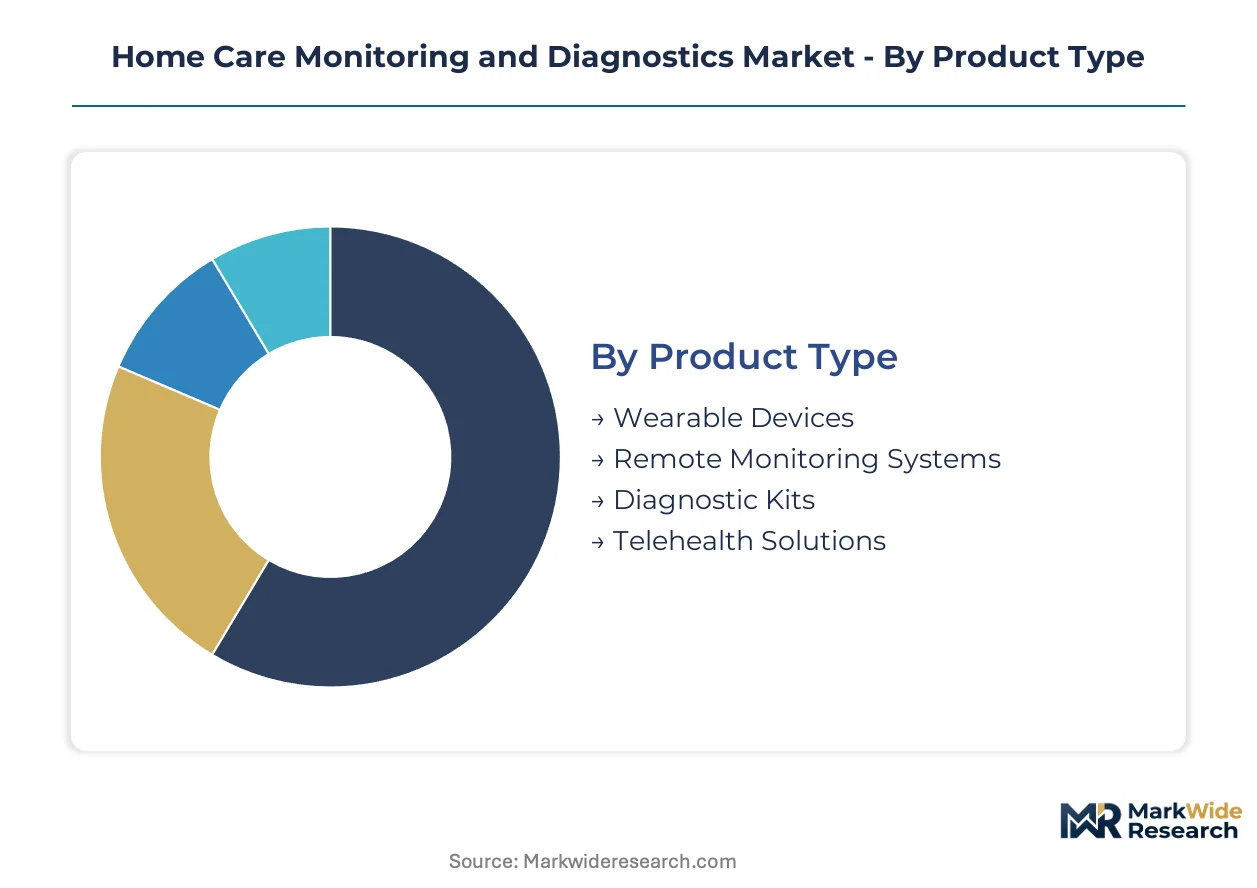
Segmentation in home care monitoring and diagnostics reveals how after-sales service intensity varies dramatically across product categories. Service bundling decisions directly shape margin capture and customer retention in this hardware-dependent market.
Product Type:
After-sales service intensity peaks with wearable devices and remote monitoring systems, where installation complexity and patient onboarding demands strain operational scale.
- Wearable Devices:Multi-parameter patches hybridize optical and electrical sensing modalities for simultaneous cardiac rhythm, oxygen saturation, and blood pressure capture. Demand concentrates in post-acute cardiac monitoring contracts with United States home health agencies, where Medicare reimbursement codes pull surveillance into residential settings.
- Remote Monitoring Systems:Connected physiological measurement platforms transmit blood glucose, blood pressure, and oxygen saturation data via encrypted wireless protocols. United States demand dominates due to direct payment infrastructure for remote therapeutic monitoring that compresses hospital-centric procurement cycles.
- Diagnostic Kits:Asynchronous testing solutions serve regions with limited broadband penetration where real-time connectivity fails.
- Telehealth Solutions:AI-enabled platforms with automated escalation protocols integrate triage capabilities for margin expansion.
Wearable devices hold the largest share; momentum sits with telehealth solutions.
End User:
Cost tier stratification separates institutional purchasers from direct-to-patient acquisition patterns, with Medicare Advantage capitation driving granular cost accounting demands.
- Patients:Direct acquisition through pharmacy-centric retail placement captures hypertensive traffic at prescription points.
- Caregivers:Informal care networks require simplified device interfaces and remote troubleshooting support.
- Healthcare Providers:Integrated delivery networks in competitive United States metropolitan markets unbundle after-sales service from device acquisition.
- Home Health Agencies:Chronic disease management programs expand adoption of connected devices through dedicated service networks bundling installation with clinician training.
Home health agencies hold the largest share; momentum sits with direct patient acquisition.
Technology:
Application maturity separates established wireless transmission from emerging edge inference capabilities, with latency compression redistributing diagnostic authority to residential environments.
- Wireless Technology:HIPAA interoperability standards mandate encrypted data transmission protocols.
- IoT Solutions:Machine learning inference at the edge compresses latency between physiological event detection and clinical response.
- Mobile Applications:Patient-facing interfaces require sustained adherence support that operational infrastructure must maintain.
- Telemedicine Platforms:Convergence with AI triage captures the steepest expansion trajectory in platform-based service margins.
Wireless technology holds the largest share; momentum sits with telemedicine platforms.
Service Type:
Margin concentration favors recurring revenue streams over one-time technical interventions, with subscription-based data services requiring operational infrastructure to sustain patient adherence.
- Data Analysis:AI-driven interpretation of continuous physiological signals demands algorithmic transparency documentation under FDA Software as a Medical Device frameworks.
- Consultation Services:Clinical triage integration with automated escalation protocols expands margin pools.
- Technical Support:Field service networks for device installation strain operational scale in distributed residential settings.
- Training Services:Clinician onboarding and patient education separate as unbundled line items under competitive procurement pressure.
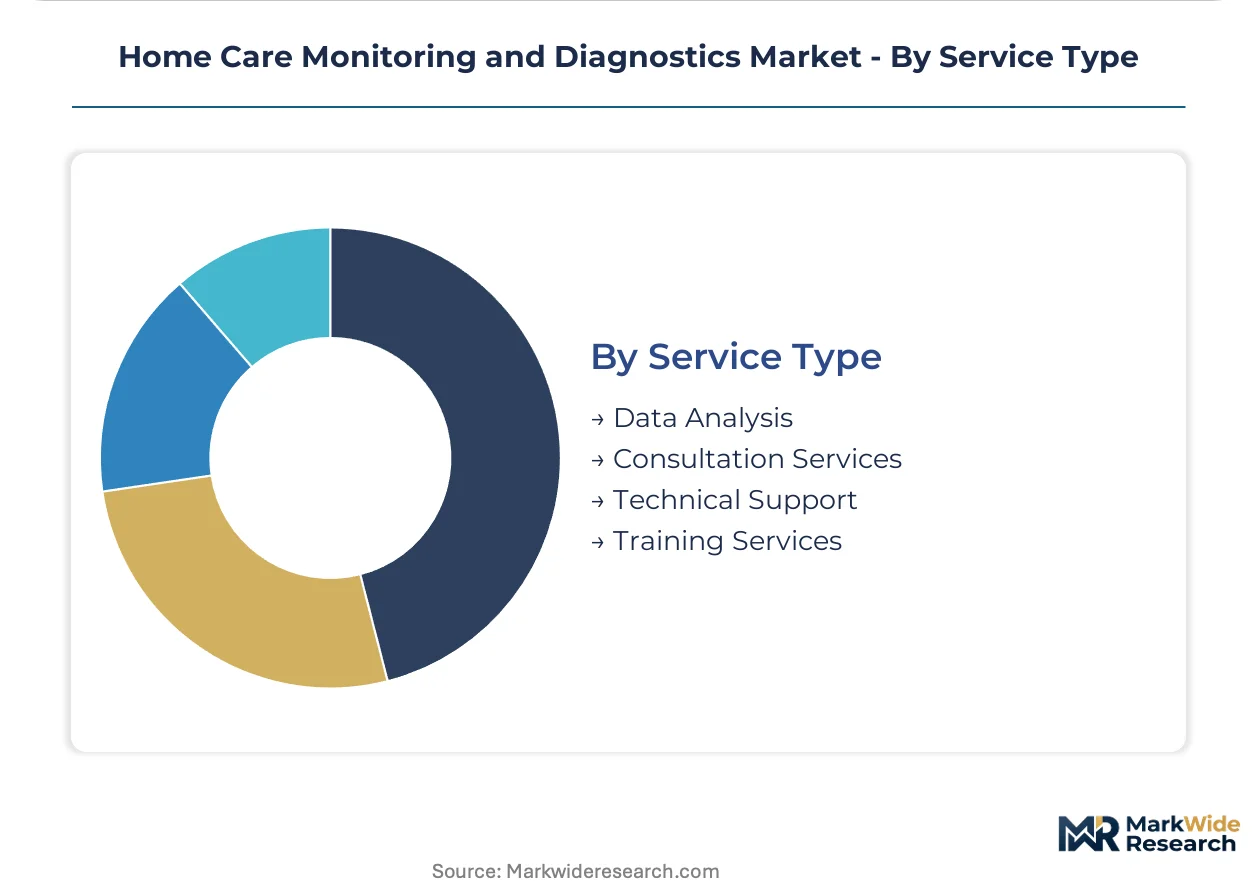
Data analysis holds the largest share; momentum sits with consultation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price realization in the United States runs 40-60% above European levels due to Medicare reimbursement infrastructure, while German and Japanese markets compress margins through reference pricing and stringent procurement protocols.
United States
Medicare reimbursement codes for remote therapeutic monitoring pull acute care surveillance into residential settings, creating direct payment infrastructure that bypasses hospital procurement. FDA Software as a Medical Device pathways accelerate commercialization timelines for algorithm-driven diagnostic tools. The Boston-Cambridge corridor concentrates digital health venture activity, with home monitoring startups clustering near Massachusetts General Hospital and the MIT innovation ecosystem.
Germany
Chronic disease management contracts with statutory health insurers drive adoption of connected physiological measurement devices in ambulatory care networks. EU MDR conformity requirements and GDPR privacy obligations impose certification burdens on device distribution. The MedTech cluster in Baden-Württemberg, centered on Stuttgart and Tübingen, hosts precision sensor manufacturers supplying electrochemical substrate for glucose monitoring strips.
Japan
Aging demographics and hospital bed reduction policies accelerate demand for home-based cardiac rhythm and blood pressure surveillance. PMDA regulatory frameworks govern Software as a Medical Device submissions for AI-enabled diagnostic algorithms. The Kansai region around Osaka anchors domestic manufacturing of photoplethysmography sensors, with METI industrial policy supporting edge inference chip development for wearable patches.
China
Hospital-at-home pilot programs in tier-one cities expand procurement of multi-parameter monitoring devices for post-acute cardiac patients. NMPA medical device registration requirements and MIIT data localization rules shape product architecture for wireless transmission protocols. The Yangtze River Delta, particularly Suzhou and Shanghai, concentrates contract manufacturing of electrochemical biosensors for export markets.
United Kingdom
NHS Long Term Plan commitments to out-of-hospital care shift investment toward remote patient monitoring platforms for chronic disease cohorts. MHRA post-Brexit regulatory autonomy maintains alignment with FDA breakthrough device pathways for accelerated market access. The Oxford-Cambridge Arc hosts telehealth platform developers integrating AI triage with automated escalation protocols for margin expansion.
Home Care Monitoring and Diagnostics Market Vendor Landscape
Vertically integrated diagnostics conglomerates and specialized sensor manufacturers split the market into distinct capability tiers, with consolidated procurement power in United States integrated delivery networks favoring full-service vendors over component suppliers. The competitive terrain stratifies across three archetypes: diversified health technology conglomerates with captive sensor manufacturing, focused device specialists leveraging pharmacy retail channels, and digital-native platform vendors monetizing subscription data services. Dominant competitive moves include backward integration into electrochemical substrate production and strategic partnerships with home health agencies for dedicated service network deployment.
Among diversified health technology conglomerates, Abbott Diagnostics and Philips Healthcare exemplify contrasting approaches to home channel penetration—Abbott through upstream control over enzyme and substrate supply continuity for consumable revenue streams, Philips through field service networks bundling device installation with clinician training. Omron Healthcare occupies a distinct position within the pharmacy-centric retail placement archetype, capturing hypertensive patient traffic at prescription points through blood pressure device differentiation. These three anchors illustrate how strategic archetype selection determines margin pool access in a market where recurring consumable revenue and subscription-based data services command premium valuations.
| Leading Market Players |
|---|
| Abbott Diagnostics |
| Philips Healthcare |
| Roche Diagnostics |
| Omron Healthcare |
| Johnson & Johnson |
| Medtronic |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers |
| Fitbit |
| Others |
Supply Flow & Price Mechanics
Electrochemical substrate manufacturing for glucose monitoring strips concentrates in vertically integrated producers across the United States and Germany, anchoring margin capture downstream in consumable revenue streams rather than device hardware. Pricing power flows to manufacturers controlling enzyme supply continuity and FDA-cleared production lines, while distributors and retail pharmacies compete on replenishment speed and patient adherence programs.
Pricing Analysis
Configured-to-order pricing for remote monitoring platforms with bundled installation and clinician training commands premiums of 25-35% above standard direct-to-patient device sales. The dominant pricing structure stratifies across premium, standard, and economy tiers differentiated by FDA clearance tier, after-sales service intensity, and algorithmic capability depth. Pricing pressure stems from Medicare Advantage capitation demanding granular cost accounting and unbundled service line items. Integrated delivery networks exhibit highest price sensitivity due to competitive metropolitan procurement, while direct-to-patient channels absorb premiums for convenience and adherence support.
Supply Chain Analysis
Upstream feedstock for electrochemical biosensors draws from precision substrate manufacturers concentrated in the United States, Germany, and Japan, with enzyme production anchored in captive facilities near Boston-Cambridge and Baden-Württemberg. Key inputs span electrochemical membranes, photodiode arrays for photoplethysmography, and edge inference chipsets. Single-source vulnerability sits with vertically integrated glucose strip producers controlling proprietary enzyme formulations. Distribution runs through pharmacy-centric retail chains, dedicated home health service networks, and direct-to-patient e-commerce portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-native platform vendors monetizing subscription data services without hardware dependency, requiring defensive repositioning around captive supply and service bundling.
For Market Incumbents: Build switching-cost moats through backward integration into electrochemical substrate production and exclusive home health agency service network contracts. Counter AI-native platform substitution by embedding algorithmic triage into hardware-software bundles that EHR systems cannot easily displace. Prioritize FDA Software as a Medical Device pathway investments to accelerate clearance timelines against emerging algorithm-only competitors. For New Entrants and Emerging Players: Broadband infrastructure gaps in rural United States counties and secondary European markets present underpenetrated white-space for asynchronous diagnostic kits with offline data capture. Pharmacy-centric retail placement at prescription points offers lowest customer acquisition cost for hypertensive patient segments. Target go-to-market partnerships with Medicare Advantage plans seeking capitated home monitoring expenditures outside hospital procurement channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telehealth platform vendors lacking FDA-cleared diagnostic hardware and dependent on third-party device APIs for data ingestion. Five-to-ten year viability hinges on reimbursement code expansion beyond remote therapeutic monitoring into AI triage and automated escalation services. Watch for CMS reimbursement decisions on algorithm-only diagnostic codes as inflection signal for platform margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Abbott Diagnostics leverages accelerated pathways to compress commercialization timelines for algorithm-driven glucose monitoring tools. |
| Hospital System Partnership | Philips Healthcare bundles device installation with clinician training to secure exclusive chronic disease management contracts. |
| Reimbursement Strategy | Omron Healthcare targets Medicare Advantage capitation structures to capture hypertensive patient traffic at pharmacy prescription points. |
| Software Companion Development | Telehealth platforms integrate AI triage with automated escalation protocols to expand margin pools beyond hardware sales. |
| CE Marking Pathway | EU MDR conformity investments enable European distribution despite certification burdens from parallel GDPR privacy obligations. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, home health agency operations directors, and GPO contracts managers, then refined against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement code databases, hospital procurement transaction records, and SEC 10-K disclosures from diversified health technology conglomerates. Bottom-up device shipment and consumable revenue estimates triangulated with top-down market sizing from payer expenditure data and integrated delivery network capitation disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, end user archetype, technology maturity, and service intensity. CAGRs derived from regression analysis of historical Medicare reimbursement expansion rates, FDA clearance timeline compression, and broadband infrastructure penetration curves. Industry-specific forecast inputs incorporated remote therapeutic monitoring code utilization trends and Software as a Medical Device submission volume trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native platform vendors bypassing hardware entirely would shift outcomes toward subscription-only margin pools. Cross-checking against CMS Medicare expenditure benchmarks and FDA 510(k) clearance databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Neuro-Monitoring System Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market