
 Neonatal and Fetal Monitors Market | 2026-2036
Neonatal and Fetal Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal and Fetal Monitors Market Foresight
Modular monitor configurations paired with disposable sensor bundles is broadening buyer choice across hospital systems. GE Healthcare leverages its imaging heritage to dominate integrated cardiotocograph platforms in North American academic medical centers. Koninklijke Philips N.V. anchors its position through deep channel control in European maternity networks. Medtronic specializes in invasive hemodynamic extensions for high-risk neonatal intensive care units.
Neonatal and fetal monitors comprise electronic devices that track fetal heart rate, uterine contractions, neonatal blood oxygen saturation, and electrocardiographic signals through ultrasound transducers, Doppler probes, pulse oximetry sensors, and surface electrodes, typically operating at 1-2 MHz ultrasound frequencies with SpO2 accuracy within 2-3% for clinical decision support. These systems serve to reduce perinatal mortality, detect fetal distress, and guide obstetric intervention timing in delivery suites and NICU settings. Fetal heart rate monitors occupy the largest installed base among device types, while wireless monitors represent the fastest-expanding category as labor-delivery units seek maternal mobility. Hospitals command the dominant procurement channel, though home care providers are gaining traction for remote postpartum assessment programs.
The FDA enforces premarket notification and quality system regulations for neonatal pulse oximeters and cardiotocographs under 21 CFR 870, directly shaping product development timelines and clinical validation requirements for US market access. The EU Medical Device Regulation and CE marking framework, administered by notified bodies under EMA-aligned standards, impose post-market surveillance and clinical evidence obligations that filter which device configurations reach European maternity wards. Stakeholders must monitor evolving interoperability mandates between monitor platforms and electronic health record systems as health systems consolidate procurement around integrated data architectures.
Market Dynamics
Wireless telemetry architectures are compressing the installed base of wired cardiotocograph systems as US hospital maternity wards prioritize maternal mobility during labor. This infrastructure transition is forcing incumbents to recalibrate hardware-software bundling strategies and sensor economics.
Growth Catalysts
- FDA premarket pathway refinement:Streamlined 510(k) review for wireless fetal monitoring platforms accelerates hospital procurement cycles in the United States. Maternity wards leverage this regulatory clarity to justify capital equipment replacement.
- German university hospital procurement concentration:Academic medical centers in Germany anchor volume demand for integrated cardiotocograph systems. Their purchasing power shapes regional vendor pricing and service bundling norms.
- Remote postpartum assessment programs:Home care providers deploy pulse oximetry-enabled monitoring kits for neonatal discharge follow-up. This channel expansion extends device utilization beyond traditional hospital settings.
Market Restraints
- Pulse oximetry sensor cost volatility:Disposable SpO2 sensors constitute recurring opex burdens for NICU operations. Price sensitivity intensifies as hospital systems consolidate purchasing.
- EU MDR clinical evidence requirements:Post-market surveillance obligations under the Medical Device Regulation extend validation timelines for European market entry. Smaller manufacturers face resource strain.
- Ultrasound transducer technical limitations:Signal artifact during maternal movement degrades fetal heart rate tracing reliability. This constrains wireless system performance in active labor scenarios.
Strategic Opportunities
- Indian tertiary maternity network expansion:Government-funded hospital infrastructure programs create procurement windows for mid-range cardiotocograph systems. Domestic manufacturing incentives reduce import duty exposure.
- AI-enabled waveform interpretation:Machine learning algorithms analyzing fetal heart rate patterns converge with cloud-based telemetry platforms. This technology pairing enables predictive distress alerting.
- Direct-to-provider sensor subscription models:Manufacturers bypass traditional distributor markups through recurring revenue arrangements with hospital systems. Channel restructuring captures lifetime value.
Industry Challenges
- Biomedical engineering talent scarcity:NICU device specialization requires hybrid expertise in neonatal physiology and signal processing. Workforce gaps delay product development cycles.
- EHR interoperability certification complexity:Health system consolidation demands seamless data exchange between monitor platforms and electronic record architectures. Integration testing extends deployment timelines.
- Legacy wired system stranded asset risk:Hospitals face write-down pressures from depreciated cardiotocograph installations. Capital planning friction slows wireless upgrade decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal and Fetal Monitors Market |
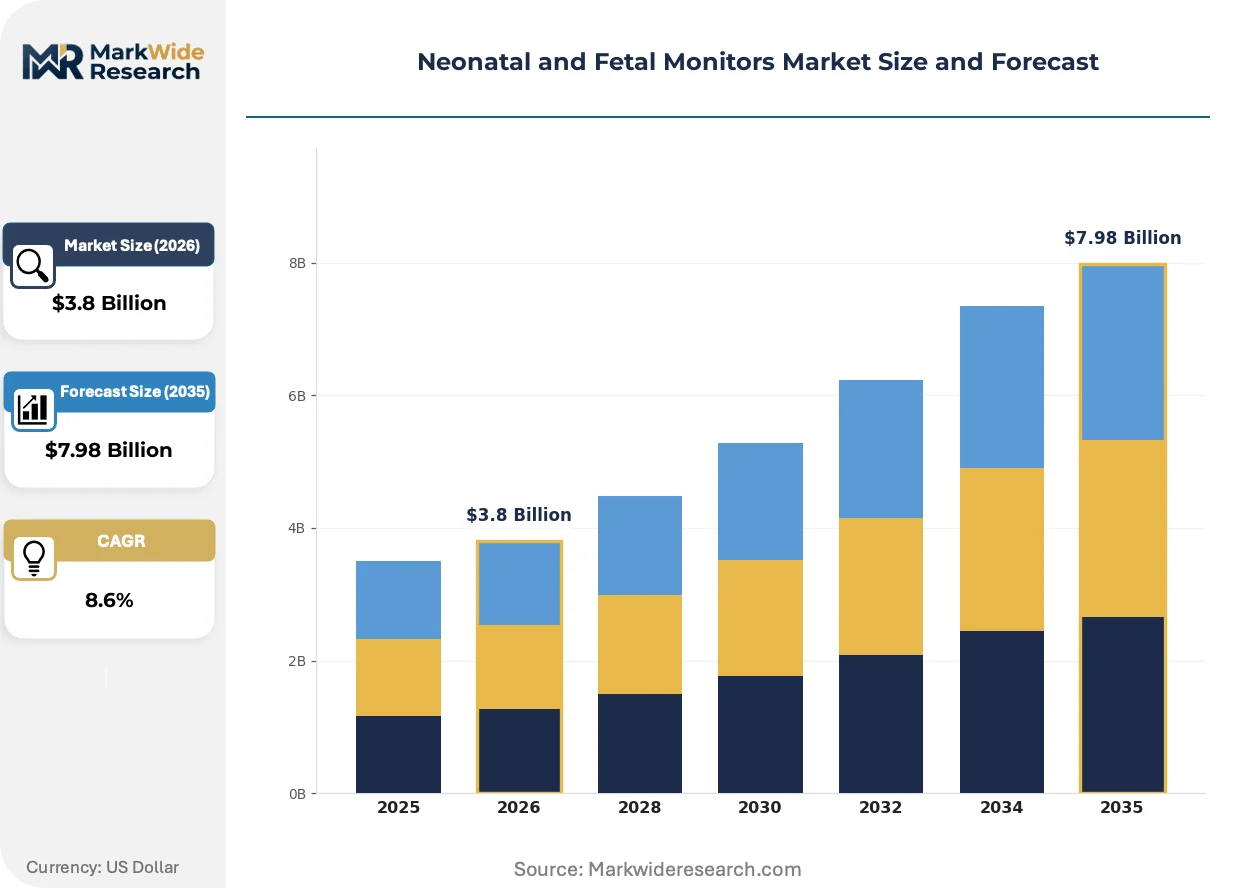
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Fetal Heart Rate Monitors, Neonatal Pulse Oximeters, Cardiotocographs, Wireless Monitors End User: Hospitals, Maternity Wards, Outpatient Clinics, Home Care Providers Application: Fetal Monitoring, Neonatal Care, Labor Management, Postpartum Assessment Technology: Ultrasound, Doppler, Infrared, ECG |
| Companies Covered | Koninklijke Philips N.V., GE Healthcare, Medtronic, Siemens Healthineers, Drägerwerk AG & Co. KGaA, Becton Dickinson, Masimo Corporation, Fisher & Paykel Healthcare, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal and Fetal Monitors Market Shifts & Advancements
Digital signal processing advances are compressing the form factor and power requirements of fetal monitoring hardware. These technical shifts enable new deployment modalities that reshape competitive positioning.
Sensor fusion architectures combining ultrasound Doppler with pulse oximetry and electrocardiographic inputs is unifying multi-parameter monitoring into single-platform configurations. Labor-delivery units in academic medical centers adopt these integrated systems to reduce bedside clutter and training overhead. The technology is unifying previously separate device categories, compressing vendor addressable markets while raising switching costs.
EU MDR post-market surveillance mandates require systematic clinical follow-up for cardiotocograph and pulse oximetry devices already in distribution. Manufacturers must maintain vigilance databases and periodic safety update reports. High-risk device classifications in Germany and France impose disproportionate compliance burdens on smaller competitors.
Hospital system procurement consolidation is compressing vendor negotiation leverage as integrated delivery networks centralize maternity device purchasing. Independent community hospitals lose direct supplier relationships as contracting authority migrates to regional headquarters. This concentration is most visible in the United States, where health system mergers have reduced the number of independent decision-makers by half over the past decade.
Neonatal and Fetal Monitors Market Segmentation
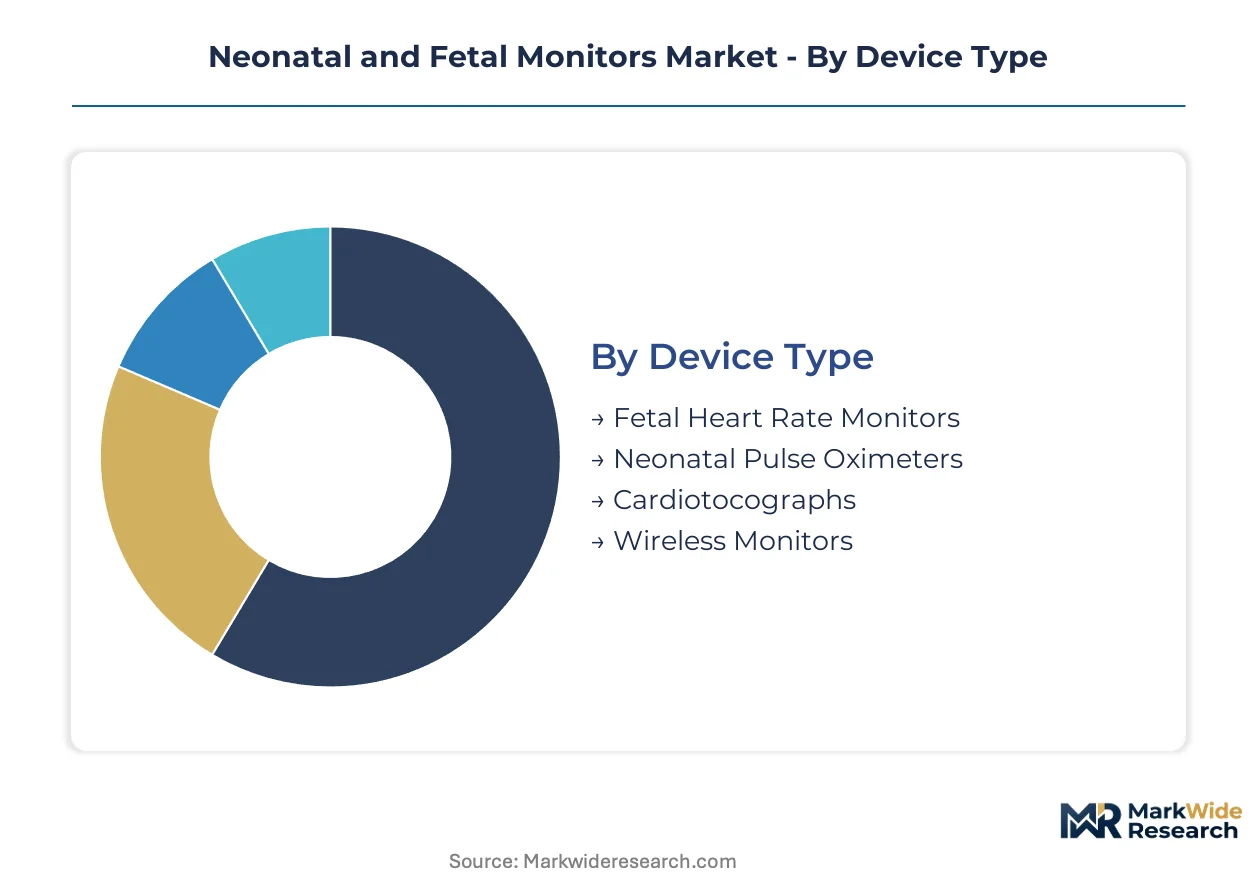
Neonatal and fetal monitor segmentation reveals how clinical workflows and procurement economics fragment demand across device configurations. Understanding these divisions illuminates where technology convergence creates bundling opportunities versus where specialization preserves premium pricing.
Device Type:
Standardization dominates high-volume categories while modular architectures enable customization for academic medical centers and specialized NICUs.
- Fetal Heart Rate Monitors:Ultrasound transducer-based systems operating at 1-2 MHz frequencies generate continuous cardiotocographic tracings. Demand concentrates in United States hospital maternity wards where FDA 510(k) pathway clarity accelerates replacement cycles for wired installations.
- Neonatal Pulse Oximeters:Photoplethysmography sensors with SpO2 accuracy within 2-3% enable non-invasive oxygen saturation monitoring in premature infant populations. German university hospitals anchor procurement volumes as these institutions prioritize integrated monitoring platforms with disposable sensor bundles.
- Cardiotocographs:Multi-parameter systems combining fetal heart rate and uterine contraction measurement.
- Wireless Monitors:Telemetry-enabled platforms supporting maternal mobility during active labor.
Leading the category by volume: Fetal Heart Rate Monitors. Growing fastest: Wireless Monitors.
End User:
Procurement authority concentrates differently across settings, with health system consolidation reshaping vendor access patterns.
- Hospitals:Integrated delivery networks centralize capital equipment purchasing for labor-delivery units and NICUs. United States health system mergers have halved independent decision-makers over the past decade, compressing supplier negotiation leverage.
- Maternity Wards:Specialized obstetric units within larger hospital structures command dedicated cardiotocograph installations. German academic medical centers shape regional pricing norms through concentrated procurement volumes.
- Outpatient Clinics:Limited-scope facilities conducting antenatal surveillance with portable Doppler systems.
- Home Care Providers:Remote postpartum assessment programs deploy pulse oximetry-enabled kits for neonatal discharge follow-up.
Hospitals dominate absolute procurement spend. Home Care Providers climb the fastest as reimbursement shifts favor remote monitoring.
Application:
Workflow integration requirements vary sharply across clinical phases, determining whether standalone or multi-parameter configurations prevail.
- Fetal Monitoring:Continuous or intermittent surveillance of fetal heart rate patterns and uterine activity during gestation and delivery. United States maternity wards prioritize wireless telemetry architectures that enable maternal mobility without signal loss.
- Neonatal Care:Intensive monitoring of premature or compromised infants in specialized NICU environments. German university hospitals anchor demand for invasive hemodynamic extensions and multi-parameter integration.
- Labor Management:Real-time guidance for obstetric intervention timing during active delivery.
- Postpartum Assessment:Transition-period monitoring extending from delivery suite to home settings.
Fetal Monitoring commands the largest installed base. Postpartum Assessment sees the steepest expansion trajectory as remote care programs proliferate.
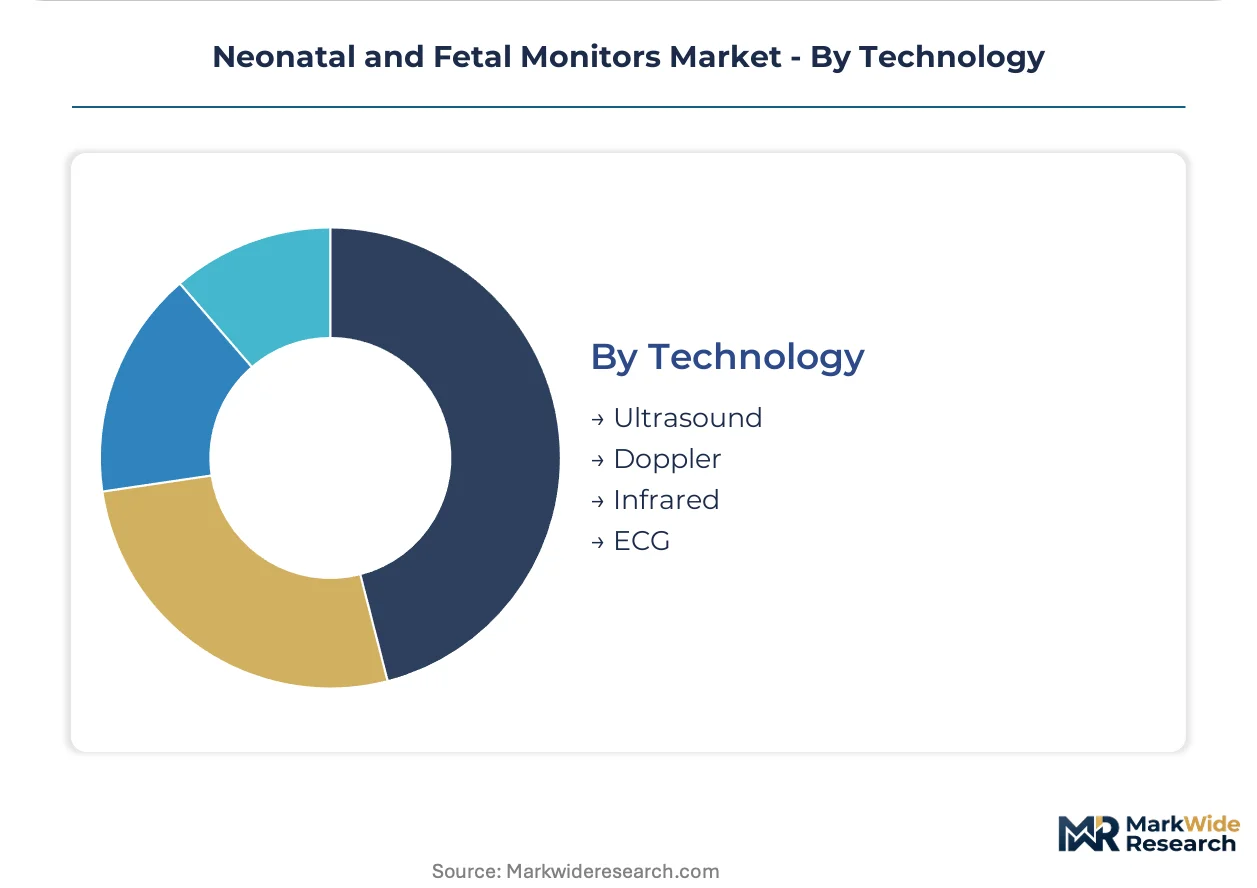
Technology:
Underlying sensing modalities compete on signal fidelity, artifact rejection, and integration complexity within unified platforms.
- Ultrasound:Piezoelectric transducers emitting 1-2 MHz frequencies detect fetal cardiac motion through maternal abdominal tissue. Signal artifact during maternal movement constrains wireless system reliability in active labor scenarios.
- Doppler:Frequency-shift detection enables continuous fetal heart rate acquisition with compact, portable form factors. United States outpatient clinics favor these systems for antenatal surveillance given lower capital requirements.
- Infrared:Photoplethysmography-based pulse oximetry for transcutaneous oxygen saturation measurement.
- ECG:Surface electrode configurations capturing neonatal electrocardiographic signals for arrhythmia detection.
Ultrasound maintains the dominant technology position. Wireless Doppler configurations gain share fastest as maternal mobility priorities reshape labor-delivery unit specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States while consumption spreads across mature healthcare systems in Europe and North America. Asia-Pacific markets absorb mid-range equipment through government-funded hospital expansion programs.
United States
Hospital maternity wards drive replacement demand for wireless cardiotocograph systems as labor-delivery units prioritize maternal mobility. FDA 510(k) pathway refinements under 21 CFR 870 accelerate regulatory clearance timelines for new platform submissions. Academic medical centers in Boston and the Research Triangle anchor procurement volumes for integrated monitoring configurations.
Germany
University hospitals concentrate demand for high-parameter cardiotocograph systems with invasive hemodynamic extensions. EU MDR post-market surveillance obligations extend validation timelines but create compliance barriers that favor established manufacturers. The Baden-Württemberg medical technology cluster around Stuttgart supports sensor manufacturing and subsystem integration for domestic producers.
China
Government-funded tertiary maternity network expansion creates procurement windows for mid-range fetal monitoring platforms. NMPA medical device registration requirements under Category II and III classifications shape product localization strategies. Manufacturing concentrates in the Yangtze River Delta with assembly operations serving domestic hospital procurement and regional export markets.
India
Public hospital infrastructure programs under the National Health Mission expand installed base for portable Doppler and pulse oximetry systems. CDSCO medical device rules impose import licensing requirements that incentivize domestic manufacturing partnerships. Procurement concentrates in Maharashtra and Karnataka where state government medical colleges anchor regional tender volumes.
Japan
Aging demographics and declining birth rates compress absolute demand for fetal monitoring equipment while shifting focus toward high-acuity NICU configurations. PMDA pharmaceutical and medical device agency reviews emphasize clinical evidence standards for newborn care technologies. Tokyo and Osaka metropolitan hospital networks maintain premium-tier procurement for multi-parameter integrated platforms.
Neonatal and Fetal Monitors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the Neonatal and Fetal Monitors Market. Three to five multinational healthcare technology groups dominate integrated platform sales through direct hospital relationships and long-term service contracts. Strategic archetypes separate imaging heritage conglomerates, dedicated patient monitoring specialists, and invasive critical care device manufacturers. Competitive moves center on sensor ecosystem lock-in through disposable bundle economics and EHR interoperability certification to defend installed base positions.
Within the imaging-heritage tier, GE Healthcare and Siemens Healthineers exemplify diversified medical technology conglomerates leveraging diagnostic equipment relationships to cross-sell integrated monitoring platforms. Koninklijke Philips N.V. and Drägerwerk AG & Co. KGaA occupy positions as dedicated patient monitoring specialists with deep channel control in European and North American maternity networks. Medtronic represents the invasive critical care archetype, extending hemodynamic monitoring expertise from adult intensive care into high-risk neonatal applications. These three archetypes structure competitive dynamics around hardware-software bundling strategies, sensor subscription economics, and clinical workflow integration depth.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic |
| Siemens Healthineers |
| Drägerwerk AG & Co. KGaA |
| Becton Dickinson |
| Masimo Corporation |
| Fisher & Paykel Healthcare |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Photodiode and piezoelectric ceramic price indices cascade through neonatal monitor manufacturing into three-tier pricing structures across premium, standard, and economy levels. Hospital procurement consolidation in the United States and Germany compresses margin buffers as disposable sensor bundles absorb component cost volatility.
Pricing Analysis
Cost-down pressure on mid-range cardiotocograph systems accelerates because health system GPOs centralize maternity device contracting. Pricing stratifies across premium, standard, and economy tiers driven by FDA 510(k) certification grade and disposable sensor bundle economics. Price erosion runs through economy-tier portable Doppler units as Indian and Chinese domestic manufacturers expand capacity. Independent community hospitals exhibit highest price sensitivity; academic medical centers in Germany and Boston demonstrate lowest sensitivity due to research funding offsets.
Supply Chain Analysis
India's PLI scheme for medical electronics and China's NMPA localization mandates reshape component sourcing for pulse oximetry sensors and ultrasound transducers. Manufacturing concentrates in Germany's Baden-Württemberg cluster, China's Yangtze River Delta, and India's Maharashtra-Karnataka corridor. Supply chains draw from Malaysian photodiode foundries, Japanese piezoelectric ceramic suppliers, and Taiwanese semiconductor packaging houses. Single-source vulnerability in SpO2 LED emitters creates chokepoint exposure. Distribution runs through hospital GPO contracts and regional medical device distributors with service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into disposable sensor manufacturing represents the decisive upstream lever as recurring revenue economics dominate maternity ward procurement. Incumbents and challengers race to capture lifetime value through captive supply of pulse oximetry probes and ultrasound gel bundles.
For Market Incumbents: Deepen backward integration into photoplethysmography sensor manufacturing to defend margin position against emerging Asian component suppliers. Lock in academic medical center installed bases through EHR interoperability certification investments that raise switching costs for wireless telemetry platforms.
For New Entrants and Emerging Players: Direct-to-hospital SaaS subscription models bypass traditional distributor markups and capture recurring revenue from mid-tier Indian maternity networks. Target Maharashtra state medical college tenders with portable Doppler systems priced below GE and Philips entry points. Lead with AI-enabled waveform interpretation as the differentiated software companion.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap patient monitoring specialists with FDA 510(k) clearances and stranded European CE MDR documentation assets. Long-term viability hinges on sensor ecosystem lock-in and cloud telemetry platform recurring revenue. Watch FDA premarket notification backlog clearance rates as inflection signal for US replacement demand timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Regulatory clarity accelerates hospital capital equipment replacement cycles in United States maternity wards. |
| CE Marking Pathway under EU MDR | Post-market surveillance compliance filters smaller competitors from German university hospital procurement. |
| Hospital System Partnership | Integrated delivery network consolidation demands seamless EHR data exchange for wireless telemetry platforms. |
| Software Companion Development | AI-enabled fetal heart rate pattern analysis converges with cloud telemetry for predictive distress alerting. |
| Reimbursement Strategy | Remote postpartum assessment program coding determines home care provider pulse oximetry kit adoption. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this neonatal and fetal monitors analysis. Primary interviews with hospital biomedical engineers, GPO contracts managers, NICU clinicians, and pulse oximetry sensor procurement leads combined with FDA 510(k) databases, EU MDR notified body documentation, and hospital capital equipment expenditure records. Bottom-up installed base modeling and top-down healthcare technology spending triangulation validated segment-level outputs.
Data-stream reconciliation across device type, end user, application, and technology segmentation dimensions produced volume and value estimates over the projection horizon. CAGRs derived from logistic diffusion modeling of wireless telemetry adoption curves and replacement cycle analysis of wired cardiotocograph installed bases. SpO2 sensor disposable revenue streams and AI software companion attach rates informed recurring revenue projections.
Inputs from FDA premarket notification databases and German BfArM vigilance reports were available through the study window; gaps in Chinese NMPA Category II registration timelines introduce uncertainty bands around Asia-Pacific adoption trajectories. Forecasts reflect assumptions regarding health system consolidation pace and EU MDR clinical evidence requirement enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market