
 Urine Output Monitoring Systems Market | 2026-2036
Urine Output Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Urine Output Monitoring Systems Market Intelligence
The U.S. Food and Drug Administration's (FDA) stringent post-market surveillance requirements for medical devices is consolidating market access for firms with robust quality management systems. Cardinal Health leverages its extensive hospital distribution network to secure large contracts. Becton, Dickinson and Company competes on the integration of its monitoring systems with broader patient data platforms. Meanwhile, RenalSense Ltd. specializes in real-time sensor technology for early detection of acute kidney injury.
Urine output monitoring systems are medical devices designed for the continuous, automated measurement of a patient's urine flow rate and volume. These systems often incorporate ultrasonic sensors or gravimetric scales to provide real-time data, replacing manual methods. Their primary purpose is to enable clinicians in critical care settings to precisely manage fluid balance and detect early signs of renal dysfunction. Electronic systems with automated data logging are supplanting traditional manual gauges within intensive care units.
Compliance with standards like ISO 13485 is fundamental for manufacturers seeking market entry across geographies. The European Union's CE marking, governed by the Medical Device Regulation (MDR), and the FDA's 510(k) clearance process in the United States dictate stringent requirements for clinical validation. Key decisions for vendors revolve around prioritizing highly integrated systems versus cost-effective disposables to capture different hospital budget segments.
Market Dynamics
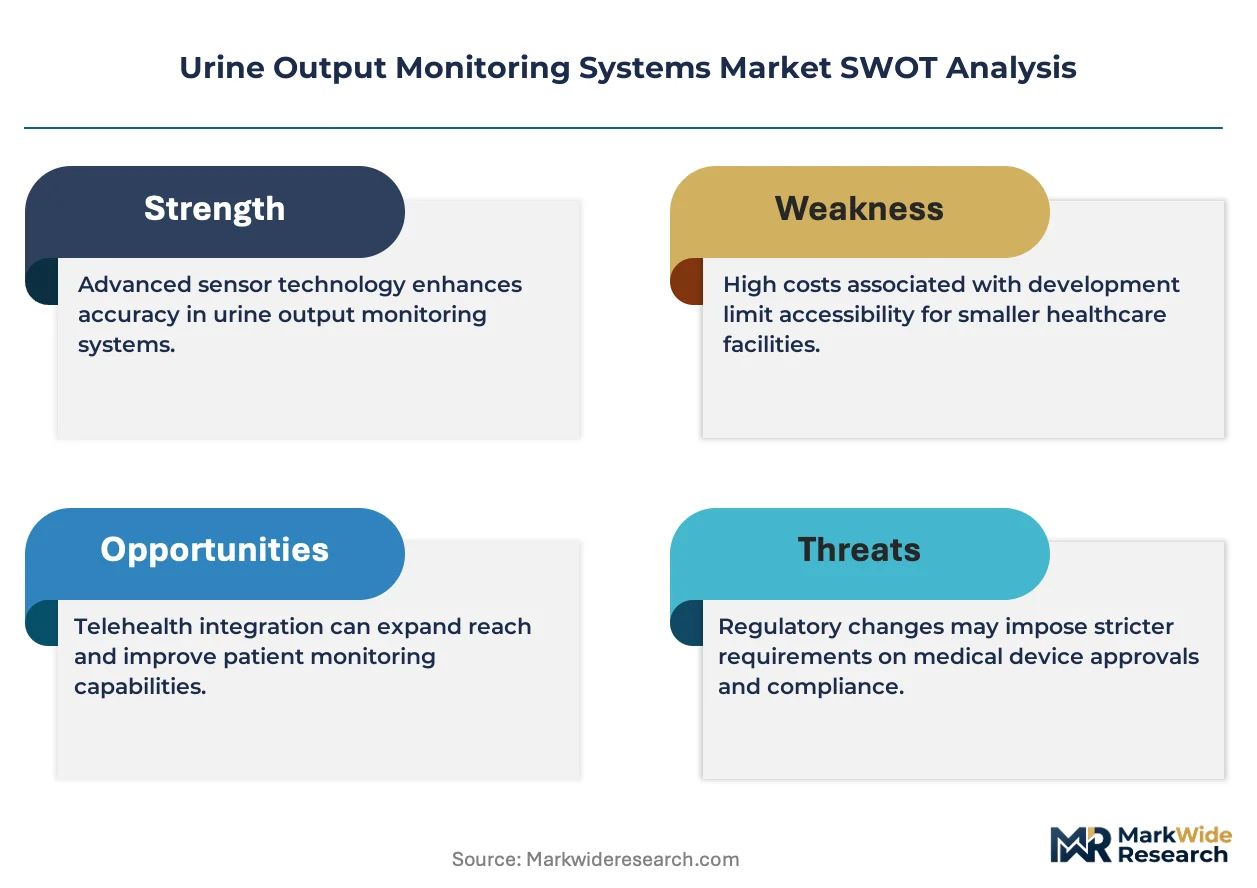
The central structural force shaping the market is the regulatory-driven push for data integration and clinical accuracy. Mandates like the European Union's MDR are compelling device manufacturers to improve data connectivity with hospital EHR systems and validate performance against stringent clinical benchmarks.
Growth Catalysts
- EHR Integration:The drive for interoperability with Electronic Health Record systems allows for automated charting, reducing nursing workload and minimizing transcription errors, a key factor for hospital IT departments in the United States.
- EU Medical Device Regulation:The MDR elevates requirements for clinical evidence and post-market surveillance, favoring manufacturers with strong quality management systems and creating a higher barrier to entry.
- Rising AKI Incidence:An increasing prevalence of acute kidney injury in aging populations, particularly within intensive care units in developed nations like Japan and Germany, necessitates more precise and continuous renal monitoring.
Market Restraints
- High Initial Cost:The significant capital investment required for automated urine output monitoring systems compared to traditional manual collection bags remains a major adoption barrier for hospitals with constrained budgets.
- Interoperability Challenges:Lack of standardized communication protocols across different medical device manufacturers creates significant hurdles for integrating new monitoring systems with existing hospital IT infrastructure and patient data platforms.
- Reimbursement Ambiguity:Inconsistent or non-existent reimbursement codes for the use of advanced, continuous monitoring systems in some healthcare systems limits financial incentives for hospitals to upgrade from manual methods.
Strategic Opportunities
- Emerging Market Expansion:Significant opportunity exists in expanding critical care infrastructure in countries like Brazil and India, where the adoption of advanced patient monitoring technologies is still in its early stages.
- Non-ICU Application Development:Systems can be adapted for use in lower-acuity settings such as post-operative recovery units or general wards to monitor at-risk patients, expanding the addressable market beyond the ICU.
- Predictive Analytics Integration:Combining urine output data with other physiological parameters through AI algorithms offers the potential to develop predictive models for early AKI detection, creating significant value for clinicians.
Industry Challenges
- Data Security Compliance:Ensuring that connected devices comply with stringent data privacy regulations like HIPAA in the U.S. and GDPR in Europe presents a significant software development and validation challenge.
- Clinical Staff Training:Effective implementation requires comprehensive training for nursing and clinical staff to ensure correct usage, data interpretation, and response to system alerts, representing an operational burden for hospitals.
- Legacy System Integration:Integrating new monitoring hardware and software with decades-old legacy patient data management systems in many hospitals is technically complex, costly, and time-consuming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urine Output Monitoring Systems Market |
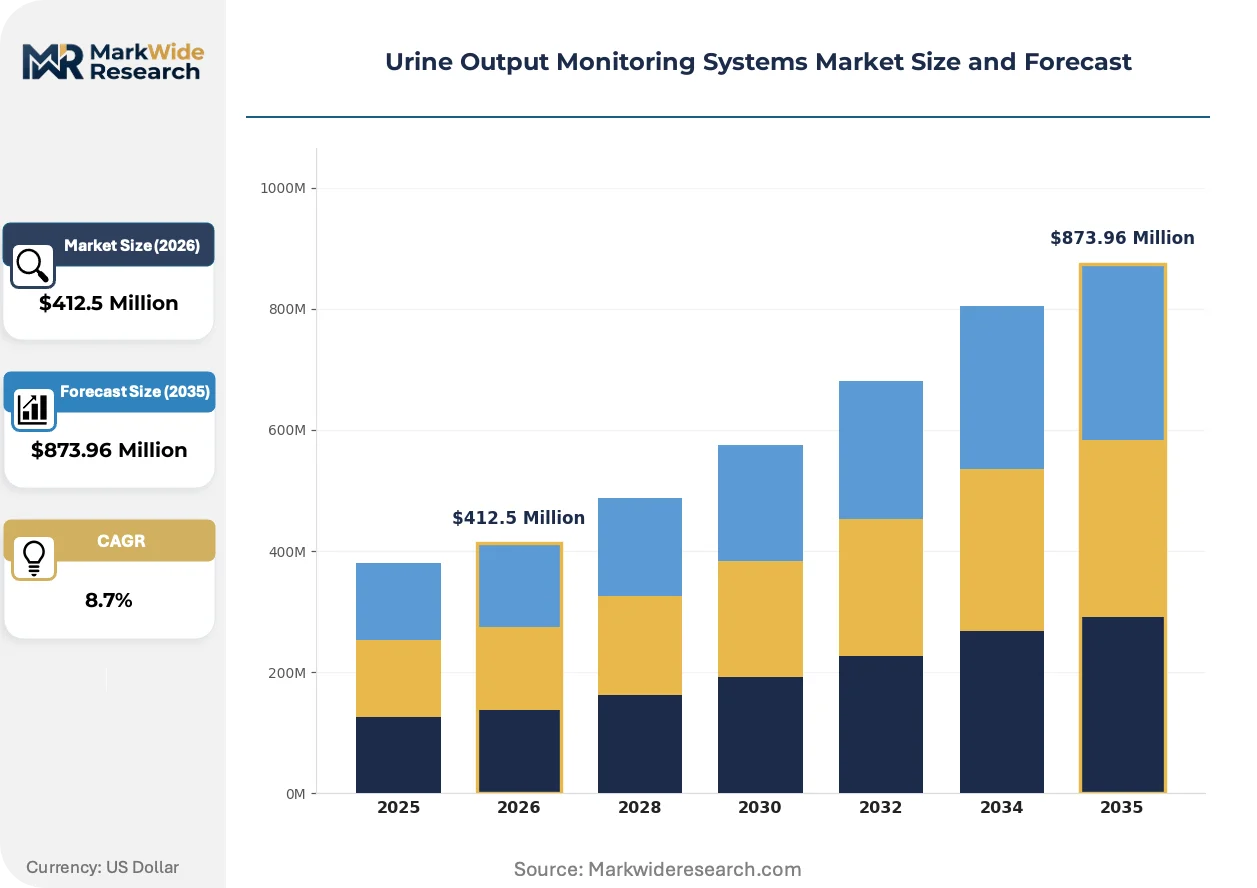
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Systems, Gravimetric Devices, Optical Sensors, Disposable Catheters, Manual Gauges Application: Critical Care, Postoperative Monitoring, Renal Function Assessment, Fluid Balance Tracking, Pediatric Care End User: Intensive Care Units, Dialysis Centers, Ambulatory Clinics, Long-term Care Facilities, Surgical Centers Technology: Ultrasonic Sensors, Capacitance Sensors, Infrared Detectors, Microfluidic Devices, Pressure Transducers |
| Companies Covered | Roche Holding AG, Biometrix, Navamedic ASA, FIZE Medical, Future Path Medical Holding Company LLC, RenalSense Ltd., Cardinal Health, Becton, Dickinson and Company, Potrero Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urine Output Monitoring Systems Market Strategic Shifts & Innovations
A fundamental shift is occurring from simple fluid measurement to predictive, data-driven renal function management. This evolution is driven by technological advancements in sensor technology, stricter regulatory frameworks for device connectivity, and new value-based procurement models in healthcare.
Real-time sensor technology, including ultrasonic and gravimetric methods, provides a continuous stream of data without manual intervention. Critical care units in North America and Europe are rapidly adopting these automated systems. This technological shift is consolidating the market around platforms that provide early, actionable insights into renal stress, reducing reliance on intermittent and labor-intensive manual measurements.
Stricter cybersecurity requirements from regulators, including the U.S. Food and Drug Administration, are reshaping device development. These rules mandate that manufacturers incorporate robust defenses against data breaches and unauthorized network access into their product design. Systems with wireless data transmission capabilities are most affected, forcing vendors to invest in secure software development and continuous post-market monitoring.
Hospital purchasing models are increasingly influenced by value-based healthcare principles, moving beyond initial unit price. Hospital networks prioritize systems that demonstrate a clear, documented impact on improving patient outcomes, such as reducing the incidence of acute kidney injury or shortening ICU stays. This demand-side shift is most visible in large, integrated delivery networks across the United States.
Urine Output Monitoring Systems Market Segmentation
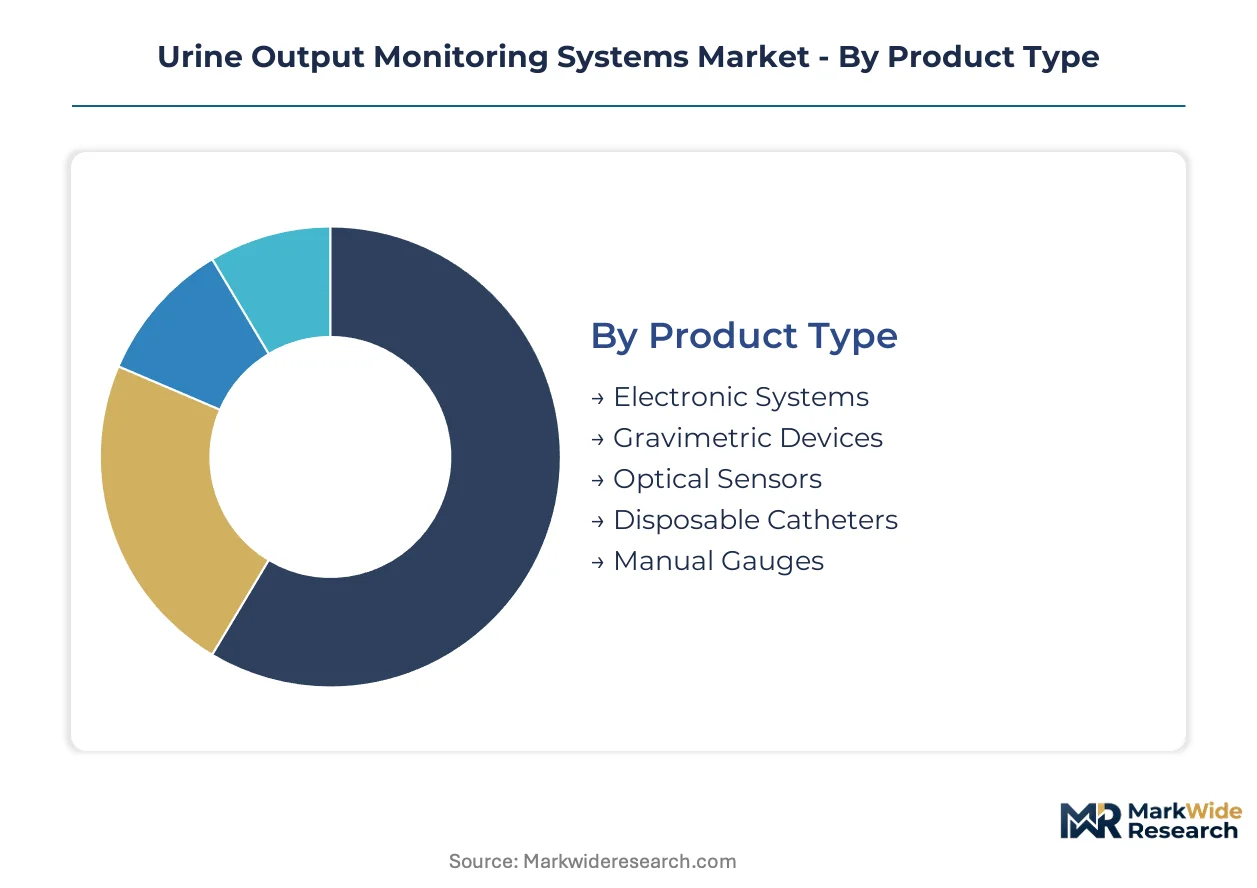
Understanding the diverse applications and technological underpinnings of urine output monitoring systems is essential for market participants. This segmentation analysis delineates the various product types, clinical applications, end-user environments, and core technologies driving market differentiation. Precise categorization reveals specific demand patterns and areas for innovation.
Product Type:
Product types in urine output monitoring systems range from advanced automated devices to established manual tools, reflecting varying levels of sophistication and data integration capabilities.
- Electronic Systems:These systems integrate sensors and digital interfaces for continuous, automated measurement of urine volume and flow rate. Demand concentrates in intensive care units across the United States, driven by the push for seamless EHR integration and reduced nursing workload.
- Gravimetric Devices:Gravimetric devices utilize precise weighing mechanisms to accurately measure urine output, often providing real-time data directly to patient monitors. Hospitals in Germany prioritize these systems for their high accuracy in critical care settings, where fluid balance is paramount for patient outcomes.
- Optical Sensors:Optical sensors detect changes in fluid levels or flow using light-based technology, offering non-contact measurement in specialized applications.
- Disposable Catheters:Disposable catheters facilitate urine collection and drainage, often integrating with monitoring systems for temporary or single-use patient management.
- Manual Gauges:Manual gauges represent traditional collection methods, relying on visual inspection and manual recording of urine volume by clinical staff.
Mature deployment sits with Manual Gauges. Newer deployment is concentrated in Electronic Systems.
Application:
The clinical utility of urine output monitoring systems spans a spectrum of patient care scenarios, each demanding specific functionalities and data precision.
- Critical Care:Critical care applications involve continuous, real-time monitoring of urine output for patients in intensive care units, often with automated data logging. Demand in the United Kingdom is high for these systems, enabling rapid clinical intervention for critically ill patients requiring precise fluid management.
- Renal Function Assessment:Renal function assessment utilizes continuous urine output data to detect early indicators of acute kidney injury and other renal dysfunctions. Hospitals in Japan prioritize these systems for early detection and proactive management of kidney-related complications in an aging population.
- Postoperative Monitoring:Postoperative monitoring tracks urine output in recovery units to assess kidney function and fluid status following surgical procedures.
- Fluid Balance Tracking:Fluid balance tracking involves comprehensive measurement of fluid intake and output, crucial for managing patients with hydration imbalances.
- Pediatric Care:Pediatric care applications require highly sensitive and accurate urine output monitoring systems adapted for the specific physiological needs of children.
Critical Care represents the largest volume application. Pediatric Care applications are expanding most quickly.
End User:
The operational environments where urine output monitoring systems are deployed significantly influence device requirements and integration priorities.
- Intensive Care Units:Intensive Care Units (ICUs) rely on continuous, automated urine output monitoring systems for critically ill patients requiring precise fluid management. Hospitals in France heavily invest in these solutions to enhance patient safety and streamline nursing workflows within high-acuity settings.
- Surgical Centers:Surgical centers utilize urine output monitoring for patients during and immediately after operations, assessing renal function and fluid status post-anesthesia. Demand in Canada is rising as these centers prioritize early detection of postoperative complications and efficient patient recovery.
- Dialysis Centers:Dialysis centers use these systems to monitor fluid removal and balance in patients undergoing renal replacement therapies.
- Ambulatory Clinics:Ambulatory clinics employ simpler urine output monitoring methods for diagnostic purposes or short-term patient observation outside hospital settings.
- Long-term Care Facilities:Long-term care facilities use these systems for chronic patient management, focusing on fluid balance and early detection of urinary tract issues.
Intensive Care Units demonstrate the highest penetration of advanced systems. Long-term Care Facilities represent a significant opportunity for future adoption.
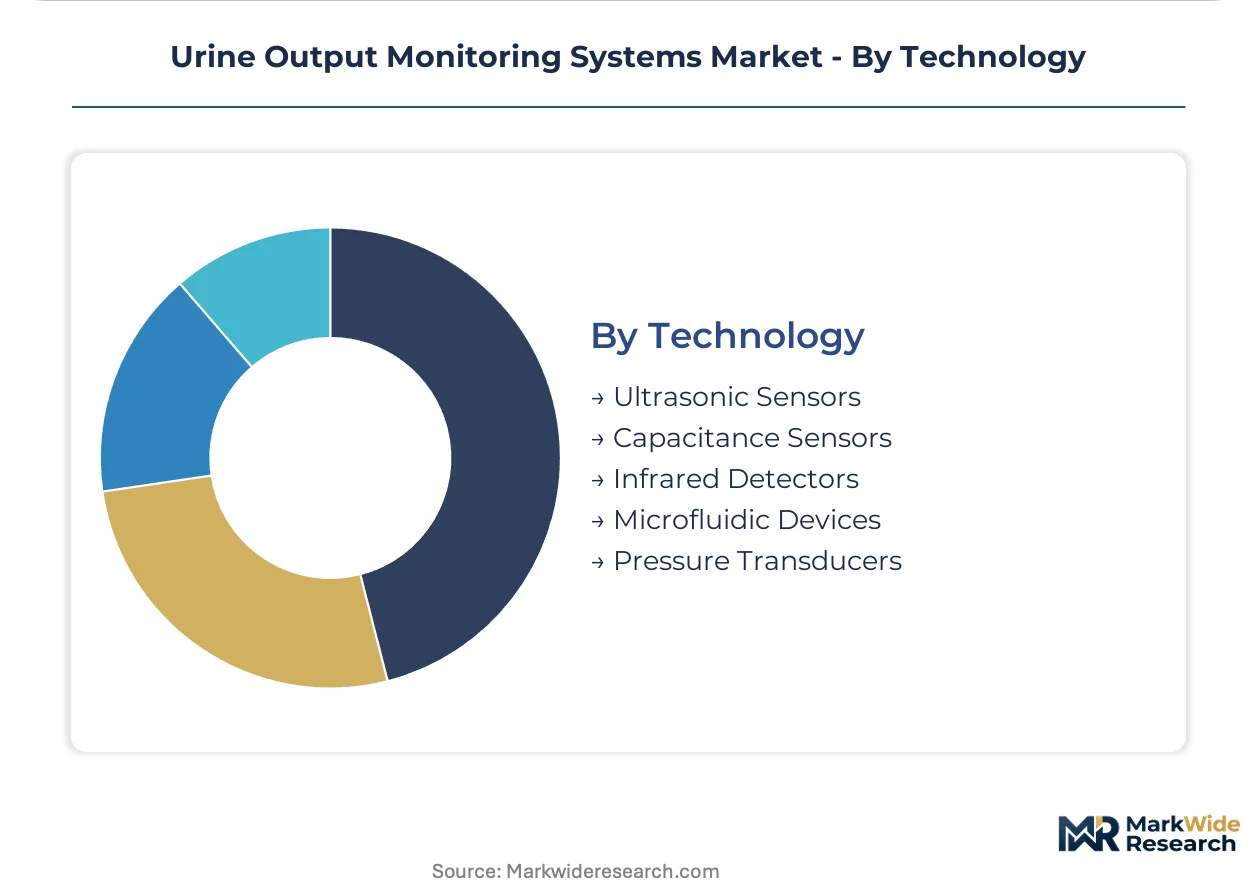
Technology:
The core sensing mechanisms employed in urine output monitoring systems underpin their accuracy, real-time capabilities, and integration potential with broader platforms.
- Ultrasonic Sensors:Ultrasonic sensors use sound waves to non-invasively measure fluid levels and flow rates, providing continuous data without direct contact with urine. Hospitals in Australia are increasingly adopting this technology for its accuracy and reduced risk of contamination in critical care environments.
- Microfluidic Devices:Microfluidic devices enable precise, small-volume measurements of urine output, often integrating lab-on-a-chip capabilities for advanced diagnostics. Research institutions in South Korea are exploring these devices for highly sensitive early detection of biomarkers related to kidney injury.
- Capacitance Sensors:Capacitance sensors detect changes in electrical capacitance caused by varying fluid levels, offering continuous volume measurement.
- Infrared Detectors:Infrared detectors use light absorption or reflection principles to monitor fluid presence and levels, particularly useful in automated systems.
- Pressure Transducers:Pressure transducers convert fluid pressure into electrical signals, allowing for continuous monitoring of urine flow dynamics in specific applications.
Ultrasonic Sensors are widely implemented due to their non-invasive nature. Microfluidic Devices hold significant promise for future diagnostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for urine output monitoring systems concentrates significantly in developed healthcare markets. These regions prioritize advanced patient monitoring technologies to enhance clinical outcomes and streamline critical care workflows. Hospital investments in sophisticated fluid management solutions are particularly strong.
United States
Hospital investments in advanced patient monitoring technologies drive demand for urine output systems. The FDA's stringent post-market surveillance requirements consolidate market access for firms with robust quality management systems. Major medical technology hubs like Boston and San Francisco are centers for innovation in integrated monitoring platforms.
Germany
High accuracy in critical care settings makes gravimetric devices a priority for hospitals in Germany. The European Union's MDR elevates standards for device accuracy and data connectivity across the nation. Clinical research institutions in Munich and Berlin are advancing real-time sensor technology for renal function assessment.
Japan
An increasing prevalence of acute kidney injury in Japan's aging population necessitates more precise renal monitoring. PMDA clearance processes dictate stringent requirements for clinical validation of new medical devices. Advanced medical equipment manufacturers in Tokyo are integrating predictive analytics into urine output monitoring solutions.
United Kingdom
Critical care applications demand continuous, real-time monitoring of urine output for critically ill patients in the United Kingdom. NHS procurement models increasingly favor systems demonstrating clear impact on patient outcomes. London's health tech ecosystem fosters partnerships between device manufacturers and hospital IT departments for EHR integration.
France
Intensive Care Units in France heavily invest in automated urine output monitoring systems to enhance patient safety. CE marking, governed by the EU MDR, mandates rigorous performance validation for medical devices. Biomedical engineering clusters in Lyon and Paris focus on developing highly integrated monitoring solutions.
Urine Output Monitoring Systems Market Key Industry Players
United States producers anchor one tier, focusing on broad hospital networks and advanced patient monitoring; European specialists hold another, emphasizing stringent regulatory compliance and high-precision devices. The market structure exhibits consolidation among established medical device companies, alongside fragmentation among niche sensor technology innovators. Strategic archetypes include large diversified healthcare conglomerates, specialized critical care solution providers, and dedicated real-time data platform developers. Companies are increasingly engaging in portfolio diversification and strategic partnerships to expand their market reach and enhance technological integration.
Within the specialized critical care solution providers, RenalSense Ltd. exemplifies innovation in real-time sensor technology for early acute kidney injury detection, positioning itself as a leader in precision diagnostics. Cardinal Health, a large diversified healthcare conglomerate, leverages its extensive hospital distribution network to secure significant contracts, underscoring its market access capabilities. Becton, Dickinson and Company competes on integrating its monitoring systems with broader patient data platforms, representing a focus on comprehensive data solutions that enhance clinical workflows and data interoperability across hospital systems.
| Leading Market Players |
|---|
| Roche Holding AG |
| Biometrix |
| Navamedic ASA |
| FIZE Medical |
| Future Path Medical Holding Company LLC |
| RenalSense Ltd. |
| Cardinal Health |
| Becton, Dickinson and Company |
| Potrero Medical |
| Others |
Cost & Logistics Intelligence
A clear performance gap exists between automated electronic systems and traditional manual gauges, manifesting in both pricing and the complexity of their respective supply chains. This divergence shapes procurement decisions and manufacturing strategies across the market.
Pricing Analysis
The volume-vs-margin split dictates pricing strategies, with high-volume disposable components priced transactionally and advanced electronic systems adopting a value-based model. Price differentiation stems from clinical validation levels, particularly for FDA 510(k) clearance, and integration capabilities with hospital EHR systems. Pricing softness affects manual gauges due to their commoditized nature. Hospital procurement departments represent the most price-sensitive buyers for basic systems, while critical care units prioritize advanced features regardless of initial cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage device logistics, ensuring timely delivery to hospitals. Geographic supply concentration for electronic components centers on East Asia, while specialized sensor manufacturing occurs in Germany and the United States. Raw material dependencies include microcontrollers, specialized plastics for disposables, and precision metal alloys for gravimetric sensors. Single-source vulnerability for specific sensor technologies presents a structural risk. The distribution model for advanced systems often involves direct sales teams and specialized medical device distributors to hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with automated electronic systems rapidly displacing legacy manual methods for urine output monitoring.
For Market Incumbents:Cement market leadership by investing heavily in AI-driven predictive analytics for early AKI detection. Deepen vertical integration into sensor manufacturing to mitigate supply chain risks for critical components. The threat of niche innovators with superior real-time data platforms requires continuous R&D in software and connectivity. Prioritize obtaining CE marking under the EU MDR to ensure broad market access.
For New Entrants and Emerging Players:Begin with targeting underpenetrated segments like long-term care facilities with cost-effective, easy-to-use automated systems. Focus on developing non-ICU application development for post-operative recovery units. A strong go-to-market angle involves emphasizing simplified user interfaces and seamless integration with existing, less complex EMR systems, particularly in smaller hospitals and clinics.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized critical care solution providers given the increasing regulatory push for data integration and clinical accuracy. Long-term viability rests on platforms offering comprehensive fluid management solutions beyond simple urine output. Identify acquisition targets with robust intellectual property in real-time sensor technology and AI algorithms for predictive diagnostics. The signal to watch is the widespread adoption of value-based procurement models by large hospital networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven Predictive Analytics | Develops early AKI detection capabilities, improving patient outcomes and reducing ICU stays. |
| Secure EU MDR Compliance | Ensures market access across Europe, meeting stringent device accuracy and data connectivity standards. |
| Expand Non-ICU Application Portfolio | Broadens addressable market beyond critical care, reaching post-operative and general ward settings. |
| Forge Hospital System Partnerships | Facilitates seamless EHR integration and streamlines procurement for advanced monitoring systems. |
| Acquire Microfluidic Device Innovators | Integrates advanced diagnostic capabilities for highly sensitive biomarker detection in urine. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational understanding of market size and regulatory landscapes. This was combined with primary interviews conducted with clinicians, hospital purchasing managers, and biomedical engineers from leading medical device companies. Bottom-up and top-down triangulation ensured data consistency and validated initial market estimates.
Market dimensions were modeled at a granular level, including segmentation by product type, application, end user, and core technology across the analysis window. Compound annual growth rates were derived from historical data analysis and projected future trends, incorporating factors such as aging populations and critical care infrastructure expansion. Forecast inputs included acute kidney injury incidence rates and hospital investment patterns in advanced monitoring technologies.
Underlying measurement precision varies by segment; electronic systems and gravimetric devices carry tighter precision than manual gauges. Forecasts reflect assumptions regarding regulatory evolution, technological advancements, and healthcare expenditure trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market