
 Epro, E-Patient Diaries and Ecoa Market | 2026-2036
Epro, E-Patient Diaries and Ecoa Market Size, Share, and Industry Trends Forecast 2026-2036
Epro, E-Patient Diaries and Ecoa Market Analysis
Regulatory-grade data-integrity certification is redrawing competitive boundaries across electronic clinical outcome assessment platforms. Medidata leverages its cloud-native architecture to anchor large-scale oncology trials across North American and European sites. IQVIA sustains dominance through integrated real-world data pipelines that connect ePRO capture to post-market surveillance networks. Signant Health differentiates via specialized patient-engagement tools that reduce dropout rates in longitudinal studies.
Electronic patient-reported outcomes, e-patient diaries, and electronic clinical outcome assessments comprise digital health technologies that capture symptom reports, medication adherence logs, and quality-of-life metrics through validated mobile interfaces, web portals, or connected wearables, with FDA 21 CFR Part 11 and EU Annex 11 compliance governing audit trails, electronic signatures, and data integrity for regulatory submissions. Mobile App solutions lead volume deployment due to smartphone penetration, while Wearable Device integration represents the fastest-expanding segment as biometrics capture expands beyond manual entry. Patient-Reported Outcomes data types command premium pricing given their direct inclusion in regulatory filings and label claims.
FDA oversight through 21 CFR Part 11 and the Digital Health Center of Excellence shapes software validation requirements and market access pathways for US-deployed platforms. EMA's MDR and GDPR frameworks in Europe impose additional data-localization and patient-consent architectures that vendors must engineer into multi-tenant systems. Stakeholders should monitor evolving FDA guidance on artificial-intelligence-enabled data capture and EMA's adaptive pathway integrations, as these will determine which platform architectures secure preferred-provider status in sponsor procurement cycles.
Market Dynamics
FDA 21 CFR Part 11 validation requirements and EU MDR data-integrity standards are compressing vendor qualification timelines, forcing platform providers to front-load compliance architecture before sponsor procurement cycles begin.
Growth Catalysts
- Decentralized Trial Mandates:Pharmaceutical sponsors now require electronic patient-reported outcome platforms for hybrid and remote study designs, eliminating paper-based capture from protocol submissions.
- EMA Adaptive Pathways:The European Medicines Agency's accelerated approval frameworks reward real-time data collection, positioning ePRO systems as infrastructure for conditional marketing authorizations.
- Wearable Biometrics:Continuous glucose monitors, accelerometers, and ECG patches are miniaturizing patient burden while expanding objective endpoint capture beyond manual diary entries.
Market Restraints
- Validation Cost Burden:FDA 21 CFR Part 11 compliance requires documented audit trails, electronic signatures, and system validation that consumes 18-24 months of pre-commercial engineering.
- Data Localization Requirements:GDPR and emerging national privacy frameworks mandate EU-resident data storage, fragmenting cloud architectures and raising infrastructure costs for multi-regional trials.
- Site Infrastructure Gaps:Rural and community-based research sites in lower-income countries lack reliable connectivity and device provisioning, limiting geographic expansion of digital capture protocols.
Strategic Opportunities
- Japan's Digital Health Acceleration:PMDA's Sakigake designation and METI's regulatory sandbox programs create fast-track pathways for AI-enabled eCOA platforms in oncology and rare disease trials.
- Voice Biomarker Integration:Convergence of natural language processing with acoustic analysis enables passive symptom detection through smartphone microphones, opening new endpoint categories.
- Direct-to-Patient Distribution:Sponsor-provisioned device kits shipped to home addresses bypass site-based provisioning, reducing startup delays and expanding eligible participant pools.
Industry Challenges
- Interoperability Architecture:Legacy electronic data capture systems require custom API development for ePRO data ingestion, extending implementation timelines and integration costs.
- Digital Literacy Variance:Elderly and cognitively impaired patient populations struggle with touchscreen interfaces, necessitating parallel paper backup protocols that compromise data uniformity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epro, E-Patient Diaries and Ecoa Market |
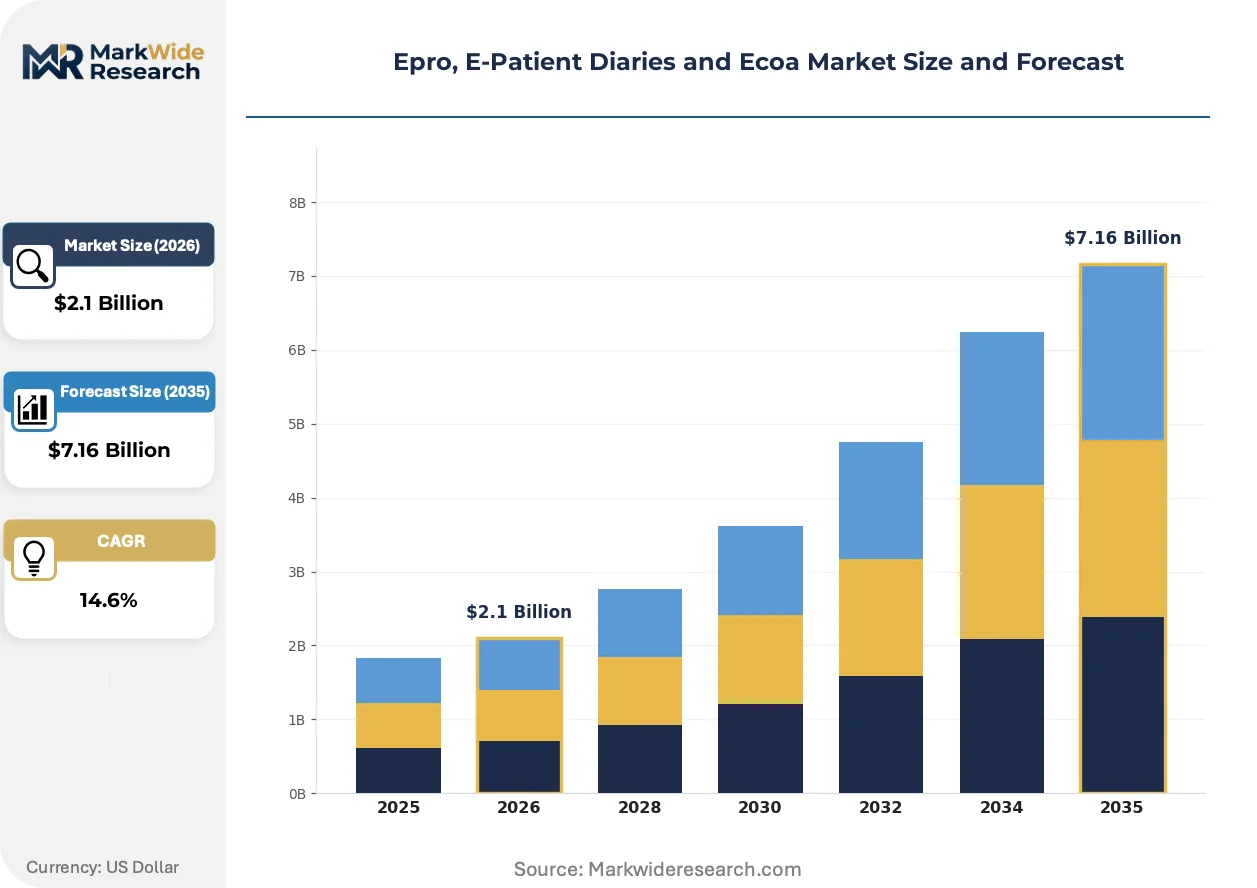
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
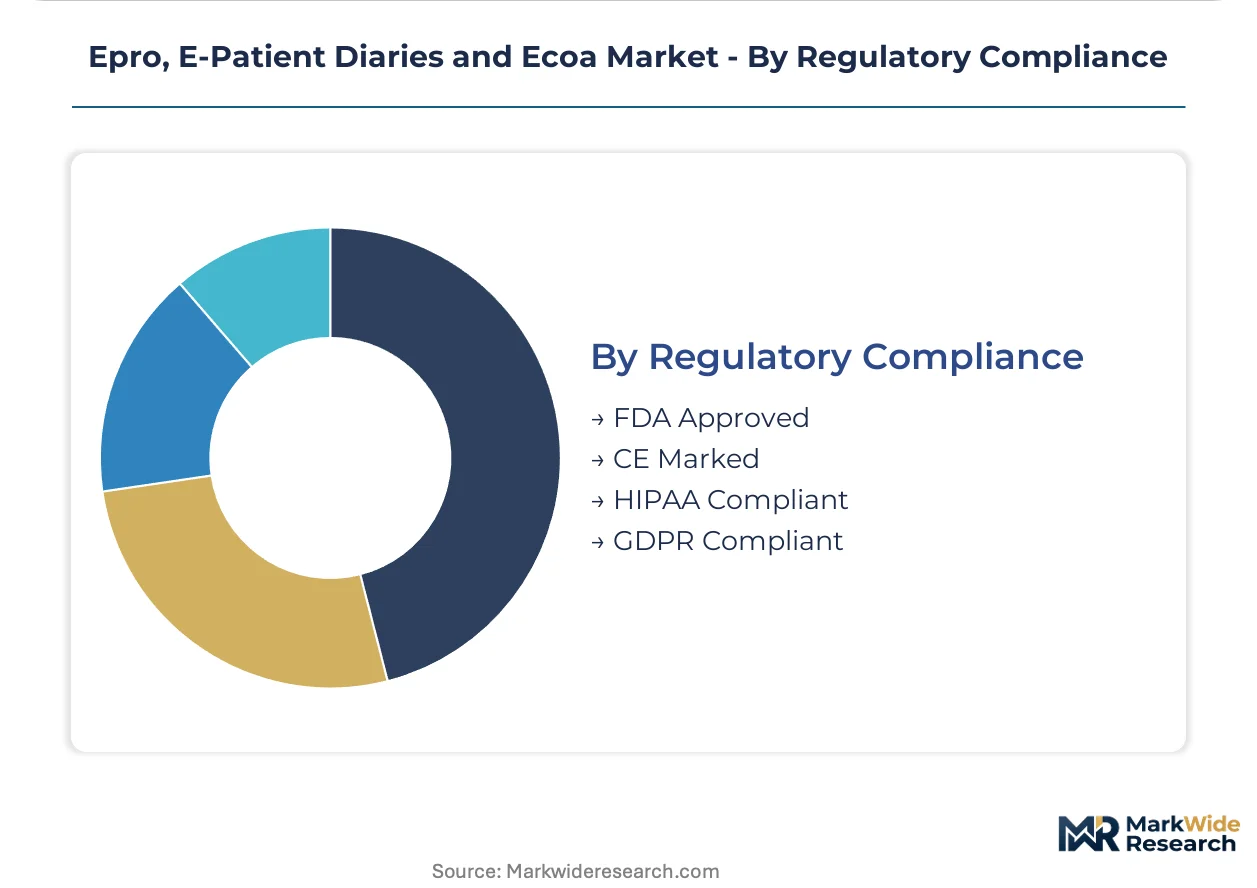
| Segmentation | Product Type: Mobile App, Web-Based Platform, Wearable Device, Tablet Solution End User: Patients, Healthcare Providers, Researchers, Caregivers Data Type: Clinical Data, Patient-Reported Outcomes, Biometrics, Treatment Feedback Regulatory Compliance: FDA Approved, CE Marked, HIPAA Compliant, GDPR Compliant |
| Companies Covered | Medidata, IQVIA, ICON plc, Signant Health, Clario, PAREXEL International Corporation, ArisGlobal, eClinical Solutions, Kayentis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epro, E-Patient Diaries and Ecoa Market Emerging Trajectories
Sensor-embedded wearables and AI-assisted data validation are compressing the gap between patient experience and regulatory-grade evidence generation, reshaping how sponsors design endpoint strategies.
Photoplethysmography and accelerometer arrays in consumer-grade smartwatches are miniaturizing continuous vital sign capture for cardiovascular and respiratory endpoints. Mid-size biotech sponsors in immuno-oncology and gene therapy are adopting these platforms for 48-week longitudinal studies. The technology is miniaturizing the distinction between clinic-based assessment and real-world monitoring, enabling ambulatory efficacy claims previously restricted to inpatient observation.
EMA's Medical Device Regulation and In Vitro Diagnostic Regulation are tightening software-as-a-medical-device classifications for algorithm-driven symptom scoring. Platform vendors must now submit technical documentation and clinical evidence for diagnostic modules integrated into patient diaries. German and French notified bodies are processing the first wave of CE-marked eCOA applications, establishing precedent for class IIa medical device pathways in digital therapeutics adjacencies.
Site-less trial procurement is displacing traditional site-based technology provisioning, with sponsors contracting directly with platform vendors for patient-facing devices. Contract research organizations in the United States and United Kingdom are unbundling their technology stacks, offering protocol design and monitoring while outsourcing ePRO infrastructure to specialized vendors. This channel disintermediation concentrates purchasing authority within sponsor procurement functions, compressing vendor margins and elevating platform performance guarantees in master service agreements.
Epro, E-Patient Diaries and Ecoa Market Segmentation

Segmentation in electronic clinical outcome assessment platforms reveals how technology choices, user workflows, and regulatory pathways create distinct commercial battlegrounds. Sponsors configure procurement strategies around these dimensions, with compliance certification and data-capture modality determining platform viability in specific trial types.
Product Type:
Substitution pressure runs strongest against Web-Based Platforms as smartphone-native interfaces displace browser-dependent workflows across decentralized trial designs.
- Mobile App:Native iOS and Android applications deliver offline-capable data capture with push-notification adherence prompts. Oncology sponsors in the United States and Germany deploy these for 24/7 symptom logging, though FDA 21 CFR Part 11 validation requirements extend development timelines significantly.
- Wearable Device:Continuous glucose monitors, accelerometers, and ECG patches automate biometric capture without manual patient entry. Cardiovascular and respiratory trials in Japan leverage these for ambulatory endpoint generation, with PMDA's Sakigake designation accelerating regulatory acceptance of sensor-derived data.
- Web-Based Platform:Browser-accessible portals serve elderly populations and regions with limited smartphone penetration, though connectivity dependencies create data-gap risks in rural study sites.
- Tablet Solution:Sponsor-provisioned hardware ensures standardized interface experiences and controlled software environments, common in multi-site phase III trials requiring uniform device configuration.
Mobile App retains volume leadership; Wearable Device holds the steepest expansion curve.
End User:
Cost-tier differentiation separates enterprise-grade researcher licenses from patient-facing free-access tiers, with procurement authority concentrating in sponsor clinical operations budgets.
- Patients:Primary data originators using smartphone or wearable interfaces for symptom diaries, medication logs, and quality-of-life instruments. Elderly and cognitively impaired subpopulations in the United States require simplified touchscreen protocols to minimize dropout rates in longitudinal studies.
- Researchers:Principal investigators and study coordinators accessing real-time dashboards, query management tools, and regulatory export functions. Academic medical centers in Germany prioritize EMA MDR-aligned audit trail capabilities for adaptive pathway submissions.
- Healthcare Providers:Site-based clinicians reviewing patient-generated data for safety signal detection and care coordination, particularly in hybrid trial designs blending remote and in-person visits.
- Caregivers:Proxy reporters for pediatric or incapacitated participants, introducing data-quality variability that FDA guidance addresses through validated observer-reported outcome instruments.
Patients dominate user counts; Researchers command the highest per-seat licensing value.
Data Type:
Application-specific requirements drive pricing stratification, with regulatory-grade endpoints commanding premium positioning against operational datasets.
- Patient-Reported Outcomes:Validated instruments capturing symptoms, functional status, and health-related quality of life directly from participants. These endpoints support label claims and reimbursement negotiations, with FDA requiring electronic implementation equivalence to paper originals.
- Biometrics:Sensor-derived physiological measurements including heart rate variability, sleep architecture, and activity counts. Japan's METI regulatory sandbox programs fast-track AI-enabled analysis of continuous biometric streams in rare disease trials.
- Clinical Data:Investigator-assessed outcomes and laboratory values integrated from electronic data capture systems, requiring complex API architectures for ePRO platform ingestion.
- Treatment Feedback:Medication adherence timestamps and dosing confirmation logs, increasingly captured through smart packaging integration rather than manual diary entry.
Patient-Reported Outouts anchor regulatory submissions; Biometrics is expanding most quickly as wearable penetration deepens.
Regulatory Compliance:
Geography determines certification requirements, with multi-tenant platforms engineering modular compliance architectures to serve parallel FDA and EMA submission pathways.
- FDA Approved:21 CFR Part 11 validation encompassing electronic signatures, audit trails, and system documentation for US marketing applications. Sponsors in the United States mandate this certification for all phase IIb and III trials.
- CE Marked:EMA MDR and IVDR conformity assessments for software-as-a-medical-device classifications, with German and French notified bodies establishing precedent for class IIa eCOA pathways.
- HIPAA Compliant:US health information privacy safeguards governing protected health data storage, transmission, and business associate agreements with cloud infrastructure providers.
- GDPR Compliant:EU data localization and patient consent architectures mandating EU-resident server infrastructure and granular data-processing disclosures.
FDA Approved certification holds the broadest sponsor recognition; CE Marked requirements are tightening fastest under MDR implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering talent and clinical trial infrastructure concentrate in the United States, Germany, and Japan, with regulatory sandbox programs in each jurisdiction accelerating vendor qualification timelines for electronic outcome assessment systems.
United States
FDA 21 CFR Part 11 validation requirements dominate sponsor procurement criteria, with pharmaceutical companies mandating electronic signatures and audit trail capabilities for all phase IIb and III submissions. The Digital Health Center of Excellence issues guidance on AI-enabled data capture that shapes platform architecture decisions. Boston and San Francisco anchor the vendor ecosystem, where cloud-native systems integrate with decentralized trial protocols.
Germany
EMA MDR implementation tightens software-as-a-medical-device classifications for algorithm-driven symptom scoring, forcing platform re-engineering for CE-marked pathways. German notified bodies process the first wave of class IIa eCOA applications, establishing precedent for diagnostic module integration. Munich and Heidelberg concentrate clinical research organizations adapting to adaptive pathway data requirements.
Japan
PMDA's Sakigake designation fast-tracks AI-enabled platforms in oncology and rare disease trials, compressing regulatory review windows for sensor-derived endpoints. METI's regulatory sandbox programs validate continuous biometric capture from wearables in ambulatory settings. Tokyo and Osaka host sponsor operations integrating ePRO systems with post-market surveillance networks.
United Kingdom
MHRA convergence with EMA standards post-Brexit creates dual-certification requirements for vendors serving European and UK trials simultaneously. NHS digital health adoption programs drive demand for patient-engagement tools in hybrid study designs. London and Cambridge concentrate contract research organizations unbundling technology stacks to specialized eCOA providers.
Switzerland
Swissmedic alignment with EMA MDR and FDA pathways positions the jurisdiction as a testing ground for multi-regulatory platform architectures. Basel's pharmaceutical cluster demands integrated real-world data pipelines connecting electronic capture to post-approval monitoring. Geneva hosts precision medicine initiatives requiring longitudinal patient-reported outcome tracking.
Epro, E-Patient Diaries and Ecoa Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated contract research organizations leveraging scale against specialized platform vendors competing on regulatory certification speed. The vendor base organizes around three strategic archetypes: full-service clinical trial organizations with captive technology, pure-play software vendors with cloud-native architectures, and medical device manufacturers extending into digital therapeutics adjacencies. M&A activity concentrates on acquiring FDA-validated platform assets, while strategic partnerships between sensor manufacturers and data analytics firms reshape endpoint capture capabilities.
Within the full-service tier, Medidata and IQVIA exemplify integrated models combining electronic capture with site networks and real-world evidence pipelines. Signant Health occupies a position among specialized patient-engagement vendors, differentiating through adherence optimization tools that address dropout rates in longitudinal oncology studies.
| Leading Market Players |
|---|
| Medidata |
| IQVIA |
| ICON plc |
| Signant Health |
| Clario |
| PAREXEL International Corporation |
| ArisGlobal |
| eClinical Solutions |
| Kayentis |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 11 validation requirements gate both vendor qualification timelines and price differentiation across electronic clinical outcome assessment platforms, compressing procurement cycles for uncertified entrants while elevating premium positioning for audit-trail-compliant architectures. Sponsors in the United States and Germany now mandate documented electronic signatures and system validation as table stakes, forcing platform providers to front-load compliance engineering before commercial engagement begins.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across electronic patient-reported outcome platforms, with validated audit-trail capabilities separating premium SaaS subscriptions from standard web-based deployments. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, integration complexity with electronic data capture systems, and after-sales validation support. Cost compression in the standard tier is intensifying because sponsor procurement functions are unbundling technology stacks from contract research organization bundles. Academic medical centers and mid-size biotech sponsors exhibit the highest price sensitivity, while large pharmaceutical sponsors prioritize compliance guarantees over per-seat licensing costs.
Supply Chain Analysis
Port congestion across transpacific trade lanes elevates inbound logistics costs for sensor-embedded wearables and tablet hardware provisioned to decentralized trial sites. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, with EU data-localization mandates fragmenting server architectures for GDPR-compliant deployments. Component dependencies span ARM-based mobile processors, photoplethysmography sensors, and lithium-polymer batteries for continuous monitoring devices. Single-source vulnerability runs through Taiwan semiconductor foundries supplying wearable biometric chipsets. Distribution runs through sponsor-provisioned direct-to-patient kits and site-based hardware deployment, with channel disintermediation compressing contract research organization technology margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic clinical outcome assessment platforms represent a service-attach opportunity where validation consulting and ongoing compliance auditing expand faster than core software licensing, with sponsors contracting separately for FDA submission support and EMA technical documentation.
For Market Incumbents: Compound defensive moats through backward integration into wearable sensor manufacturing and captive validation consulting practices that accelerate client 21 CFR Part 11 readiness. Cloud-native platform vendors face margin pressure from unbundled procurement patterns; incumbents should anchor multi-year master service agreements with performance guarantees on dropout-rate reduction in longitudinal oncology studies. For New Entrants and Emerging Players: Japan's PMDA Sakigake designation fast-tracks regulatory acceptance for AI-enabled symptom detection platforms, creating entry pathways for voice biomarker and acoustic analysis modules that bypass saturated North American procurement cycles. Target rare disease trial sponsors in Tokyo and Osaka seeking sensor-derived ambulatory endpoints for accelerated approval pathways, with go-to-market positioning centered on METI regulatory sandbox validation and compressed implementation timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pure-play software architectures as cloud-native deployment reduces server infrastructure requirements, while wearable-integrated platforms face rising hardware provisioning costs. Long-term viability favors vendors with FDA-validated platform assets and established EMA notified body relationships over sensor hardware manufacturers lacking regulatory-grade software capabilities. Watch for EMA MDR enforcement actions against non-compliant diagnostic modules as an inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 11 Validation Fast-Track | Compresses 18-24 month pre-commercial engineering timelines for sponsor procurement eligibility. |
| Wearable Biometric Integration Partnership | Enables continuous glucose monitor and ECG patch data ingestion for cardiovascular endpoint claims. |
| Direct-to-Patient Device Distribution | Bypasses site-based provisioning delays and expands eligible participant pools in decentralized trials. |
| EMA MDR Technical Documentation Buildout | Establishes CE-marked class IIa pathways for algorithm-driven symptom scoring modules. |
| Real-World Evidence Pipeline Integration | Connects ePRO capture to post-market surveillance networks for adaptive pathway submissions. |
Methodological Framework
A spread of perspectives from clinical operations executives at pharmaceutical sponsors, regulatory affairs leads managing FDA and EMA submissions, contract research organization technology procurement officers, and academic medical center principal investigators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 21 CFR Part 11 guidance documents, EMA MDR technical documentation requirements, ClinicalTrials.gov protocol registrations, and cloud infrastructure provider compliance disclosures. Bottom-up sizing of platform deployments across oncology, cardiovascular, and rare disease indications triangulated with top-down pharmaceutical R&D technology spending allocations.
Segmentation dimensions modeled span product type, end user archetype, data capture modality, and regulatory compliance tier across the projection horizon. Deployment model variations between mobile-native, wearable-integrated, and web-based architectures intersected with sponsor size stratification and therapeutic area regulatory intensity. CAGRs were derived from sponsor technology budget trajectories, decentralized trial adoption curves, and wearable penetration rates in longitudinal studies. Forecast inputs incorporated PMDA Sakigake designation velocity, EMA adaptive pathway submission volumes, and FDA Digital Health Center of Excellence guidance evolution.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory tightening and sponsor unbundling of technology procurement from site services; material deviation in FDA enforcement posture or EMA MDR implementation timing would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Neuro-Monitoring System Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Multiparameter Patient Monitoring System Market