
 Medical Telemetry Market | 2026-2036
Medical Telemetry Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Telemetry Market Outlook
Silicon is decoupling from legacy substrate dependence in telemetry hardware as gallium nitride semiconductors replace silicon-based power management chips, cutting device energy draw by half while extending transmission range. GE Healthcare leverages captive semiconductor sourcing to stabilize component costs across its patient monitoring portfolio. Koninklijke Philips anchors its telemetry division on proprietary signal-processing algorithms that filter motion artifact from ambulatory cardiac data. Siemens Healthineers competes through integrated imaging-to-telemetry workflows that feed real-time hemodynamics into catheterization lab decision-support systems.
Medical telemetry encompasses the wireless acquisition, digital encoding, and remote transmission of physiological parameters—heart rate, blood oxygen saturation, respiratory rate, glucose levels—using FCC-allocated frequencies in the 400–2500 MHz bands with transmit power typically below 1 watt to ensure patient safety and minimize interference. The primary commercial purpose is to enable continuous clinical surveillance without tethering patients to bedside instrumentation, thereby reducing length-of-stay and enabling early discharge protocols. Wearable monitors lead product type revenue as health systems amortize capital across multipurpose wrist and patch formats rather than dedicated single-parameter devices. Remote patient monitoring represents the fastest-expanding application segment, propelled by reimbursement codes that now compensate physicians for interpreting transmitted data outside traditional facility settings. Cellular technology dominates technology deployment where Wi-Fi infrastructure remains inconsistent, particularly in rural home care environments where patients lack broadband connectivity.
FDA premarket notification pathways and FCC Part 15 rules jointly shape device development timelines and transmission specifications for manufacturers seeking US market access. The Centers for Medicare & Medicaid Services reimbursement frameworks determine whether health systems recover telemetry costs through episode-based payments or fee-for-service billing. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-enabled arrhythmia detection algorithms, as predicate-device equivalency standards for machine-learning-based telemetry systems remain unsettled and will determine which product architectures achieve commercial clearance.
Market Dynamics
Hospital-at-home reimbursement expansion is restructuring medical telemetry demand as CMS episode-based payment codes now cover remote cardiac monitoring, pulling capital away from bedside devices and into ambulatory patch systems.
Growth Catalysts
- FCC Part 15 spectrum allocation:Unlicensed 400–2500 MHz bands enable manufacturers to deploy wireless physiological monitors without per-device spectrum licensing, compressing go-to-market timelines for new entrants.
- Gallium nitride semiconductor migration:GaN power management chips cut telemetry device energy consumption by half while extending transmission range, allowing single-charge operation across 72-hour monitoring windows.
- Home care infrastructure buildout:United States health systems are scaling remote patient monitoring deployments to reduce length-of-stay, creating pull-through demand for wearable cardiac patches and cellular-enabled glucose transmitters.
Market Restraints
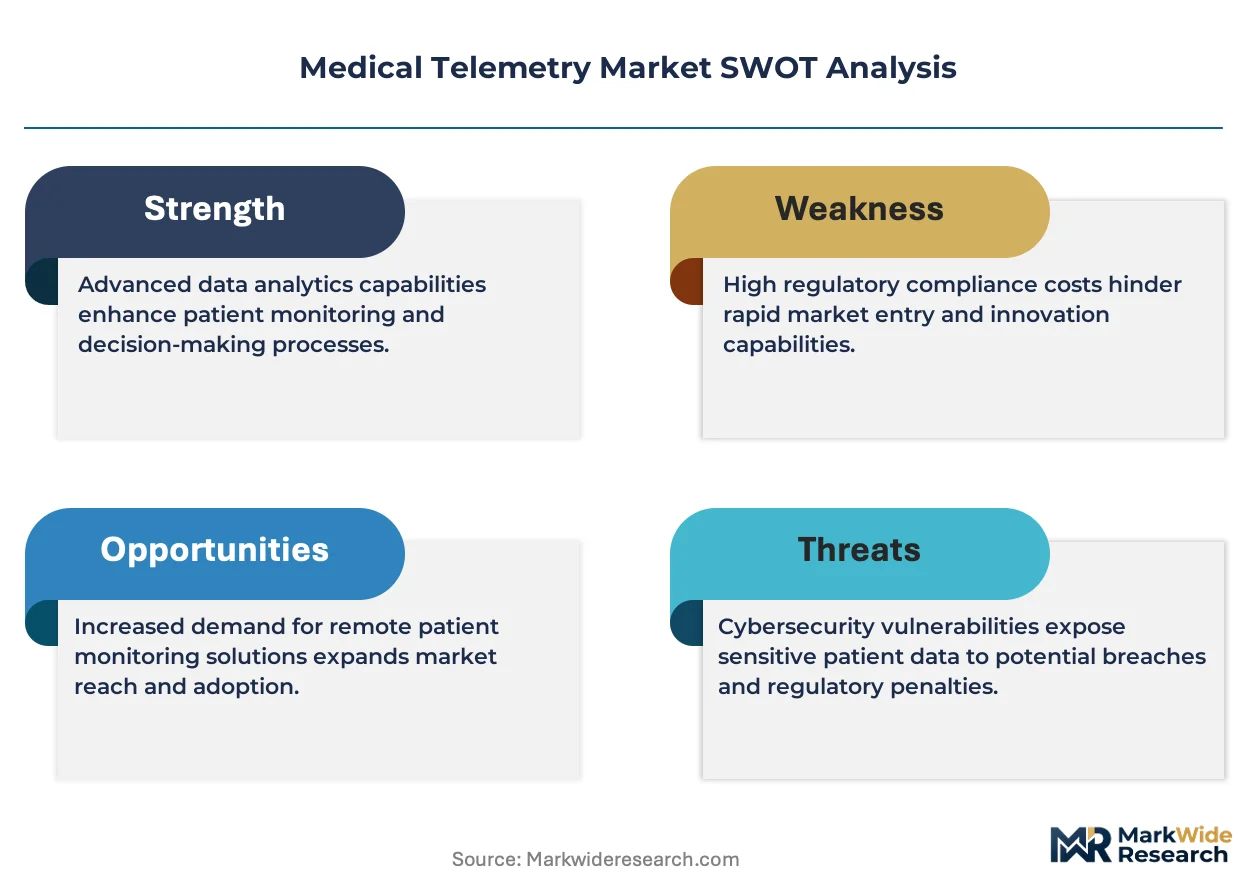
- Semiconductor supply concentration:Captive GaN foundry capacity concentrates with Asian contract manufacturers, exposing device developers to wafer allocation volatility during capacity crunches.
- Predicate-device equivalency uncertainty:FDA has not finalized machine-learning-based arrhythmia detection standards, forcing developers to pursue lengthier de novo pathways rather than streamlined premarket notifications.
- Broadband infrastructure gaps:Rural United States markets lack consistent Wi-Fi coverage, forcing reliance on higher-cost cellular modules that compress hardware margins.
Strategic Opportunities
- AI-enabled diagnostic convergence:Edge-computing telemetry devices integrating on-chip inference engines can flag arrhythmias without cloud transmission, opening subscription revenue models for algorithm licensing.
- Cellular LPWAN expansion:NB-IoT and LTE-M network buildout in underserved United States rural counties enables first-time remote monitoring penetration where broadband is unavailable.
- Integrated imaging-telemetry workflows:Catheterization labs are demanding real-time hemodynamic feeds from wearable monitors to guide interventional decisions, creating cross-selling opportunities for system vendors.
Industry Challenges
- Motion artifact filtering:Ambulatory cardiac monitoring requires sophisticated signal-processing algorithms to isolate true arrhythmia signals from patient movement noise, demanding specialized biomedical engineering talent scarce outside major device clusters.
- Legacy EMR integration:Health systems operate fragmented electronic medical record architectures, forcing telemetry vendors to maintain multiple HL7 FHIR interface configurations that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Telemetry Market |
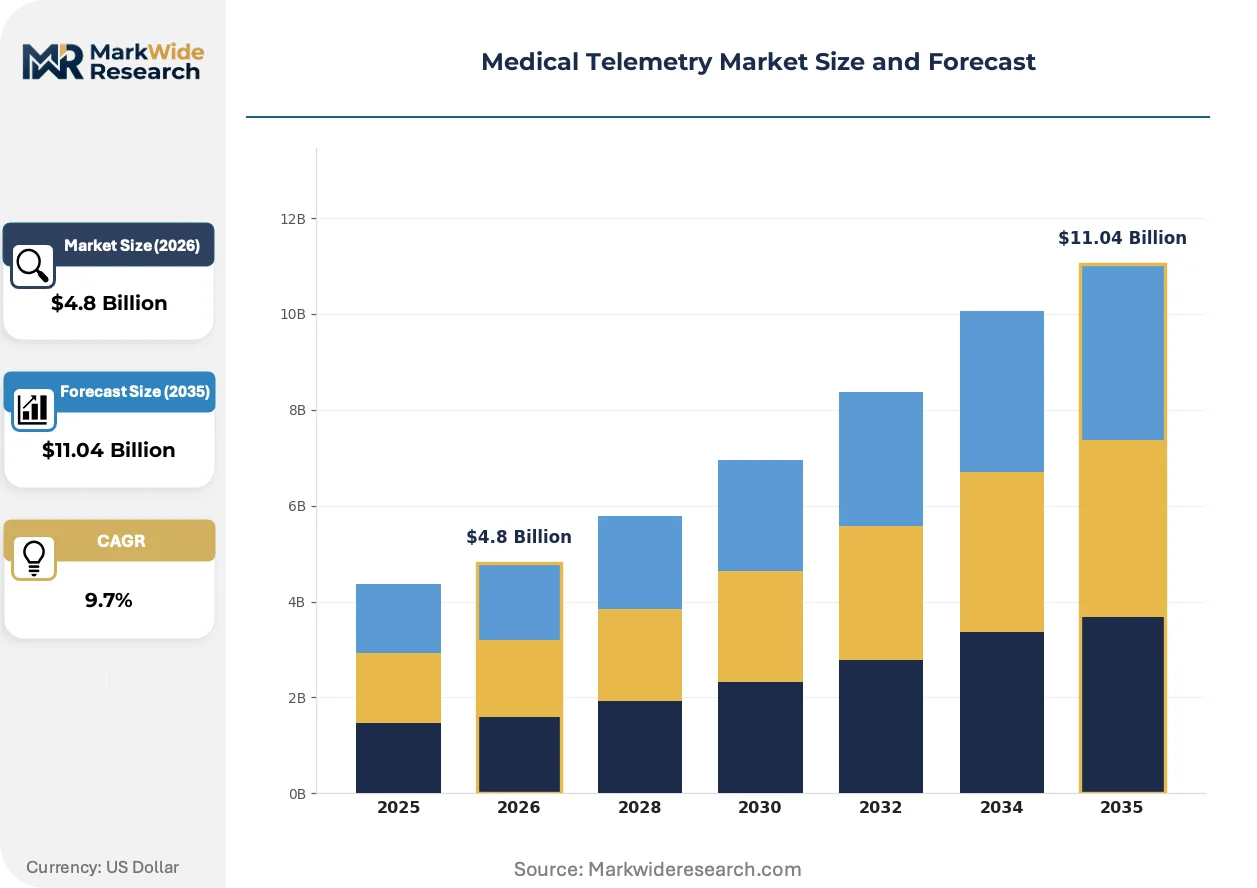
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Implantable Devices, Fixed Monitors, Mobile Applications End User: Hospitals, Home Care, Rehabilitation Centers, Nursing Facilities Technology: Analog Transmission, Digital Transmission, Cellular Technology, Wi-Fi Technology Application: Cardiac Monitoring, Respiratory Monitoring, Diabetes Management, Remote Patient Monitoring |
| Companies Covered | GE Healthcare, Koninklijke Philips, Siemens Healthineers, Nihon Kohden, Medtronic, BioTelemetry, Mindray Medical International, Masimo Corporation, Hill-Rom Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Telemetry Market Strategic Shifts
Silicon substrate dependence is dissolving as compound semiconductors and edge AI architectures reconfigure device economics. Three concurrent shifts are compressing development cycles while expanding clinical utility.
GaN power management is modularizing telemetry hardware architecture. Gallium nitride semiconductors replace silicon-based voltage regulators in wearable monitors, enabling discrete power subsystems that can be swapped across wrist, patch, and implantable form factors without full device redesign. United States device developers are adopting GaN reference designs from semiconductor vendors to accelerate platform iteration. This modularization is collapsing the traditional 18-month hardware refresh cycle into 9-month increments.
EMA's Medical Device Regulation (MDR) is tightening clinical evidence requirements for wireless patient monitors seeking European market access. The regulation now mandates post-market surveillance data for software-as-a-medical-device components, forcing telemetry vendors to maintain European-specific clinical registries. Cardiac patch manufacturers with limited European installed base are withdrawing from the market rather than absorbing compliance costs, concentrating supply among larger system vendors.
Hospital procurement is consolidating telemetry purchasing under integrated service contracts rather than capital equipment budgets. United States health systems are bundling device acquisition, connectivity, and clinical interpretation into per-patient-per-day fees, displacing traditional device ownership models. This shift favors vendors with captive cloud infrastructure and 24/7 monitoring centers over hardware-only suppliers.
Medical Telemetry Market Segmentation
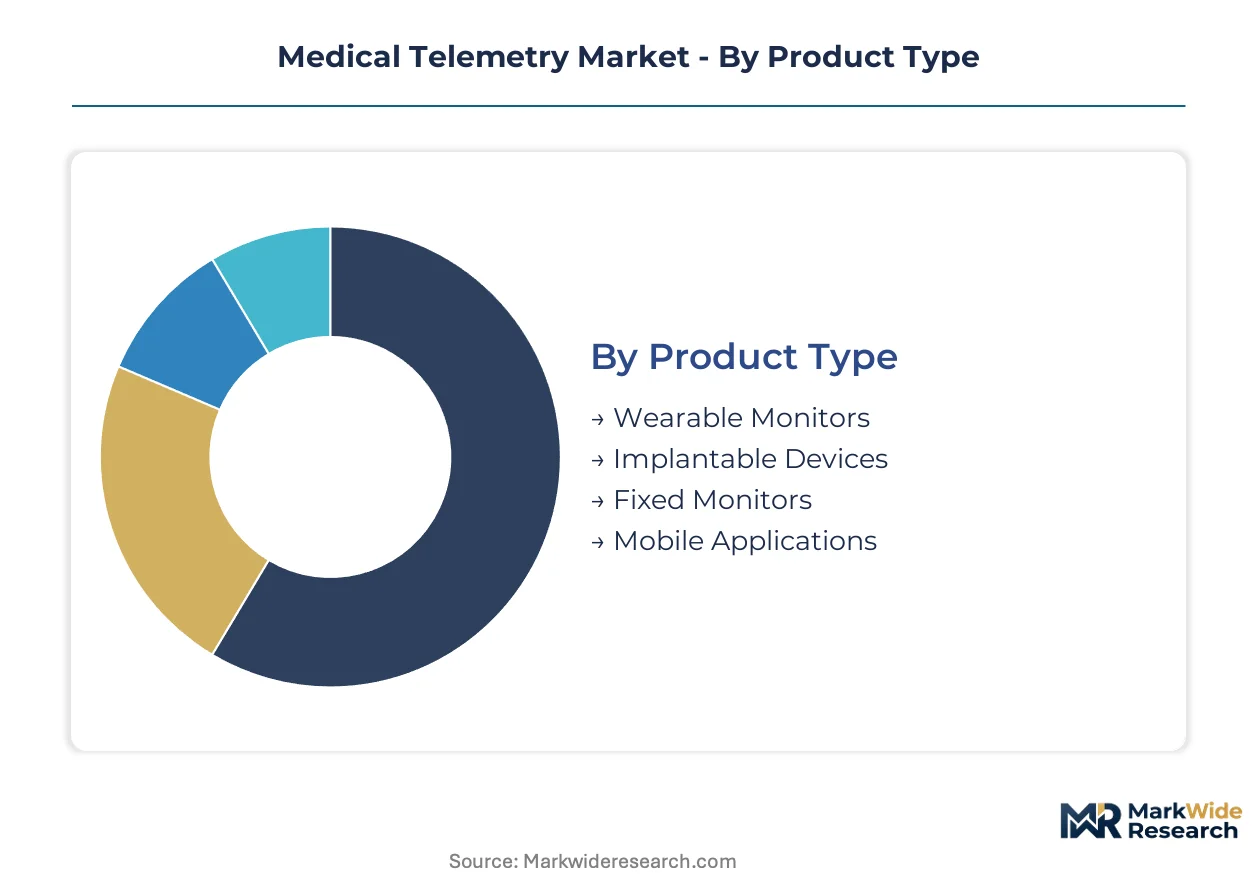
Medical telemetry segmentation reveals how hardware form factors, care settings, transmission protocols, and clinical applications create distinct commercial battlegrounds. Each category carries unique margin profiles and regulatory pathways that reshape vendor positioning.
Product Type:
Buyers differentiate by capital intensity versus operational flexibility, with health systems weighing upfront device costs against per-patient monitoring revenue.
- Wearable Monitors:Wrist-worn and patch-based devices combine photoplethysmography sensors with Bluetooth Low Energy transmission. United States health systems amortize capital across multipurpose formats rather than single-parameter alternatives. Demand concentrates in hospital-at-home programs where CMS reimbursement codes now cover remote cardiac surveillance.
- Implantable Devices:Subcutaneous loop recorders and pacemaker-integrated transmitters demand biocompatible encapsulation and decade-long battery longevity. Cardiology practices in Cleveland Clinic and Mayo Clinic networks drive adoption for cryptogenic stroke workups. FDA predicate-device pathways favor established manufacturers with legacy implantable portfolios.
- Fixed Monitors:Bedside telemetry stations with centralized nursing station displays remain tethered to acute care infrastructure.
- Mobile Applications:Smartphone-based data aggregation platforms rely on consumer hardware and cloud middleware.
Volume sits with Wearable Monitors; growth tilts toward Implantable Devices.
End User:
Reimbursement mechanics separate institutional buyers from consumer-directed purchasing, with payment velocity determining vendor cash flow cycles.
- Hospitals:Integrated delivery networks negotiate enterprise telemetry contracts bundling device acquisition, connectivity, and clinical interpretation. United States systems like HCA and Tenet deploy capital equipment across catheterization labs, step-down units, and emergency departments. Procurement teams prioritize FCC Part 15 compliance and FDA 510(k) clearance documentation.
- Home Care:Patients discharged under hospital-at-home protocols receive cellular-enabled patches with 24/7 monitoring center oversight. Rural United States counties lacking broadband infrastructure drive cellular module demand despite hardware margin compression.
- Rehabilitation Centers:Skilled nursing facilities with subacute cardiac recovery programs purchase mid-tier monitoring capacity.
- Nursing Facilities:Long-term care operators face Medicaid reimbursement constraints that limit device refresh cycles.
Procurement concentration favors Hospitals; expansion velocity belongs to Home Care.
Technology:
Transmission reliability requirements and infrastructure availability dictate module selection, with rural-urban connectivity divides forcing technology trade-offs.
- Cellular Technology:NB-IoT and LTE-M modules enable first-time remote monitoring penetration where Wi-Fi remains unavailable. United States rural counties in Montana, Wyoming, and Alaska depend on cellular backhaul for glucose transmitters and cardiac patches. Verizon and AT&T network buildout determines addressable market expansion.
- Digital Transmission:Packet-switched protocols with AES-256 encryption secure HIPAA-compliant physiological data streams. Health systems in United States metropolitan corridors deploy digital telemetry across integrated EMR architectures.
- Analog Transmission:Legacy FM-based systems persist in older hospital infrastructure with limited upgrade budgets.
- Wi-Fi Technology:802.11ac/ax standards serve dense inpatient environments with consistent broadband coverage.
Deployment scale rests with Digital Transmission; penetration gains accrue to Cellular Technology.
Application:
Clinical acuity and reimbursement code availability determine monitoring duration and data interpretation intensity, with cardiac applications commanding premium pricing.
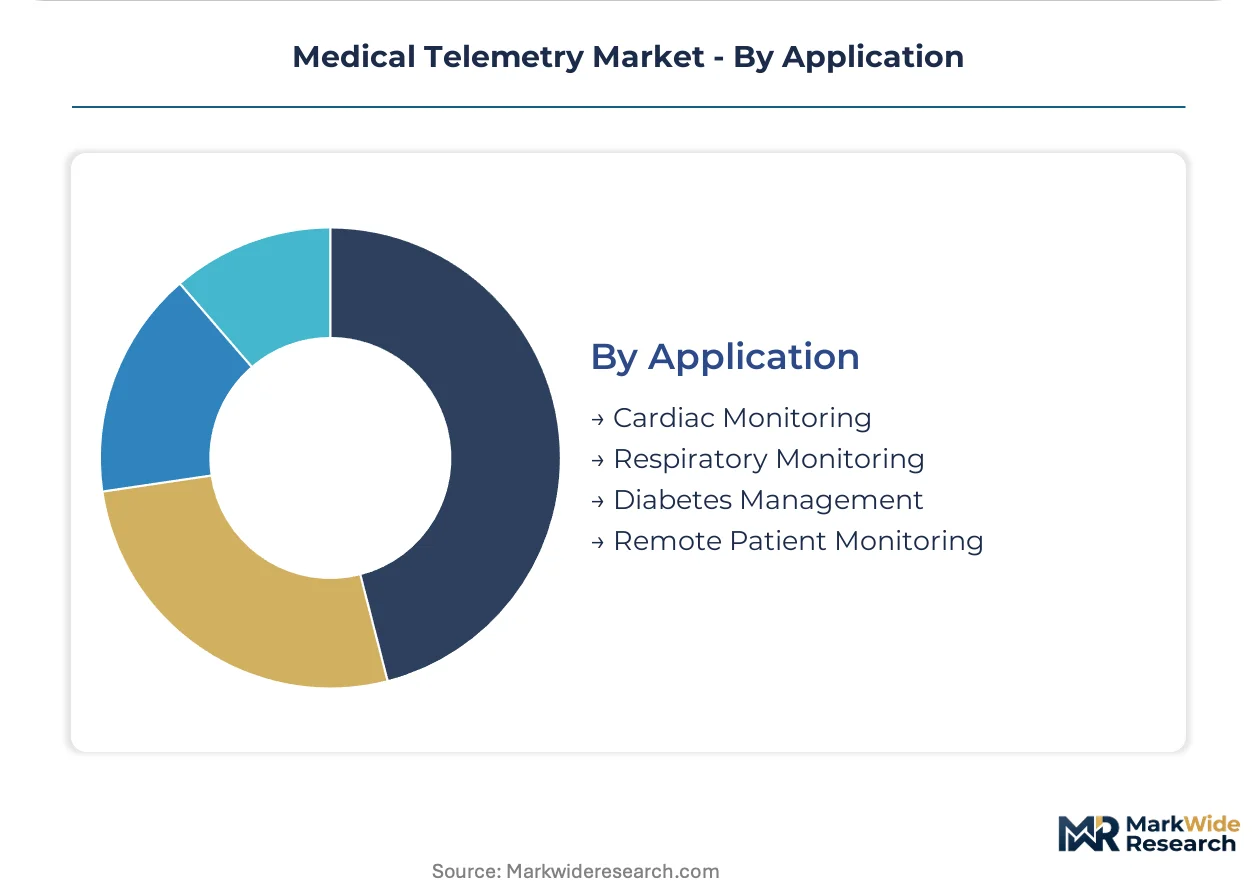
- Remote Patient Monitoring:CMS episode-based payment codes now compensate physicians for interpreting transmitted data outside traditional facility settings. United States cardiology practices bill CPT 99457 and 99458 for asynchronous review of arrhythmia transmissions. Revenue models shift toward per-patient-per-month subscription fees.
- Cardiac Monitoring:Ambulatory electrocardiography with automated arrhythmia detection requires sophisticated motion artifact filtering algorithms. United States device developers face FDA uncertainty on machine-learning-based predicate-device equivalency standards.
- Respiratory Monitoring:Pulse oximetry and capnography transmission supports post-surgical and COPD patient surveillance.
- Diabetes Management:Continuous glucose monitor data streams integrate with insulin dosing algorithms in closed-loop systems.
Revenue concentration aligns with Cardiac Monitoring; policy tailwinds favor Remote Patient Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems concentrate the majority of medical telemetry procurement as CMS reimbursement codes for remote patient monitoring pull capital toward ambulatory patch systems and away from bedside infrastructure. Cellular-enabled cardiac monitors penetrate rural counties lacking broadband coverage, while metropolitan centers deploy integrated imaging-to-telemetry workflows across catheterization labs.
United States
FDA 510(k) clearance pathways and FCC Part 15 spectrum rules jointly compress time-to-market for wireless cardiac monitor developers entering the market. Hospital-at-home reimbursement expansion under CMS episode-based payment codes now covers remote cardiac surveillance, restructuring demand toward ambulatory patch formats. The Cleveland Clinic and Mayo Clinic networks in Ohio and Minnesota drive adoption of implantable loop recorders for cryptogenic stroke workups.
Germany
Siemens Healthineers anchors integrated imaging-to-telemetry workflows that feed real-time hemodynamics into catheterization lab decision-support systems across German hospital networks. EMA Medical Device Regulation tightening clinical evidence requirements for wireless patient monitors forces telemetry vendors to maintain European-specific post-market surveillance registries. The Baden-Württemberg region around Stuttgart concentrates medical device engineering talent for signal-processing algorithm development.
Japan
Nihon Kohden leverages domestic manufacturing capacity for patient monitoring systems serving aging demographics in acute care and home care settings. PMDA regulatory pathways for software-as-a-medical-device components require local clinical trial data, extending clearance timelines for foreign telemetry vendors. The Kanto region around Tokyo hosts concentrated biomedical engineering clusters developing motion artifact filtering algorithms for ambulatory cardiac data.
China
Mindray Medical International competes through cost-optimized patient monitoring portfolios targeting domestic hospital procurement and export markets. NMPA regulatory harmonization with international standards accelerates clearance for wireless physiological monitors using domestically manufactured GaN semiconductors. The Yangtze River Delta around Shanghai concentrates contract manufacturing capacity for telemetry hardware components.
United Kingdom
NHS England procurement frameworks bundle telemetry device acquisition with connectivity and clinical interpretation services, displacing traditional capital equipment purchasing models. MHRA post-Brexit regulatory autonomy maintains alignment with MDR clinical evidence requirements while streamlining software-as-a-medical-device pathways. The Cambridge-Oxford-London corridor concentrates digital health startups developing edge-computing inference engines for arrhythmia detection.
Medical Telemetry Market Competitive Environment
Strategic partnerships dominate the current landscape as device developers secure captive semiconductor sourcing and cloud infrastructure partnerships to stabilize component costs. The market structures around three tiers: diversified system vendors with integrated imaging-to-telemetry workflows, specialized cardiac monitoring firms with proprietary signal-processing algorithms, and emerging hardware developers leveraging GaN reference designs for rapid platform iteration. M&A activity concentrates among mid-tier monitoring specialists seeking scale, while technology licensing agreements proliferate around edge AI inference engines for on-chip arrhythmia detection.
Within the diversified system vendor tier, GE Healthcare, Koninklijke Philips, and Siemens Healthineers exemplify contrasting strategic positions. GE Healthcare represents captive semiconductor sourcing strategies that stabilize component costs across patient monitoring portfolios. Koninklijke Philips anchors on proprietary biomedical signal-processing capabilities that filter motion artifact from ambulatory cardiac data. Siemens Healthineers occupies a position defined by integrated imaging-to-telemetry workflows feeding real-time hemodynamics into interventional decision-support systems.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips |
| Siemens Healthineers |
| Nihon Kohden |
| Medtronic |
| BioTelemetry |
| Mindray Medical International |
| Masimo Corporation |
| Hill-Rom Holdings |
| Others |
Value Chain & Pricing Dynamics
Captive GaN semiconductor sourcing anchors both supply security and pricing power for device developers navigating Asian foundry concentration. United States health systems purchasing telemetry bundles under per-patient-per-day contracts reward vendors with stable component costs and integrated cloud infrastructure.
Pricing Analysis
Volume concentrates in wearable monitors while margins concentrate in implantable devices with decade-long replacement cycles. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard tiers, and economy tiers targeting emerging markets with streamlined feature sets. Cost compression in cellular-enabled home care hardware intensifies because rural broadband gaps force expensive module inclusion. Hospital procurement committees exhibit lowest price sensitivity due to bundled service contracts, while skilled nursing facilities face acute margin pressure under Medicaid reimbursement constraints.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese and South Korean GaN foundry capacity, where wafer allocation volatility exposes device developers during semiconductor crunches. Raw material dependencies center on gallium nitride substrates, lithium-ion cells for extended monitoring windows, and biocompatible encapsulation polymers for implantable formats. Tariff exposure on Chinese-manufactured Bluetooth modules and sensor assemblies feeds upstream cost uncertainty. Distribution runs through integrated delivery network procurement offices and group purchasing organizations consolidating telemetry acquisitions across United States hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical telemetry sector functions as a vertical-integration race where control over GaN semiconductor supply and captive cloud infrastructure determines pricing power. Winners secure foundry allocation agreements and 24/7 monitoring center capacity simultaneously.
For Market Incumbents: Cement foundry partnerships with Taiwanese and South Korean semiconductor manufacturers to lock in wafer allocation during capacity crunches. Acquire edge-AI telemetry startups before FDA finalizes machine-learning predicate-device standards, as algorithm-integrated hardware will command premium positioning once clearance pathways stabilize. For New Entrants and Emerging Players: Enter via cellular-enabled cardiac patches for rural United States counties where Verizon and AT&T network buildout creates first-time addressable markets. Target skilled nursing facilities with stripped-down monitoring hardware undercutting bundled hospital contracts, then upsell cloud interpretation services to capture recurring revenue. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified system vendors seeking GaN reference design capabilities and proprietary motion artifact filtering algorithms. Long-term viability favors developers with European MDR compliance infrastructure already deployed, as post-market surveillance registries create insurmountable barriers for late entrants. Watch FDA guidance on machine-learning predicate-device equivalency as the critical inflection signal determining which product architectures achieve commercial clearance.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Sourcing Agreement | Captive foundry allocation stabilizes component costs during Taiwan and South Korea capacity crunches. |
| FDA 510(k) Submission for Edge-AI Arrhythmia Detection | On-chip inference engines open subscription revenue models before cloud transmission requirements. |
| Hospital-at-Home Reimbursement Strategy | CMS episode-based payment codes now compensate remote cardiac surveillance outside facility settings. |
| European MDR Clinical Registry Establishment | Post-market surveillance infrastructure satisfies EMA evidence requirements for wireless patient monitors. |
| Cellular LPWAN Network Partnership | NB-IoT and LTE-M buildout in rural United States counties enables first-time monitoring penetration. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this medical telemetry analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and FCC regulatory specialists combined with FDA 510(k) databases, CMS Medicare reimbursement schedules, and semiconductor import manifests. Bottom-up device shipment estimates triangulated against top-down health system capital expenditure surveys.
Data-stream reconciliation across product type, end user, transmission technology, and clinical application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from weighted average of historical volume trajectories and reimbursement policy elasticity assumptions. Forecast inputs incorporated GaN semiconductor price curves, cellular module cost declines, and CMS code expansion timelines for remote patient monitoring.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance delays on machine-learning predicate-device standards and foundry allocation disruptions in Asian contract manufacturing. Forecasts reflect documented assumptions about reimbursement code expansion, semiconductor cost curves, and hospital procurement consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Wrist Blood Pressure Monitors Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market