
 Network Slicing Market | 2026-2036
Network Slicing Market Size, Share, and Industry Trends Forecast 2026-2036
Network Slicing Market Intelligence
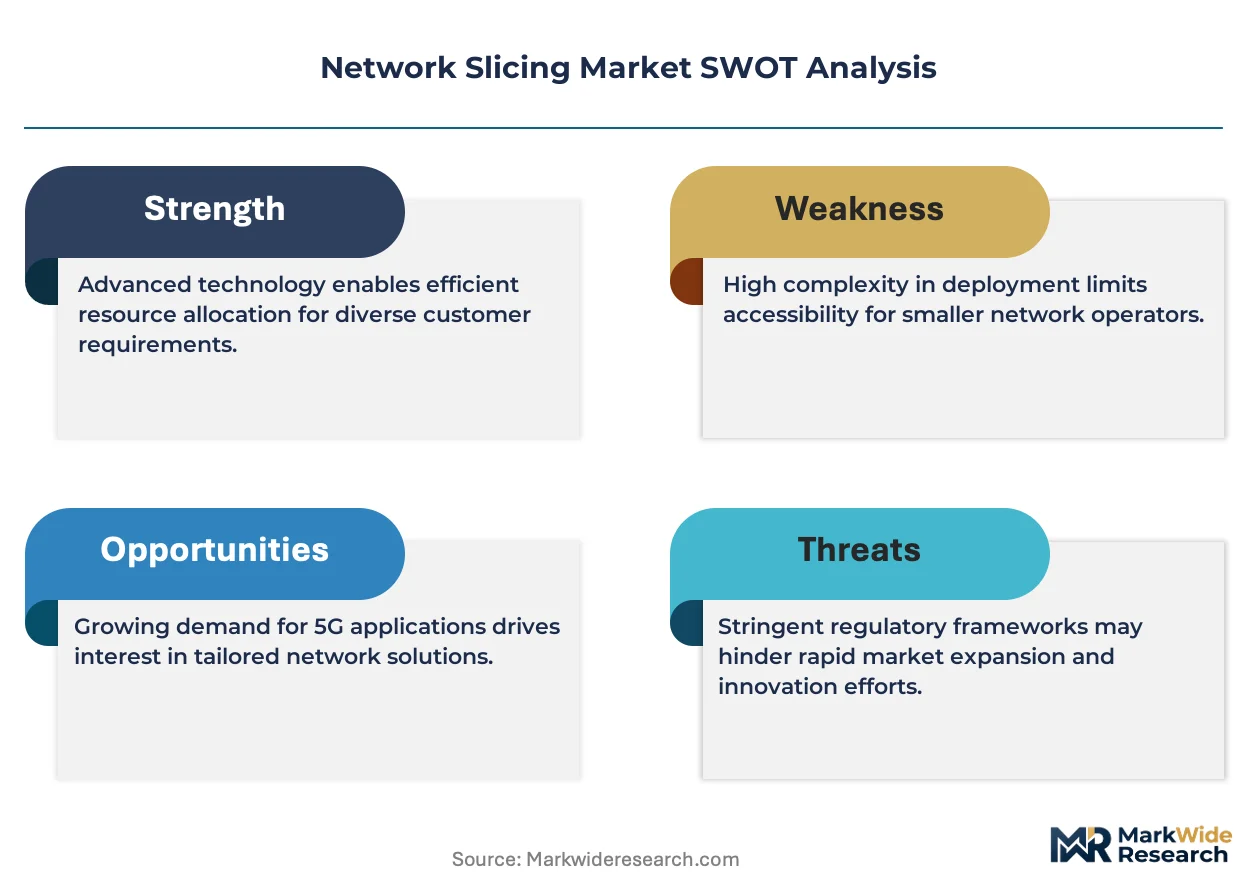
Software-defined per-slice resource allocation is reshaping how telecom infrastructure delivers differentiated connectivity services. Ericsson leverages its R&D intensity in 3GPP standardization to anchor early commercial deployments across European operator networks. Huawei competes through vertical integration into radio access and core network equipment, while Nokia specializes in cloud-native slice orchestration platforms for enterprise private networks.
Network slicing creates logically isolated virtual networks atop shared physical infrastructure, with each slice receiving guaranteed bandwidth, latency, and security parameters configured through policy-driven automation. Its primary purpose is enabling a single 5G network to simultaneously support divergent service requirements from consumer broadband to industrial control systems. The application dimension shows Ultra-Reliable Low Latency Communication commanding premium positioning for factory automation and remote surgery use cases, while Smart Cities represents the fastest-growing segment as municipalities procure dedicated slices for traffic management and public safety networks. Slice Orchestration services within the service type dimension concentrate margin pools, since vendors bundle ongoing policy management and dynamic resource adjustment into recurring contracts.
The Federal Communications Commission in the United States governs spectrum allocation rules that determine whether operators can dedicate licensed frequencies to enterprise slices, while the European Telecommunications Standards Institute publishes technical specifications for cross-border slice interoperability that shape product compliance requirements. China's Ministry of Industry and Information Technology mandates domestic certification for core network elements, creating market access conditions that favor local integration partners. Stakeholders must monitor how national spectrum auctions and cross-border data sovereignty rules affect slice deployment economics in multi-jurisdiction enterprise contracts.
Market Dynamics
The transition from 5G Non-Standalone to 5G Standalone architecture is collapsing the technical barriers that previously prevented true slice isolation, forcing infrastructure vendors to reconfigure their core network offerings around cloud-native orchestration stacks.
Growth Catalysts
- Industrial automation mandates:German manufacturers under the Industrie 4.0 framework are procuring private network slices for real-time factory control systems. This creates guaranteed demand for ultra-reliable low-latency configurations.
- Autonomous vehicle corridors:Transportation operators across multiple jurisdictions are deploying dedicated bandwidth slices for connected highway infrastructure. Vehicle-to-everything communication requires deterministic latency guarantees.
- 3GPP Release 17 specifications:The enhanced network slicing framework enables cross-operator slice roaming. This technical standardization removes interoperability barriers that previously constrained enterprise adoption.
Market Restraints
- Silicon supply concentration:Advanced baseband processor fabrication concentrates among a limited set of foundry operators. This creates vulnerability in radio access network equipment availability.
- Core network element certification:China's Ministry of Industry and Information Technology mandates domestic testing protocols for virtualization infrastructure. Foreign vendors face extended approval timelines.
- Optical transport capacity costs:Fronthaul fiber deployment for distributed radio units requires substantial capital outlay. Dense urban environments face right-of-way access constraints.
Strategic Opportunities
- Smart city infrastructure procurement:Municipal governments in the United States are issuing requests for proposals combining traffic management with public safety network slices. These contracts bundle long-term operational support.
- Edge computing convergence:Multi-access edge computing platforms are integrating with slice orchestration systems. This convergence enables sub-ten-millisecond application response for augmented reality services.
- Cross-border spectrum harmonization:The European Telecommunications Standards Institute is advancing technical specifications for international slice roaming. This regulatory alignment benefits multinational enterprise deployments.
Industry Challenges
- Cloud-native orchestration expertise scarcity:Kubernetes-based network function virtualization requires specialized DevOps capabilities. Traditional telecom engineering teams lack container orchestration proficiency.
- End-to-end slice testing complexity:Validating quality-of-service guarantees across radio, transport, and core domains demands new certification methodologies. No standardized test frameworks exist for multi-vendor environments.
- Legacy billing system integration:Existing charging platforms cannot accommodate dynamic per-slice resource metering. Operators must rebuild revenue assurance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Slicing Market |
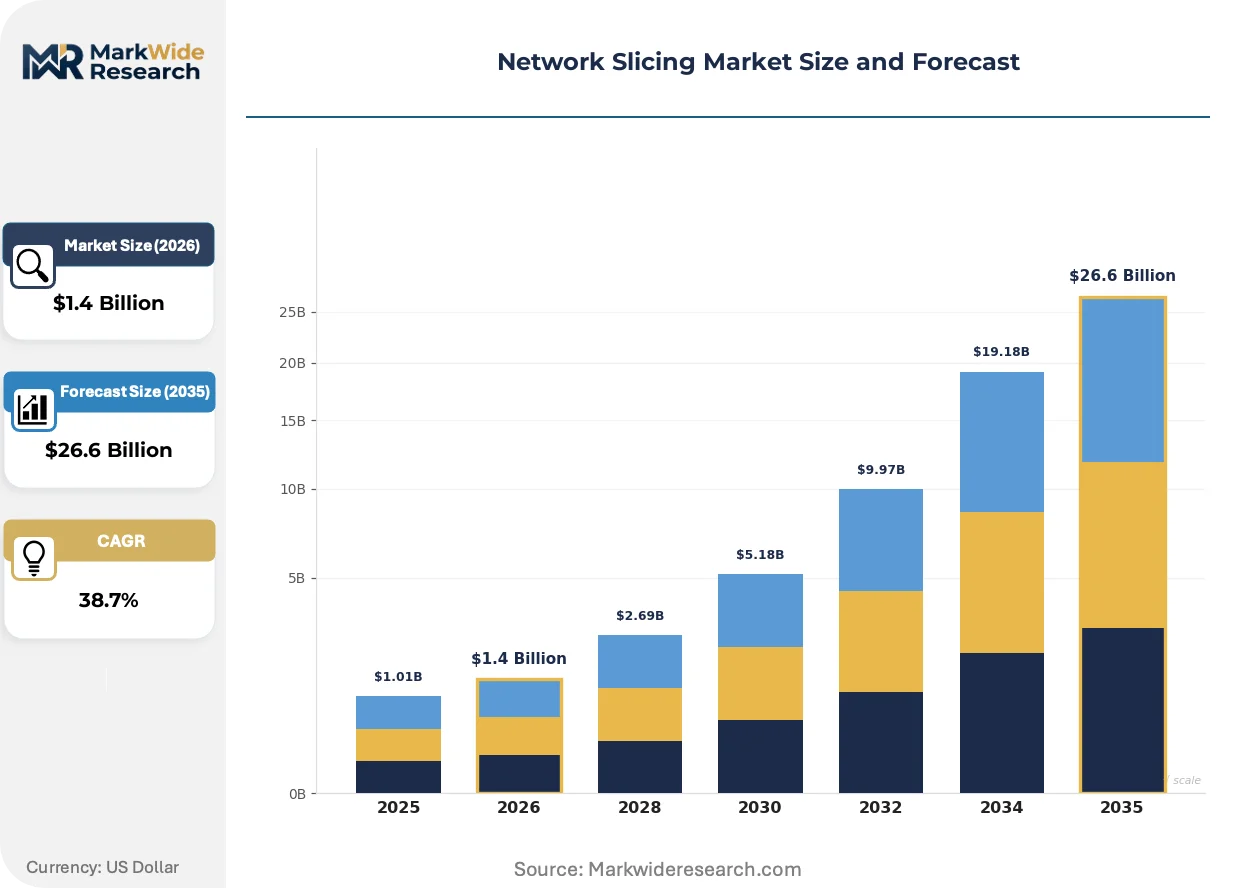
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $26.6 Billion |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Software Defined Networking, Network Function Virtualization, Edge Computing, 5G Core, AI Integration Application: Enhanced Mobile Broadband, Massive IoT, Ultra-Reliable Low Latency Communication, Private Networks, Smart Cities End User: Telecom Operators, Cloud Service Providers, Manufacturing Facilities, Transportation Operators, Energy Companies Service Type: Infrastructure Management, Slice Orchestration, Security Services, Network Analytics, SLA Assurance |
| Companies Covered | Cisco, Amdocs, Ericsson, Ciena Corporation, Samsung, Huawei, ZTE, HCL, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Slicing Market Strategic Shifts & Innovations
Software-defined resource allocation is collapsing traditional network engineering workflows, with policy-driven automation replacing manual configuration across radio access and core domains. This transformation compresses service deployment timelines from months to hours.
Intent-based networking is collapsing the manual configuration burden that previously constrained slice deployment velocity. Telecommunications operators are adopting declarative policy engines that automatically translate business requirements into technical parameters. This compression of operational overhead enables rapid slice instantiation for enterprise customers with fluctuating bandwidth demands.
The European Union's Cybersecurity Act establishes certification frameworks for critical network infrastructure components. Equipment vendors must demonstrate compliance with Common Criteria evaluation assurance levels before deployment in member state networks. German industrial manufacturers are prioritizing suppliers with pre-certified security profiles to accelerate private network slice procurement cycles.
Enterprise buyers are consolidating vendor relationships around integrated slice orchestration platforms rather than procuring radio, transport, and core elements separately. This preference shift favors suppliers offering end-to-end managed services with guaranteed service level agreements. The pattern is most pronounced in Japan, where manufacturing conglomerates are awarding decade-long contracts to single-source infrastructure providers.
Network Slicing Market Segmentation
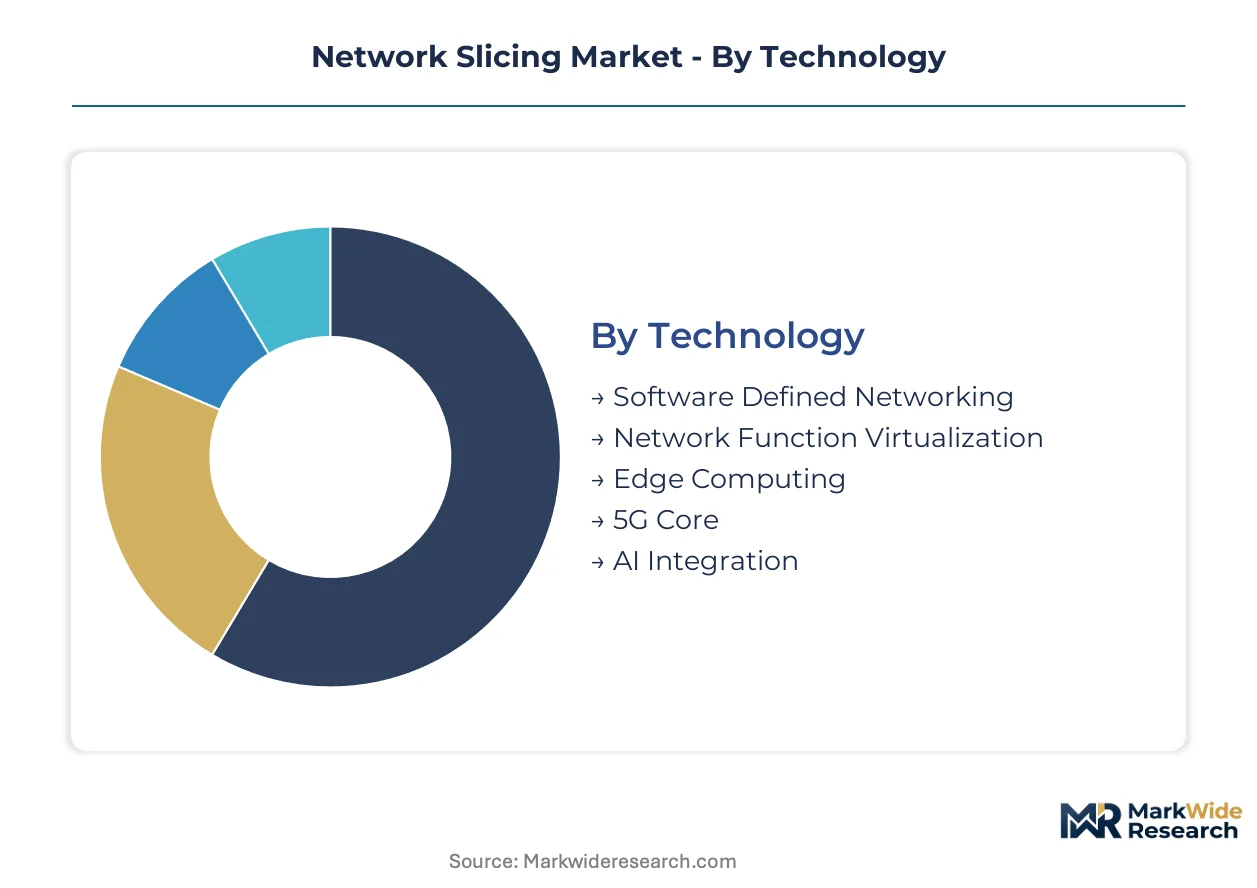
Network slicing architectures demand differentiated service delivery models across technical, operational, and commercial dimensions. Each segment category reflects distinct value capture mechanisms—from infrastructure deployment to ongoing orchestration services.
Technology:
After-sales service intensity varies dramatically across technology layers, with cloud-native components requiring continuous platform updates versus hardware-centric deployments.
- Software Defined Networking:Centralized control plane abstraction enables dynamic traffic engineering across transport networks. German automotive manufacturers prioritize SDN-enabled slices for deterministic factory floor connectivity under Industrie 4.0 mandates.
- Network Function Virtualization:Virtualized network functions deploy on commodity hardware, collapsing proprietary appliance dependencies. Telecom operators in Japan are consolidating vendor relationships around NFV-based core networks to reduce operational fragmentation.
- Edge Computing:Distributed compute nodes co-located with radio access equipment.
- 5G Core:Cloud-native service-based architecture enabling slice instantiation.
- AI Integration:Machine learning models for predictive resource allocation and anomaly detection.
NFV holds the largest share; momentum sits with Edge Computing.
Application:
Cost tier differentiation separates premium ultra-reliable configurations from standardized mass connectivity offerings.
- Ultra-Reliable Low Latency Communication:Sub-millisecond latency guarantees with 99.999% availability for mission-critical control systems. Remote surgery applications in South Korea and autonomous vehicle corridors in the United States command premium pricing for deterministic performance.
- Smart Cities:Integrated traffic management, public safety, and environmental monitoring slices. Municipal procurement in the United States is expanding most quickly as federal infrastructure funding flows to connected urban infrastructure.
- Enhanced Mobile Broadband:High-throughput consumer and enterprise connectivity.
- Massive IoT:Low-cost, low-power connectivity for dense sensor deployments.
- Private Networks:Enterprise-dedicated spectrum and infrastructure isolation.
Ultra-Reliable Low Latency Communication holds the largest share; momentum sits with Smart Cities.
End User:
Customer type determines procurement complexity, with facility operators requiring embedded engineering support versus wholesale service providers.
- Telecom Operators:Wholesale slice provisioning to enterprise and consumer segments. European operators are anchoring early commercial deployments through 3GPP Release 17 standardization investments.
- Manufacturing Facilities:Private network slices for real-time industrial automation. German manufacturers under the Industrie 4.0 framework represent the steepest expansion trajectory for guaranteed quality-of-service contracts.
- Cloud Service Providers:Hyperscale platform integration with network slicing orchestration.
- Transportation Operators:Connected highway and logistics corridor infrastructure.
- Energy Companies:Grid modernization and distributed generation control systems.
Telecom Operators hold the largest share; momentum sits with Manufacturing Facilities.
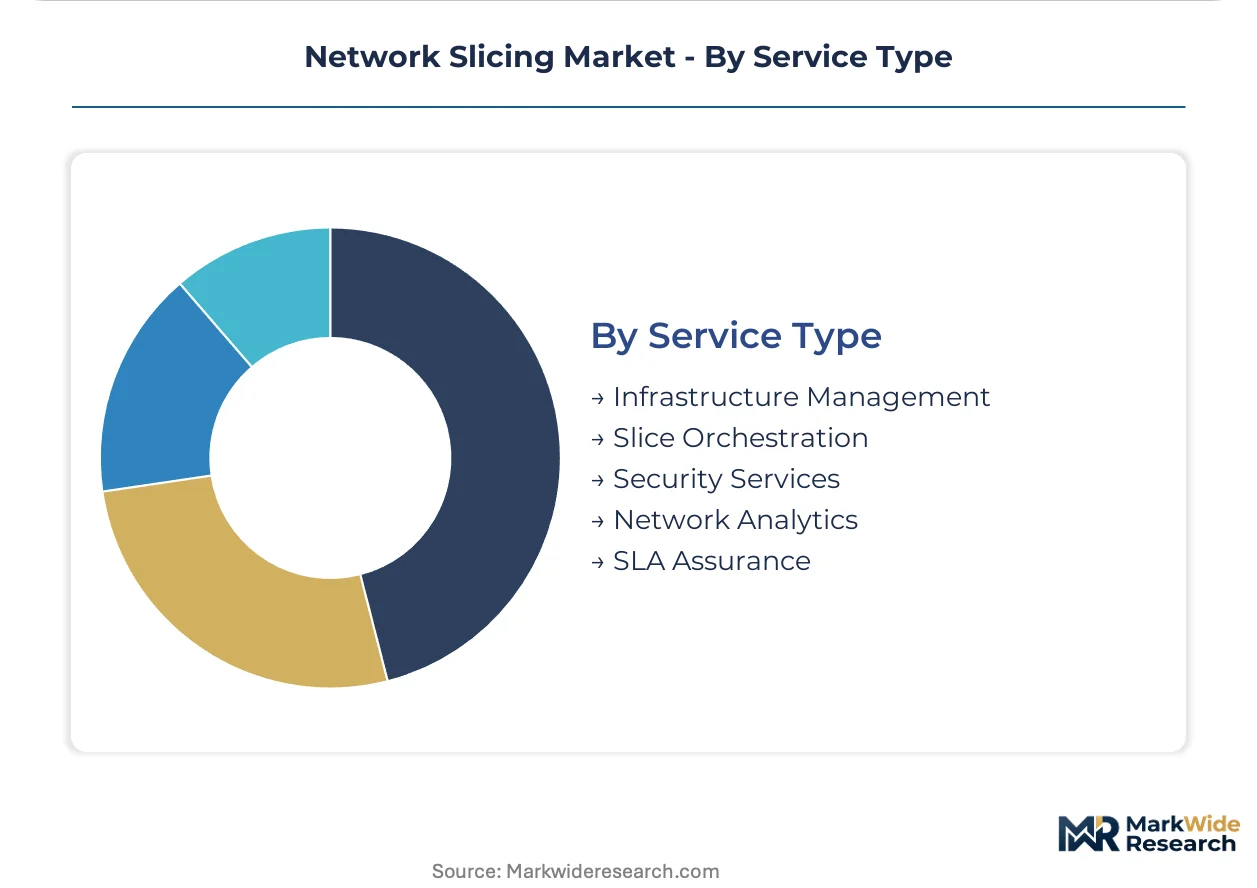
Service Type:
Margin concentration flows toward recurring orchestration and assurance services versus one-time infrastructure deployment.
- Slice Orchestration:Policy-driven lifecycle management spanning instantiation, modification, and termination. Vendors bundle dynamic resource adjustment into multi-year contracts with Japanese manufacturing conglomerates seeking single-source accountability.
- SLA Assurance:End-to-end quality monitoring with automated remediation workflows. Financial services firms in Singapore and healthcare networks in Switzerland are driving demand for contractual performance guarantees with penalty structures.
- Infrastructure Management:Physical and virtual resource provisioning and maintenance.
- Security Services:Per-slice isolation, encryption, and threat detection.
- Network Analytics:Usage pattern analysis and predictive capacity planning.
Slice Orchestration holds the largest share; momentum sits with SLA Assurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation equipment flows into manufacturing facilities across South Korea and Japan, establishing a trade corridor that shapes slice deployment patterns in Northeast Asia. Equipment vendors align certification timelines with destination market spectrum regulations.
United States
Transportation authorities in California and Texas are procuring dedicated slices for autonomous vehicle corridors on interstate highways. The FCC governs spectrum allocation rules that determine whether operators can dedicate licensed frequencies to enterprise slices. Detroit's automotive cluster demands ultra-reliable configurations for connected manufacturing lines.
Germany
Industrial manufacturers under the Industrie 4.0 framework are deploying private network slices for real-time factory control systems. The KBA coordinates vehicle-to-everything communication standards that intersect with slice performance requirements. Bavaria's manufacturing belt concentrates procurement for guaranteed quality-of-service contracts.
China
Smart city municipalities are integrating traffic management with public safety network slices in dense urban corridors. The MIIT mandates domestic certification for core network elements, creating market access conditions that favor local integration partners. Shenzhen's technology cluster drives edge computing convergence with slice orchestration systems.
Japan
Manufacturing conglomerates are awarding decade-long contracts to single-source infrastructure providers for integrated slice platforms. METI oversees industrial digitalization incentives that accelerate private network adoption. The Nagoya-Toyota industrial corridor exemplifies premium-tier procurement for mission-critical automation.
South Korea
Healthcare networks are deploying remote surgery applications commanding premium pricing for deterministic performance. The MFDS regulates medical device connectivity standards that shape slice reliability requirements. Seoul's digital health cluster anchors early commercial deployments of ultra-reliable low-latency configurations.
Network Slicing Market Key Industry Players
Channel-controlling players compete with product-specialist players across orchestration platforms and radio access domains. The vendor base concentrates around three strategic tiers: end-to-end infrastructure integrators, cloud-native software specialists, and regional equipment fabricators. Dominant competitive moves include strategic partnerships between telecom operators and industrial automation vendors, plus portfolio diversification into edge computing convergence.
Within the infrastructure integrator tier, Ericsson and Nokia exemplify European-origin players anchoring early commercial deployments through 3GPP standardization investments. Huawei occupies a position among vertically integrated equipment vendors with radio access and core network capabilities. These three represent distinct archetypes: standardization-driven R&D intensity, cloud-native orchestration specialization, and vertical integration across network layers.
| Leading Market Players |
|---|
| Cisco |
| Amdocs |
| Ericsson |
| Ciena Corporation |
| Samsung |
| Huawei |
| ZTE |
| HCL |
| Nokia |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Singapore fiber corridor carries optical transport equipment whose freight costs cascade through slice deployment economics, compressing margins for distributed radio unit deployments while amplifying price premiums for edge-integrated orchestration platforms. Supply concentration in baseband processor fabrication and core network virtualization stacks enables tiered pricing separation between hardware-centric infrastructure bundles and software-defined recurring service contracts.
Pricing Analysis
The 5G Non-Standalone to 5G Standalone generation gap commands a 40-60% premium for true slice isolation capabilities, with prior-generation equipment relegated to basic connectivity tiers and next-gen cloud-native stacks capturing orchestration-margin pools. Three-tier pricing structure across premium ultra-reliable configurations, standard enterprise slices, and economy-tier massive IoT offerings differentiates by latency guarantee and security certification grade. Pricing pressure stems from silicon supply constraints in advanced baseband fabrication, forcing cost absorption in mid-tier offerings. Manufacturing facilities under Industrie 4.0 mandates show lowest price sensitivity due to mission-critical automation requirements, while municipal smart city procurement exhibits highest sensitivity to total cost of ownership.
Supply Chain Analysis
Export control restrictions on 5G radio access equipment and virtualization infrastructure limit technology flows between Western and Chinese vendor ecosystems, fragmenting procurement options for multinational enterprises. Supply concentrates in Germany for industrial automation integration, South Korea for semiconductor components, and China for base station manufacturing. Raw material dependencies span gallium nitride substrates for radio frequency amplification, high-purity silicon for baseband processors, and specialized optical fiber for fronthaul transport. Single-source vulnerability pervades advanced node chip fabrication. Distribution runs through telecom operator procurement channels for wholesale slices and direct vendor relationships for private enterprise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G Standalone architecture transition constitutes a high-growth disruption, with 3GPP Release 17 standardization collapsing interoperability barriers that previously constrained enterprise adoption velocity.
For Market Incumbents: Pre-empt cloud-native orchestration platform consolidation by acquiring Kubernetes-based network function virtualization specialists before hyperscalers capture the integration layer. Defend against emerging software-defined networking pure-plays through backward integration into radio access equipment captive supply. Anchor position in German Industrie 4.0 procurement cycles through pre-certified security profiles aligned with EU Cybersecurity Act requirements.
For New Entrants and Emerging Players: Pursue slice orchestration software niches underserved by vertically integrated infrastructure vendors, particularly multi-vendor quality-of-service assurance tools. Target United States municipal smart city procurement as the most penetrable segment, where federal infrastructure funding outpaces vendor capacity. Deploy edge computing convergence as the primary go-to-market angle, bundling sub-ten-millisecond application response guarantees with slice instantiation services.
For Investors and Strategic Acquirers: Cloud-native orchestration pure-plays with DevOps-native engineering teams represent the highest-conviction acquisition archetype for medium-term value capture. Long-term viability hinges on 5G Standalone penetration rates across industrial automation and autonomous vehicle corridors. Watch cross-border spectrum harmonization progress under ETSI specifications as the inflection signal for multinational enterprise contract scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Orchestration Platform Launch | Ericsson and Nokia compete through Kubernetes-based slice lifecycle management automation. |
| Edge Computing Convergence Partnership | Multi-access edge computing integration enables sub-ten-millisecond augmented reality response guarantees. |
| 3GPP Release 17 Certification Investment | Cross-operator slice roaming capabilities unlock multinational enterprise contract expansion. |
| Private Network Slice Managed Service | Japanese manufacturing conglomerates award decade-long single-source infrastructure accountability contracts. |
| EU Cybersecurity Act Pre-Certification | German industrial manufacturers prioritize Common Criteria evaluation assurance for procurement acceleration. |
Research Approach
Operator-level perspectives from telecom network architects, industrial automation engineers, municipal procurement officers, and cloud infrastructure specialists anchored the qualitative base for this analysis. Primary interviews combined with secondary validation across 3GPP technical specifications, FCC spectrum allocation filings, ETSI interoperability standards, and MIIT certification protocols. Bottom-up deployment projections triangulated against top-down infrastructure spending forecasts from national digitalization programs.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling technology segmentation by software-defined networking, network function virtualization, edge computing, and 5G core architecture layers. Application dimensions spanned ultra-reliable low-latency communication, smart cities, enhanced mobile broadband, massive IoT, and private networks. End-user categories incorporated telecom operators, manufacturing facilities, cloud service providers, transportation operators, and energy companies. CAGRs derived from deployment velocity curves weighted by spectrum auction timelines and industrial automation mandate compliance deadlines.
Macroeconomic conditions sit as an overlay; deviation in infrastructure capital expenditure cycles or semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions regarding 3GPP standardization adoption rates and cross-border regulatory alignment. Material shifts in export control regimes or national spectrum allocation policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Europe Subscriber Data Management Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Hong Kong Data Center Networking Market