
 Japan Geographic Information System (GIS) Market | 2026-2036
Japan Geographic Information System (GIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Geographic Information System (GIS) Market Intelligence
Modular service bundling is rebalancing buyer choice across the Japan GIS landscape. NTT DATA Corporation leverages its telecommunications backbone to integrate fiber network data with municipal geospatial platforms. PASCO Corporation anchors its position through specialized aerial survey capabilities tied to disaster response contracts. Esri Japan competes by localizing cloud-based analytics tools for prefectural government workflows.
A geographic information system captures, stores, manipulates, analyzes, and presents spatial data referenced to Earth coordinates, typically operating through layered vector and raster architectures with sub-meter accuracy for cadastral applications. Its primary commercial purpose is enabling location-based decision-making for asset management, risk assessment, and service delivery optimization. Remote sensing and 3D mapping together command the technology dimension as satellite imagery resolution improves and LiDAR costs decline. Cloud-based deployment shows the steepest trajectory among implementation modes as METI guidelines encourage shared infrastructure across prefectures. Government agencies remain the dominant end-user channel, though utility companies represent the fastest-expanding procurement segment as deregulation forces grid modernization.
METI sets digital infrastructure standards while JIS committees govern data format interoperability for geospatial platforms across Japanese jurisdictions. The Geospatial Information Authority of Japan mandates baseline topographic accuracy thresholds that shape vendor certification requirements and public-sector tender eligibility. PMDA's emerging interest in location-linked health surveillance adds a cross-sector compliance layer for GIS providers entering medical geography. Stakeholders must track whether forthcoming prefectural data sovereignty rules fragment cloud deployment options or consolidate vendor consolidation pressure.
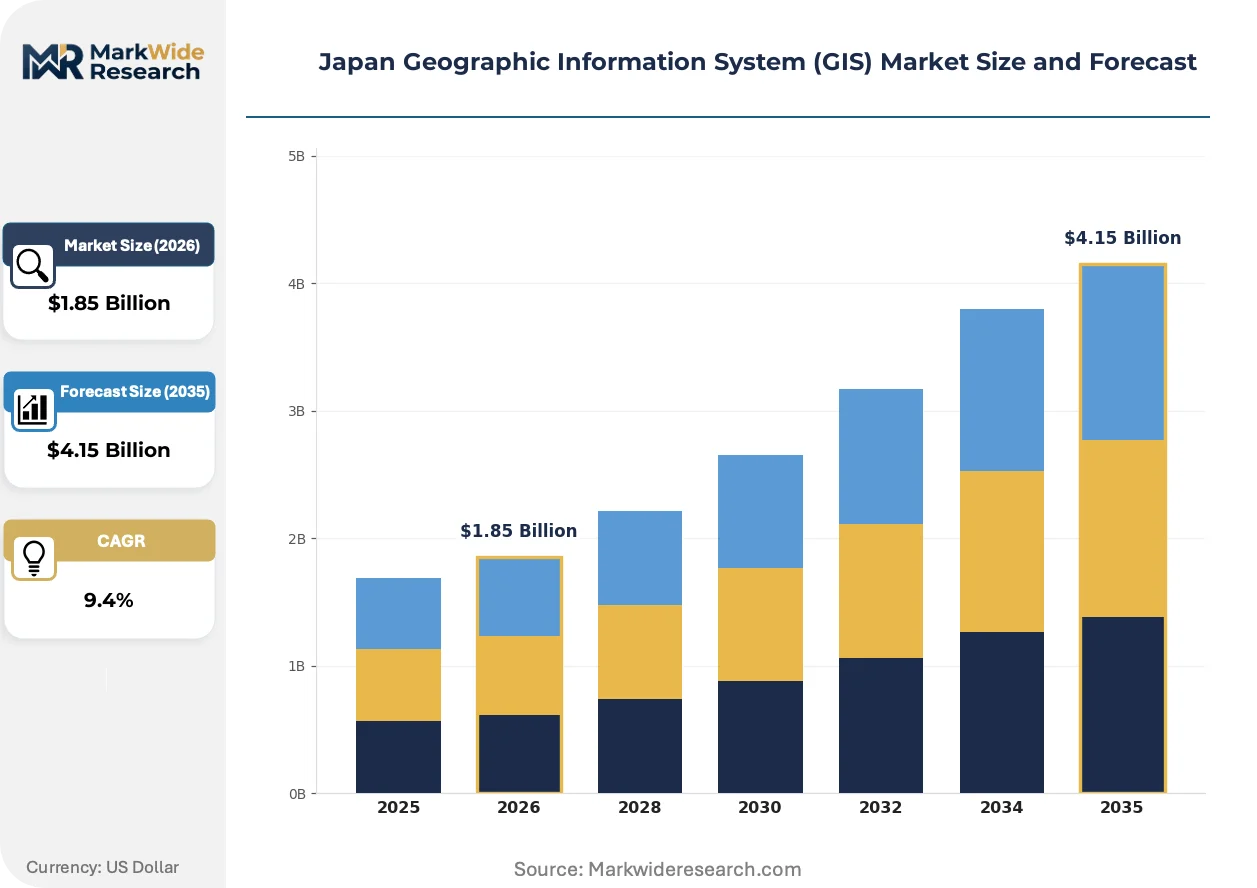
Market Dynamics
METI's digital twin standardization mandate is compressing procurement cycles across municipal governments, forcing legacy platform vendors to re-architect interoperability layers or face exclusion from prefectural tenders.
Growth Catalysts
- Flood-risk mapping mandates:Municipal governments across Honshu prefectures now require geospatial platforms for disaster preparedness infrastructure, expanding software licensing volumes.
- Pipeline network modernization:Utility companies in the Tokyo-Osaka corridor deploy LiDAR-enabled asset tracking to replace paper-based maintenance records for aging gas and water infrastructure.
- Cloud infrastructure subsidies:METI guidelines incentivize shared geospatial platforms across prefectural boundaries, reducing per-agency deployment costs.
Market Restraints
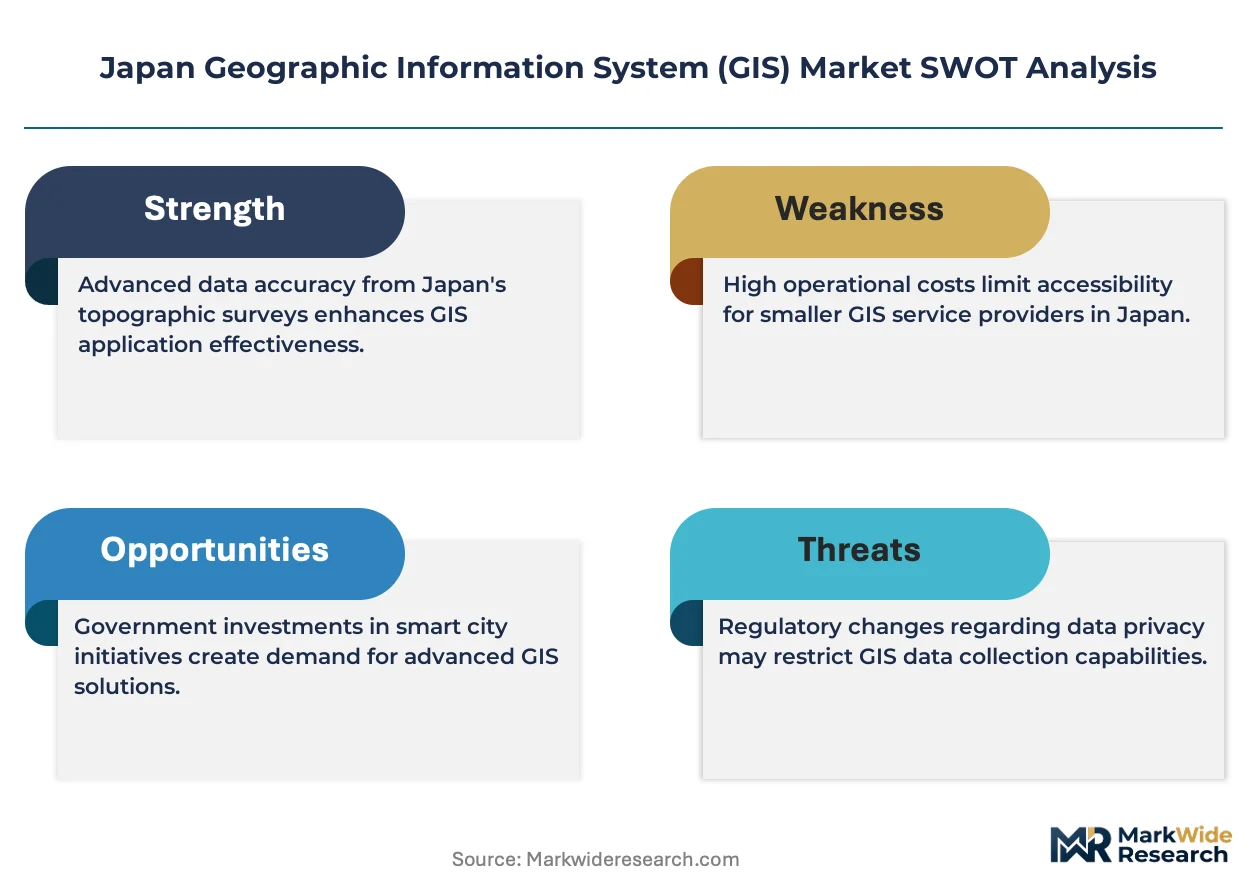
- LiDAR sensor cost volatility:Aerial survey providers face margin pressure from import-dependent hardware supply chains concentrated in East Asian manufacturing hubs.
- Data sovereignty fragmentation:Emerging prefectural rules on cloud data residency create compliance complexity for multi-jurisdiction platform deployments.
- Interoperability certification delays:JIS committee review timelines extend vendor qualification periods, slowing new entrant market access.
Strategic Opportunities
- Hokkaido agricultural digitization:Precision farming adoption remains underpenetrated in northern prefectures, creating whitespace for soil-monitoring GIS integrations.
- Health geography convergence:PMDA's emerging location-linked surveillance frameworks open medical geography applications for existing municipal platform vendors.
- 5G network mapping:Telecommunications infrastructure rollouts require sub-meter accuracy geospatial databases, pulling fiber network data into unified platforms.
Industry Challenges
- Geomatics talent scarcity:Specialized surveying expertise shortages constrain project scaling for disaster response contracts with tight delivery windows.
- Legacy system integration friction:Decades-old municipal CAD archives resist automated conversion to modern vector-raster hybrid architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Geographic Information System (GIS) Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Management, Agriculture, Disaster Response Technology: Remote Sensing, Spatial Analysis, Data Visualization, 3D Mapping End User: Government Agencies, Research Institutions, Utility Companies, Private Sector Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Mobile GIS |
| Companies Covered | ASIA AIR SURVEY CO., LTD., NTT DATA Corporation, PASCO Corporation, NEC Corporation, Hitachi Solutions, Ltd., Esri Japan, Kokusai Kogyo Co., Ltd., Zenrin Co., Ltd., Hexagon AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Geographic Information System (GIS) Market Strategic Shifts & Innovations
Three interconnected shifts are restructuring how geospatial value gets created and captured across Japanese jurisdictions, from acquisition hardware through analytics delivery.
AI-assisted feature extraction from satellite imagery is overtaking manual photogrammetry workflows in prefectural mapping departments. Tokyo and Osaka metropolitan governments now mandate automated building-footprint detection for annual tax assessment updates. Compression of production timelines from months to weeks is overtaking traditional survey contractor business models.
METI's 2023 digital infrastructure guidelines now require API-first platform architectures for all new municipal procurements above threshold values. This industrial consequence forces incumbent vendors to expose previously proprietary data formats. Prefectural IT departments respond by consolidating vendor panels around interoperability-certified providers.
Subscription-based platform access is displacing perpetual license purchases among mid-sized municipal governments. Annual recurring revenue models now dominate procurement conversations in Kyushu and Shikoku regional cities. This shift concentrates buyer power with prefectural-level negotiating bodies rather than individual agency purchasing departments.
Japan Geographic Information System (GIS) Market Segmentation
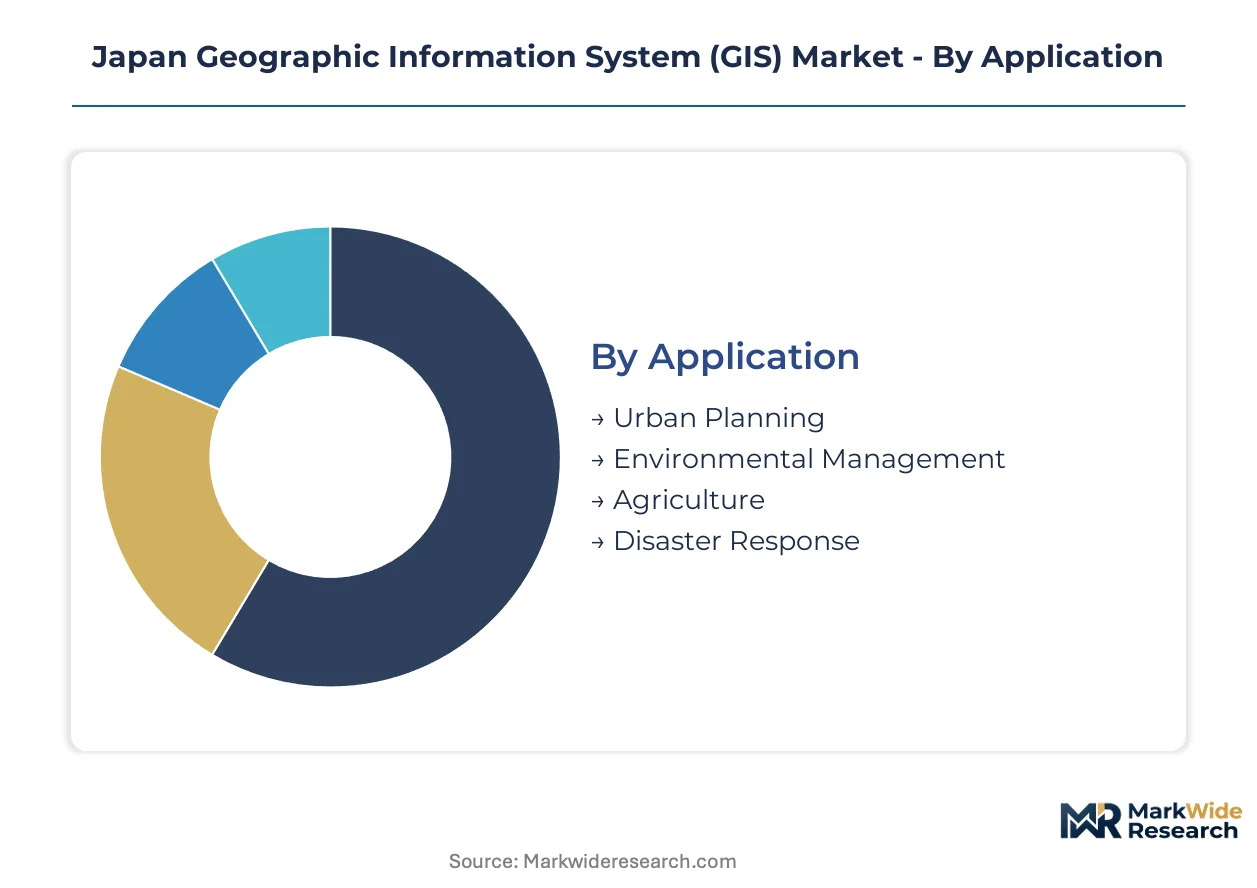
GIS procurement patterns in Japan diverge sharply across application domains and deployment modes. Municipal governments prioritize flood-risk infrastructure while utilities drive precision asset tracking, creating distinct capability requirements that vendors must address through specialized platform configurations.
Application:
Buyer differentiation in this category stems from regulatory mandate intensity versus discretionary investment capacity.
- Urban Planning:Zoning compliance and land-use optimization tools dominate procurement specifications. Tokyo and Osaka metropolitan governments mandate automated building-footprint detection for property tax assessment workflows, compressing survey contractor delivery timelines from months to weeks.
- Disaster Response:Real-time hazard visualization and evacuation route modeling define platform requirements. Honshu prefectures now require geospatial infrastructure for flood-risk mapping under revised civil protection guidelines, expanding software licensing volumes across municipal IT departments.
- Environmental Management:Emissions tracking and ecosystem monitoring applications serve METI carbon accounting mandates.
- Agriculture:Precision farming adoption remains concentrated in Hokkaido soil-monitoring deployments, with whitespace opportunity in northern prefecture digitization.
Volume sits with Urban Planning; growth tilts toward Disaster Response.
Technology:
Capability maturity separates established surveying workflows from emerging AI-augmented processing layers.
- Remote Sensing:Satellite imagery acquisition and aerial photogrammetry form the foundational data layer. Improving sub-meter resolution and declining LiDAR hardware costs are displacing manual feature extraction in prefectural mapping departments.
- 3D Mapping:LiDAR-enabled point cloud generation and digital twin construction command premium platform pricing. Utility companies in the Tokyo-Osaka corridor deploy these tools for aging pipeline network modernization, replacing paper-based maintenance records with geospatial asset tracking.
- Spatial Analysis:Geoprocessing engines and predictive modeling modules support location-based decision automation.
- Data Visualization:Dashboard and reporting interfaces serve non-technical municipal stakeholders.
Revenue concentrates in Remote Sensing; 3D Mapping is climbing the fastest.
End User:
Budget scale and procurement autonomy create tiered service expectations across buyer types.
- Government Agencies:Prefectural and municipal IT departments dominate tender volumes with standardized interoperability requirements. METI digital twin guidelines and JIS certification mandates shape vendor qualification criteria and public-sector eligibility.
- Utility Companies:Gas, water, and electricity network operators represent the most rapidly expanding procurement segment. Deregulation pressures and grid modernization investments pull fiber network data into unified geospatial platforms with sub-meter accuracy specifications.
- Research Institutions:Academic and scientific users drive specialized analytics tool development.
- Private Sector:Logistics and real estate firms adopt location intelligence for competitive positioning.
Contract value peaks with Government Agencies; Utility Companies are gaining share fastest.
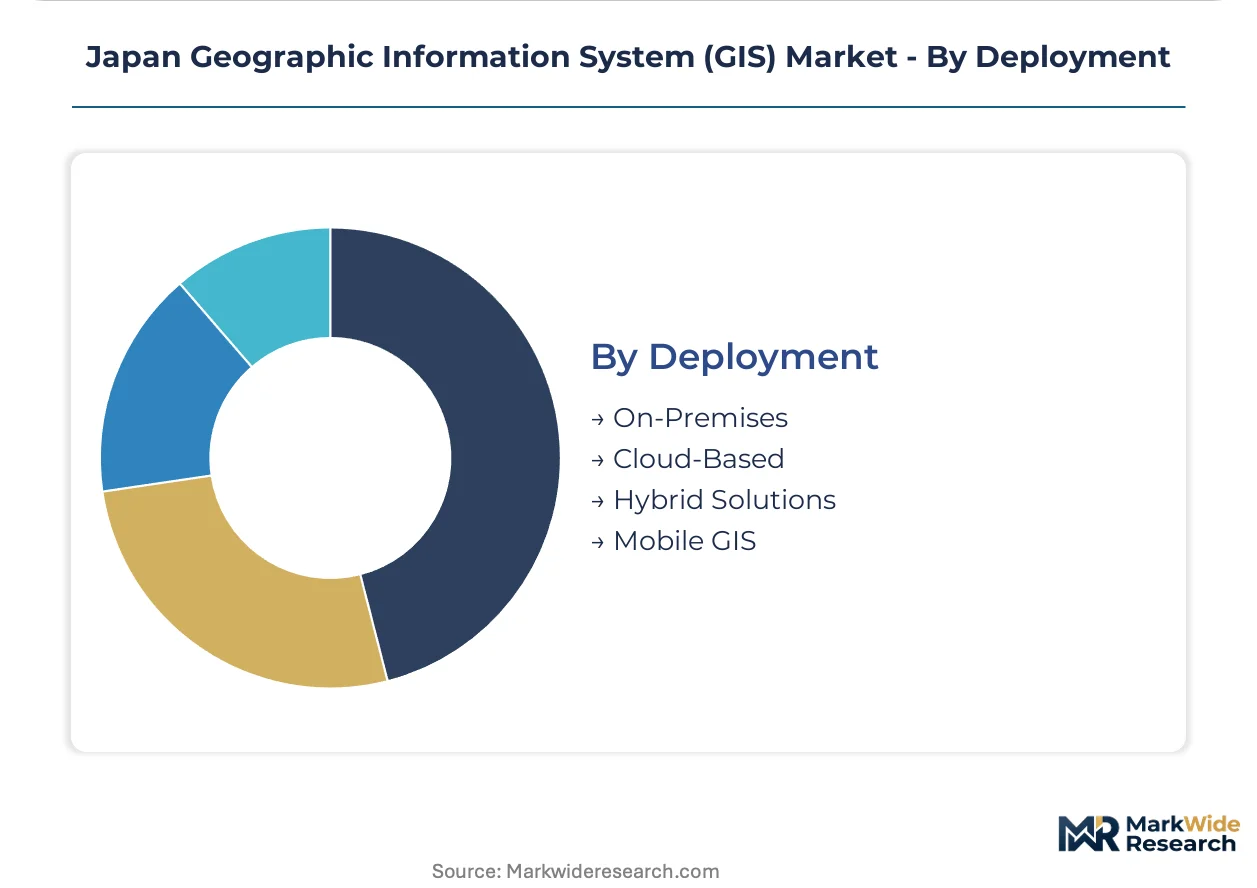
Deployment:
Infrastructure ownership preferences segment buyers between capital expenditure control and operational flexibility.
- Cloud-Based:Shared platform access across prefectural boundaries reduces per-agency deployment costs under METI subsidy frameworks. Subscription models now dominate procurement conversations in Kyushu and Shikoku regional cities, concentrating buyer power with prefectural-level negotiating bodies.
- On-Premises:Dedicated server installations persist in agencies with stringent data residency requirements. Emerging prefectural rules on cloud data residency create compliance complexity that sustains demand for localized infrastructure despite higher total cost of ownership.
- Hybrid Solutions:Mixed architectures balance sensitive data local storage with scalable processing in shared environments.
- Mobile GIS:Field-deployable applications serve disaster response teams and utility inspection crews requiring offline functionality.
Installed base remains with On-Premises; Cloud-Based deployment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's GIS production concentrates in the Tokyo-Osaka corridor while consumption spreads across Honshu's municipal governments and northern prefectures seeking agricultural digitization.
Kanto/Tokyo
Tokyo metropolitan government mandates automated building-footprint detection for annual property tax assessments, compressing survey contractor delivery timelines. METI digital twin guidelines require API-first platform architectures for all municipal procurements above threshold values. The capital's utility companies deploy sub-meter accuracy geospatial databases for fiber network modernization under deregulation pressures.
Kansai/Osaka
Osaka prefectural governments drive cloud-based GIS adoption through shared infrastructure subsidies, reducing per-agency deployment costs. JIS certification mandates shape vendor qualification criteria for public-sector tenders. The Osaka-Kobe industrial cluster anchors LiDAR-enabled asset tracking for aging pipeline network replacement.
Chubu/Nagoya
Nagoya's manufacturing base generates precision mapping demand for supply chain optimization and facility management. The central region's municipal IT departments consolidate vendor panels around interoperability-certified providers. Toyota's surrounding industrial ecosystem pulls geospatial analytics into logistics and distribution network planning.
Kyushu
Regional cities across Kyushu now favor subscription-based platform access over perpetual license purchases. Annual recurring revenue models concentrate buyer power with prefectural-level negotiating bodies. Fukuoka's emerging tech sector drives mobile GIS adoption for field-deployable disaster response applications.
Hokkaido
Precision farming adoption remains underpenetrated in Japan's northernmost prefecture, creating whitespace for soil-monitoring GIS integrations. Agricultural cooperatives seek geospatial platforms for crop yield optimization and land-use planning. Sapporo's municipal government experiments with hybrid cloud architectures balancing data residency requirements with scalable processing.
Japan Geographic Information System (GIS) Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Japan's GIS procurement landscape. Tiered market structure emerges between telecommunications-integrated platforms, aerial survey contractors, and localized software vendors. Three strategic archetypes dominate: infrastructure-backed systems integrators, specialized geomatics service providers, and global platform localizers. Competitive moves center on METI interoperability certification acquisition and prefectural panel consolidation through shared cloud infrastructure bids.
Within the telecommunications-integrated tier, NTT DATA Corporation represents infrastructure-backed platform deployment. PASCO Corporation and Esri Japan exemplify contrasting specialization models—survey-centric services versus localized cloud analytics. These three anchors illustrate how vendor qualification criteria under JIS and METI frameworks reshape competitive positioning across municipal tender processes.
| Leading Market Players |
|---|
| ASIA AIR SURVEY CO., LTD. |
| NTT DATA Corporation |
| PASCO Corporation |
| NEC Corporation |
| Hitachi Solutions, Ltd. |
| Esri Japan |
| Kokusai Kogyo Co., Ltd. |
| Zenrin Co., Ltd. |
| Hexagon AB |
| Others |
Cost & Logistics Intelligence
Captive in-house production of LiDAR processing modules anchors pricing power for established Japanese GIS vendors while squeezing margins for survey contractors dependent on imported hardware. METI's interoperability certification requirements compound this dynamic by privileging vertically integrated platform providers over specialized component assemblers in prefectural tender processes.
Pricing Analysis
Margin tightening in the aerial survey tier reflects import-dependent LiDAR sensor supply chains concentrated in East Asian manufacturing hubs. Subscription-based SaaS pricing now dominates municipal procurement in regional cities, compressing upfront license revenues while extending customer lifetime value for certified platform vendors. Price differentiation rests on JIS certification grade and after-sales integration support, with prefectural IT departments showing lowest sensitivity due to consolidated negotiating power.
Supply Chain Analysis
Freight cost volatility on semiconductor components from Taiwan and South Korea disrupts delivery schedules for geospatial processing hardware. LiDAR sensors, GPS modules, and high-resolution imaging chips draw from concentrated East Asian manufacturing centers, exposing vendors to single-source vulnerability when customs delays hit critical survey seasons. Distribution runs through systems integrators with METI certification rather than direct vendor-to-agency sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where METI's digital twin standardization mandate erects a certification barrier that rewards incumbent investment in interoperability architecture while filtering out undercapitalized challengers.
For Market Incumbents: To counter cloud-native entrants from telecommunications integrators, deepen proprietary data format conversion capabilities for legacy municipal CAD archives and secure JIS committee participation to influence emerging prefectural data sovereignty rules. Certification investment in API-first architectures represents the critical defensive lever. For New Entrants and Emerging Players: Cloud-based platform partnerships with regional telecommunications providers offer the most viable route around incumbent survey-contractor relationships. Hokkaido's underpenetrated precision farming segment and Kyushu's subscription-ready municipal governments present accessible whitespace, with health geography convergence under PMDA frameworks offering a differentiated application wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to infrastructure-backed systems integrators seeking geomatics capabilities. Long-term viability favors vendors with captive LiDAR processing capacity and established prefectural panel positions. Watch for METI digital infrastructure guideline revisions as the signal indicating consolidation acceleration or new entrant opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Investment | Qualification for prefectural tenders above METI threshold values locks in revenue visibility. |
| Legacy CAD Archive Conversion | Automated migration tools capture municipal modernization budgets and displace manual contractors. |
| Cloud Infrastructure Partnership | Shared platform access reduces per-agency deployment costs under METI subsidy frameworks. |
| Health Geography Platform Extension | PMDA location-linked surveillance frameworks open medical applications for municipal vendors. |
| LiDAR Processing Verticalization | In-house sensor integration buffers margin pressure from East Asian hardware supply chains. |
Research Approach
Independent corroboration across prefectural IT procurement officers, utility asset management directors, and aerial survey operations managers underwrites the qualitative findings. Primary fieldwork with METI policy specialists and JIS committee participants combined with secondary validation from METI digital infrastructure guidelines, Geospatial Information Authority of Japan accuracy mandates, and municipal tender databases. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-checked for consistency.
Rate-of-change decomposition across technology adoption curves, regulatory implementation timelines, and procurement cycle compression shaped the analytical framework. Segmentation dimensions modeled include deployment mode, end-user type, application domain, and technology maturity tier. CAGRs were derived from historical procurement volume trajectories and policy-mandated spending floors, with METI subsidy eligibility criteria and JIS certification timelines serving as industry-specific forecast inputs.
The model holds under stable regulatory implementation schedules; deviation in prefectural data sovereignty rule fragmentation or LiDAR import tariff shifts would shift platform deployment trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market