
 Cache Server Market | 2026-2036
Cache Server Market Size, Share, and Industry Trends Forecast 2026-2036
Cache Server Market Outlook
Market Context
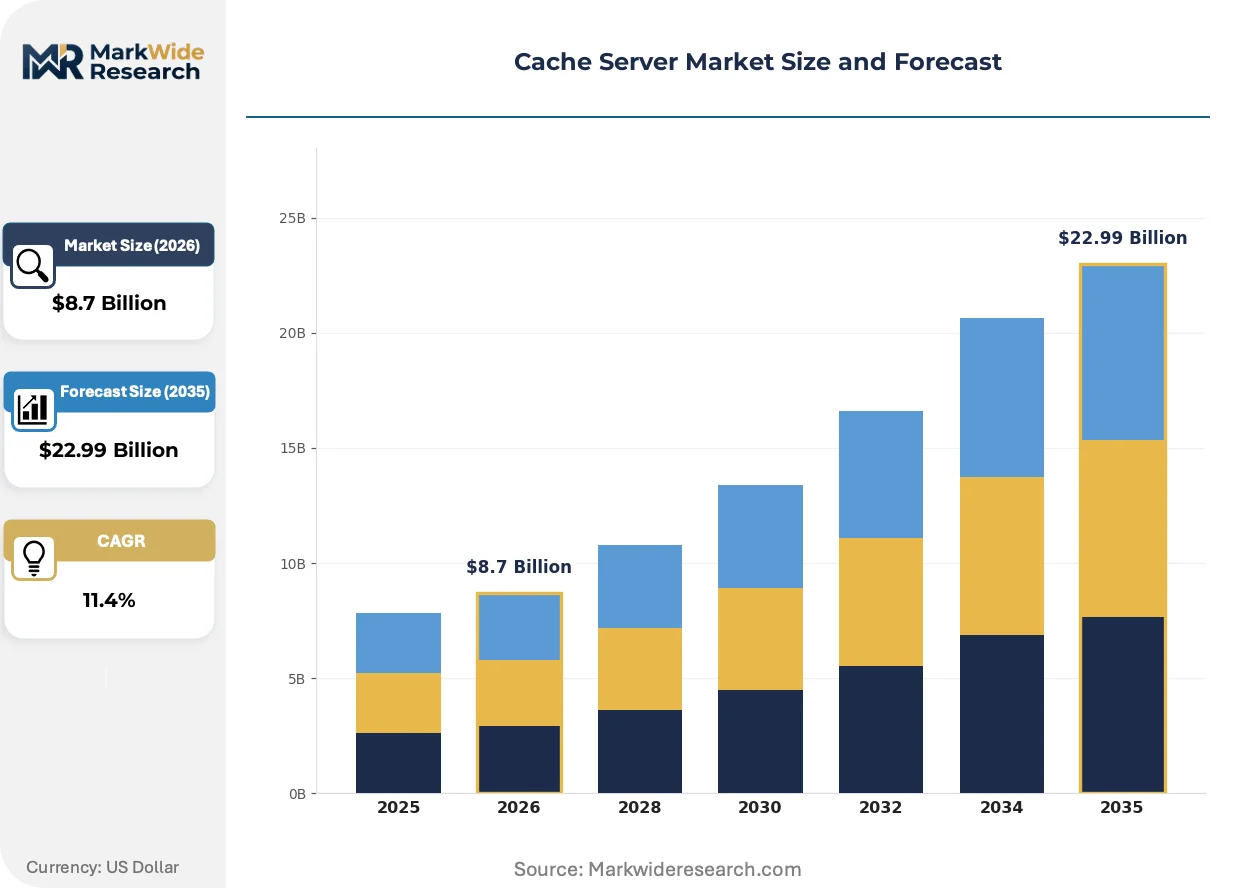
India's data center corridor is tilting toward cache server densification as Mumbai and Hyderabad add hyperscale capacity. Amazon Web Services (AWS) anchors South Asian infrastructure through localized edge nodes and dedicated cache tiers. Cloudflare competes with a freemium-to-enterprise model that extends into tier-two Indian cities. Akamai Technologies dominates premium content delivery through its managed cache fabric and direct carrier relationships.
Technical Definition and Structural Segments
A cache server is a dedicated network appliance or software instance that stores copies of frequently accessed data in high-speed memory or solid-state storage, typically delivering sub-millisecond response times for read-heavy workloads while reducing origin server load and bandwidth consumption. Cloud-based deployment leads solution type adoption as enterprises migrate from on-premise hardware to elastic, consumption-priced cache tiers; in-memory caching sustains the fastest growth trajectory due to real-time analytics and personalization engine requirements. Financial services end users concentrate margin pools around low-latency distributed cache configurations, while e-commerce drives volume through seasonal scaling demands.
Regulatory Frame and Outlook
India's Ministry of Electronics and Information Technology enforces data localization mandates that require cache nodes within national boundaries, reshaping vendor architecture decisions. The EU GDPR and AI Act impose cross-border data flow restrictions and algorithmic transparency requirements that complicate distributed cache topologies spanning European and Asian nodes. Stakeholders must monitor evolving sovereignty rules to determine whether regional cache fragmentation or unified global fabrics offer superior risk-adjusted returns.
Market Dynamics
Edge computing architectures are fragmenting centralized cache topologies as hyperscalers deploy micro-nodes closer to end users, forcing vendors to re-engineer software stacks for distributed consistency models.
Growth Catalysts
- EU AI Act compliance:Algorithmic transparency mandates accelerate edge-based caching deployments across European financial services and healthcare data pipelines.
- Video streaming infrastructure:Live sports and gaming platforms drive sub-50ms latency requirements that only localized cache clusters can satisfy.
- India's data localization:MeitY mandates require in-country cache nodes, compelling infrastructure expansion across Mumbai, Hyderabad, and Chennai corridors.
Market Restraints
- DDR5 memory pricing volatility:Cache hardware margins compress when high-bandwidth memory contract rates spike, particularly affecting on-premise appliance vendors.
- Taiwan semiconductor concentration:Advanced packaging for cache-optimized processors relies on a concentrated foundry base, creating supply vulnerability.
- GDPR cross-border friction:Distributed cache topologies spanning European and Asian nodes face operational complexity from data residency enforcement.
Strategic Opportunities
- Brazil's underpenetrated fintech sector:PIX real-time payment infrastructure creates demand for low-latency cache layers in São Paulo and Rio de Janeiro data centers.
- AI inference edge convergence:Model serving workloads are hybridizing with traditional content caching, opening unified platform architectures.
- EU Green Deal incentives:Energy-efficient cache hardware qualifies for sustainable infrastructure tax credits in Germany and France.
Industry Challenges
- Distributed systems engineering talent scarcity:Cache consistency protocol expertise concentrates at hyperscalers, constraining mid-market vendor hiring pipelines.
- Legacy mainframe integration:Financial institutions struggle to synchronize modern cache layers with COBOL-based core banking systems without data integrity risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cache Server Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Type: In-Memory Caching, Database Caching, Content Delivery Network, Distributed Cache End User: E-Commerce, Gaming, Telecom, Financial Services Technology: Memcached, Redis, Apache Ignite, Ehcache |
| Companies Covered | Microsoft Azure, Fastly, Akamai Technologies, Varnish Software, StackPath, Cloudflare, Google Cloud Platform, Nginx, Amazon Web Services (AWS), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cache Server Market Strategic Shifts
Cache infrastructure is converging with AI inference pipelines and sustainability mandates, reshaping hardware design priorities and procurement criteria across enterprise and cloud-native segments.
Software-defined cache fabrics are hybridizing storage-class memory with traditional DRAM hierarchies, enabling tiered hot-warm-cold data placement within single-node architectures. Automotive autonomous driving programs adopt these configurations for real-time map and sensor fusion workloads. The structural consequence is compression of dedicated cache appliance demand as software stacks absorb hardware functions.
REACH chemical restrictions and F-Gas Regulation phase-downs are forcing coolant redesigns for high-density cache servers, particularly affecting liquid-cooled deployments in Frankfurt and Amsterdam data center clusters. Vectors of compliance cost concentrate in hyperscale buildouts where power density exceeds air-cooling thresholds.
Consumption-based cache pricing is displacing perpetual licensing across enterprise buyers, with annual commits replacing three-year hardware refresh cycles. Systems integrators and managed service providers capture margin from this transition in North American financial services verticals. Germany and Japan exhibit strongest resistance due to capital expenditure preference in regulated industries.
Cache Server Market Segmentation
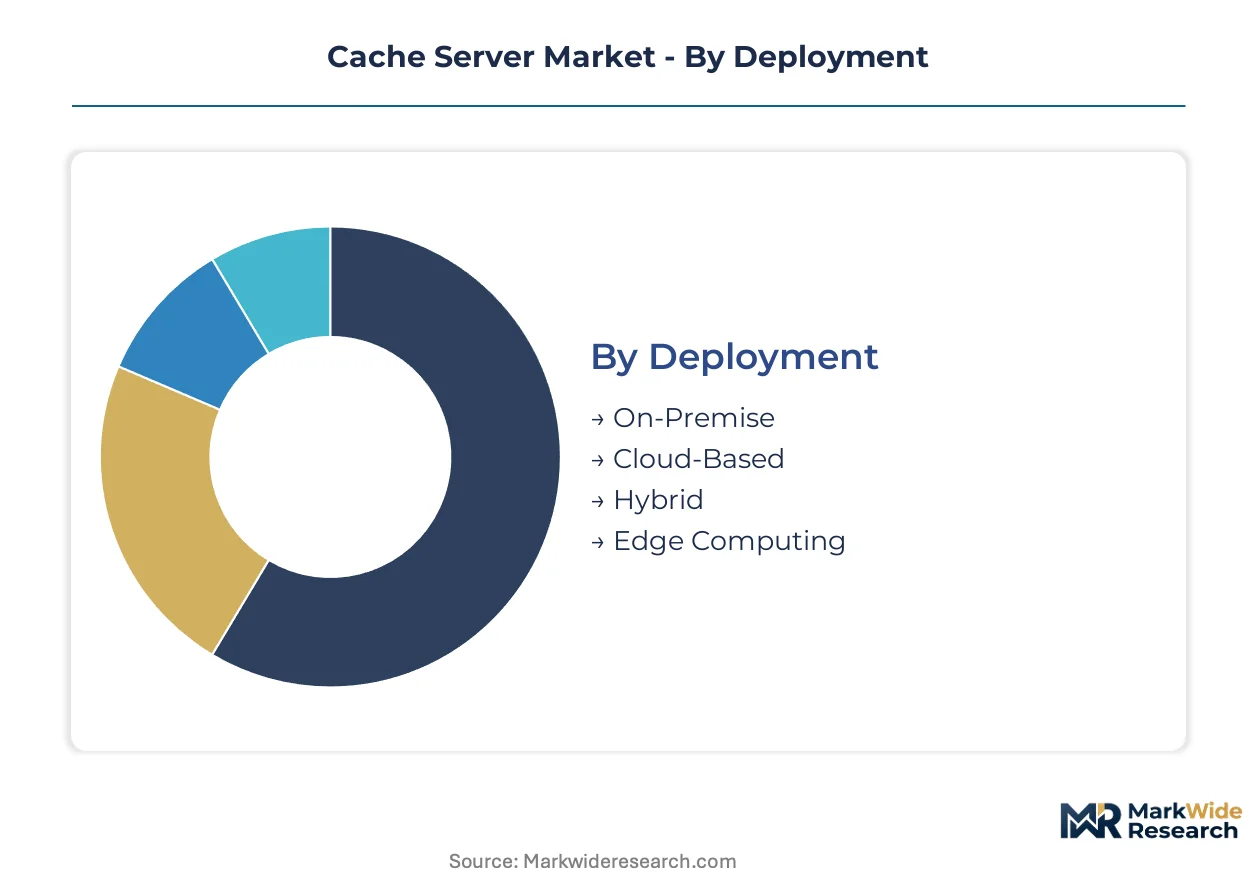
Cache server segmentation reveals distinct procurement patterns across deployment models, solution architectures, and technology stacks. Each dimension carries specific regulatory, latency, and cost implications that reshape vendor competitive positioning.
Deployment:
Use cases span sovereign data requirements to elastic consumption models, with latency sensitivity and compliance mandates driving architectural choice.
- Cloud-Based:Elastic cache tiers provisioned through hyperscale providers enable consumption-priced scaling without capital commitment. E-commerce platforms in Germany leverage these configurations for seasonal demand spikes while maintaining EU AI Act audit trails.
- Edge Computing:Micro-nodes deployed within 10 kilometers of end users deliver sub-10ms response for autonomous vehicle telemetry and real-time gaming. Frankfurt's data center cluster anchors European edge cache density due to interconnection richness.
- On-Premise:Dedicated hardware within enterprise facilities serves financial institutions with RBI-mandated data localization in Mumbai and Hyderabad corridors.
- Hybrid:Split architectures synchronize hot-tier edge caches with cold-tier cloud storage, common among telecom operators managing 5G user plane traffic.
The dominant share belongs to Cloud-Based deployments, while Edge Computing is closing the gap fastest.
Solution Type:
Performance requirements and data structure complexity determine solution selection across transactional and analytical workloads.
- In-Memory Caching:DRAM-based storage delivers microsecond access for real-time personalization engines and fraud detection pipelines. Financial services in São Paulo deploy these layers for PIX real-time payment authorization.
- Content Delivery Network:Globally distributed edge caches optimize video streaming and static asset delivery. Live sports platforms in Brazil and India drive capacity expansion for sub-50ms latency guarantees.
- Distributed Cache:Partitioned data structures across multiple nodes serve microservices architectures with high availability requirements.
- Database Caching:Query result caching reduces relational database load for legacy mainframe integration scenarios in North American banking.
In-Memory Caching commands premium pricing, with Content Delivery Network solutions expanding most quickly.
End User:
Vertical-specific latency thresholds and regulatory exposure shape procurement criteria and vendor selection.
- Financial Services:Distributed cache configurations with synchronous replication satisfy low-latency trading and regulatory audit requirements. GDPR and EU AI Act compliance drive edge-based deployments across Frankfurt and Amsterdam clusters.
- E-Commerce:Seasonal scaling demands and personalization engine requirements favor cloud-based elastic tiers with annual commit pricing.
- Gaming:Real-time multiplayer synchronization and asset streaming concentrate demand in São Paulo and Mumbai edge nodes.
- Telecom:5G core network functions and subscriber data management require hybrid deployments with strict national boundary enforcement.
Financial Services generates the highest margin pool, while Gaming shows the steepest expansion trajectory.
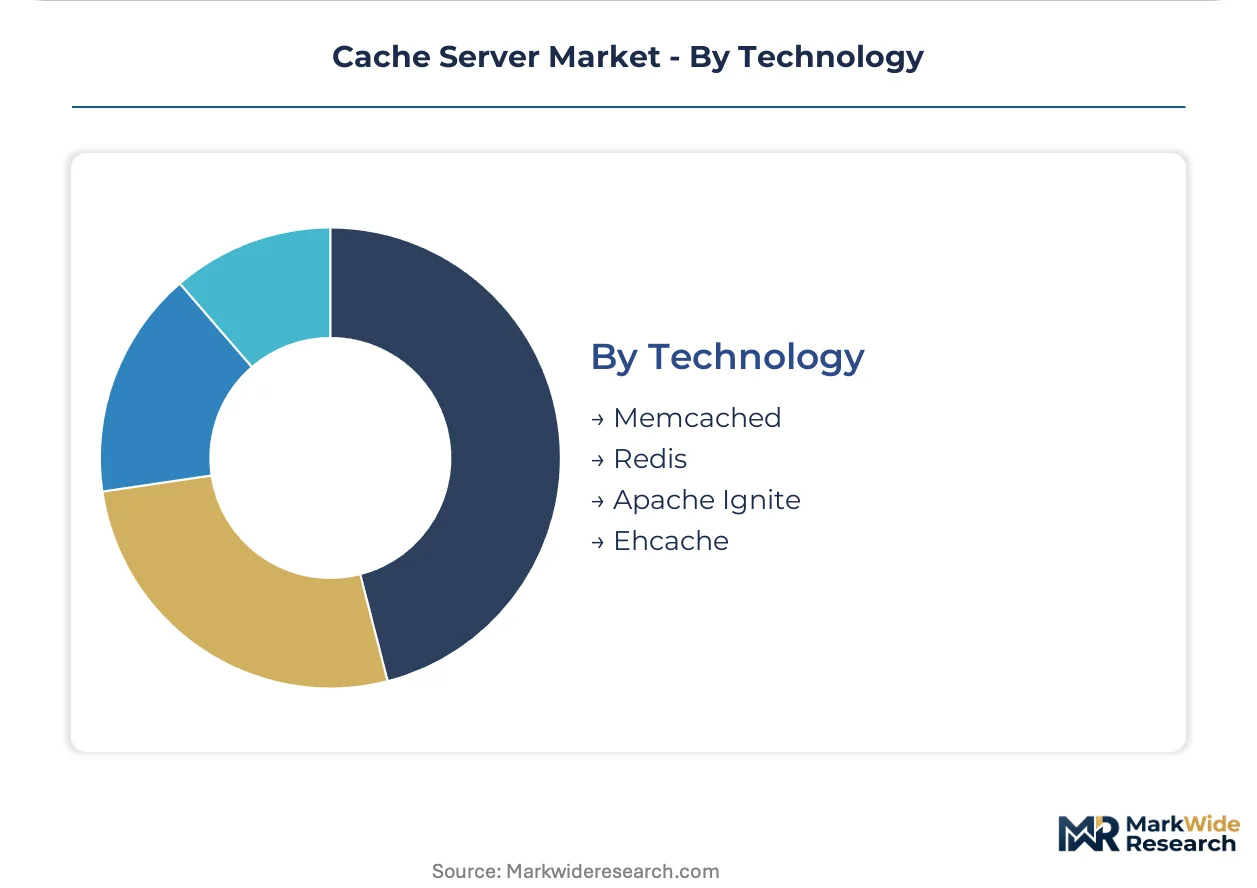
Technology:
Open-source foundations dominate with commercial support tiers, though performance characteristics diverge across data structure and persistence models.
- Redis:In-memory data structure store supporting strings, hashes, streams, and geospatial indexes with optional persistence. German automotive programs adopt Redis Enterprise for autonomous driving map tile caching.
- Memcached:Simple key-value store optimized for small object caching with minimal overhead. E-commerce volume deployments favor its memory efficiency for session state management.
- Apache Ignite:Memory-centric distributed database, caching, and processing platform. Financial services deploy for ACID transaction support across cache and persistence layers.
- Ehcache:Java-native caching library integrated with Hibernate and Spring frameworks. Enterprise Java applications in regulated industries maintain legacy deployments.
Redis holds the installed base advantage, with Apache Ignite gaining share fastest among new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cache server infrastructure concentrates in data center clusters where hyperscale cloud providers and content delivery networks co-locate. Germany, the United States, India, Brazil, and Japan anchor deployment volumes through distinct regulatory and demand drivers.
Germany
Frankfurt's data center corridor attracts hyperscale cache investments driven by EU AI Act compliance mandates and GDPR data residency requirements. The EU Green Deal incentivizes energy-efficient liquid-cooled deployments exceeding air-cooling density thresholds. Hesse's Rhine-Main cluster hosts the densest concentration of edge cache nodes serving European financial services pipelines.
United States
Enterprise migration to consumption-priced elastic tiers drives cloud-based cache expansion across financial services and e-commerce verticals. FCC broadband infrastructure programs accelerate edge node deployment in underserved markets. Northern Virginia's data center alley maintains the largest installed base of distributed cache capacity globally.
India
MeitY data localization mandates compel in-country cache node placement for video streaming and fintech platforms. RBI regulations require financial institutions to maintain transaction data within national boundaries. Mumbai and Hyderabad corridors add hyperscale capacity as AWS and Cloudflare expand localized edge infrastructure.
Brazil
PIX real-time payment infrastructure generates low-latency cache demand across São Paulo and Rio de Janeiro data centers. ANVISA and central bank regulations shape data handling requirements for financial services deployments. São Paulo's fintech corridor anchors South American cache density for gaming and streaming platforms.
Japan
METI digital infrastructure initiatives promote edge computing adoption for autonomous vehicle and industrial IoT workloads. Capital expenditure preference in regulated industries sustains on-premise cache appliance demand alongside cloud migration. Tokyo-Osaka corridor maintains premium-tier deployments for low-latency trading and telecommunications.
Cache Server Market Competitive Environment
Hyperscale cloud providers and specialized content delivery networks split the market between integrated platform bundles and best-of-breed edge services. The vendor base concentrates around three strategic archetypes: cloud-native infrastructure platforms, dedicated CDN specialists, and open-source software vendors with commercial support tiers. Dominant competitive moves include geographic edge expansion into regulated markets and vertical integration of caching with AI inference pipelines.
Among hyperscale cloud providers, Amazon Web Services (AWS) and Microsoft Azure exemplify the integrated platform archetype through elastic cache tiers bundled with broader infrastructure services. Cloudflare occupies a position within the specialized CDN tier, extending freemium-to-enterprise models into tier-two cities across India and Brazil. Akamai Technologies anchors the premium managed services segment through direct carrier relationships and dedicated cache fabric deployments.
| Leading Market Players |
|---|
| Microsoft Azure |
| Fastly |
| Akamai Technologies |
| Varnish Software |
| StackPath |
| Cloudflare |
| Google Cloud Platform |
| Nginx |
| Amazon Web Services (AWS) |
| Others |
Value Chain & Pricing Dynamics
Frankfurt's data center corridor concentrates liquid-cooled cache server deployments where REACH chemical restrictions and F-Gas Regulation phase-downs inflate compliance costs, compressing hardware margins and forcing vendors toward software-defined alternatives that reduce capital intensity.
Pricing Analysis
EU AI Act compliance mandates dictate the pricing tier structure across European deployments, with audit-ready edge configurations commanding premiums over standard cloud tiers. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-certified sovereign deployments from consumption-based elastic tiers and freemium entry points. Cost compression in on-premise appliance segments is intensifying because DDR5 memory contract volatility erodes hardware margins. E-commerce platforms exhibit highest price sensitivity due to seasonal scaling unpredictability, while financial services accept premium positioning for synchronous replication guarantees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for cache-optimized processors and advanced packaging substrates. Taiwan, South Korea, and the United States anchor semiconductor fabrication for high-bandwidth memory and cache-optimized CPUs. Raw material dependencies center on silicon wafers, palladium-based capacitors, and liquid cooling coolants subject to REACH restrictions. Single-source vulnerability concentrates in TSMC's advanced packaging capacity for multi-chip cache modules. Distribution runs through hyperscale cloud providers, systems integrators, and direct OEM channels serving enterprise data centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cache server infrastructure is entering a cyclical recovery phase as hyperscaler capex cycles turn positive and edge computing deployments accelerate across regulated markets.
For Market Incumbents: Entrench position through backward integration into high-bandwidth memory supply chains and captive liquid-cooling subsystem production. AWS and Azure's bundled infrastructure platforms threaten standalone cache appliance vendors with margin compression. Certification investment in EU AI Act audit trails and GDPR data residency compliance creates switching costs that lock financial services clients into multi-year commitments. For New Entrants and Emerging Players: Tier-two Indian cities beyond Mumbai and Hyderabad represent the most penetrable entry point for edge cache deployments, where Cloudflare's freemium model has established demand but enterprise conversion remains incomplete. Brazil's PIX real-time payment infrastructure in São Paulo and Rio de Janeiro offers parallel white-space opportunity with lower competitive density. A channel partnership strategy with regional systems integrators accelerates enterprise sales cycles without direct hyperscaler confrontation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors open-source software vendors with commercial support tiers and established Redis or Apache Ignite code contributions. Long-term viability hinges on convergence with AI inference pipelines and sustainability-certified hardware designs. The signal to watch is hyperscaler edge node buildout announcements in Frankfurt, Mumbai, and São Paulo as leading indicators of capacity absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Geographic Expansion | MeitY localization mandates in India require Mumbai and Hyderabad cache infrastructure. |
| AI Inference Pipeline Integration | Model serving workloads hybridize with content caching in unified platform architectures. |
| Green Certification Investment | EU Green Deal tax credits in Germany reward energy-efficient liquid-cooled deployments. |
| Open-Source Commercial Support Tier | Redis and Apache Ignite code contributors capture enterprise support contract margins. |
| Systems Integrator Channel Partnership | Managed service providers in North American financial services absorb pricing transition friction. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with CTOs, platform engineers, IT procurement officers, and hyperscaler infrastructure planners; and secondary validation against SEC capex disclosures, hyperscaler earnings call transcripts, and EU regulatory filings. Bottom-up triangulation against top-down market sizing ensured segment-level consistency across deployment models and technology stacks.
Forecast inputs span cloud-based, edge computing, on-premise, and hybrid deployment architectures across financial services, e-commerce, gaming, and telecom verticals. Segmentation dimensions include solution type, end-user industry, and technology stack with regional adoption patterns. CAGRs were derived from elasticity modeling against hyperscaler infrastructure investment cycles and edge node deployment trajectories. AI inference workload convergence and data sovereignty enforcement timelines served as scenario-weighting variables.
Stress conditions across DDR5 memory pricing volatility, Taiwan semiconductor supply disruption, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hyperscaler capex cycles and regulatory implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Computer Network Design Services Market