
 Automotive Data Management Market | 2026-2036
Automotive Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Data Management Market Intelligence
Subscription-based software-defined feature packs is expanding the addressable revenue per vehicle beyond one-time hardware sales. DXC Technology leverages its legacy systems integration heritage to anchor multi-cloud data architectures for major OEMs. Continental AG competes through embedded edge-to-cloud pipelines that sustain real-time telemetry throughput at manufacturing scale. KPIT Technologies specializes in automotive-specific middleware that differentiates its offering from generic enterprise platforms.
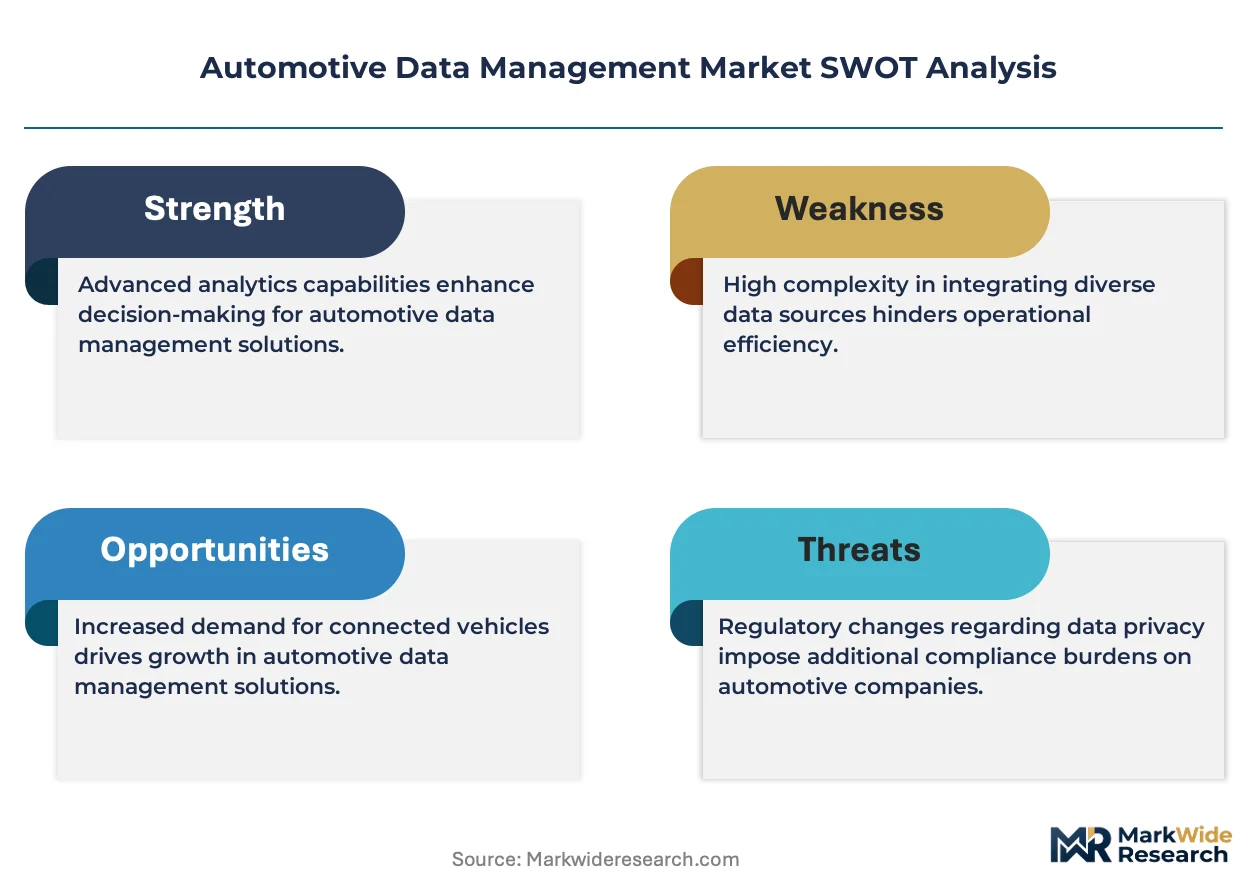
Automotive data management encompasses the collection, processing, storage, and governance of vehicle-generated telemetry, diagnostic codes, sensor streams, and user interaction logs across distributed cloud and edge infrastructure. The discipline serves the primary commercial purpose of enabling predictive operational decisions, regulatory compliance documentation, and monetizable connected services throughout a vehicle's lifecycle. Cloud storage solutions and data analytics platforms currently occupy the largest margin pools as OEMs consolidate fragmented data lakes into unified architectures. Predictive maintenance applications within the application dimension are demonstrating the fastest structural expansion, driven by warranty cost reduction imperatives and uptime guarantees in commercial fleets.
The EU AI Act and GDPR impose algorithmic transparency and data residency obligations that shape product architecture decisions for any platform serving European vehicle owners. The US NHTSA and EPA frameworks govern event data recorder retention and emissions-related diagnostic reporting, creating compliance-driven procurement cycles for domestic fleet operators. Stakeholders must monitor how fragmented sovereignty requirements across Germany, the United States, and China fragment platform standardization efforts and force region-specific engineering investments.
Market Dynamics
Connected vehicle telemetry volumes are compressing legacy ETL pipelines, forcing OEMs to rebuild data architectures around stream processing and edge-native ingestion. This infrastructure stress concentrates procurement decisions among engineering clusters capable of sustaining sub-100ms latency guarantees.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European OEMs must deploy explainable inference engines for automated driving functions, creating procurement pull for governance-integrated data platforms.
- Fleet operator uptime guarantees:Commercial vehicle lessors demand predictive maintenance APIs that warranty operational availability, accelerating telemetry standardization across mixed-vendor fleets.
- Edge-to-cloud pipeline maturation:5G network slicing enables deterministic data routing from vehicle gateways to regional cloud zones, reducing backhaul costs for high-frequency sensor streams.
Market Restraints
- Semiconductor supply concentration:Automotive-grade SoC fabrication concentrates at TSMC and Samsung foundries, creating 18-24 month lead time volatility for edge compute modules.
- GDPR data residency friction:Cross-border telemetry replication requires sovereign cloud deployments, fragmenting platform economics and inflating infrastructure overhead.
- Legacy CAN bus protocol inertia:Decades-old vehicle network architectures resist seamless IP-based integration, forcing expensive gateway translation layers.
Strategic Opportunities
- India PLI scheme for automotive electronics:Domestic data center buildouts and software R&D incentives attract platform providers seeking cost-engineering hubs outside saturated European markets.
- Vehicle-to-grid bidirectional data monetization:Battery state telemetry from electric fleets creates new revenue streams for utilities managing distributed energy resources.
- ISO/SAE 21434 cybersecurity certification:Mandatory security engineering processes for connected vehicles open consulting and tooling revenue adjacent to core data management.
Industry Challenges
- Automotive MLops talent scarcity:The intersection of embedded systems, functional safety, and MLOps expertise remains underdeveloped, inflating compensation for qualified platform architects.
- Multi-tenant data isolation complexity:Shared infrastructure serving competing OEMs requires cryptographic segmentation that exceeds standard cloud-native security postures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Data Management Market |
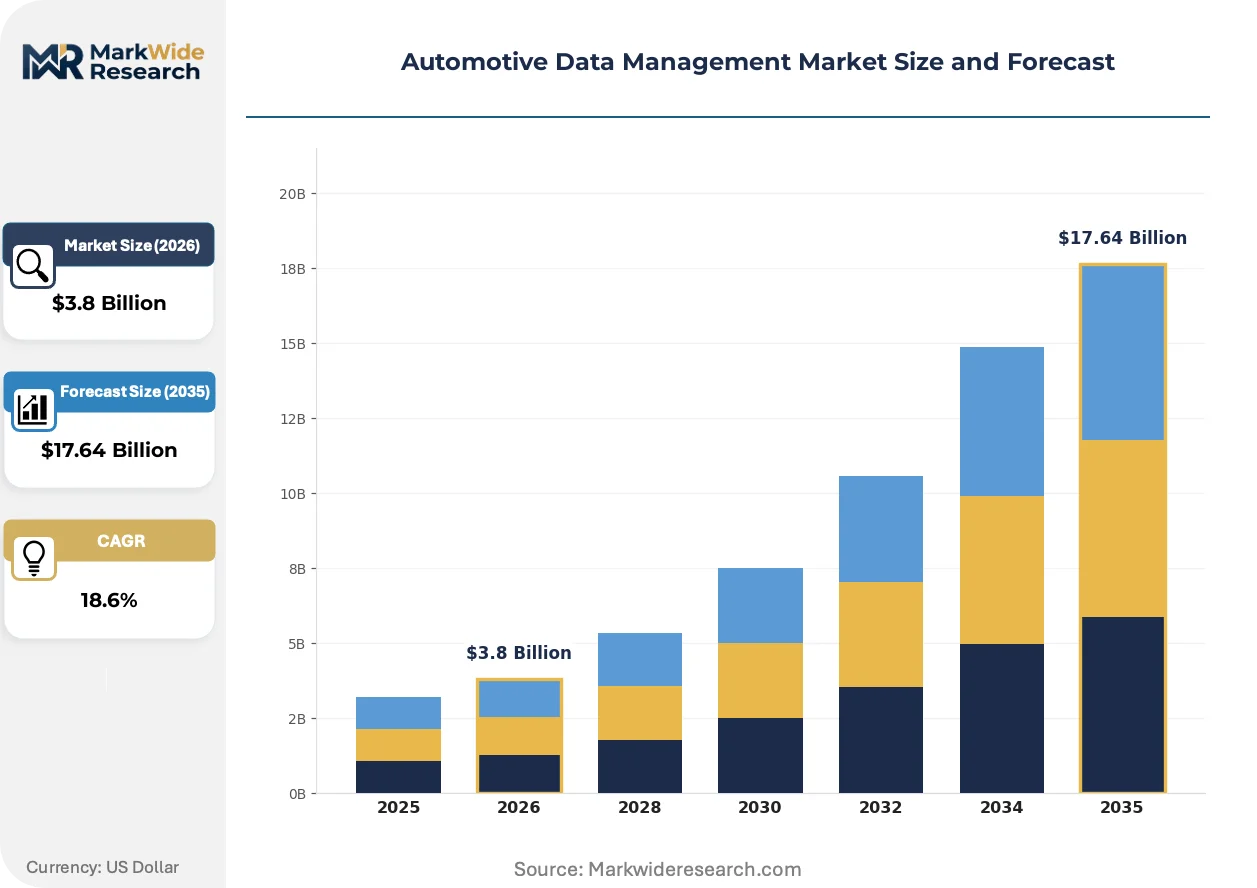
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Analytics Platforms, Cloud Storage Solutions, Data Integration Tools, Data Security Systems, Telematics Software Application: Fleet Management, Connected Vehicle Services, Predictive Maintenance, Driver Behavior Analysis, Supply Chain Optimization End User: Vehicle Manufacturers, Aftermarket Providers, Fleet Operators, Insurance Firms, Regulatory Agencies Deployment: On-Premise, Cloud-Based, Hybrid Models, Edge Computing, Mobile Integration |
| Companies Covered | DXC Technology, Infosys, N-iX, Continental AG, KPIT Technologies, Sigma Software, Cognizant, Yalantis, Adastra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Data Management Market Strategic Shifts & Innovations
Data platform architectures are pivoting from batch-centric lakes to streaming-native meshes that sustain real-time inference across distributed vehicle fleets. This shift redefines competitive differentiation around latency engineering rather than storage economics.
Federated learning frameworks are absorbing sensitive model training workloads that previously required raw telemetry centralization. German luxury OEMs deploy these architectures to satisfy GDPR minimization principles while preserving collaborative algorithm improvement. The approach is absorbing what had been a fundamental tension between ML performance and regulatory compliance.
The EU AI Act's risk classification system imposes documentation burdens on automated driving data pipelines that exceed prior type-approval requirements. OEMs must now maintain immutable provenance records for training datasets and model versioning. European engineering centers are responding by embedding compliance tooling directly into CI/CD workflows rather than treating documentation as post-hoc audit preparation.
Fleet procurement departments are consolidating vendor relationships around vertically integrated platform stacks that unify edge hardware, connectivity, and cloud analytics. This behavior compresses the addressable market for point-solution providers while expanding contract values for full-stack competitors. The concentration is most visible in German commercial vehicle leasing, where procurement teams prioritize single-vendor accountability for uptime SLAs.
Automotive Data Management Market Segmentation
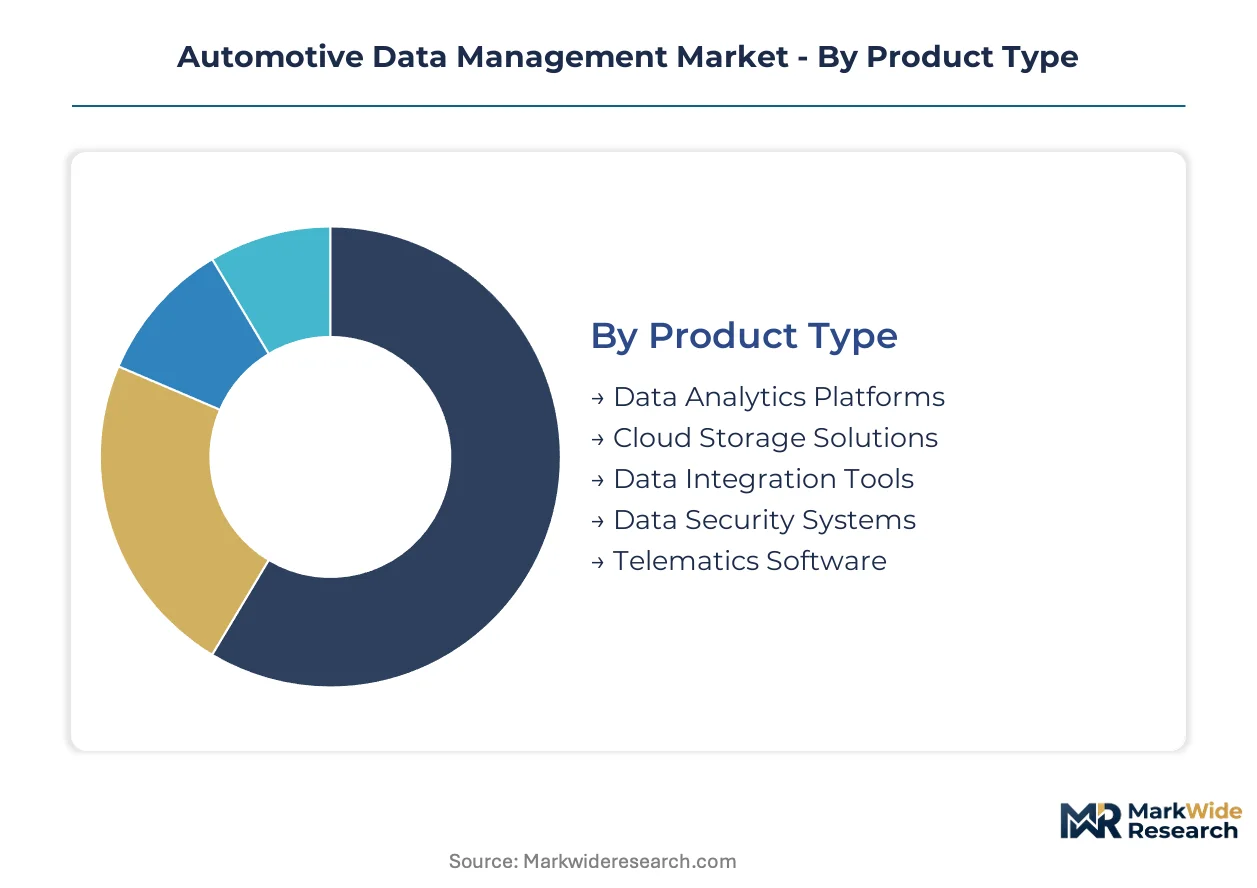
Automotive data management platforms serve divergent technical requirements across vehicle lifecycles. Procurement patterns fragment sharply between real-time operational workloads and archival compliance systems.
Product Type:
Technical specifications around latency tolerance and data sovereignty requirements differentiate procurement decisions across the stack.
- Data Analytics Platforms:Stream processing engines ingest telemetry at manufacturing scale, supporting predictive inference across distributed fleets. German OEM headquarters concentrate procurement here, driven by EU AI Act documentation mandates for automated driving functions.
- Cloud Storage Solutions:Unified data lake architectures consolidate fragmented OEM repositories, enabling cross-vehicle analytics. Sovereign cloud deployments in Frankfurt and Stuttgart satisfy GDPR residency requirements for European vehicle owners.
- Data Integration Tools:ETL modernization pipelines bridge legacy CAN bus architectures with IP-based vehicle networks.
- Data Security Systems:Cryptographic segmentation protects multi-tenant infrastructure serving competing manufacturers.
- Telematics Software:Embedded modules manage gateway-to-cloud routing for high-frequency sensor streams.
Mature deployment sits with Cloud Storage Solutions. Newer deployment is concentrated in Data Analytics Platforms.
Application:
Commercial imperatives around warranty cost reduction and uptime guarantees reshape demand concentration across use cases.
- Predictive Maintenance:Algorithmic failure prediction reduces warranty exposure and sustains fleet operational availability. Commercial vehicle lessors in Germany prioritize these APIs, linking procurement to contractual uptime SLAs.
- Fleet Management:Real-time vehicle tracking and route optimization consolidate mixed-vendor telemetry standards. Logistics operators demand sub-100ms latency guarantees for dispatch coordination.
- Connected Vehicle Services:Subscription-based feature packs monetize over-the-air software updates.
- Driver Behavior Analysis:Telematics scoring models inform usage-based insurance pricing.
- Supply Chain Optimization:Component traceability systems satisfy ISO/SAE 21434 cybersecurity documentation.
Procurement volume concentrates in Fleet Management. Steepest expansion trajectory belongs to Predictive Maintenance.
End User:
Stakeholder technical sophistication and regulatory exposure determine platform architecture requirements.
- Vehicle Manufacturers:OEM engineering clusters demand full-stack integration from edge hardware through cloud analytics. German headquarters drive platform standardization decisions across global production networks.
- Fleet Operators:Commercial lessors prioritize vertically integrated vendor accountability for operational availability. Procurement teams consolidate relationships around single-source uptime guarantees.
- Aftermarket Providers:Independent service networks require interoperable diagnostic data access.
- Insurance Firms:Actuarial departments ingest telematics streams for risk-adjusted pricing models.
- Regulatory Agencies:NHTSA and KBA auditors mandate immutable event data recorder retention systems.
Platform maturity aligns with Vehicle Manufacturers. Emerging demand concentrates among Fleet Operators.
Deployment:
Infrastructure location decisions trade latency performance against data sovereignty compliance burdens.
- Cloud-Based:Regional cloud zones process batched telemetry with elastic compute scaling. GDPR cross-border replication restrictions force sovereign deployments, fragmenting platform economics.
- Edge Computing:Vehicle-gateway inference sustains real-time decisions without backhaul dependency. 5G network slicing enables deterministic routing to manufacturing-adjacent compute nodes.
- On-Premise:Captive data centers serve classified prototype testing and pre-homologation validation.
- Hybrid Models:Tiered processing splits latency-sensitive workloads between edge and cloud tiers.
- Mobile Integration:Smartphone-tethered diagnostics extend connected services to legacy vehicle parc.
Established infrastructure favors Cloud-Based architectures. Investment flows concentrate in Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of automotive data platforms concentrates in engineering clusters serving European and North American OEM headquarters, while consumption spreads across fleet operators in commercial vehicle corridors. Germany anchors platform development through tier-1 supplier ecosystems, whereas the United States drives cloud-scale deployment for connected vehicle services. China and India represent divergent growth vectors—Beijing prioritizes sovereign data architectures, while Indian engineering centers capture cost-optimized R&D migration.
Germany
EU AI Act documentation mandates and GDPR residency requirements pull procurement toward sovereign cloud deployments in Frankfurt and Stuttgart engineering clusters. KBA auditors enforce immutable provenance standards for automated driving training datasets, forcing OEMs to embed compliance tooling into CI/CD pipelines. Continental AG and KPIT Technologies maintain headquarters in Bavaria and Baden-Württemberg, anchoring edge-to-cloud development for luxury vehicle manufacturers.
United States
NHTSA event data recorder retention rules and EPA emissions reporting frameworks create compliance-driven procurement cycles for domestic fleet operators. Cloud hyperscalers operate regional zones in Virginia and Oregon, processing batched telemetry with elastic compute scaling. Detroit-area engineering centers sustain legacy systems integration heritage while Silicon Valley clusters pioneer stream-processing architectures for autonomous vehicle fleets.
China
MIIT data localization requirements and dual carbon goals accelerate sovereign data center buildouts for electric vehicle telemetry. GB standards mandate cybersecurity certification for connected vehicle gateways, opening consulting revenue adjacent to core platform deployment. Yangtze River Delta manufacturing corridors concentrate edge compute module production, though semiconductor fabrication dependence on TSMC creates supply volatility.
India
PLI scheme incentives for automotive electronics attract platform providers seeking cost-engineering hubs outside saturated European markets. CDSCO and TRAI frameworks govern diagnostic data portability for connected health applications in commercial fleets. Karnataka and Telangana software clusters specialize in automotive-specific middleware development, differentiating offerings from generic enterprise platforms.
Japan
METI industrial data sharing initiatives promote federated learning frameworks that satisfy privacy minimization principles while preserving collaborative algorithm improvement. JIS standards govern functional safety documentation for predictive maintenance APIs serving commercial lessors. Kanto and Chubu engineering corridors sustain embedded systems expertise for gateway-to-cloud routing at manufacturing scale.
Automotive Data Management Market Key Industry Players
Top-tier vendors anchor full-stack platform integration, while mid-tier specialists compete through middleware differentiation and regional engineering proximity. Market structure tilts toward consolidation as fleet procurement teams prioritize single-vendor accountability for uptime SLAs. Three archetypes dominate: legacy systems integrators with multi-cloud heritage, embedded edge-to-cloud pipeline specialists, and automotive-specific middleware developers. Competitive moves center on strategic partnerships with semiconductor foundries and geographic expansion into PLI-subsidized Indian engineering corridors.
Within the legacy integration tier, DXC Technology and Cognizant occupy positions defined by enterprise-scale cloud architecture deployment. Continental AG exemplifies the embedded pipeline archetype through its manufacturing-adjacent edge compute heritage. KPIT Technologies represents automotive middleware specialization, distinguishing its platform from generic enterprise offerings through vehicle lifecycle expertise. These three anchors collectively span the technical requirements from legacy ETL modernization to real-time stream processing at fleet scale.
| Leading Market Players |
|---|
| DXC Technology |
| Infosys |
| N-iX |
| Continental AG |
| KPIT Technologies |
| Sigma Software |
| Cognizant |
| Yalantis |
| Adastra |
| Others |
Cost & Logistics Intelligence
Sovereign-backed data center operators in Germany and China anchor platform infrastructure investments, compressing pricing power for independent software vendors while concentrating procurement leverage among state-adjacent buyers. This ownership pattern tightens margin discipline across subscription tiers as vendors compete for sovereign cloud mandates.
Pricing Analysis
Margin tightening in mid-tier SaaS offerings reflects hyperscaler bundling strategies that absorb standalone analytics functionality into broader cloud contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates by latency guarantees and GDPR certification depth, with fleet operators exhibiting highest price sensitivity and luxury OEMs least. Cost-down pressure on edge hardware accelerates because automotive-grade SoC fabrication concentrates at TSMC and Samsung foundries.
Supply Chain Analysis
Dual-sourcing requirements for edge compute modules mandate qualification of secondary foundry partners, fragmenting procurement timelines but reducing single-source exposure. Supply chains draw from Taiwan for silicon fabrication, Germany for automotive software engineering, and India for cost-optimized middleware development. Dependencies span automotive-grade SoCs, sovereign cloud infrastructure, and 5G network slicing capabilities. Single-source vulnerability at TSMC creates structural risk. Distribution runs through direct OEM platform engineering contracts and tier-1 supplier integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over edge-to-cloud pipeline latency determines platform viability, with semiconductor sourcing and sovereign data center access as the decisive upstream levers.
For Market Incumbents: Anticipate hyperscaler bundling threats by embedding compliance tooling directly into CI/CD workflows rather than treating documentation as post-hoc audit preparation. Secure captive supply of automotive-grade SoCs through foundry partnership commitments to reduce 18-24 month lead time volatility. Strengthen platform stickiness via federated learning architectures that satisfy GDPR minimization principles. For New Entrants and Emerging Players: Launch via PLI-subsidized Indian engineering corridors to capture cost-optimized R&D migration outside saturated European markets. Target aftermarket diagnostic interoperability as the most penetrable segment, where independent service networks require standardized data access. Pursue ISO/SAE 21434 cybersecurity certification as the primary go-to-market credential. For Investors and Strategic Acquirers: Fleet operator consolidation around single-vendor uptime SLAs is the leading indicator that full-stack platform integration will outcompete point solutions. Position for 5-10 year viability around automotive-specific middleware developers with vehicle lifecycle expertise. Monitor India PLI scheme incentive expansions as the inflection signal for geographic engineering migration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unifies fragmented OEM data lakes into sovereign cloud architectures compliant with EU AI Act. |
| Software-Defined Vehicle Investment | Enables subscription-based feature packs that expand addressable revenue per vehicle. |
| Geographic Manufacturing Footprint | Captures PLI scheme incentives in Karnataka and Telangana software clusters. |
| Strategic Partnership | Secures 5G network slicing capabilities for deterministic vehicle-to-cloud routing. |
| Acquisition of Specialist Firm | Absorbs embedded systems expertise for sub-100ms latency guarantee engineering. |
Research Approach
Multi-period observation of connected vehicle telemetry volumes, sovereign cloud deployment patterns, and regulatory documentation mandates anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-1 supplier procurement leads, fleet operations directors, and sovereign data center architects. Secondary validation drew from vehicle production databases, hyperscaler capex disclosures, EU AI Act implementation guidance, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Input-output matrices mapped deployment model, vehicle class, and regional regulatory cluster to project adoption trajectories across the analysis window. CAGRs derived from elasticity modeling against semiconductor supply constraints and fleet operator procurement consolidation patterns. Industry-specific forecast inputs included 5G infrastructure rollout schedules and PLI scheme incentive allocation trajectories.
Semiconductor supply disruption, sovereign data localization mandate expansion, and hyperscaler bundling acceleration are the dominant revision risks that would necessitate forecast adjustment. A model refresh is warranted upon material change in EU AI Act enforcement severity or India PLI scheme scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Content Delivery Network (CDN) Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Enterprise Server Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
South Korea Data Center Networking Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Netherlands Data Center Networking Market