
 Dynamic Data Management System Market | 2026-2036
Dynamic Data Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamic Data Management System Market Foresight
Cloud-native financial institutions and regulated healthcare networks is bifurcating demand away from traditional on-premises buyers. Oracle Corporation leverages its autonomous database portfolio to anchor enterprise workloads in regulated sectors. Microsoft Corporation sustains competitive pressure through deep Azure integration and hybrid deployment flexibility. IBM Corporation differentiates via mainframe-connected data fabric architectures that serve legacy modernization programs.
A dynamic data management system constitutes an integrated software platform that automates data ingestion, schema evolution, quality assurance, and real-time synchronization across distributed sources, typically processing petabyte-scale streams with sub-second latency for operational decision support. The primary commercial purpose centers on eliminating data silos while maintaining governance compliance as organizations aggregate structured, semi-structured, and unstructured information. Cloud-based deployment now captures the fastest expansion trajectory as enterprises abandon capital-intensive infrastructure commitments, while data governance applications command premium pricing due to regulatory complexity and audit-ready lineage requirements. Machine Learning technology integration represents the emerging margin pool, though data lakes infrastructure retains volume leadership in industrial IoT and genomics workloads.
The EU AI Act and GDPR impose algorithmic transparency and data residency mandates that directly shape procurement specifications for European buyers, while the US SEC climate disclosure rules and HIPAA security standards extend compliance-driven replacement cycles across North American financial and healthcare sectors. ISO 27001 and SOC 2 Type II certifications have become non-negotiable gating criteria for vendor selection in enterprise RFP processes. Stakeholders must weigh sovereign data requirements against cloud economics when architecting multi-region deployment strategies.
Market Dynamics
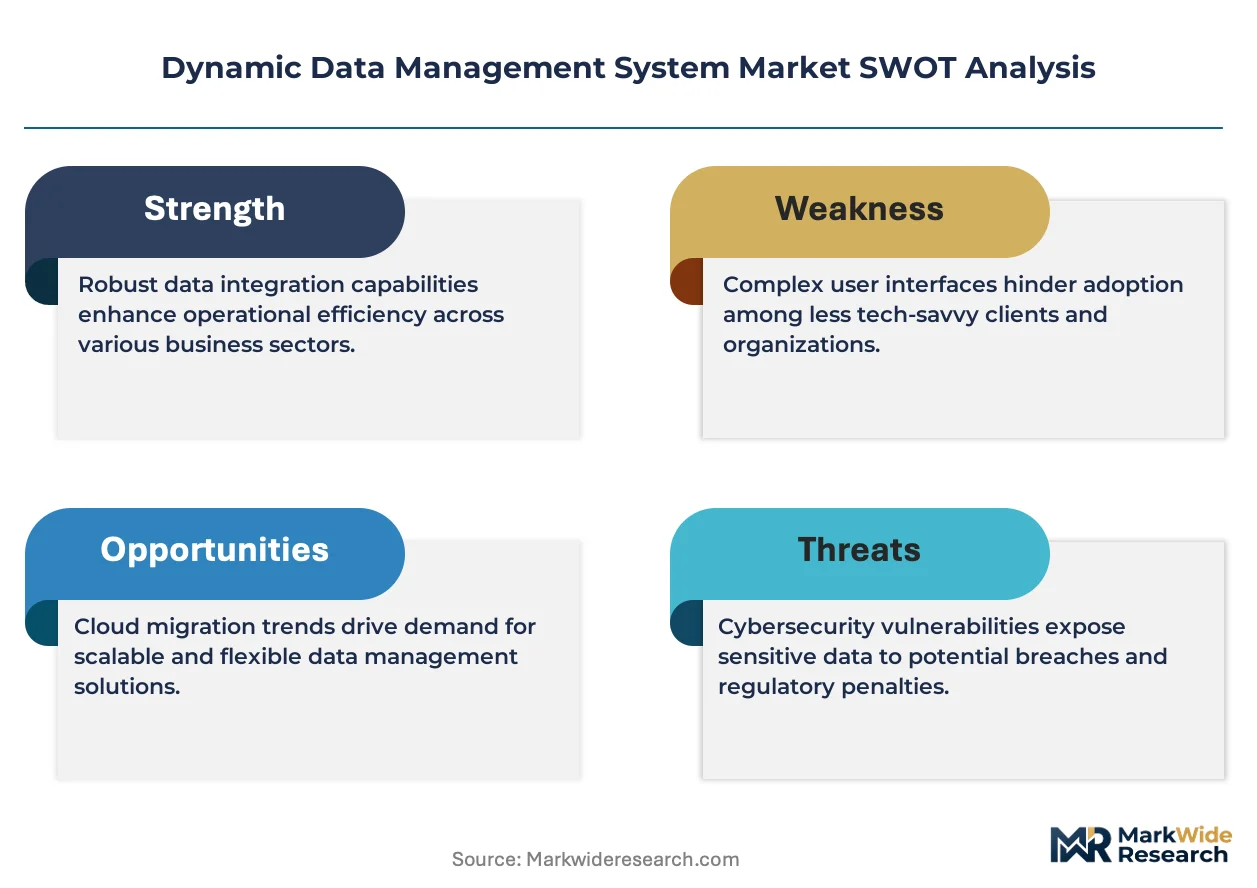
Real-time governance automation is compressing procurement cycles as financial services firms replace batch-processing architectures with continuous compliance engines that embed policy enforcement directly into data pipelines.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European enterprises must maintain auditable data lineage for automated decision systems, forcing wholesale replacement of legacy metadata repositories.
- Healthcare network consolidation:Integrated delivery systems in the United States require unified patient data fabrics that synchronize electronic health records across acquired hospital networks under HIPAA security standards.
- Edge computing proliferation:Industrial IoT deployments in Germany's automotive corridor generate petabyte-scale telemetry streams that demand sub-second ingestion and schema evolution capabilities.
Market Restraints
- Specialized engineering talent scarcity:Data fabric architects with combined governance and distributed systems expertise command premium compensation that inflates implementation budgets.
- Cloud egress cost volatility:Multi-terabyte replication across availability zones generates unpredictable bandwidth charges that erode total-cost-of-ownership projections.
- Legacy mainframe integration friction:IBM zSeries environments resist API-native connectivity, requiring costly middleware layers that delay modernization timelines.
Strategic Opportunities
- India's digital public infrastructure expansion:The country's Account Aggregator framework and Data Empowerment and Protection Architecture create demand for consent-managed data exchange platforms.
- Convergence of data mesh and AI governance:Organizations seek unified platforms that simultaneously enforce domain-oriented ownership and model risk management protocols.
- Japan's manufacturing data sovereignty requirements:METI guidelines on industrial data localization favor domestic deployment of edge-native management systems with JIS-compliant security modules.
Industry Challenges
- Cross-functional data stewardship recruitment:Enterprises struggle to staff hybrid roles combining legal compliance expertise with pipeline engineering skills.
- SOC 2 Type II certification timelines:Audit-ready control documentation for multi-tenant SaaS deployments extends sales cycles by six to nine months.
- Schema drift remediation automation:Production pipelines fail when upstream source systems modify structures without notification, requiring costly manual intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dynamic Data Management System Market |
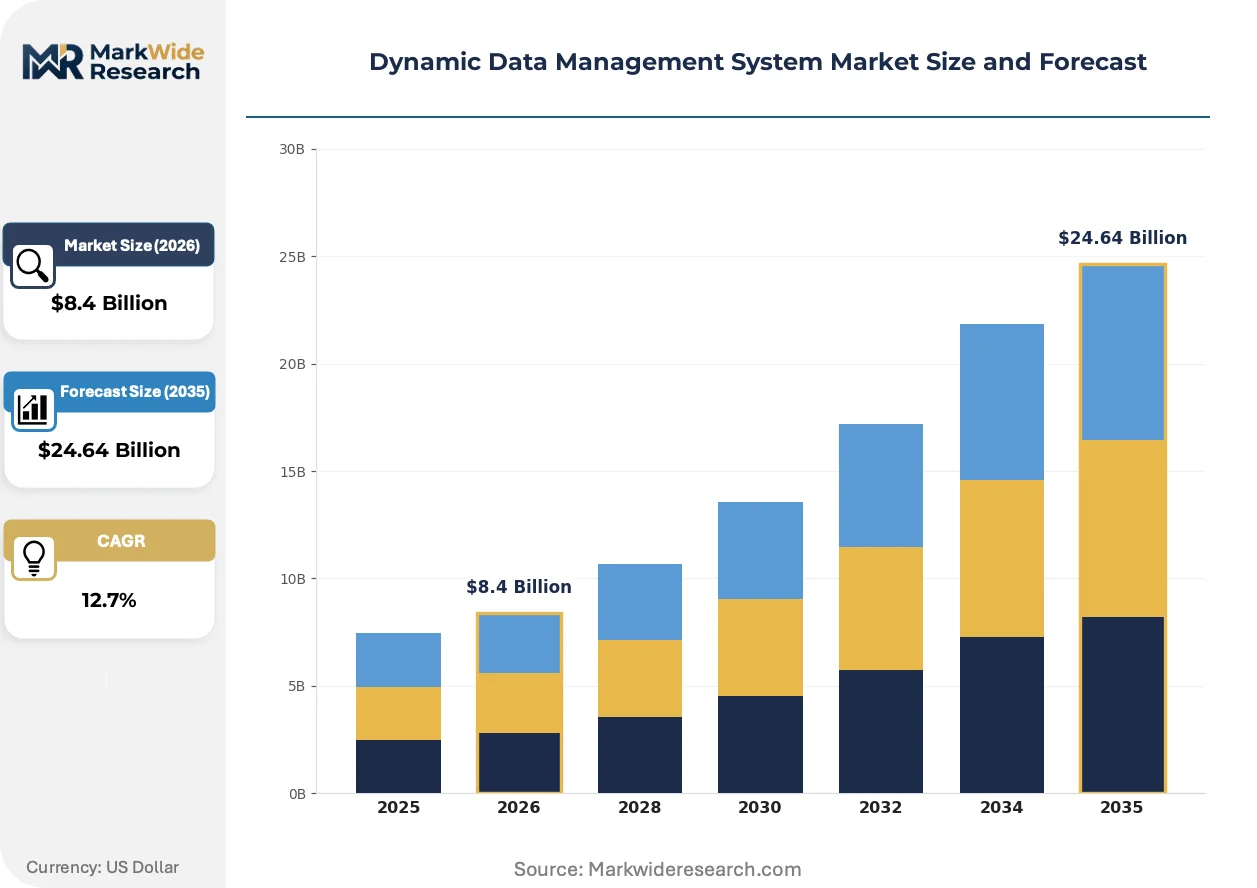
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $24.64 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Tenant End User: SMEs, Large Enterprises, Government, Non-Profit Technology: Machine Learning, Big Data, Artificial Intelligence, Data Lakes Application: Data Integration, Data Analytics, Data Governance, Data Visualization |
| Companies Covered | Oracle Corporation, Microsoft Corporation, IBM Corporation, SAP SE, Teradata, MongoDB, Couchbase Inc., BMC Software Inc., SolarWinds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamic Data Management System Market Shifts & Advancements
Automated policy enforcement engines are displacing manual data stewardship workflows across regulated industries, embedding governance rules directly into ingestion pipelines rather than applying them retrospectively.
Active metadata management is miniaturizing governance overhead by embedding business context, quality scores, and lineage tracking directly into data assets as they flow through pipelines. Financial services firms in Singapore and Switzerland deploy these capabilities to satisfy regulator demands for real-time risk visibility. The technology is miniaturizing the traditional data catalog from a separate queryable repository into an always-on distributed layer that travels with the data itself.
The EU AI Act's risk classification framework is forcing enterprises to reconstruct training data provenance for high-risk automated systems, particularly in credit scoring and insurance underwriting applications. Organizations must now demonstrate that historical datasets exclude prohibited bias indicators and maintain documentation of preprocessing decisions. German automotive suppliers and French banking networks face the most acute compliance pressure as national regulators accelerate enforcement timelines ahead of the 2026 full implementation deadline.
Subscription-based consumption models are displacing perpetual license arrangements as buyers prioritize operational expenditure predictability over capital deployment flexibility. Healthcare networks and municipal governments in the United States favor usage-tiered pricing that aligns costs with actual query volumes and storage growth. This shift concentrates vendor risk in customer retention mechanics rather than upfront deal profitability, rewarding platforms with demonstrable time-to-value metrics and embedded professional services.
Dynamic Data Management System Market Segmentation
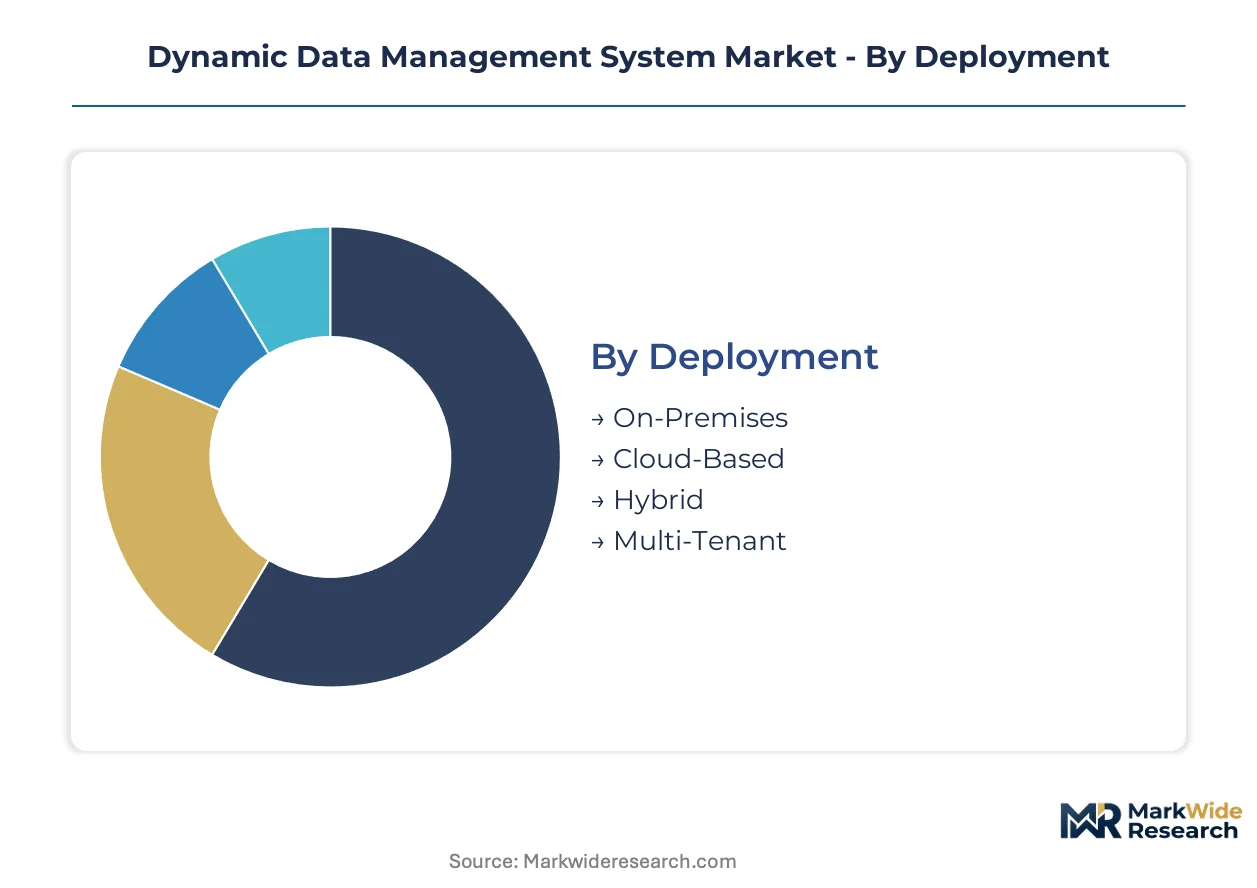
Deployment architecture determines capital intensity and compliance posture for buyers across financial services, healthcare, and industrial sectors. Technology integration depth separates premium pricing tiers from commoditized infrastructure plays. Application focus shapes vendor competitive positioning between governance-heavy regulated industries and analytics-driven commercial sectors.
Deployment:
Margin pools concentrate in hybrid configurations that bridge legacy mainframe estates with cloud-native analytics workloads.
- On-Premises:Dedicated hardware installations within enterprise data centers deliver sub-millisecond latency for trading floor and factory floor applications. German automotive OEMs and Swiss private banks maintain these deployments to satisfy sovereign data requirements under GDPR and national banking secrecy laws.
- Cloud-Based:Fully managed SaaS platforms eliminate capital expenditure cycles and compress time-to-value for mid-market buyers. Healthcare networks in the United States favor this model to align spending with patient volume fluctuations while maintaining HIPAA-compliant encryption standards.
- Hybrid:Split architectures partition sensitive workloads on-premises while bursting analytics to public cloud. Financial services firms in Singapore deploy hybrid stacks to satisfy Monetary Authority data localization rules without sacrificing elastic compute for risk modeling.
- Multi-Tenant:Shared infrastructure platforms deliver cost efficiency through resource pooling across non-competing tenants. Municipal governments and non-profit consortia leverage multi-tenant arrangements to access enterprise-grade capabilities at fractional cost.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
End User:
Procurement sophistication varies sharply by organizational scale and regulatory exposure.
- SMEs:Mid-market buyers prioritize subscription pricing and rapid deployment over customization depth. Regional healthcare clinics and specialty manufacturers in India adopt lightweight data fabric solutions through the country's Account Aggregator framework.
- Large Enterprises:Global institutions require federated governance across hundreds of data domains. French banking networks and Japanese automotive conglomerates invest heavily in unified platforms that reconcile data mesh principles with AI Act compliance documentation.
- Government:Public sector buyers mandate sovereign infrastructure and audit-ready lineage for national security applications. EU member state tax authorities and India's digital public infrastructure programs drive specialized procurement specifications.
- Non-Profit:Research consortia and humanitarian organizations prioritize cost transparency and open interoperability standards. Genomics collaboratives and climate monitoring networks favor community-governed data commons architectures.
Large Enterprises anchor current revenue. SMEs are gaining share fastest among new deployments.
Technology:
Integration complexity separates high-margin platforms from infrastructure commodities.
- Machine Learning:Embedded ML pipelines automate schema discovery, anomaly detection, and quality scoring without manual intervention. Credit scoring platforms in the United States and insurance underwriting systems in France deploy these capabilities to satisfy EU AI Act risk classification requirements.
- Big Data:Distributed processing frameworks handle petabyte-scale telemetry from industrial IoT deployments. Germany's automotive corridor generates the densest concentration of demand for real-time ingestion and edge-to-cloud synchronization.
- Artificial Intelligence:Generative AI interfaces enable natural language querying of complex data estates. Healthcare networks experiment with AI-powered clinical decision support that demands rigorous training data provenance documentation.
- Data Lakes:Centralized repositories for raw, unprocessed information retain volume leadership in genomics, satellite imagery, and scientific research workloads. Research institutions favor open-format lake architectures to prevent vendor lock-in.
Data Lakes holds installed capacity. Machine Learning is climbing the fastest up the technology mix.
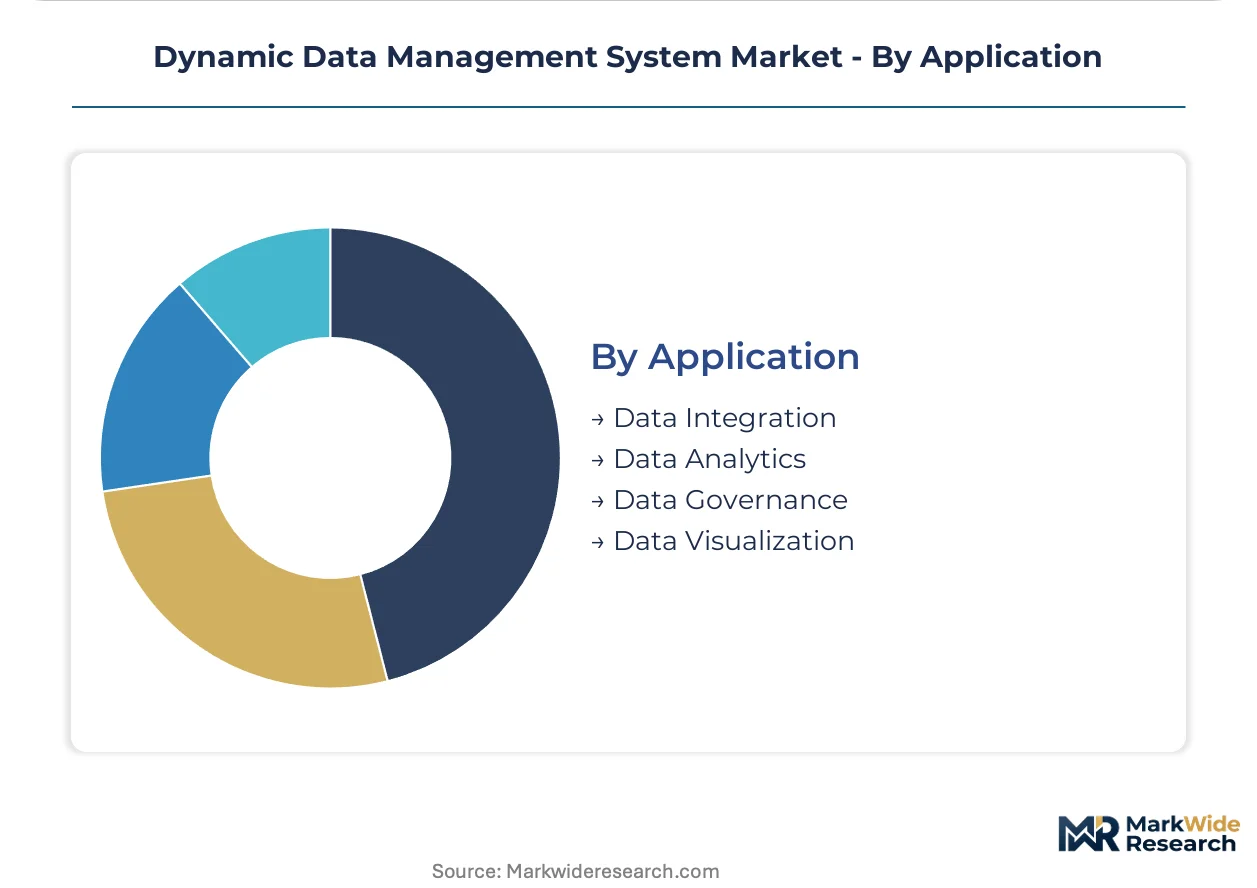
Application:
Functional specialization determines pricing power and renewal rates.
- Data Integration:Pipeline automation that unifies disparate sources into coherent streams commands premium pricing in acquisition-heavy industries. United States healthcare networks require these capabilities to synchronize electronic health records across merged hospital systems.
- Data Analytics:Descriptive and predictive capabilities that transform raw information into actionable intelligence. Retail and logistics operators in Japan deploy analytics platforms to optimize supply chain responsiveness under METI-guided digital transformation mandates.
- Data Governance:Policy enforcement, lineage tracking, and compliance documentation represent the fastest-expanding application segment. GDPR and EU AI Act mandates force wholesale replacement of legacy metadata systems across European enterprises.
- Data Visualization:Interactive dashboards and self-service reporting tools democratize access to complex datasets. Municipal governments and educational institutions prioritize intuitive interfaces for non-technical stakeholders.
Data Integration holds installed capacity. Data Governance is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers export telemetry processing capabilities to industrial operators across Central Europe and North America. The EU AI Act and GDPR compliance mandates reshape procurement specifications continent-wide. Singapore's Monetary Authority data localization rules attract hybrid cloud investment from regional financial institutions.
United States
Healthcare network consolidation and SEC climate disclosure rules drive demand for unified patient data fabrics and audit-ready lineage systems. HIPAA security standards govern electronic health record synchronization across merged hospital systems. The Greater Boston biotech corridor deploys real-time governance platforms for genomics research workloads.
Germany
Automotive OEMs and machinery manufacturers invest heavily in edge-native management systems for industrial IoT telemetry streams. The EU AI Act risk classification framework forces credit scoring and insurance underwriting platforms to reconstruct training data provenance. Stuttgart's automotive software corridor concentrates demand for sub-second ingestion capabilities.
Singapore
Monetary Authority data localization rules compel financial services firms to maintain sovereign infrastructure for risk modeling workloads. Hybrid deployment architectures satisfy residency requirements without sacrificing elastic compute scalability. The city-state's fintech hub attracts regional headquarters for governance platform vendors.
India
The Account Aggregator framework and Data Empowerment and Protection Architecture create demand for consent-managed data exchange platforms. RBI guidelines shape procurement specifications for financial sector data fabrics. Maharashtra's Mumbai-Pune technology corridor hosts domestic deployment of lightweight SME-focused solutions.
Japan
METI guidelines on industrial data localization favor edge-native management systems with JIS-compliant security modules. Manufacturing conglomerates require unified platforms that reconcile data mesh principles with sovereign data requirements. The Nagoya-Toyota automotive cluster generates concentrated demand for real-time synchronization capabilities.
Dynamic Data Management System Market Competitive Landscape
Listed leaders compete with private specialists across deployment flexibility and governance depth. The vendor base organizes into three tiers: cloud-native platforms commanding premium pricing in mid-market healthcare, mainframe-connected incumbents serving legacy modernization programs, and open-source-anchored challengers penetrating developer-centric workloads. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through localized compliance certifications.
Within the enterprise infrastructure tier, Oracle Corporation and Microsoft Corporation exemplify divergent approaches to regulated sector penetration. IBM Corporation occupies a distinct position bridging mainframe estates with cloud-native analytics. These three anchors represent the competitive spectrum from autonomous database automation through hybrid deployment flexibility to legacy-connected data fabric architectures.
| Leading Market Players |
|---|
| Oracle Corporation |
| Microsoft Corporation |
| IBM Corporation |
| SAP SE |
| Teradata |
| MongoDB |
| Couchbase Inc. |
| BMC Software Inc. |
| SolarWinds |
| Others |
Supply & Pricing Matrix
Petabyte-scale processing capacity utilization in hyperscale cloud regions creates steep economies of scale that compress unit economics for mid-market buyers while elevating price floors for sovereign-compliant on-premise deployments. German automotive OEMs and Singaporean financial institutions absorb these premiums to satisfy GDPR and Monetary Authority data localization mandates.
Pricing Analysis
Next-generation autonomous database architectures command 40-60% premiums over prior-generation manual administration tiers, while legacy mainframe-connected fabrics retain pricing power in regulated sectors. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth, with ISO 27001 and SOC 2 Type II tiers extracting maximum value. Cost compression in cloud-native SaaS tiers is intensifying because hyperscaler margin pressure feeds through to independent software vendors. Regional healthcare clinics in India exhibit highest price sensitivity, while Swiss private banks and EU tax authorities demonstrate lowest elasticity due to non-negotiable audit requirements.
Supply Chain Analysis
Inventory lead times for specialized data fabric engineering talent extend 6-9 months across the United States, Germany, and India, constraining implementation velocity for complex governance deployments. Software supply chains draw from open-source distributed processing frameworks, proprietary encryption modules, and cloud-native orchestration layers. Single-source vulnerability concentrates in hyperscaler infrastructure dependencies, where egress cost volatility erodes total-cost-of-ownership projections. Distribution runs through systems integrator partnerships and direct enterprise sales organizations, with channel partners capturing mid-market healthcare and municipal government segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in dynamic data management are approaching an inflection as interoperability standards and consent-managed exchange frameworks displace proprietary data silos. India's Account Aggregator ecosystem exemplifies this shift, creating network effects that reward early standardization adopters.
For Market Incumbents: Compound defensive moats through mainframe-to-cloud bridge architectures that lock in legacy modernization budgets. Deepen vertical integration into sovereign-compliant encryption modules to neutralize emerging European specialists. Prioritize SOC 2 Type II certification maintenance as table stakes for financial services procurement.
For New Entrants and Emerging Players: ISO 27001 fast-track programs open procurement doors to EU government and healthcare segments previously blocked by audit timelines. India's SME healthcare clinics and Germany's mid-tier automotive suppliers represent the most penetrable white-space targets. Lead with usage-tiered pricing that aligns costs with actual query volumes, mirroring the consumption models favored by municipal governments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms serving regulated healthcare networks with embedded professional services. Five-to-ten year viability favors vendors demonstrating sub-90-day time-to-value metrics and cross-functional data stewardship training programs. Watch for EU AI Act enforcement acceleration as the definitive demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with Systems Integrators | Accelerates time-to-value for healthcare network consolidation projects under HIPAA. |
| Geographic Expansion via Localized Compliance | Unlocks Singapore Monetary Authority and Japan METI procurement specifications. |
| Platform Integration with Mainframe Estates | Captures IBM zSeries modernization budgets in European banking networks. |
| Product Launch in Consent-Managed Exchange | Aligns with India's Account Aggregator framework and DEPA architecture. |
| Acquisition of Specialist Governance Firm | Consolidates EU AI Act risk classification and lineage documentation capabilities. |
Research Methodology
Cross-validation between primary interviews with data platform engineers and secondary validation through hyperscaler capex disclosures anchors the qualitative findings. CTOs, IT procurement officers, integration specialists, and compliance officers at financial services and healthcare institutions provided operational perspective. SEC filings, cloud provider infrastructure investment reports, and regulatory submission databases supplied quantitative grounding. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis across deployment architecture, organization scale, vertical regulatory intensity, and regional adoption pattern shapes the analytical framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market trajectory. Machine learning integration velocity and EU AI Act compliance deadline proximity serve as industry-specific forecast inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under stable regulatory enforcement timelines and cloud infrastructure investment continuity; material deviation in GDPR or EU AI Act implementation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
US Dark Fiber Network Market