
 Global Internet Protocol Television (IPTV) CDN Market | 2026-2036
Global Internet Protocol Television (IPTV) CDN Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internet Protocol Television (IPTV) CDN Market Foresight
Platform licensing revenue is fragmenting between pure-play software vendors and vertically integrated telecom operators. Akamai Technologies leverages its edge server footprint to sustain premium positioning in live streaming workloads. Cisco Systems anchors its IPTV CDN portfolio through deep integration with routing and switching infrastructure. Ericsson competes on 5G-native delivery architectures that reduce latency for time-shifted TV applications.
Internet Protocol Television Content Delivery Network denotes a distributed server architecture that caches and streams television content over IP networks using HTTP-based adaptive bitrate protocols such as HLS and DASH, with edge nodes positioned within 50 milliseconds of end users to ensure broadcast-grade quality. The system serves broadcast networks, cable operators, and OTT platforms by transcoding source feeds into multiple resolution tiers and routing viewer requests to the nearest available node. Cloud CDN deployments are capturing the fastest expansion as media conglomerates abandon capital-intensive on-premises infrastructure for elastic capacity models. Live Streaming applications command the highest per-gigabyte pricing within the Application segment due to real-time encoding requirements and low-latency SLAs.
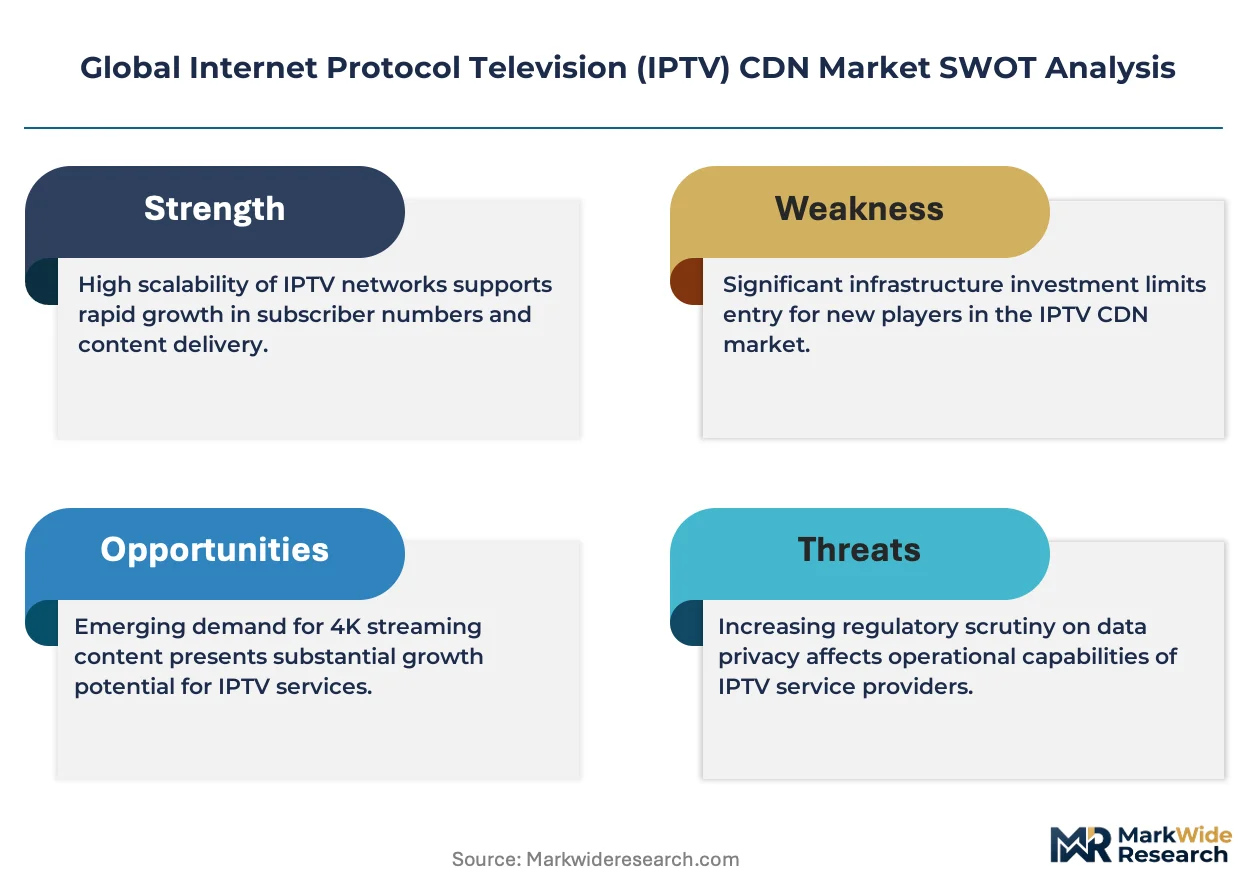
FCC net neutrality rulings in the United States, GDPR data localization mandates enforced by European regulators, and China's MIIT content distribution licensing regime collectively shape where IPTV CDN providers can deploy edge nodes and how subscriber data traverses national boundaries. India's TRAI tariff orders and the PLI scheme for telecom equipment manufacturing further influence vendor selection criteria for domestic network builds. Stakeholders must weigh sovereign data requirements against the latency economics of centralized cloud architectures as they scale their delivery footprints.
Market Dynamics
The migration from hardware-bound encoding appliances to cloud-native serverless transcoding is compressing capital deployment cycles across broadcast infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:European broadcasters must implement algorithmic transparency in content recommendation engines, forcing CDN providers to deploy explainable AI routing layers.
- Fiber-to-the-home buildouts in India:TRAI's infrastructure-sharing directives accelerate last-mile density, enabling IPTV penetration into tier-2 and tier-3 urban clusters.
- Edge computing convergence:Micro data centers co-located with 5G base stations reduce round-trip latency below broadcast tolerances for live sports wagering integration.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints limit real-time 8K encoding hardware availability for tier-1 live events.
- GDPR data localization friction:Cross-border viewer analytics require sovereign cloud instances, fragmenting operational scale economics.
- Satellite backhaul substitution:Low-earth orbit constellations threaten terrestrial CDN dominance in remote geography distribution.
Strategic Opportunities
- Brazil's ANVISA medical-grade streaming:Telemedicine protocols create certified low-latency requirements for surgical training multicast.
- Cloud-gaming overlay services:Interactive entertainment convergence with broadcast television opens latency-sensitive revenue tiers.
- India's PLI scheme for telecom equipment:Domestic manufacturing incentives reduce import dependency for edge node hardware procurement.
Industry Challenges
- Real-time video engineering talent scarcity:Adaptive bitrate algorithm specialists command premium compensation, constraining R&D velocity.
- Legacy MPEG-TS integration complexity:Hybrid broadcast-broadband architectures require protocol bridging that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internet Protocol Television (IPTV) CDN Market |
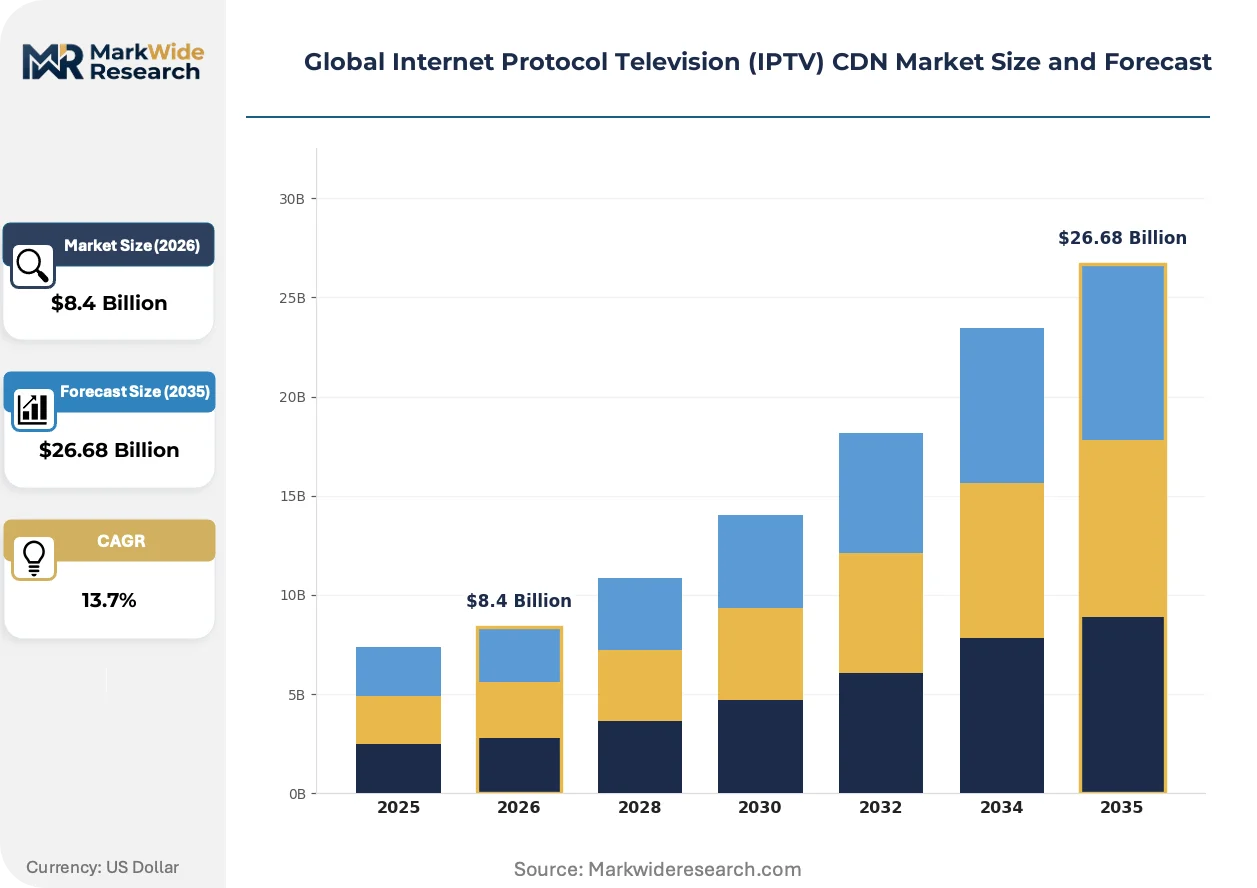
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises CDN, Cloud CDN, Hybrid CDN, Managed CDN Application: Live Streaming, Video on Demand, Catch-Up TV, Time-Shifted TV Deployment Model: Over-The-Top, IPTV Service Provider, Telecom Operators, Media Conglomerates End User: Broadcast Networks, Cable Operators, OTT Platforms, Telecommunications Companies |
| Companies Covered | Akamai Technologies, Ericsson, Cisco Systems, AT&T, Verizon Communications, Huawei Technologies, Lumen Technologies, Orange, Deutsche Telekom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internet Protocol Television (IPTV) CDN Market Shifts & Advancements
Software-defined workflows are replacing purpose-built appliances, while sovereign data requirements and interactive consumption patterns reshape competitive differentiation.
Serverless transcoding is digitizing how media companies provision encoding capacity. Broadcasters in Germany and South Korea are adopting pay-per-minute models for live event spikes. This architecture is digitizing capital allocation away from fixed hardware depreciation toward operational expenditure elasticity.
China's MIIT content distribution licensing regime tightens foreign CDN operator market access. Domestic providers must maintain in-country edge node presence with state-approved encryption standards. European and North American vendors are responding through joint venture structures with licensed local partners.
Viewer demand for synchronized second-screen experiences is fragmenting traditional linear consumption. Sports leagues and wagering platforms in the United Kingdom and Australia now require sub-500 millisecond latency as a baseline specification. This behavioral shift is most pronounced in cricket and Australian rules football broadcasts where real-time statistics drive engagement metrics.
Global Internet Protocol Television (IPTV) CDN Market Segmentation
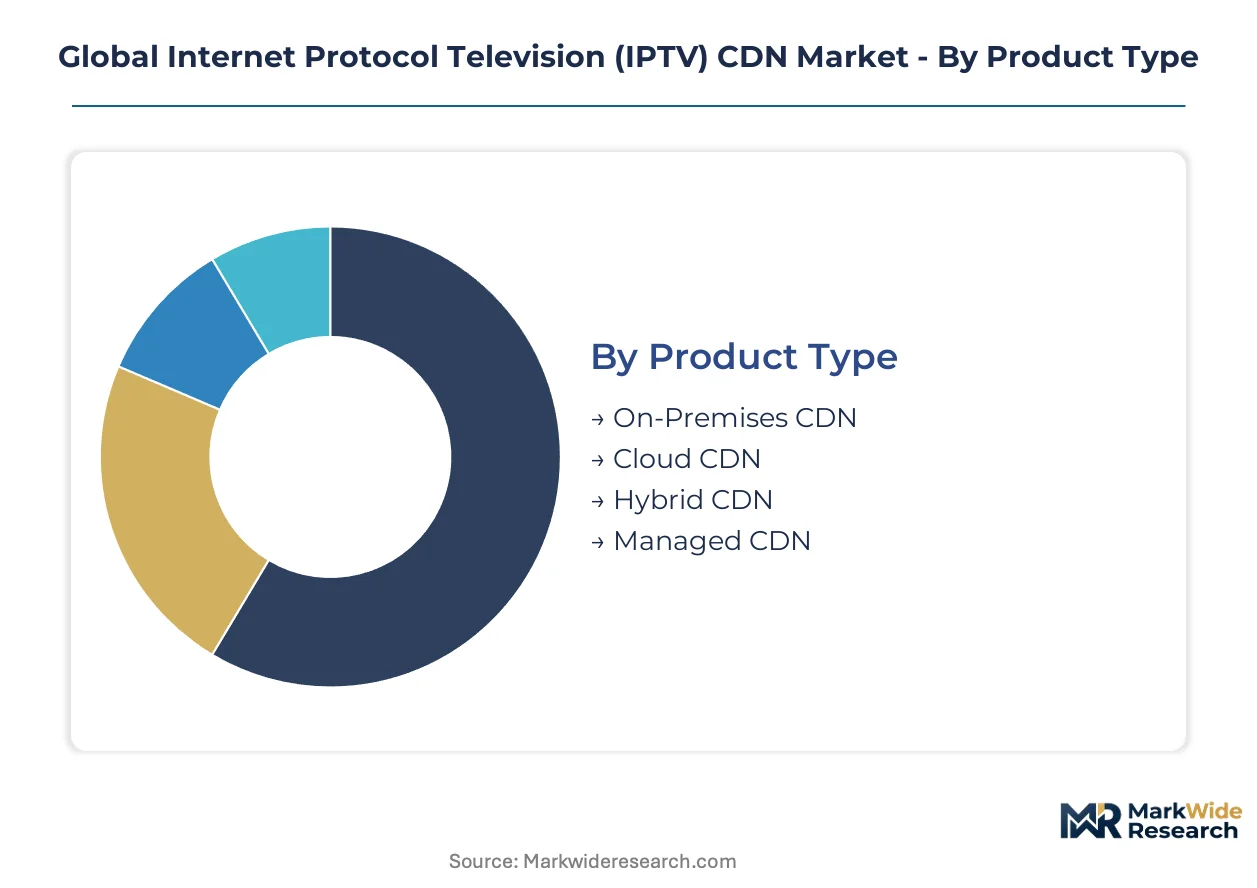
IPTV CDN architectures fragment across infrastructure ownership models, content delivery patterns, and operator business models. Each segmentation dimension reveals distinct procurement priorities and margin structures that vendors must navigate.
Product Type:
Deployment maturity spans from legacy capital-intensive hardware to elastic consumption models, reshaping vendor competitive dynamics.
- On-Premises CDN:Dedicated server clusters deployed within operator data centers with full hardware ownership and depreciation schedules. Broadcast networks in Germany and Japan maintain these deployments for regulatory compliance with domestic data sovereignty laws.
- Cloud CDN:Elastic capacity provisioned through hyperscale providers with usage-based metering. Media conglomerates in the United States and United Kingdom are displacing fixed infrastructure for event-driven scaling around major sports rights.
- Hybrid CDN:Blended architecture combining owned edge nodes with burst capacity from public cloud. Telecommunications companies in India leverage this model to balance TRAI infrastructure-sharing mandates against peak demand absorption.
- Managed CDN:Outsourced operations where vendors assume full operational responsibility including encoding, caching, and traffic engineering. Smaller cable operators in Brazil and Mexico prefer this to avoid specialized video engineering hires.
On-Premises CDN retains volume leadership; Cloud CDN holds the steepest expansion curve.
Application:
Content format economics diverge sharply based on real-time encoding requirements and viewer concurrency patterns.
- Live Streaming:Real-time transcoding with sub-500 millisecond latency SLAs for synchronous delivery. Sports wagering platforms in the United Kingdom and Australia drive premium pricing for this workload.
- Video on Demand:Asynchronous library delivery with pre-encoded assets stored across distributed edge tiers. OTT platforms in South Korea and the United States concentrate subscriber acquisition spend here.
- Catch-Up TV:Time-windowed replay services bridging linear broadcast and on-demand consumption. European public service broadcasters under EU AI Act transparency mandates deploy explainable recommendation engines for this content.
- Time-Shifted TV:Cloud DVR functionality enabling pause, rewind, and replay of live linear feeds. Telecom operators in India bundle this with fiber-to-the-home packages to differentiate against satellite competitors.
Video on Demand commands the widest subscriber base; Live Streaming generates the highest revenue per stream.
Deployment Model:
Customer archetype determines architectural requirements from consumer-facing apps to wholesale infrastructure layers.
- Over-The-Top:Direct-to-consumer streaming services operating without managed network partnerships. Netflix, Disney+, and regional equivalents in Brazil and India negotiate direct CDN contracts for last-mile optimization.
- IPTV Service Provider:Subscription television delivered over dedicated IP networks with quality-of-service guarantees. Telecom operators in France and Spain maintain these as core fixed-line revenue anchors.
- Telecom Operators:Carriers integrating IPTV as a triple-play bundle component with broadband and voice. India's Reliance Jio and Bharti Airtel are expanding fiber infrastructure to support 4K and 8K streaming tiers.
- Media Conglomerates:Content owners operating proprietary delivery infrastructure for owned-and-operated platforms. Warner Bros. Discovery and Paramount Global maintain hybrid architectures for direct subscriber relationships.
Telecom Operators retain infrastructure ownership concentration; Over-The-Top is gaining share fastest among new subscriber additions.
End User:
Customer technical sophistication ranges from broadcast engineering heritage to cloud-native platform operations.
- Broadcast Networks:Traditional television operators migrating linear workflows to IP delivery. Public broadcasters in Germany and the United Kingdom face EU AI Act compliance requirements for algorithmic content curation.
- Cable Operators:Hybrid fiber-coaxial providers upgrading DOCSIS infrastructure for IPTV convergence. Operators in the United States and Canada balance legacy MPEG-TS integration against HTTP-based adaptive bitrate migration.
- OTT Platforms:Subscription and ad-supported streaming services with cloud-native engineering cultures. These buyers prioritize serverless transcoding and edge computing convergence for interactive features.
- Telecommunications Companies:Fixed and mobile carriers using IPTV as a strategic broadband retention tool. Indian operators leverage PLI scheme incentives for domestic edge node procurement.
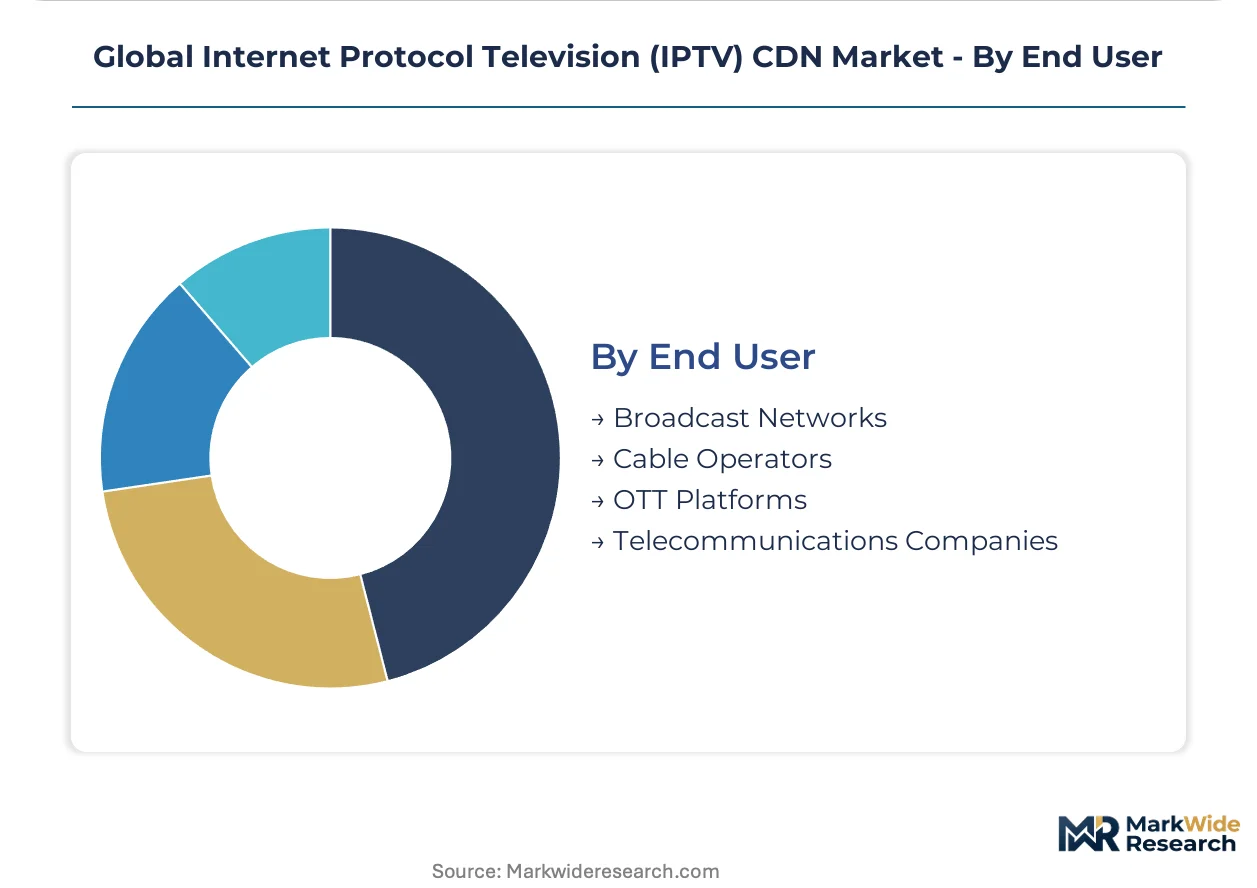
Telecommunications Companies anchor infrastructure procurement volume; OTT Platforms are climbing the fastest in capacity consumption growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Indian telecom operators demand lowest per-gigabyte rates for mass-market fiber builds, while European broadcasters absorb premium pricing for GDPR-compliant sovereign infrastructure.
United States
FCC net neutrality rulings shape where edge nodes deploy and how traffic is prioritized. Sports wagering platforms in Nevada and New Jersey drive sub-500 millisecond latency requirements for synchronized second-screen experiences. Silicon Valley clusters anchor cloud-native CDN engineering talent pools.
Germany
EU AI Act transparency mandates force broadcasters to deploy explainable recommendation engines for catch-up TV services. Public service broadcasters in Munich and Cologne maintain on-premises infrastructure for domestic data sovereignty compliance. Bavaria's media tech corridor concentrates serverless transcoding R&D operations.
India
TRAI infrastructure-sharing directives accelerate last-mile fiber density into tier-2 and tier-3 urban clusters. The PLI scheme for telecom equipment manufacturing reduces import dependency for edge node hardware procurement. Mumbai and Bangalore anchor Reliance Jio and Bharti Airtel's 4K streaming infrastructure expansion.
China
MIIT content distribution licensing regime restricts foreign CDN operator market access through state-approved encryption standards. Domestic providers must maintain in-country edge node presence with sovereign cloud instances. Beijing and Shanghai clusters concentrate joint venture structures between local licensees and Western technology partners.
Brazil
ANVISA medical-grade streaming protocols create certified low-latency requirements for surgical training multicast applications. Cable operators in São Paulo prefer managed CDN outsourcing to avoid specialized video engineering hires. The Southeast region concentrates hybrid fiber-coaxial infrastructure upgrades for IPTV convergence.
Global Internet Protocol Television (IPTV) CDN Market Competitive Landscape
Capability concentration sits with specialized edge computing architects; scale advantage sits with vertically integrated telecommunications carriers. The vendor base separates into three functional tiers: hyperscale cloud providers with elastic capacity models, network equipment manufacturers with routing-integrated portfolios, and pure-play CDN specialists with latency-optimized footprints. Consolidation pressure runs through strategic partnerships between telecom operators and technology vendors, plus geographic expansion into sovereign cloud markets with data localization requirements.
Within the specialized CDN tier, Akamai Technologies and Lumen Technologies exemplify edge-native positioning built on distributed server density. Cisco Systems and Ericsson occupy the infrastructure-integrated segment, anchoring portfolios through deep routing and 5G-native delivery architecture alignment. Huawei Technologies represents the state-affiliated equipment vendor archetype, navigating market access restrictions through licensed domestic partnerships in regulated jurisdictions.
| Leading Market Players |
|---|
| Akamai Technologies |
| Ericsson |
| Cisco Systems |
| AT&T |
| Verizon Communications |
| Huawei Technologies |
| Lumen Technologies |
| Orange |
| Deutsche Telekom |
| Others |
Supply & Pricing Matrix
Taiwan-based GPU foundry concentration at TSMC and MediaTek anchors encoding hardware costs, pushing margin pools toward software-defined transcoding vendors and managed service operators who abstract silicon dependency through serverless consumption models.
Pricing Analysis
Managed CDN service contracts and multi-year infrastructure outsourcing agreements drive lifetime value for pure-play vendors. Three-tier pricing structure across premium live-event SLAs, standard on-demand throughput, and economy-grade catch-up TV separates telecom operators from broadcast networks from regional cable providers. Cost compression in 8K encoding hardware is intensifying because Taiwan foundry capacity constraints limit supply elasticity. Indian telecom operators exhibit highest price sensitivity, while European public broadcasters under GDPR sovereign cloud mandates absorb premium rates for domestic edge node deployment.
Supply Chain Analysis
Foxconn, Jabil, and Wistron hold contract manufacturing capacity for edge server hardware deployed across IPTV CDN footprints. Component sourcing draws from Taiwan for GPU accelerators, South Korea for high-bandwidth memory modules, and China for power supply units. Single-source vulnerability around TSMC's advanced packaging nodes threatens real-time 4K and 8K encoding hardware availability. Distribution runs through direct vendor-operator relationships for hyperscale deployments and regional systems integrators for tier-2 market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as viewer demand for synchronized second-screen experiences and sub-500 millisecond latency wagering integration creates specialized infrastructure niches beyond commoditized video delivery.
For Market Incumbents: Entrench through backward integration into serverless transcoding software stacks and captive edge node manufacturing partnerships under India's PLI scheme. Satellite backhaul substitution from low-earth orbit constellations threatens terrestrial CDN dominance in remote geography distribution. Certification investment in GDPR-compliant sovereign cloud architectures defends European public broadcaster relationships against hyperscaler encroachment. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA-certified medical-grade streaming segment for surgical training multicast applications. Cloud-gaming overlay services converging with broadcast television represent the most penetrable white-space target. Go-to-market angle should emphasize latency-sensitive interactive entertainment integration with existing wagering platform APIs in the United Kingdom and Australia. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play CDN specialists with dense edge footprints but limited routing infrastructure integration. Five-to-ten year viability hinges on 5G-native delivery architecture adoption and sovereign cloud market expansion. Signal to watch: TRAI infrastructure-sharing directive enforcement intensity in India's tier-2 and tier-3 urban cluster buildouts.| Strategic Initiative | Industry Significance |
|---|---|
| Serverless Transcoding Platform Launch | Enables pay-per-minute elasticity for German and South Korean broadcasters during live event spikes. |
| Sovereign Cloud Joint Venture | Navigates China's MIIT licensing regime through state-approved encryption standard partnerships. |
| 5G Edge Computing Convergence | Positions micro data centers at Reliance Jio base stations for sub-broadcast latency sports wagering. |
| Domestic Manufacturing Scale-Up | Captures India's PLI scheme incentives for edge node hardware procurement cost reduction. |
| Explainable AI Routing Layer Deployment | Addresses EU AI Act transparency mandates for algorithmic content recommendation engines. |
Research Methodology
Initial hypotheses were tested against primary input from CDN operations directors, telecom network planning executives, broadcast engineering leads, and hyperscaler cloud procurement officers and refined through secondary validation across SEC 10-K filings, TRAI regulatory orders, EU AI Act compliance documentation, and hyperscaler capex disclosure reports. Bottom-up capacity modeling triangulated against top-down addressable market sizing.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment model elasticity, application latency tier, operator business model archetype, and regional regulatory cluster intensity. CAGRs were derived through logarithmic trend extrapolation of historical capacity deployment and forward projection of fiber-to-the-home penetration curves and 5G base station densification timelines.
Stress conditions across GPU foundry capacity constraints, GDPR data localization enforcement variance, and low-earth orbit satellite constellation deployment pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of TRAI infrastructure-sharing directive implementation metrics and EU AI Act algorithmic transparency audit schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
India Data Center Networking Market