
 Asia-Pacific Hyperscale Data Center Market | 2026-2036
Asia-Pacific Hyperscale Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hyperscale Data Center Market Analytics
Market Context
ISO/IEC 27001 certification is collapsing as a baseline qualifier rather than a differentiator, compressing the window for new entrants to establish trust. Amazon Web Services leverages its Mumbai, Singapore, and Sydney regions to dominate enterprise cloud migration across ASEAN and Oceania. Alibaba Group anchors Greater China demand through proprietary silicon and captive power purchasing, while NTT Global Data Centers specializes in Tokyo-Osaka corridor deployments with direct utility partnerships.
Technical Definition and Segment Structure
Asia-Pacific hyperscale data centers are mission-critical facilities exceeding 5,000 square meters and 5 megawatts of IT load, engineered for concurrent maintainability and PUE targets below 1.3, serving cloud computing, artificial intelligence training, and content delivery at continental scale. Server infrastructure occupies the largest capital allocation pool, though liquid cooling technology commands expanding share as thermal densities from AI training clusters exceed 50 kilowatts per rack. Colocation deployment is maturing in Singapore and Hong Kong where land scarcity elevates multi-tenant economics, while hybrid architectures are accelerating fastest in Indonesia and Vietnam as enterprises straddle legacy systems and cloud-native workloads.
Regulatory Framework and Outlook
MIIT in China enforces PUE thresholds and renewable energy quotas that reshape facility design and location decisions, while Singapore's Infocomm Media Development Authority restricts new data center permits to projects demonstrating carbon-neutral operations. Australia's Critical Infrastructure Act imposes security obligations on operators of nationally significant facilities, tightening vendor eligibility. Stakeholders must monitor how India's Digital Personal Data Protection Act and emerging state-level data center policies in Maharashtra and Telangana alter cross-border capacity planning and local partnership requirements.
Market Dynamics
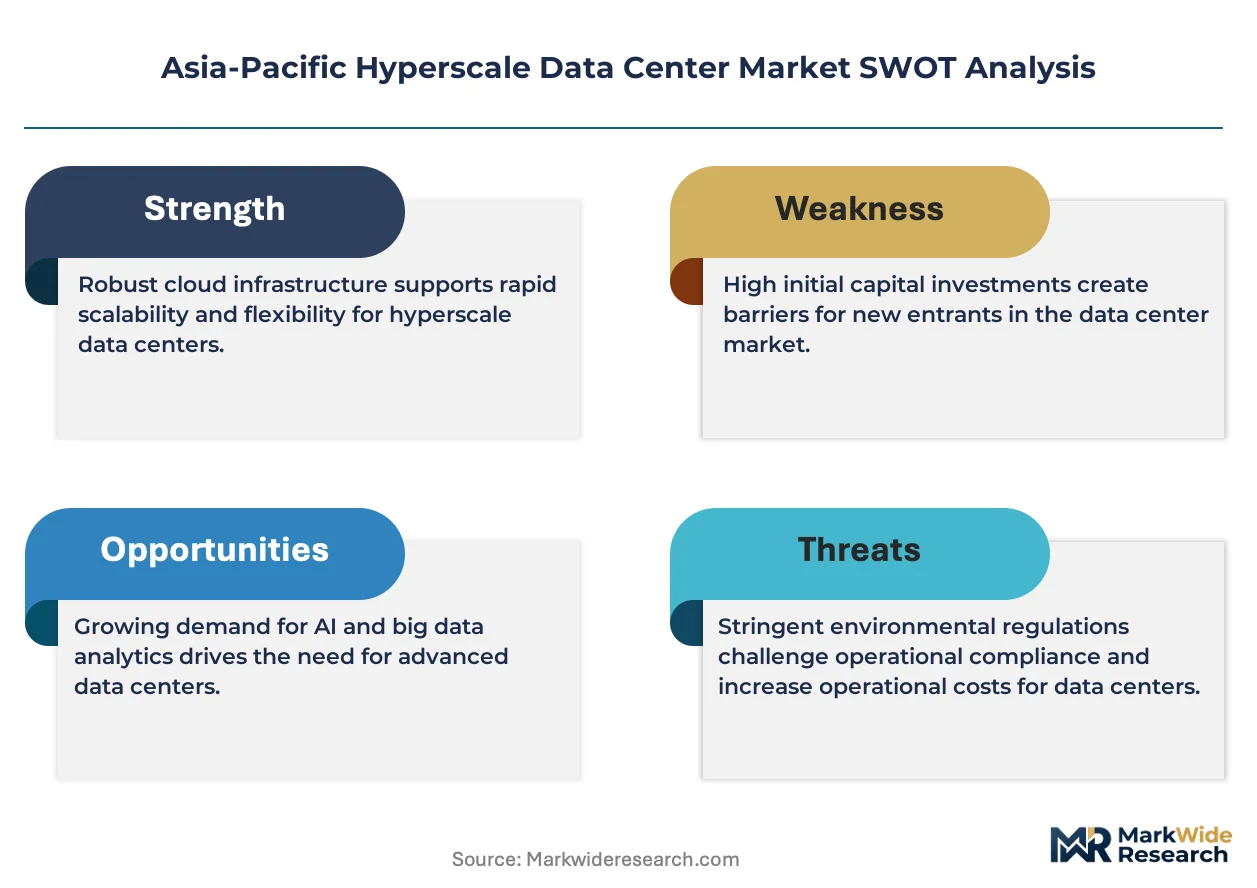
AI training clusters above 50 kilowatts per rack are decomposing traditional air-cooled facility designs across the Asia-Pacific, forcing liquid cooling retrofits and new build standards that compress deployment timelines and reshape capital allocation.
Growth Catalysts
- MIIT energy-efficiency mandates:China's PUE thresholds below 1.3 for new facilities are accelerating liquid cooling adoption and renewable energy integration, creating compliance-driven demand for advanced thermal management systems.
- Sovereign data localization:India's Digital Personal Data Protection Act and Australia's Critical Infrastructure Act are hardening requirements for domestic data storage, pulling capacity into Mumbai-Pune and Sydney-Canberra corridors.
- Generative AI training workloads:Cloud service providers across Southeast Asia are scaling GPU-dense infrastructure to serve foundation model development, concentrating procurement in Singapore and Tokyo-Osaka hubs.
Market Restraints
- Land scarcity in Singapore:The Infocomm Media Development Authority's permit restrictions for carbon-neutral projects only have collapsed available greenfield sites, elevating land costs and forcing vertical build strategies.
- Liquid cooling supply concentration:Cold plate and immersion system manufacturing concentrates in Chinese and Taiwanese component suppliers, creating single-source vulnerability for facility operators outside Greater China.
- Power grid interconnection delays:Utility upgrade timelines in Indonesia and Vietnam extend facility energization by 18-24 months, stranding committed capital and compressing project IRRs.
Strategic Opportunities
- Maharashtra and Telangana state policies:India's emerging sub-national data center incentives offer land allocation and power tariff concessions for hyperscale builds, opening greenfield capacity outside saturated Mumbai.
- Direct liquid cooling convergence:Integration of single-phase immersion with high-voltage DC power distribution is enabling 100-kilowatt rack densities, unlocking AI training economics previously constrained by thermal limits.
- Captive renewable procurement:Singapore's carbon-neutral permit requirement is forcing power purchase agreement innovation with Indonesian and Australian solar developers, creating cross-border energy trading structures.
Industry Challenges
- Thermal fluids engineering talent:The specialized skill set for dielectric fluid chemistry and two-phase heat transfer system design remains concentrated in Japanese and German supplier engineering teams, constraining operator self-build capabilities.
- Legacy facility stranded asset risk:Air-cooled data centers commissioned before 2022 face functional obsolescence for AI workloads, forcing write-downs or costly mechanical system overhauls with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hyperscale Data Center Market |
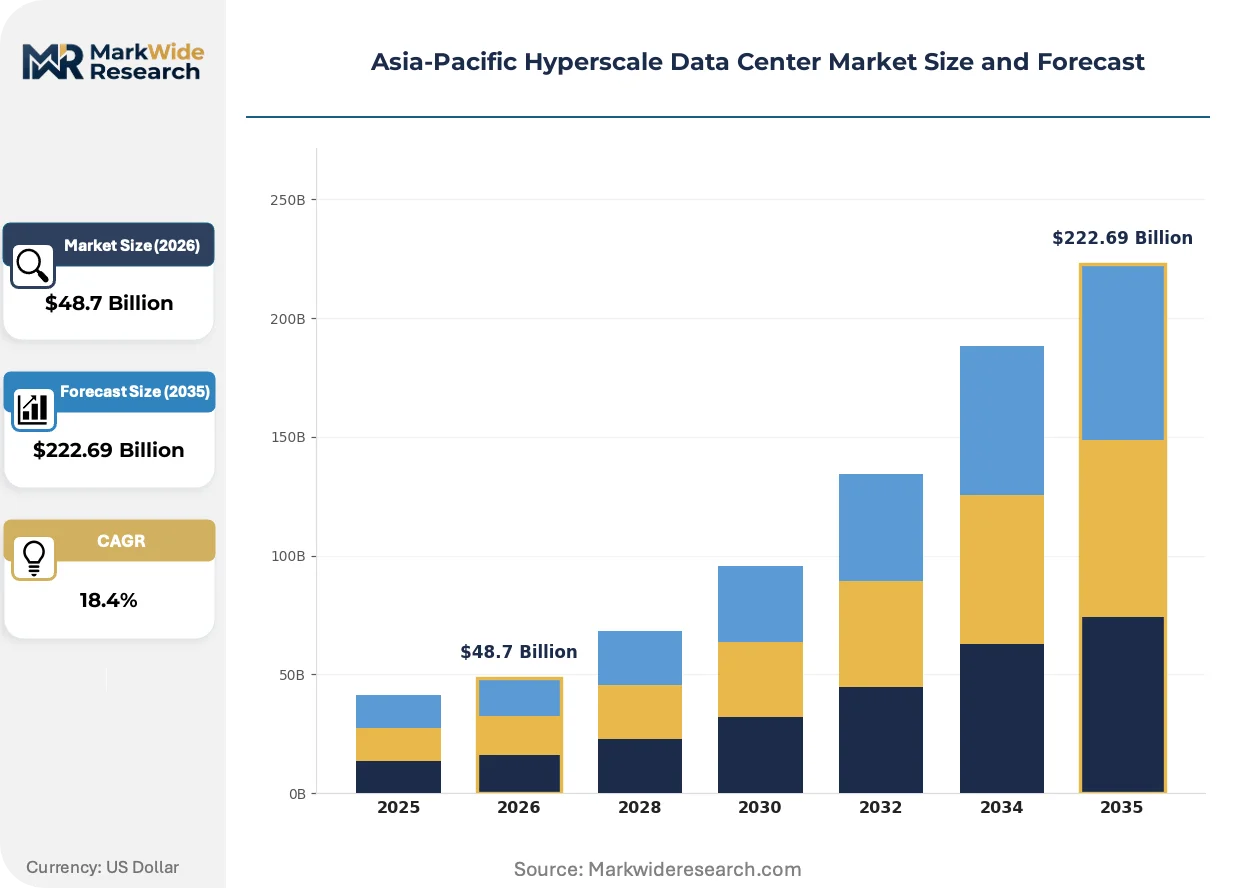
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Server, Storage, Networking, Cooling Equipment End User: Cloud Service Providers, Enterprises, Telecommunication Companies, Content Providers Deployment: On-Premises, Colocation, Hybrid, Managed Services Technology: Liquid Cooling, AI Integration, Edge Computing, Virtualization |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, Alibaba Group, Equinix, Digital Realty, NTT Global Data Centers, Huawei Cloud Computing Technologies, NEXTDC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hyperscale Data Center Market Evolving Landscape
Facility architecture is fragmenting into modular, factory-integrated subsystems that compress on-site construction timelines and enable rapid reconfiguration for shifting workload profiles across the region.
Single-phase immersion cooling is decomposing the conventional CRAH-raised floor paradigm by submerging servers in dielectric fluid baths that eliminate fan energy and enable heat capture for district heating networks. Japanese automotive and electronics manufacturers are piloting 500-kilowatt tank deployments for AI inference workloads. This thermal approach is decomposing the mechanical infrastructure layer into skid-mounted fluid handling systems that ship pre-tested from fabrication facilities.
Singapore's carbon-neutral data center permit framework is mandating 100% renewable energy matching and liquid cooling for all new approvals, with compliance verification through the Energy Market Authority's tracking registry. This policy is compressing project development timelines as developers secure Indonesian solar PPAs before groundbreaking. Australian operators under the Critical Infrastructure Act are responding with sovereign cloud certifications that mirror Singapore's sustainability requirements.
Enterprise buyers are consolidating procurement authority into centralized infrastructure teams that negotiate master service agreements with cloud providers rather than maintaining fragmented departmental contracts. This concentration is compressing switching cycles and elevating multi-year committed use discounts as the dominant pricing mechanism. The shift is most visible among Australian financial services and Indian pharmaceutical multinationals rationalizing shadow IT sprawl.
Asia-Pacific Hyperscale Data Center Market Segmentation
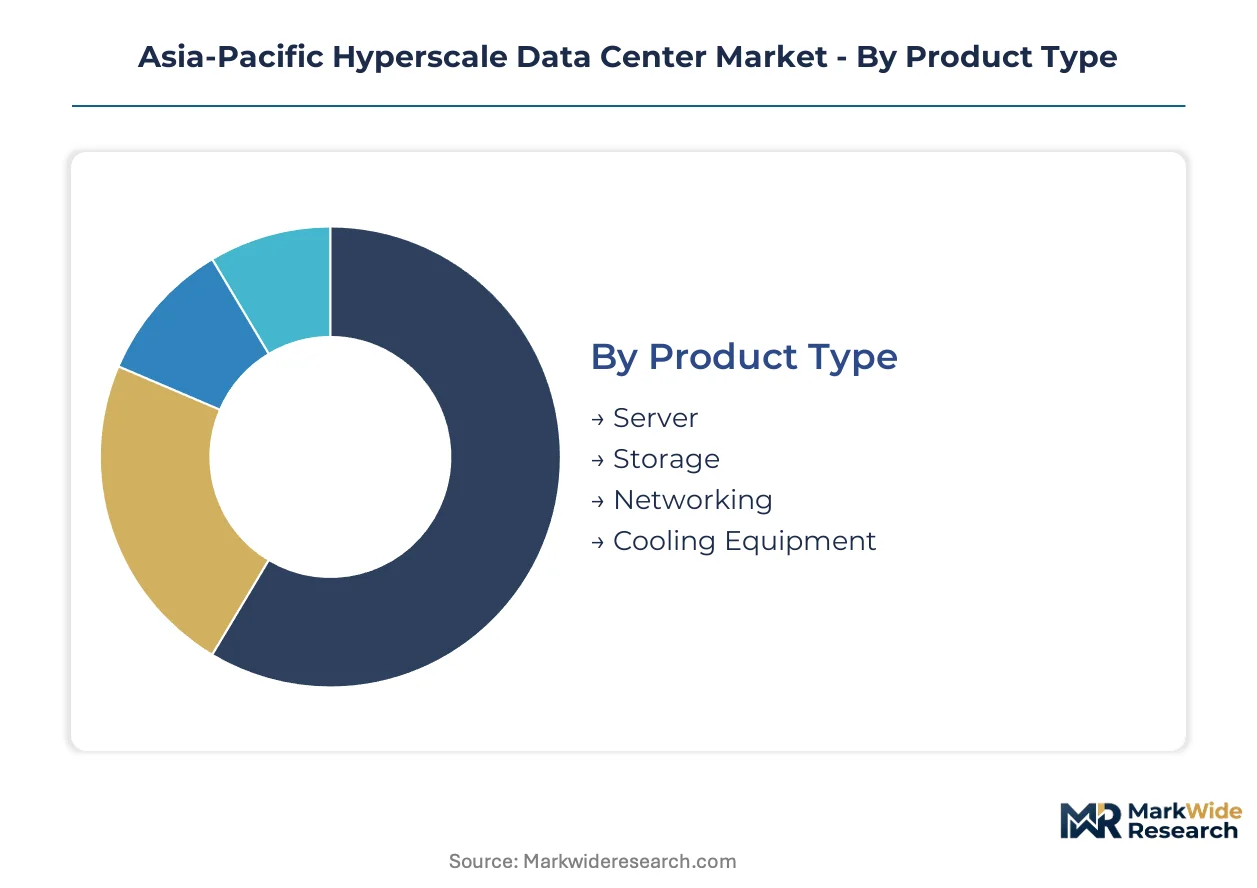
Segmentation reveals how procurement authority concentrates among cloud service providers while deployment models fragment across sovereign data requirements. Understanding these divides exposes where capital allocation shifts and which technology layers capture expanding share.
Product Type:
Server infrastructure anchors domestic demand across China's MIIT-mandated facilities, while cooling equipment exports concentrate through Taiwanese and Japanese component suppliers serving Southeast Asian builds.
- Server:High-density GPU and CPU configurations dominate capital allocation pools, with rack densities exceeding 50 kilowatts for AI training clusters. Demand concentrates in Singapore and Tokyo-Osaka hubs where cloud service providers consolidate foundation model infrastructure, constrained by liquid cooling retrofit timelines.
- Cooling Equipment:Direct liquid cooling systems and immersion tanks are displacing traditional CRAH units as thermal loads intensify. Procurement runs through Chinese and Taiwanese suppliers for cold plate assemblies, creating supply vulnerability for operators outside Greater China.
- Storage:All-flash arrays and NVMe-over-fabrics architectures serve low-latency AI inference workloads.
- Networking:400G and 800G switching fabrics interconnect distributed training clusters across metropolitan zones.
Server commands the established base. The steepest expansion runs through cooling equipment.
End User:
Cloud service providers drive volume procurement through multi-year infrastructure commitments, while enterprises fragment demand across hybrid architectures.
- Cloud Service Providers:AWS, Alibaba Cloud, and regional operators commission facilities exceeding 100 megawatts in single deployments. Procurement concentrates in Mumbai-Pune and Sydney-Canberra corridors where sovereign data localization policies harden, accelerating dedicated capacity builds.
- Enterprises:Financial services and pharmaceutical multinationals rationalize shadow IT through centralized infrastructure teams. Demand fragments across Singapore colocation and Indonesia on-premises retention as compliance requirements diverge.
- Telecommunication Companies:NTT and regional carriers deploy edge-integrated facilities for 5G core network functions.
- Content Providers:Streaming platforms commission high-bandwidth delivery nodes in Jakarta and Bangkok markets.
Cloud service providers command the established base. Enterprise hybrid deployments are climbing the fastest.
Deployment:
Colocation matures in land-constrained Singapore and Hong Kong, while hybrid architectures accelerate in Indonesia and Vietnam as enterprises straddle legacy systems.
- Hybrid:Workload portability between on-premises and cloud environments dominates enterprise procurement criteria. Adoption concentrates among Australian financial services and Indian pharmaceutical multinationals consolidating fragmented departmental contracts.
- Colocation:Multi-tenant economics prevail where land scarcity elevates construction costs. Singapore's Infocomm Media Development Authority restricts permits to carbon-neutral projects, compressing available supply.
- On-Premises:Sovereign cloud requirements under Australia's Critical Infrastructure Act sustain dedicated facility builds.
- Managed Services:Outsourced operations gain traction among mid-market enterprises lacking specialized talent pools.
Colocation commands the established base. Hybrid deployment is gaining share fastest.
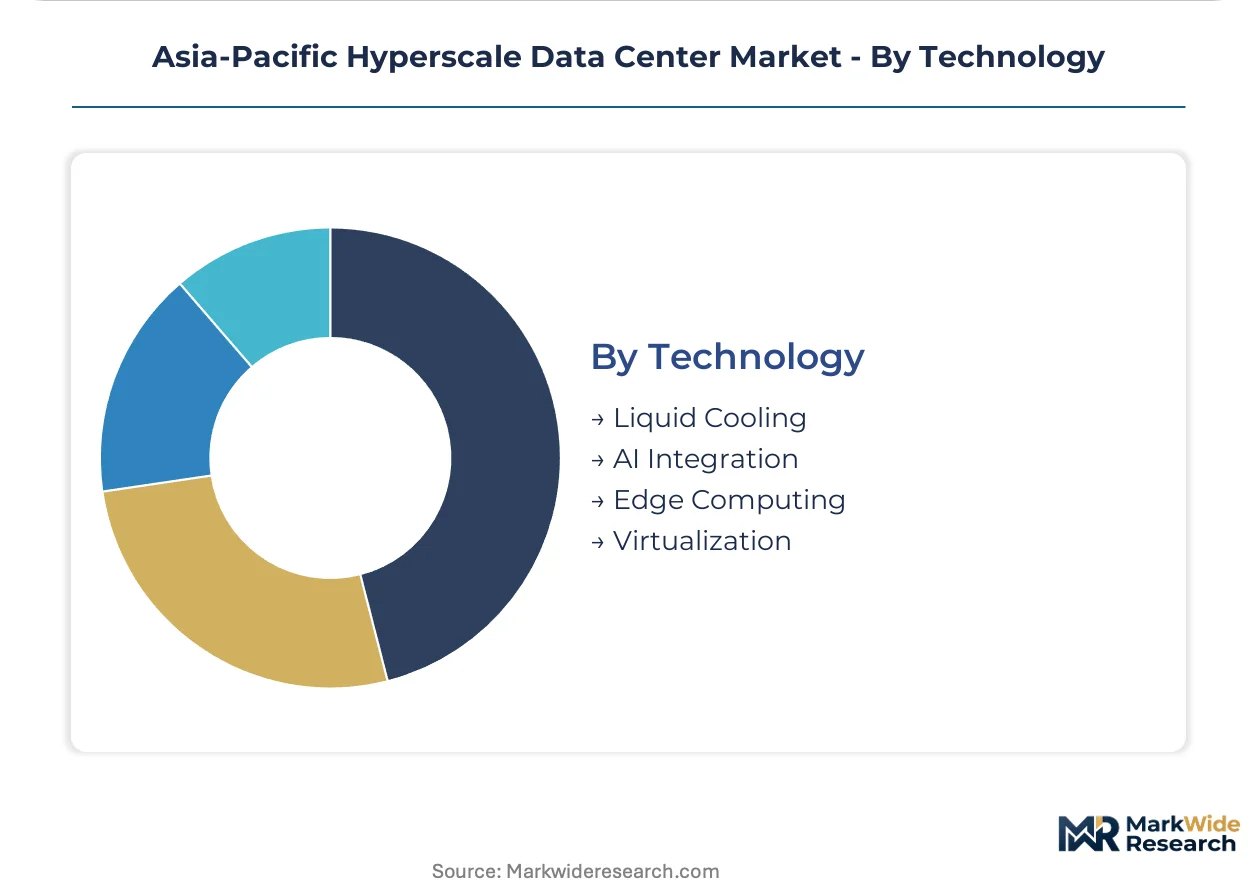
Technology:
Liquid cooling adoption concentrates in new Chinese builds under MIIT efficiency mandates, while edge computing expands across Indonesian and Vietnamese markets with immature grid infrastructure.
- Liquid Cooling:Single-phase immersion and direct-to-chip cold plates enable 100-kilowatt rack densities for AI training. Deployment concentrates in Tokyo-Osaka corridor pilot programs and Chinese hyperscale facilities, constrained by dielectric fluid engineering talent shortages.
- AI Integration:GPU-dense infrastructure for foundation model training reshapes facility power distribution and thermal design. Procurement clusters in Singapore and Sydney where cloud providers anchor regional AI service delivery.
- Edge Computing:Distributed micro-facilities serve latency-sensitive applications in secondary cities.
- Virtualization:Software-defined infrastructure optimizes utilization across fluctuating workload profiles.
Virtualization commands the established base. Liquid cooling is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT mandates are compressing deployment timelines across the region, while India's state-level incentives and Australia's Critical Infrastructure Act reshape capital allocation toward sovereign capacity corridors.
China
Beijing-Tianjin-Hebei and Yangtze River Delta clusters absorb the bulk of new capacity under MIIT's PUE thresholds below 1.3. Guangdong province enforces renewable energy quotas that accelerate liquid cooling retrofits. Shanghai's Lingang New Area hosts hyperscale builds combining captive solar procurement with direct liquid cooling infrastructure.
India
Maharashtra and Telangana state policies offer land allocation and power tariff concessions that pull developers beyond saturated Mumbai-Pune corridors. The Digital Personal Data Protection Act hardens domestic storage requirements. Chennai and Hyderabad are emerging as secondary hubs where cloud service providers secure greenfield parcels at lower land costs.
Australia
Sydney-Canberra axis concentrates sovereign cloud builds under the Critical Infrastructure Act's security obligations. New South Wales and Victoria compete for hyperscale investment through streamlined planning approvals. Melbourne's western suburbs host emerging facilities serving financial services compliance requirements.
Japan
Tokyo-Osaka corridor remains the primary deployment zone where NTT and cloud providers secure direct utility partnerships. METI efficiency standards push liquid cooling adoption in new builds. Osaka's southern industrial belt attracts AI training clusters seeking proximity to submarine cable landing stations.
Singapore
Infocomm Media Development Authority restrictions limit permits to carbon-neutral projects with 100% renewable matching and liquid cooling. Land scarcity forces vertical construction strategies at premium costs. Developers are securing Indonesian solar PPAs before groundbreaking to meet compliance verification through the Energy Market Authority's tracking registry.
Asia-Pacific Hyperscale Data Center Market Competitive Landscape
Player mix skews toward integrated cloud providers with captive infrastructure arms, creating a tiered structure where hyperscale operators control procurement volume and specialized data center REITs capture multi-tenant economics. Three archetypes dominate: global cloud platforms with regional region portfolios, Asia-headquartered technology conglomerates with proprietary silicon and power purchasing, and specialized data center operators with direct utility partnerships. Competitive moves concentrate on securing renewable energy offtake agreements ahead of permit applications and compressing construction timelines through modular factory-integrated subsystems.
Among global cloud platforms, Amazon Web Services, Microsoft Corporation, and Google LLC anchor regional capacity through Mumbai, Singapore, and Sydney region deployments. These entities exemplify the integrated infrastructure archetype where compute, storage, and networking procurement authority concentrates under centralized teams negotiating multi-year committed use structures. Their positioning reflects the shift toward sovereign data localization requirements across ASEAN and Oceania markets.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| Alibaba Group |
| Equinix |
| Digital Realty |
| NTT Global Data Centers |
| Huawei Cloud Computing Technologies |
| NEXTDC |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month utility interconnection timelines in Indonesia and Vietnam compress inventory carrying costs for committed power infrastructure, concentrating pricing power among operators with secured grid access while forcing late entrants toward premium land parcels with existing substations.
Pricing Analysis
Cost-plus contracts indexed to Singapore's landed power costs dominate colocation agreements, with pricing stratifying across premium tier-one certifications, standard multi-tenant facilities, and economy remote-hall configurations. Price differentiation hinges on ISO 27001 audit tier and renewable energy matching percentage. Cost compression in standard-tier builds intensifies as Chinese cold plate suppliers expand export capacity. Cloud service providers exhibit lowest price sensitivity due to committed use structures; mid-market enterprises face acute pressure from shadow IT consolidation mandates.
Supply Chain Analysis
Port congestion across the Shanghai-Ningbo trade lane elevates inbound logistics costs for Taiwanese cold plate assemblies and Japanese dielectric fluid systems. Manufacturing concentrates in China, Taiwan, and South Korea for server infrastructure, with German and Japanese suppliers anchoring thermal fluid chemistry. The supply chain rests on single-source vulnerability for two-phase heat transfer components outside Greater China. Distribution runs through direct utility partnerships for power infrastructure and specialized HVAC contractors for liquid cooling deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dielectric fluid engineering talent shortages in Southeast Asia constrain operator self-build capabilities, creating a structural bottleneck where facility owners must either captive-source specialized skills or accept vendor lock-in from Japanese and German supplier engineering teams.
For Market Incumbents: Compound renewable energy procurement advantages by securing Indonesian solar PPAs ahead of Singapore's Energy Market Authority compliance verification deadlines. Deepen captive power purchasing in Maharashtra and Telangana to preempt state-level incentive exhaustion. Defend against stranded asset risk through selective air-cooled facility divestment before AI workload obsolescence accelerates.
For New Entrants and Emerging Players: Managed liquid cooling retrofit services for legacy air-cooled facilities represent the most penetrable white-space target, as operator engineering teams lack two-phase heat transfer system design capabilities. Target Australian financial services and Indian pharmaceutical multinationals consolidating fragmented departmental contracts. Lead with sovereign cloud certification bundled with thermal infrastructure modernization to bypass incumbent colocation relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from Japanese automotive and electronics manufacturers piloting 500-kilowatt immersion tank deployments for AI inference workloads. Long-term viability favors operators with secured land positions in Chennai and Hyderabad where cloud service providers seek greenfield capacity at lower land costs than saturated Mumbai-Pune corridors. Monitor MIIT enforcement intensity in Guangdong province as inflection indicator for Chinese liquid cooling retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Retrofit | Enables 100-kilowatt rack densities for AI training clusters under MIIT PUE mandates. |
| Cross-Border Renewable PPA | Satisfies Singapore's carbon-neutral permit requirements through Indonesian solar procurement. |
| Modular Factory-Integrated Subsystem | Compresses on-site construction timelines for vertical builds in land-scarce Singapore. |
| Sovereign Cloud Certification | Aligns with Australia's Critical Infrastructure Act security obligations for financial services. |
| State-Level Incentive Capture | Secures land allocation and power tariff concessions in Maharashtra and Telangana corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing data center facility directors, cloud provider infrastructure procurement leads, utility interconnection planners, and liquid cooling system engineering specialists. Secondary validation drew from MIIT policy circulars, Singapore Energy Market Authority tracking registry disclosures, Australian Critical Infrastructure Act guidance notes, and hyperscaler capital expenditure filings. Bottom-up facility-level capacity builds were triangulated against top-down regional demand projections across the analysis window.
Across the modeling period, the analytical framework segmented volume and value outputs by product type, end-user archetype, deployment model, and technology layer, with regional regulatory clusters as an additional dimension. CAGRs were derived from installed base growth rates and replacement cycle acceleration for air-cooled legacy facilities. Forecast inputs incorporated GPU cluster density trajectories and sovereign data localization policy enforcement timelines.
Forecasts assume regulatory continuity in China's MIIT efficiency mandates, Singapore's carbon-neutral permit framework, and India's Digital Personal Data Protection Act; material policy shifts would require re-modeling deployment timelines and capital allocation patterns. Specific risks include tariff escalation on Taiwanese cold plate imports and extended utility interconnection delays in Indonesian and Vietnamese markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Underwater Data Center Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Sweden Data Center Server Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market