
 Taiwan Data Center Networking Market | 2026-2036
Taiwan Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Networking Market Insights
AI-driven workload orchestration is rewriting how data center fabrics handle east-west traffic patterns in Taiwan facilities. Cisco Systems leverages its ASIC portfolio to anchor switching deployments at hyperscale campuses. Arista Networks differentiates through cloud-grade operating systems optimized for low-latency AI training clusters. NVIDIA Corporation extends its position by integrating networking silicon with GPU-centric server architectures.
Taiwan data center networking encompasses the switching, routing, and interconnect infrastructure that enables compute-to-compute and compute-to-storage communication within facilities, typically operating at speeds from 100 Gbps to 800 Gbps with sub-microsecond latency requirements. The equipment category spans switches, routers, firewalls, and load balancers, with Ethernet technology dominating current deployments while InfiniBand gains traction for high-performance computing environments. Optical fiber technology leads capital allocation as hyperscalers upgrade spine-leaf architectures, and the cloud provider end-user segment commands the largest share of infrastructure spending due to AI cloud service expansion.
Taiwan's National Communications Commission enforces telecommunications infrastructure standards, while the National Institute of Standards and Technology frameworks inform cybersecurity compliance for cross-border data flows. The country's Ministry of Digital Affairs shapes data sovereignty requirements that affect network architecture decisions for foreign-operated facilities. Stakeholders must monitor how domestic semiconductor export controls and evolving energy efficiency mandates interact with networking equipment procurement cycles.
Market Dynamics
AI training clusters are compressing switch refresh cycles from five years to eighteen months as hyperscalers chase sub-microsecond latency for GPU-to-GPU communication. This acceleration is reshaping capital allocation across Taiwan's data center corridor.
Growth Catalysts
- Generative AI inference demand:Cloud providers in Hsinchu Science Park are deploying 800 Gbps spine-leaf architectures to support large language model serving at scale.
- National Institute of Standards and Technology cybersecurity frameworks:Cross-border data flow compliance is mandating zero-trust network segmentation in foreign-operated facilities.
- Silicon photonics integration:Optical interconnect density is doubling per rack unit, enabling power-efficient scaling of east-west traffic in AI training environments.
Market Restraints
- Advanced ASIC supply concentration:Taiwan's dependence on a single foundry ecosystem for high-end switching silicon creates vulnerability in 3nm node allocation.
- Copper and rare earth price volatility:Optical transceiver manufacturing faces input cost pressure from dysprosium and terbium supply constraints.
- InfiniBand-Ethernet protocol fragmentation:Competing interconnect standards force redundant inventory and qualification overhead for multi-tenant facilities.
Strategic Opportunities
- Edge AI inference in Taichung:Secondary metropolitan clusters lack high-bandwidth interconnect infrastructure, creating greenfield deployment potential for distributed training nodes.
- Ministry of Digital Affairs data sovereignty mandates:Localized routing requirements are generating demand for domestically certified firewall and load balancer appliances.
- Co-packaged optics convergence:Switch ASIC and silicon photonics integration is collapsing power budgets and physical footprint for next-generation top-of-rack designs.
Industry Challenges
- Terabit-scale network engineering talent scarcity:Taiwan's technical institutes produce insufficient graduates versed in 800 Gbps signal integrity and PAM4 modulation.
- Legacy 100 Gbps infrastructure stranding:Existing leaf switches lack the buffer depth and programmable pipeline features required for RoCEv2 congestion management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Networking Market |
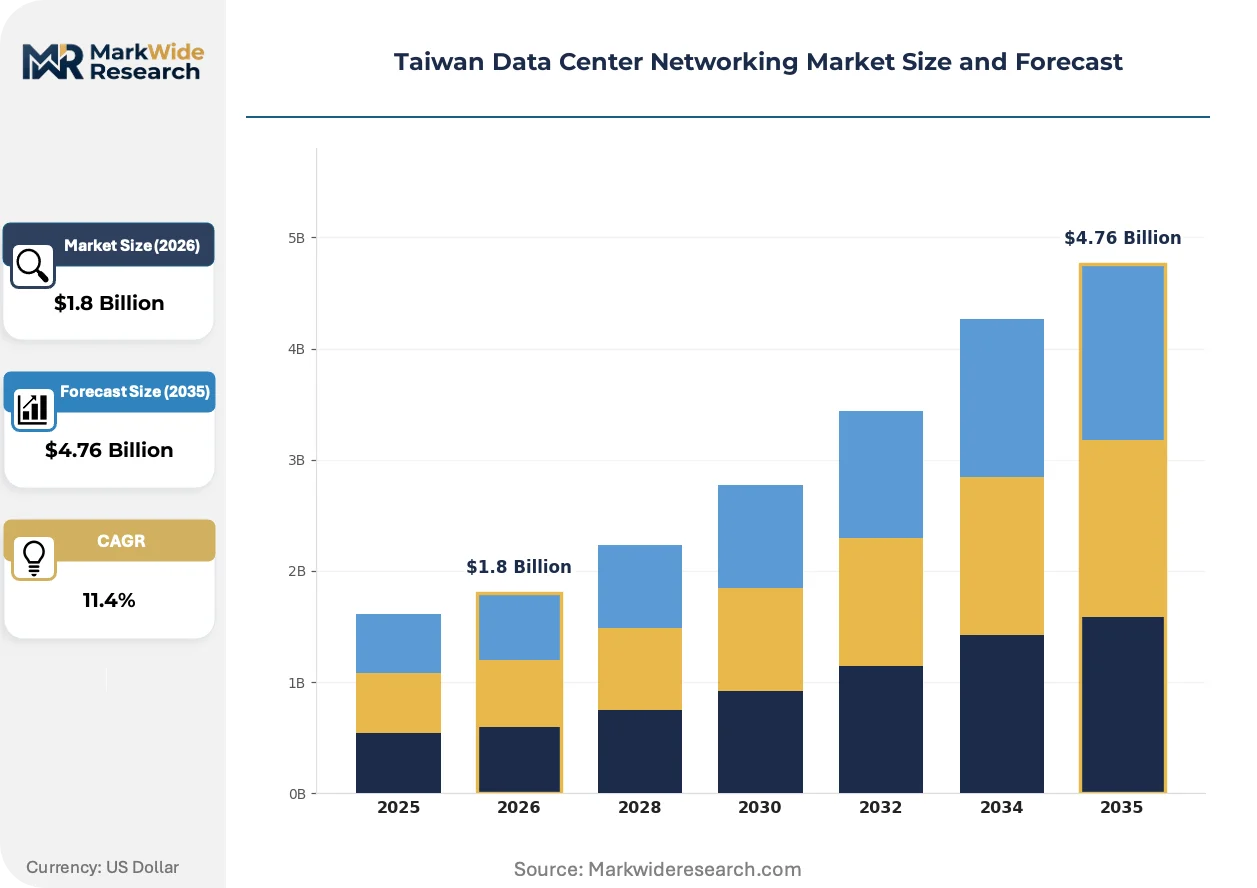
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Switches, Routers, Firewalls, Load Balancers Technology: Ethernet, Optical Fiber, InfiniBand, MPLS End User: Cloud Providers, Enterprises, Telecom Operators, Government Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Cisco Systems, Arista Networks, Huawei Technologies, Extreme Networks, VMware, NVIDIA Corporation, Dell, NEC Corporation, Broadcom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Networking Market Trends and Innovations
Programmable data planes and intent-based automation are displacing manual configuration in Taiwan facilities. These shifts are compressing provisioning timelines and hardening security posture simultaneously.
Co-packaged optics is digitizing switch-to-switch interconnect economics by embedding silicon photonics directly onto switch ASIC substrates. Hyperscale operators in Taipei metropolitan clusters are qualifying these designs for 51.2 Tbps aggregate bandwidth targets. The technology is digitizing power-per-bit calculations and collapsing optical component count in spine layers.
Taiwan's National Communications Commission is tightening electromagnetic compatibility certification timelines for critical infrastructure networking equipment. The industrial consequence is extended pre-deployment validation cycles for imported switch platforms. Foreign vendors are responding by establishing local testing partnerships and pre-certifying designs through domestic laboratories.
Buyers are consolidating vendor relationships around full-stack networking vendors capable of delivering switching, telemetry, and automation software under unified support contracts. Systems integrators serving Taiwan's cloud provider segment are losing margin to direct manufacturer relationships. This concentration is most visible among AI cloud operators in Hsinchu Science Park demanding single-throat-to-choke accountability for fabric performance.
Taiwan Data Center Networking Market Segmentation
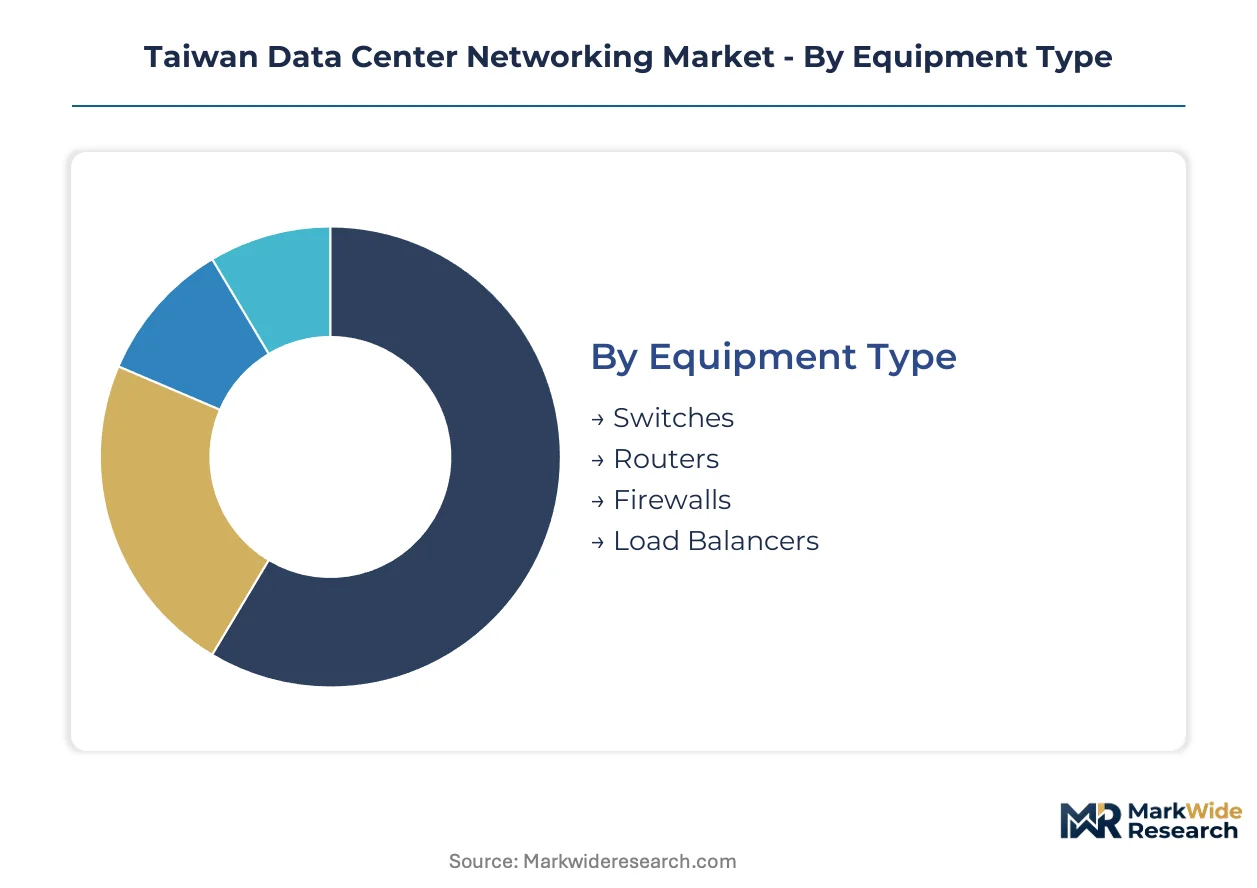
Segmentation reveals how capital allocation splits between hardware procurement and service engagement models across Taiwan's data center corridor. Equipment type and technology choices determine infrastructure lifecycle economics, while end user profiles and service arrangements shape vendor relationship structures.
Equipment Type:
Mature switching platforms anchor current deployments, while emerging programmable fabrics are gaining share in AI-optimized facilities.
- Switches:Spine-leaf architectures dominate hyperscale builds, with 400 Gbps and 800 Gbps port densities now standard for new Hsinchu Science Park installations. Cloud providers in Taipei metropolitan clusters are driving demand for programmable pipelines supporting RoCEv2 congestion management.
- Routers:Border gateway platforms handle inter-facility traffic and cross-border connectivity, with demand concentrating at internet exchange points serving AI training campuses. The National Communications Commission's cybersecurity mandates are accelerating refresh cycles for stateful inspection capabilities.
- Firewalls:Next-generation platforms with TLS 1.3 decryption are required for Ministry of Digital Affairs data sovereignty compliance in foreign-operated facilities.
- Load Balancers:Application delivery controllers supporting containerized microservices are expanding fastest in cloud provider edge nodes across Taichung.
Switches retain volume leadership; load balancers hold the steepest expansion curve.
Technology:
Cost tier stratification separates commodity Ethernet deployments from premium optical and InfiniBand interconnects serving latency-sensitive workloads.
- Ethernet:Dominates general-purpose compute fabrics with 100 Gbps to 400 Gbps standard deployments, though buffer depth limitations constrain AI training efficiency. Enterprise data centers in Taipei favor this technology for cost-predictable refresh cycles.
- Optical Fiber:Silicon photonics integration is collapsing power-per-bit economics in spine layers, with co-packaged optics designs now qualifying for 51.2 Tbps aggregate bandwidth targets. Hyperscale operators are prioritizing this technology for east-west traffic scaling.
- InfiniBand:Sub-microsecond latency requirements for GPU-to-GPU communication are expanding adoption in Hsinchu AI training clusters, despite protocol fragmentation challenges with Ethernet alternatives.
- MPLS:Legacy enterprise WAN interconnects persist in regulated verticals requiring deterministic path control, though SD-WAN substitution is accelerating.
Ethernet commands the largest installed base; optical fiber is climbing the fastest.
End User:
Customer type determines procurement scale, with hyperscale cloud operators consolidating vendor relationships around full-stack accountability.
- Cloud Providers:Hyperscale operators in Hsinchu Science Park and Taipei metropolitan clusters drive 800 Gbps spine-leaf refresh cycles, demanding single-throat-to-choke vendor relationships for fabric performance. AI cloud service expansion is compressing equipment refresh from five years to eighteen months.
- Enterprises:Financial services and semiconductor manufacturers in Tainan and Taichung are adopting zero-trust segmentation for National Institute of Standards and Technology cross-border compliance, though procurement volumes trail cloud provider scale.
- Telecom Operators:5G core network virtualization is generating demand for telco-grade routing resilience in facilities serving mobile edge computing nodes.
- Government:Critical infrastructure mandates from the National Communications Commission are driving domestic certification requirements for firewall and load balancer appliances in sovereign data centers.
Cloud providers dominate capital deployment; government infrastructure is expanding most quickly.
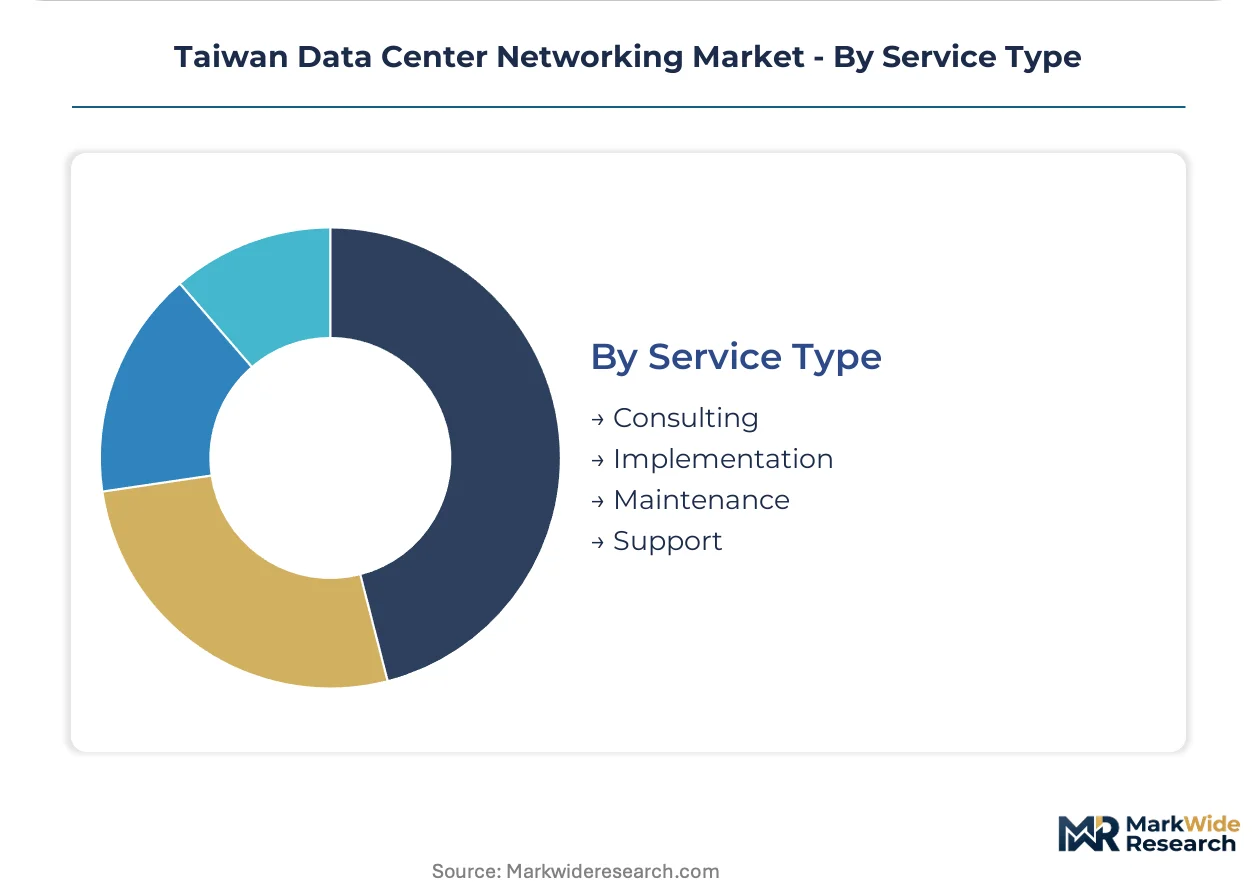
Service Type:
Margin concentration favors implementation and maintenance engagements over commoditized consulting arrangements.
- Consulting:Network architecture design services for AI training cluster optimization command premium pricing in Hsinchu, though repeatable methodologies are compressing differentiation.
- Implementation:Spine-leaf deployment and migration services generate the highest service attach rates, particularly for 400 Gbps to 800 Gbps upgrade projects requiring signal integrity validation.
- Maintenance:Hardware replacement and firmware management contracts provide recurring revenue stability, with telemetry-enabled predictive support gaining traction among cloud providers.
- Support:24/7 network operations center services are consolidating around vendors with local Mandarin-speaking engineering presence in Taipei.
Implementation captures the largest service contract value; maintenance delivers the most predictable recurring streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports data center networking equipment to hyperscale operators across the United States, Japan, and Singapore. The island's foundry ecosystem supplies switching ASICs to global cloud infrastructure builders. Cross-border data flow regulations in destination markets shape product certification requirements for Taiwanese manufacturers.
Hsinchu Science Park
AI training clusters drive 800 Gbps spine-leaf deployments across hyperscale campuses. The National Communications Commission enforces electromagnetic compatibility standards for critical infrastructure equipment. Cloud providers concentrate procurement decisions here, compressing switch refresh cycles to eighteen months.
Taipei Metropolitan Clusters
Enterprise data centers adopt zero-trust segmentation for cross-border compliance with National Institute of Standards and Technology frameworks. The Ministry of Digital Affairs mandates data sovereignty requirements affecting foreign-operated facility network architecture. Financial services and semiconductor manufacturers dominate demand in Songshan and Neihu districts.
Taichung Secondary Metro
Edge AI inference nodes lack high-bandwidth interconnect infrastructure, creating greenfield deployment opportunities. The National Communications Commission cybersecurity standards extend to distributed training facilities. Industrial parks in the Taichung Harbor zone attract cloud provider edge node investments.
Tainan Technology Corridor
Legacy enterprise facilities face 100 Gbps infrastructure stranding as RoCEv2 congestion management requirements escalate. The Ministry of Digital Affairs data localization rules affect multi-tenant facility network designs. Semiconductor packaging and testing operations generate specialized low-latency interconnect demand.
Kaohsiung Maritime Hub
Submarine cable landing stations anchor international bandwidth exchange infrastructure. The National Communications Commission regulates cross-border telecommunications gateway equipment. CHT and other carriers expand neutral host data center capacity near Asia-Pacific cable systems.
Taiwan Data Center Networking Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement contracts across Taiwan's data center corridor. The vendor base stratifies into full-stack networking providers, programmable silicon specialists, and optical interconnect fabricators. Three archetypes dominate: ASIC-integrated platform vendors, cloud-grade operating system providers, and silicon photonics innovators. Competitive moves center on co-packaged optics convergence and direct manufacturer relationships displacing systems integrator margins.
Within the full-stack platform tier, Cisco Systems and Arista Networks exemplify channel-controlling archetypes with unified support accountability. NVIDIA Corporation occupies a distinct position integrating networking silicon with GPU-centric architectures. These three anchors represent divergent strategic postures: legacy switching dominance, cloud-native operating system specialization, and AI workload-optimized convergence.
| Leading Market Players |
|---|
| Cisco Systems |
| Arista Networks |
| Huawei Technologies |
| Extreme Networks |
| VMware |
| NVIDIA Corporation |
| Dell |
| NEC Corporation |
| Broadcom |
| Others |
Pricing and Supply Chain Analysis
Kaohsiung Port-to-Hsinchu freight corridors carry optical transceiver components at rates indexed to dysprosium and terbium spot markets, concentrating margin pressure on Taiwanese switching equipment manufacturers while enabling tiered pricing power for vendors with captive silicon photonics capabilities.
Pricing Analysis
Cost-plus contracts with London Metal Exchange rare earth indexation dominate optical component procurement, separating vendors with backward integration into silicon photonics from standard Ethernet switch assemblers. Price differentiation rests on certification grade under National Communications Commission electromagnetic compatibility standards and volume scale for hyperscale cloud provider commitments. Pricing pressure stems from copper and rare earth price volatility in optical transceiver manufacturing. Enterprise data centers in Taipei exhibit highest price sensitivity due to budget-predictable refresh cycles, while Hsinchu AI cloud operators prioritize latency performance over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk assessment for Taiwanese networking equipment vendors dependent on mainland rare earth processing. Manufacturing concentration centers on Taiwan for 3nm switching ASICs, Japan for precision optical components, and Malaysia for final assembly operations. Raw material dependencies include dysprosium and terbium for optical transceivers, high-purity silicon for photonics substrates, and advanced laminate materials for signal integrity. Single-source vulnerability persists at the 3nm foundry node for high-end switching silicon. Distribution runs through direct manufacturer relationships with hyperscale cloud providers, displacing systems integrator margins in Hsinchu and Taipei clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan data center networking fragmentation creates entry niches as AI workload specialization splits demand between Ethernet generalists and InfiniBand latency optimizers, with protocol fragmentation forcing redundant vendor qualification overhead.
For Market Incumbents: Harden switching ASIC supply security through multi-foundry qualification at 5nm and 3nm nodes to offset single-source vulnerability from Taiwan's concentrated foundry ecosystem. Deepen telemetry-enabled predictive maintenance contracts to lock in cloud provider recurring revenue against Arista Networks cloud-grade operating system competition. Prioritize co-packaged optics R&D investment to collapse power-per-bit economics and defend spine-layer market share. For New Entrants and Emerging Players: Edge AI inference nodes in Taichung secondary metropolitan clusters represent the most penetrable entry point, lacking high-bandwidth interconnect infrastructure for distributed training workloads. Ministry of Digital Affairs data sovereignty mandates for domestically certified firewall appliances create greenfield demand in government and foreign-operated facilities. Go-to-market execution should anchor on local Mandarin-speaking engineering support partnerships to displace foreign vendor maintenance contracts. For Investors and Strategic Acquirers: Silicon photonics specialists with switch ASIC integration capabilities present the most attractive acquisition archetype for next-generation co-packaged optics convergence. Long-term viability hinges on terabit-scale network engineering talent pipeline development and qualification timelines under tightening National Communications Commission certification windows. Monitor hyperscaler capex disclosure patterns for 800 Gbps spine-leaf deployment acceleration as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Convergence | Embedding silicon photonics onto switch ASIC substrates collapses power budgets for 51.2 Tbps spine targets. |
| Domestic Certification Partnership | Local testing laboratory relationships compress National Communications Commission electromagnetic compatibility validation timelines. |
| Terabit-Scale Talent Pipeline | Taiwan technical institute partnerships address 800 Gbps signal integrity and PAM4 modulation engineering scarcity. |
| Direct Hyperscale Relationships | Single-throat-to-choke vendor accountability displaces systems integrator margins in Hsinchu Science Park. |
| Multi-Protocol Inventory Rationalization | Unified Ethernet-InfiniBand qualification reduces redundant switching platform overhead for multi-tenant facilities. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with data center network architects, cloud infrastructure procurement officers, semiconductor foundry planning executives, and National Communications Commission regulatory staff; and secondary validation through hyperscaler capex disclosures, Taiwan Ministry of Digital Affairs policy filings, and optical component trade flow data. Bottom-up equipment shipment estimates triangulated against top-down infrastructure spending projections across the analysis window.
Forecast inputs considered equipment type segmentation by switching platform generation, technology adoption curves for silicon photonics and InfiniBand, end-user concentration in cloud provider versus enterprise facilities, and service type margin structures. CAGRs were derived from weighted average growth across these dimensions, incorporating AI training cluster refresh cycle compression from five years to eighteen months and Ministry of Digital Affairs data sovereignty mandate implementation timelines.
Practitioners should monitor rare earth supply disruption indicators, National Communications Commission certification timeline revisions, and hyperscaler GPU deployment acceleration for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Nosql Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Netherlands Data Center Networking Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Brazil Servers Market