
 Spain Data Center Networking Market | 2026-2036
Spain Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Data Center Networking Market Insights
Copper backplane cabling is pivoting toward silicon photonics interconnects in high-density Spain data center builds, cutting power-per-bit transmission costs. Cisco Systems Inc. leverages its merchant silicon partnerships to dominate spine-leaf architectures in Iberian hyperscale facilities. Arista Networks Inc. differentiates through ultra-low-latency switching platforms purpose-built for algorithmic trading co-location in Madrid. Juniper Networks Inc. anchors its position via automated fabric management software that reduces provisioning cycles for multi-tenant environments.
Spain data center networking encompasses the switching, routing, and interconnect infrastructure that enables compute-to-compute and compute-to-storage communication within facilities, typically operating at speeds from 25 Gbps to 800 Gbps per port with latency budgets under 500 nanoseconds for financial applications. This infrastructure serves cloud providers, enterprises, and telecommunications carriers that require deterministic performance for distributed workloads. Ethernet switches command the largest product type revenue pool as hyperscalers standardize on 400 GbE leaf-spine designs, while InfiniBand technology captures the fastest expansion trajectory among AI training clusters where RDMA over Converged Ethernet competes for socket share. Hybrid cloud deployment generates disproportionate margin concentration as enterprises bridge on-premises VMware stacks with Azure and AWS regional zones, creating complex interconnection requirements that favor vendors with unified management planes.
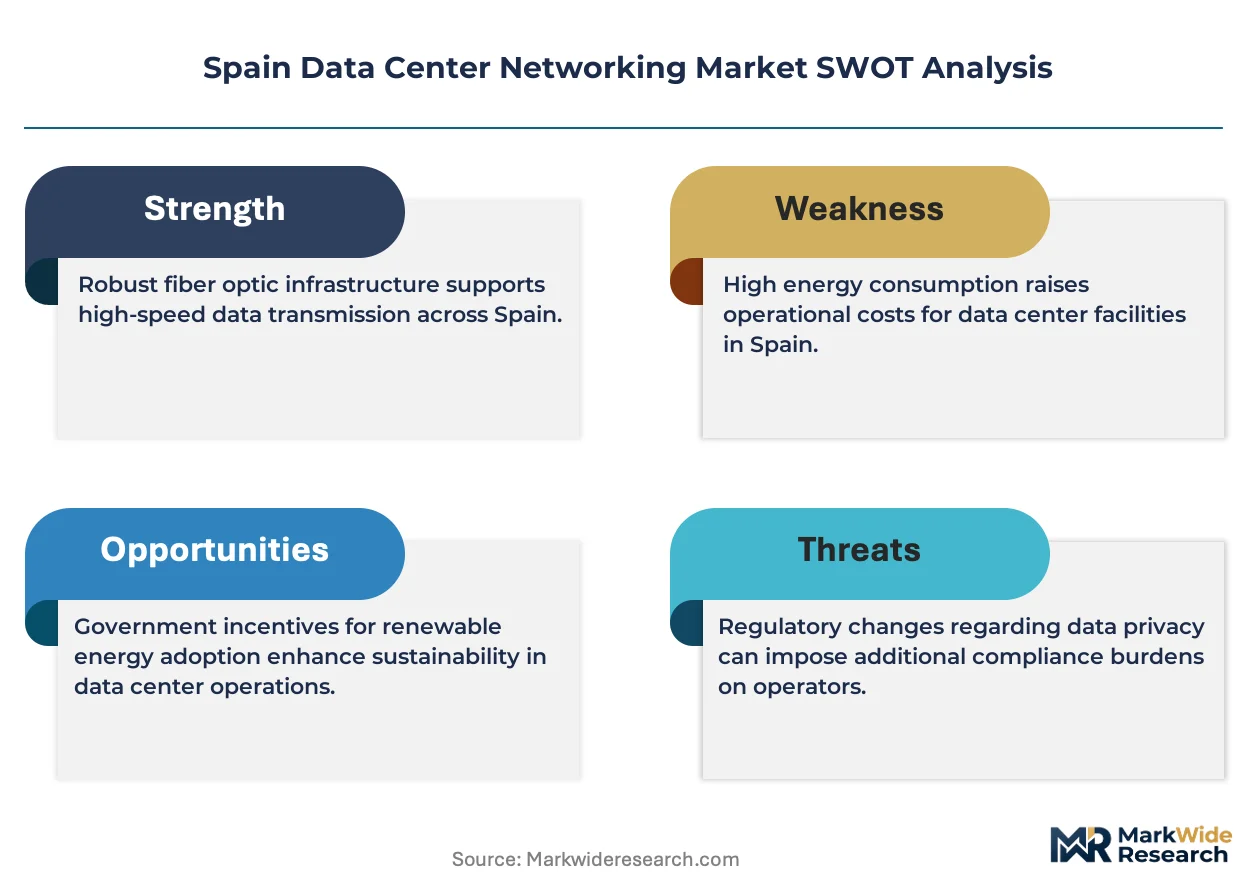
Spain's national cybersecurity regulator enforces NIS2 transposition measures that mandate encrypted east-west traffic inspection, directly expanding demand for next-generation firewall-integrated switches. The EU AI Act's risk-classification framework for automated decision systems pressures data center operators to implement auditable network segmentation, reinforcing procurement of policy-driven microsegmentation platforms. Stakeholders must weigh sovereign cloud certification requirements against the operational complexity of maintaining parallel network fabrics for regulated and non-regulated workloads.
Market Dynamics
Silicon photonics interconnects are compressing power-per-bit transmission costs in Madrid and Barcelona hyperscale builds, forcing incumbent copper backplane vendors to accelerate R&D cycles or cede socket share in high-density leaf-spine architectures.
Growth Catalysts
- NIS2 transposition:Spain's national cybersecurity regulator mandates encrypted east-west traffic inspection, expanding demand for next-generation firewall-integrated switches in financial and government data centers.
- Algorithmic trading co-location:Madrid's proximity to submarine cable landing stations attracts ultra-low-latency switching deployments for derivatives exchanges and quantitative hedge funds.
- Renewable energy interconnection:Hyperscale operators cluster facilities near wind and solar farms in the Madrid metro corridor to meet carbon neutrality commitments while securing favorable power purchase agreements.
Market Restraints
- Merchant silicon concentration:Spine-leaf switch ASIC sourcing depends on a narrow supplier base in Taiwan and the United States, exposing Spanish integrators to geopolitical supply disruptions.
- Copper price volatility:Power distribution infrastructure remains tethered to copper busbar and cabling costs, which fluctuate with London Metal Exchange pricing and mining output constraints in Chile and Peru.
- Optical transceiver thermal limits:800 Gbps pluggable modules exceed 15-watt power envelopes in dense chassis configurations, restricting deployment flexibility in legacy cooling environments.
Strategic Opportunities
- Andalusia edge expansion:Secondary markets like Seville and Málaga offer undeveloped land and submarine cable diversity for latency-sensitive content delivery networks serving North Africa and Latin America.
- EU AI Act segmentation:Risk-classification frameworks for automated decision systems create procurement pull for auditable microsegmentation platforms in healthcare and public sector data centers.
- RDMA over Converged Ethernet convergence:AI training clusters in Barcelona are adopting RoCEv2 as an InfiniBand alternative, opening socket opportunities for Ethernet-native vendors in high-performance computing interconnects.
Industry Challenges
- Optical packaging engineering scarcity:Spanish universities produce limited graduates with silicon photonics co-packaging expertise, forcing operators to recruit from Dutch and German talent pools.
- CSRD reporting integration:EU Corporate Sustainability Reporting Directive mandates granular Scope 3 emissions disclosure across network equipment supply chains, extending procurement cycles by 4-6 months.
- VMware-AWS-Azure fabric interoperability:Enterprise hybrid cloud deployments require unified management planes across incompatible orchestration stacks, complicating multi-vendor support agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Data Center Networking Market |
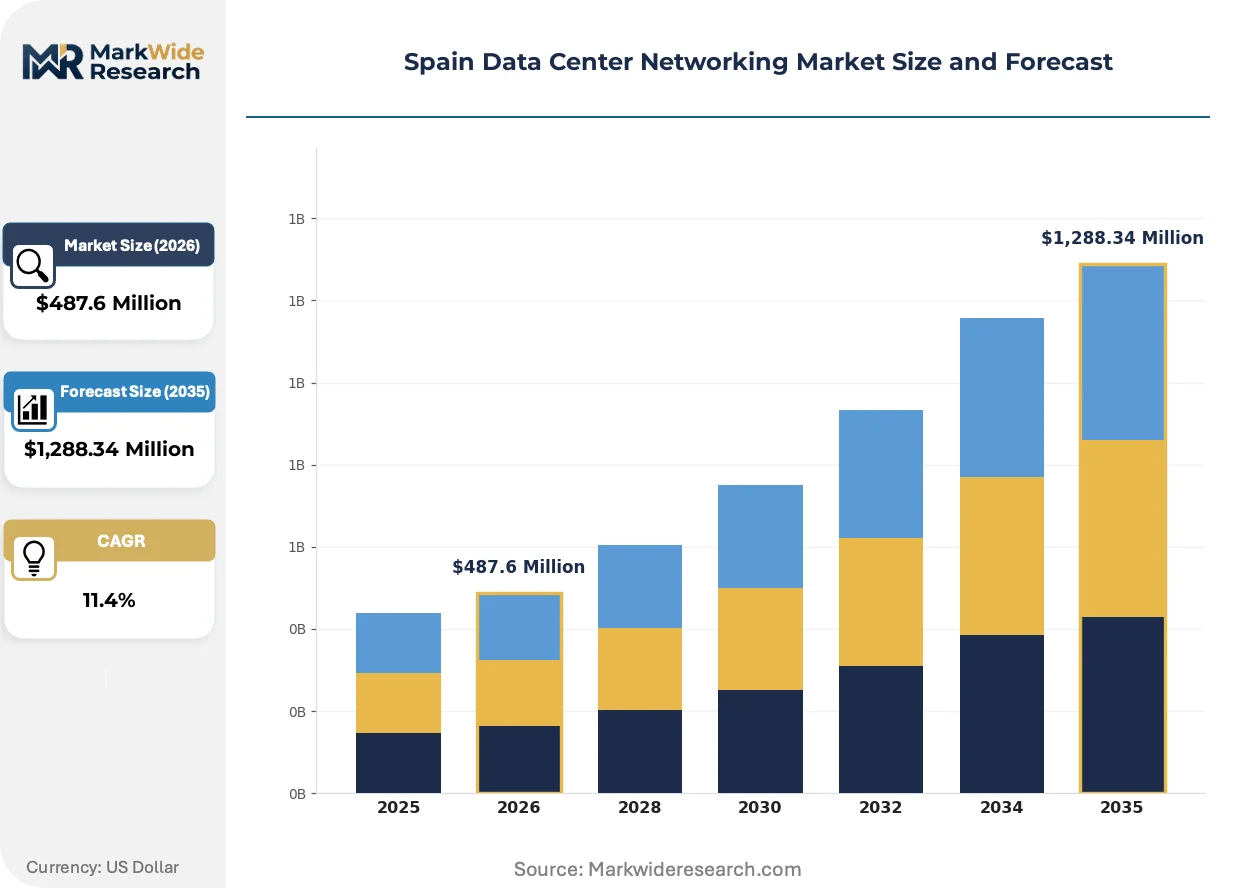
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Network Interface Cards, Access Points Deployment Type: On-Premises, Colocation, Private Cloud, Hybrid Cloud End User: Telecommunications, BFSI, Retail, IT Services Technology: Ethernet, Fiber Channel, InfiniBand, Wi-Fi 6 |
| Companies Covered | Cisco Systems Inc., Juniper Networks Inc., Arista Networks Inc., Broadcom Inc., Hewlett Packard Enterprise, Dell Technologies, VMware Inc., NEC Corporation, Fujitsu Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Data Center Networking Market Trends and Innovations
Co-packaged optics and policy-driven network automation are compressing architectural refresh cycles while regulatory pressure on embodied carbon forces equipment procurement to prioritize energy efficiency metrics over port density alone.
Co-packaged optics is electrifying Spain data center networking by integrating silicon photonics directly into switch ASIC packages, eliminating pluggable transceiver power overhead. Hyperscale operators in Madrid are piloting 51.2 Tbps switches with co-packaged engines to cut thermal load per rack by 30%. This technology is electrifying competitive positioning among vendors racing to deliver production volumes before 400 GbE refresh waves peak.
EU CSRD reporting mandates are forcing Spanish data center operators to document Scope 3 emissions across network equipment lifecycles, including embodied carbon in semiconductor manufacturing. Procurement teams now require vendors to submit third-party verified environmental product declarations before contract award. Financial services and public sector verticals are most affected, with several Madrid operators delaying 2024 expansion projects to align supplier qualification workflows with disclosure timelines.
Consumption-based network-as-a-service contracts are displacing traditional capex-heavy ownership models among mid-market Spanish enterprises. Colocation providers in Barcelona now offer bundled switching, routing, and security infrastructure with metered pricing tied to actual traffic volumes. This shift is most visible in pharmaceutical and legal services verticals, where IT budgets prioritize operational flexibility over asset control.
Spain Data Center Networking Market Segmentation
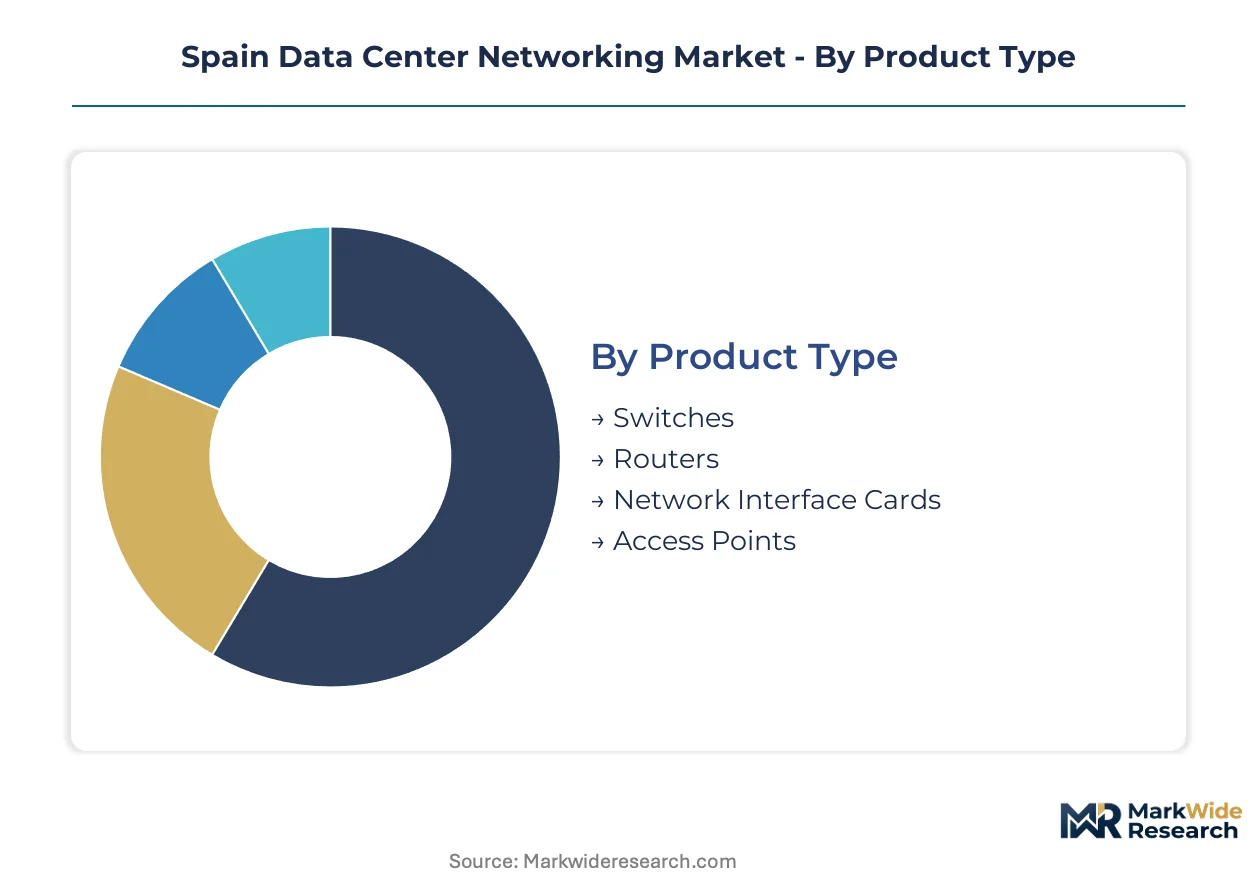
Spain data center networking procurement follows distinct technical and commercial logics across product categories, deployment models, and end-user verticals. Buyers prioritize latency determinism in financial applications, power efficiency in hyperscale builds, and interoperability in hybrid environments.
Product Type:
Capital allocation tilts toward port density and power efficiency as hyperscalers refresh Madrid and Barcelona facilities.
- Switches:Spine-leaf architectures dominate hyperscale deployments, with 400 GbE leaf switches capturing procurement volume in Madrid metro corridor facilities. Cloud providers standardize on merchant silicon-based platforms to reduce vendor lock-in and accelerate refresh cycles.
- Routers:Border gateway and WAN aggregation platforms handle inter-facility traffic between Barcelona submarine cable landing stations and Madrid compute clusters. Telefonica and regional carriers deploy disaggregated routing stacks to separate hardware from control plane software.
- Network Interface Cards:SmartNICs with DPU offloading gain traction in AI training clusters for RDMA acceleration.
- Access Points:Wi-Fi 6E supports out-of-band management and technician mobility in hyperscale halls.
Switches lead on scale; InfiniBand-adjacent NIC architectures lead on momentum.
Deployment Type:
Operational control requirements and data sovereignty obligations fragment procurement patterns across Spanish enterprises.
- Hybrid Cloud:Enterprises bridge on-premises VMware estates with Azure and AWS Madrid zones, creating complex east-west traffic patterns that demand unified policy management. Financial services and pharmaceutical verticals drive this segment as they navigate NIS2 compliance while leveraging public cloud burst capacity.
- Colocation:Barcelona and Madrid facilities attract mid-market enterprises seeking metered networking without capital ownership. Providers bundle switching, cross-connects, and DDoS protection into per-rack or per-cabinet service contracts.
- On-Premises:Defense and classified government workloads mandate fully owned infrastructure with air-gapped segmentation.
- Private Cloud:Large enterprises in automotive and industrial sectors maintain OpenStack or VMware-based fabrics for legacy application hosting.
Colocation leads on scale; hybrid cloud leads on momentum.
End User:
Latency sensitivity and regulatory exposure determine vendor selection criteria across Spanish verticals.
- BFSI:Algorithmic trading co-location in Madrid demands sub-500 nanosecond switching latency with deterministic jitter profiles. Banco Santander and BBVA deploy ultra-low-latency leaf switches alongside precision timing infrastructure for derivatives market making.
- Telecommunications:Telefonica, Vodafone Spain, and Orange España operate national backbone interconnection points that feed retail and wholesale data center services. These carriers prioritize multi-tenant network automation and zero-touch provisioning for enterprise VPN and cloud on-ramp products.
- IT Services:Systems integrators and managed service providers resell white-labeled networking infrastructure to SME clients.
- Retail:E-commerce platforms and omnichannel operators concentrate in Barcelona for Mediterranean latency coverage.
Telecommunications leads on scale; BFSI leads on momentum.
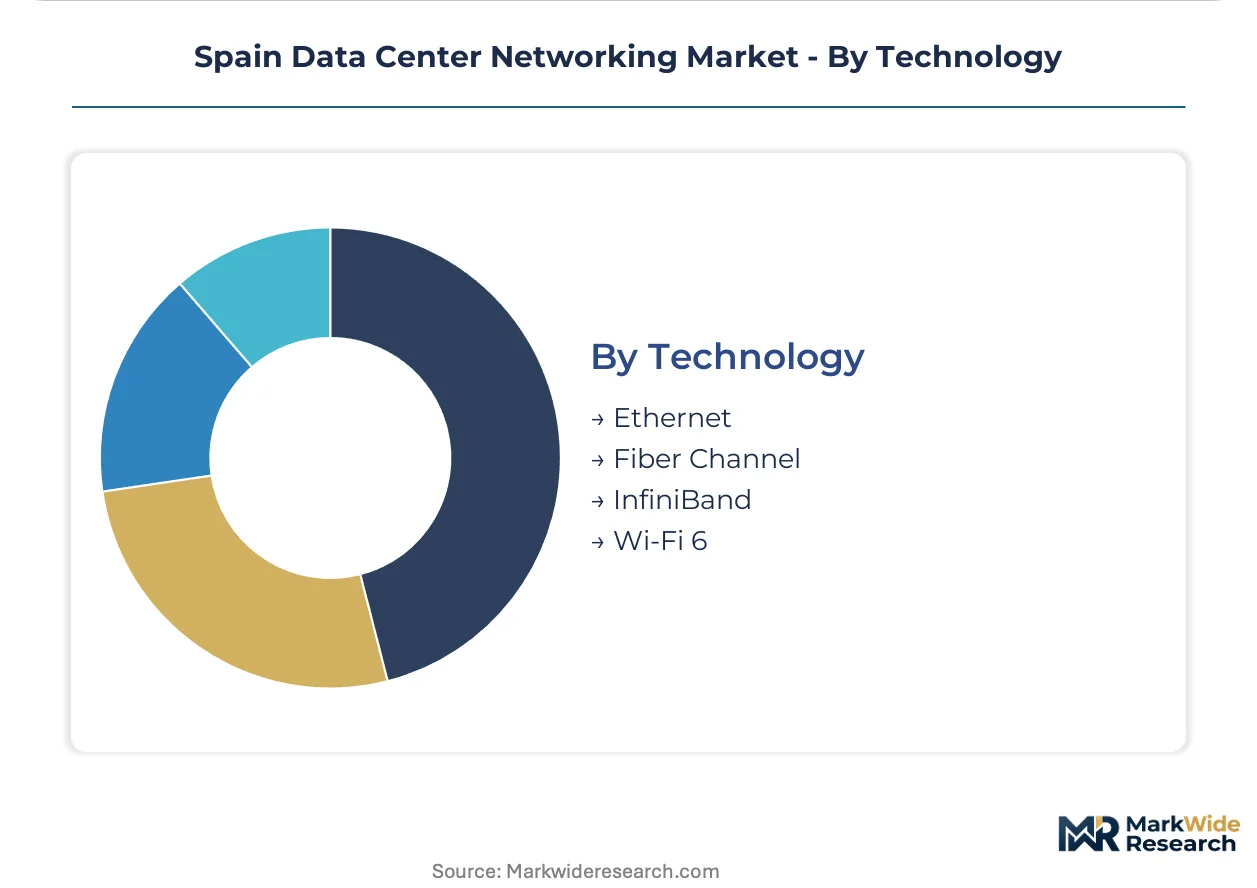
Technology:
Physical layer selection hinges on bandwidth requirements, power budgets, and interoperability with existing storage fabrics.
- Ethernet:Dominates general-purpose compute with 25 Gbps to 400 Gbps per port standardization across hyperscale leaf-spine designs. RoCEv2 implementations in Barcelona AI clusters challenge InfiniBand's historical grip on high-performance computing interconnects.
- InfiniBand:Retains socket share in dedicated AI training environments where NVIDIA GPU interconnects mandate native RDMA. Barcelona supercomputing facilities and financial risk modeling clusters deploy HDR and NDR InfiniBand for all-to-all GPU communication patterns.
- Fiber Channel:Legacy storage area networks persist in Madrid financial data centers with existing EMC and NetApp investments.
- Wi-Fi 6:Supports technician mobility and temporary staging areas without cabling overhead.
Ethernet leads on scale; InfiniBand leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Madrid metro corridor anchors Spain data center networking demand through hyperscale clustering near renewable interconnection points. Barcelona's submarine cable landing stations attract latency-sensitive financial and content delivery infrastructure. Regional procurement patterns diverge across autonomous communities based on energy availability, regulatory exposure, and submarine cable proximity.
Madrid
Hyperscale operators cluster facilities near wind and solar farms to secure favorable power purchase agreements while meeting carbon neutrality commitments. Spain's National Cybersecurity Strategy enforces NIS2 transposition measures that mandate encrypted east-west traffic inspection in financial and government facilities. The Madrid metro corridor hosts algorithmic trading co-location deployments where sub-500 nanosecond switching latency supports derivatives exchanges and quantitative hedge funds.
Catalonia
Barcelona's submarine cable diversity attracts latency-sensitive content delivery networks serving North Africa and Latin America. EU CSRD reporting mandates force operators to document Scope 3 emissions across network equipment lifecycles, extending procurement cycles. The Barcelona metropolitan area pilots 51.2 Tbps switches with co-packaged optics to cut thermal load per rack in high-density AI training clusters.
Andalusia
Secondary markets like Seville and Málaga offer undeveloped land and submarine cable diversity for emerging edge deployments. The region's lower land costs and renewable energy potential attract mid-market enterprises seeking metered colocation services. Andalusian facilities increasingly bundle switching, cross-connects, and DDoS protection into per-rack service contracts for pharmaceutical and legal services verticals.
Basque Country
Industrial automation and automotive manufacturing drive private cloud networking demand across Bilbao and San Sebastián. Regional operators maintain OpenStack or VMware-based fabrics for legacy application hosting in manufacturing environments. The Basque Country's advanced manufacturing base creates procurement pull for deterministic network performance in industrial IoT and predictive maintenance workloads.
Valencia
The port city's logistics and maritime trade infrastructure supports data center networking for supply chain analytics and customs processing. Valencia's emerging tech corridor attracts smaller colocation providers serving Mediterranean-facing enterprises. Regional facilities prioritize Wi-Fi 6E for out-of-band management and technician mobility in hybrid cloud deployments bridging on-premises estates with Azure and AWS zones.
Spain Data Center Networking Market Competitive Landscape
Merchant silicon partnerships dominate the current landscape as vendors race to deliver production volumes before 400 GbE refresh waves peak. The vendor base concentrates around three strategic tiers: merchant silicon-anchored hyperscale specialists, automated fabric management platforms, and legacy infrastructure incumbents with broad portfolio breadth. Competitive positioning hinges on spine-leaf architecture expertise, ultra-low-latency switching credentials, and unified management plane capabilities across multi-vendor environments.
Within the merchant silicon tier, Cisco Systems Inc. and Arista Networks Inc. exemplify divergent positioning strategies. Cisco leverages broad partnership ecosystems to anchor spine-leaf architectures across Iberian hyperscale facilities, while Arista occupies a position purpose-built for algorithmic trading co-location latency requirements. Juniper Networks Inc. sits within the automated fabric management segment, representing vendors that reduce provisioning cycles through software-defined approaches. These three companies collectively illustrate how competitive differentiation in Spain converges on silicon sourcing flexibility, latency determinism, and operational automation depth.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Juniper Networks Inc. |
| Arista Networks Inc. |
| Broadcom Inc. |
| Hewlett Packard Enterprise |
| Dell Technologies |
| VMware Inc. |
| NEC Corporation |
| Fujitsu Limited |
| Others |
Pricing and Supply Chain Analysis
Captive silicon sourcing from Taiwan-based foundries anchors both supply security and pricing leverage for Spanish data center networking vendors, compressing margin buffers when wafer costs fluctuate. This integration pattern concentrates procurement power among hyperscale operators while forcing mid-market buyers into longer contract cycles.
Pricing Analysis
Input-cost pass-through from merchant silicon ASICs and optical transceivers shapes contract structures across Madrid and Barcelona deployments. Three-tier pricing stratifies across premium ultra-low-latency switches, standard spine-leaf configurations, and economy-grade access hardware. Cost compression in the economy tier intensifies because copper backplane vendors cede socket share to silicon photonics alternatives. Hyperscale cloud providers exhibit lowest price sensitivity due to volume scale, while mid-market pharmaceutical and legal services verticals negotiate metered network-as-a-service contracts to limit capital exposure.
Supply Chain Analysis
EU CSRD domestic-content disclosure mandates are reshaping sourcing protocols for Spanish operators documenting Scope 3 emissions across equipment lifecycles. Manufacturing concentration centers on Taiwan for merchant silicon ASICs, China for optical transceiver assembly, and Malaysia for passive component fabrication. Dependencies on rare-earth-doped fiber amplifiers, high-speed DAC cables, and precision timing modules create single-source vulnerability when geopolitical restrictions disrupt cross-strait logistics. Distribution runs through Telefonica and regional carrier procurement hubs before reaching enterprise and colocation end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain data center networking functions as a geographic-arbitrage play where Madrid's renewable energy interconnection points offer power cost advantages against Frankfurt and Amsterdam alternatives, while Barcelona's submarine cable diversity reduces latency premiums for Latin American traffic.
For Market Incumbents: Hedge merchant silicon concentration risk by qualifying secondary ASIC sources from Broadcom and Marvell alongside dominant Taiwan suppliers. Anchor spine-leaf architecture dominance through certification investment in EU AI Act-compliant microsegmentation platforms. Defensive capacity positioning near Seville and Málaga secures land-bank advantages before Andalusian edge markets mature.
For New Entrants and Emerging Players: Cloud-native SaaS management planes offer the most penetrable entry vector for mid-market pharmaceutical and legal services verticals seeking operational flexibility over asset ownership. Target Andalusian secondary markets where incumbent presence remains thin and submarine cable diversity supports North African latency requirements. Lead with consumption-based pricing models that displace traditional capex-heavy procurement cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where automated fabric management software creates differentiation against hardware-centric incumbents. Long-term viability favors vendors with unified orchestration planes spanning VMware, Azure, and AWS environments. Acquisition target archetypes include RoCEv2-specialist NIC vendors serving Barcelona AI training clusters. Monitor NIS2 enforcement timelines as inflection indicators for next-generation firewall-integrated switch procurement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Diversification | Qualifying secondary ASIC sources reduces Taiwan supply concentration exposure for Madrid hyperscale builds. |
| Co-Packaged Optics Deployment | Piloting 51.2 Tbps switches with integrated photonics cuts thermal load in Barcelona AI clusters. |
| EU AI Act Certification Investment | Auditable microsegmentation platforms capture procurement pull from Madrid healthcare and public sector verticals. |
| Andalusian Edge Expansion | Seville and Málaga facilities exploit submarine cable diversity for latency-sensitive North African content delivery. |
| Network-as-a-Service Transition | Metered pricing models displace capex ownership among Barcelona pharmaceutical and legal services mid-market clients. |
Research Methodology
Direct dialogue with data center infrastructure directors, hyperscale network architects, colocation procurement leads, and optical transceiver manufacturing engineers grounded qualitative findings in operational realities. Secondary validation drew from SEC filings of merchant silicon vendors, EU CSRD disclosure databases, submarine cable landing station operator reports, and Spanish national cybersecurity regulator guidance documents. Bottom-up installation tracking across Madrid and Barcelona facilities triangulated against top-down hyperscaler capex disclosure analysis.
Analytical lenses combined bottom-up port shipment aggregation with top-down infrastructure spend modeling across the projection horizon. Segmentation dimensions included product type, deployment model, end-user vertical, and physical layer technology. CAGRs were derived from elasticity-adjusted demand curves incorporating NIS2 compliance timelines and AI training cluster buildout trajectories. Forecast inputs weighted renewable energy interconnection availability and merchant silicon supply lead times.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics co-packaging would alter the outlook if thermal engineering constraints persist beyond current pilot phases. Forecasts reflect documented assumptions around EU regulatory enforcement intensity and hyperscaler facility expansion cadence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Data Center Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Nosql Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Data Center Servers Market