
 Middle East Data Center Server Market | 2026-2036
Middle East Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Center Server Market Insights
The shift from single-source procurement to multi-vendor sourcing is hardening across Middle East data center operators. Hewlett Packard Enterprise leverages its direct sales presence in Riyadh and Dubai to anchor enterprise rack deployments. Dell Technologies competes through channel density, sustaining local distributor partnerships that reduce lead times for blade server configurations. Huawei Technologies navigates geopolitical complexity, positioning its ARM-based lines where Western vendor access faces friction.
A data center server is a high-availability compute node engineered with redundant power supplies, ECC memory, and thermal designs supporting continuous operation at ambient temperatures up to 45°C, purpose-built to host virtualized workloads and cloud-native applications for enterprise and telecom operators. Rack servers dominate volume shipments across colocation facilities in the Gulf Cooperation Council states, reflecting standardized density requirements. Edge Computing represents the fastest-expanding technology segment, as telecom operators deploy micro data centers closer to 5G base stations to minimize latency for autonomous systems and industrial IoT.
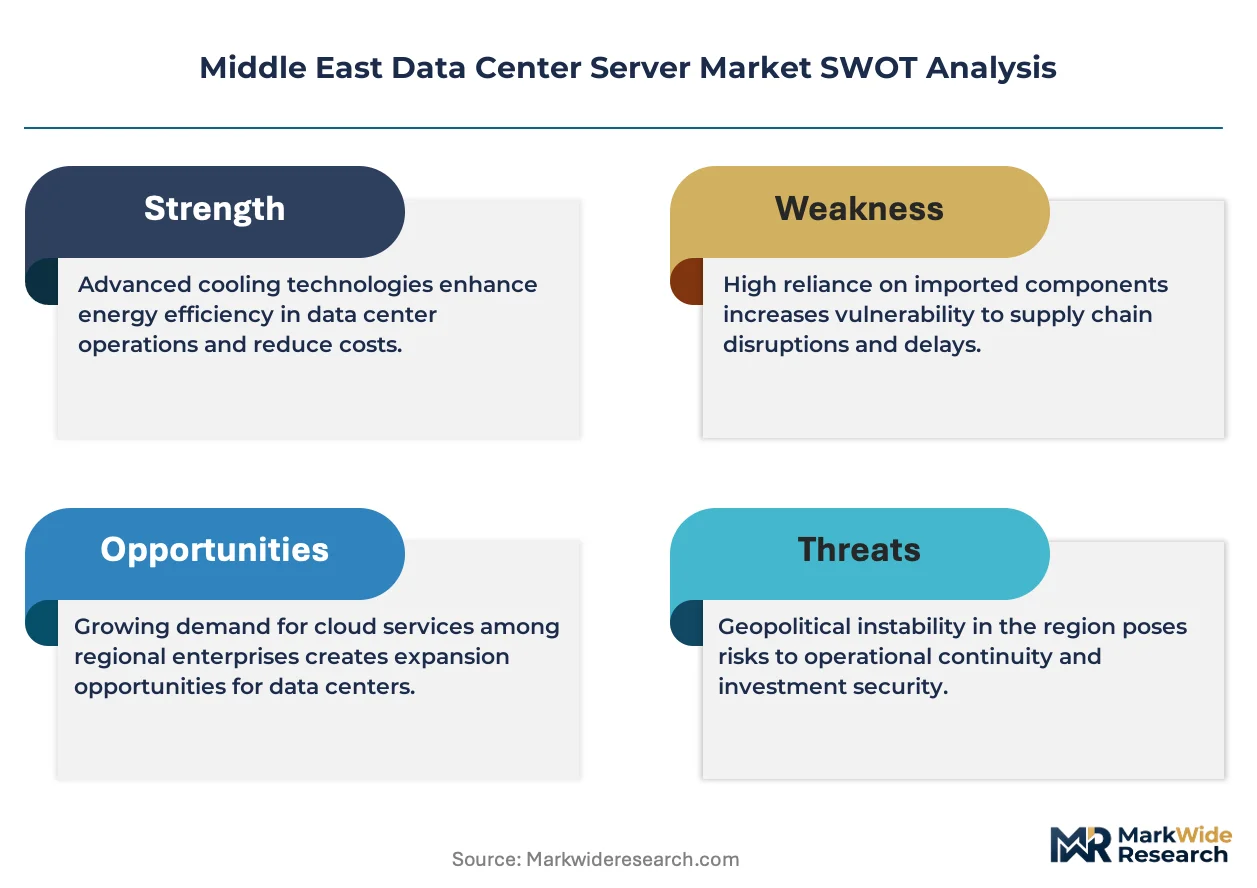
Saudi Arabia's Communications, Space and Technology Commission enforces energy-efficiency standards that filter server procurement specifications for new facilities. The UAE's Telecommunications and Digital Government Regulatory Authority shapes data localization rules that mandate on-premises or hybrid deployment models for government and healthcare end users. Stakeholders must monitor how evolving national cybersecurity frameworks redefine certification requirements for foreign server vendors seeking public sector access.
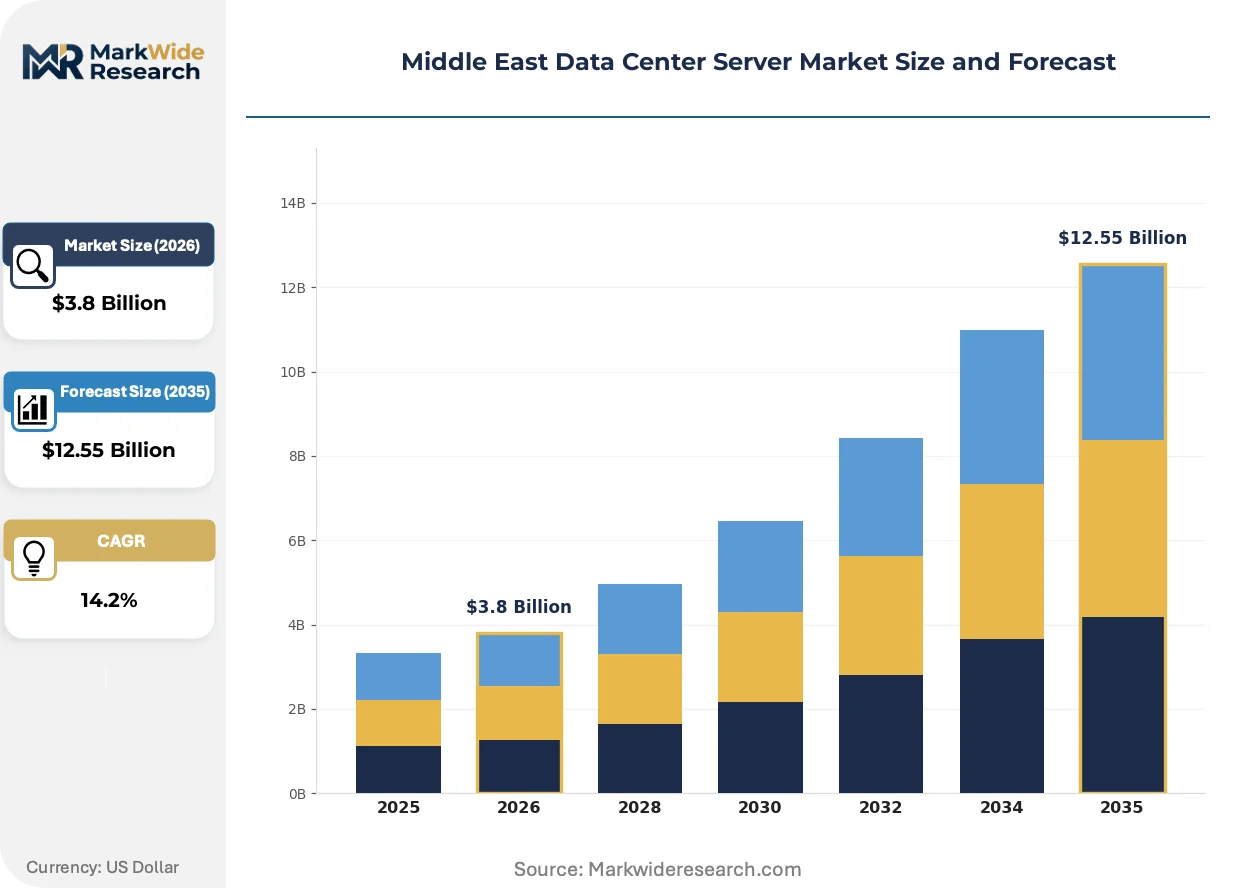
Market Dynamics
Sovereign wealth capital deployment and dual carbon mandates are compressing procurement timelines while forcing energy-efficiency specifications into every server RFP across Gulf Cooperation Council states.
Growth Catalysts
- Saudi Arabia's dual carbon goals:Energy-efficiency mandates filter server procurement specifications for new hyperscale facilities, accelerating refresh cycles toward liquid-cooled architectures.
- Cloud computing adoption among BFSI institutions:Banking and financial services operators are collapsing traditional procurement phases, shifting from capital expenditure models to managed infrastructure contracts.
- Edge Computing deployment:Telecom operators position micro data centers adjacent to 5G base stations, generating incremental server demand for latency-sensitive autonomous and industrial IoT workloads.
Market Restraints
- Geopolitical vendor access friction:Western technology export controls constrain supply options for certain compute architectures, forcing operators toward costlier multi-source strategies.
- Liquid cooling infrastructure capex:Transitioning from air-cooled to immersion or direct-to-chip cooling demands substantial facility retrofit investment, extending payback periods for existing assets.
- Localization content requirements:Domestic manufacturing mandates in key Gulf states limit immediate access to globally optimized supply chains, inflating landed costs for imported server components.
Strategic Opportunities
- Kuwait and Qatar capacity gaps:These markets currently lack hyperscale colocation density, creating first-mover advantage for operators building sovereign cloud nodes ahead of government digitalization waves.
- AI training cluster demand:National AI strategies across the Gulf are mandating domestic GPU-heavy infrastructure, opening specialized high-density deployment contracts.
- Channel partnership restructuring:Direct distributor relationships are displacing traditional tiered resale, allowing server vendors to capture margin previously allocated to intermediary layers.
Industry Challenges
- Certification timeline compression:Evolving national cybersecurity frameworks require foreign vendors to obtain new public sector access credentials, delaying revenue recognition on government contracts.
- Legacy virtualization stack integration:Enterprise data centers running mature VMware or Hyper-V environments face substantial migration complexity when adopting cloud-native server configurations.
- Thermal engineering talent scarcity:Liquid cooling and 45°C ambient design expertise remains concentrated among a limited pool of specialists, inflating compensation costs for facility engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Center Server Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Server Type: Rack Servers, Blade Servers, Tower Servers, Micro Servers Technology: Virtualization, Cloud Computing, Automation, Edge Computing End User: Telecommunications, BFSI, Government, Healthcare Deployment Model: On-Premises, Colocation, Hybrid, Cloud |
| Companies Covered | Cisco Systems, Fujitsu Limited, Hewlett Packard Enterprise, Inspur Group, Supermicro, Dell Technologies, Lenovo Group, Huawei Technologies, IBM Corporation, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Center Server Market Trends and Innovations
Compute architecture convergence and regulatory energy mandates are forcing simultaneous transitions in cooling technology, procurement contracting, and workload placement across Middle East facilities.
ARM-based server processors are unifying performance-per-watt optimization with software ecosystem maturation. Hyperscale operators in Dubai and Riyadh are piloting these architectures for cloud-native workloads previously reserved for x86. This unification is compressing the historical instruction-set architecture duopoly, creating procurement leverage for operators negotiating multi-vendor supply agreements.
Saudi Arabia's Communications, Space and Technology Commission enforces server energy-efficiency standards that filter procurement specifications for new facilities. These mandates disqualify legacy air-cooled designs from state-backed infrastructure tenders. Colocation providers respond by pre-certifying liquid-cooled rack configurations ahead of formal RFP release, shortening sales cycles for compliant vendors.
Multi-year managed infrastructure contracts are displacing traditional capital purchase arrangements among enterprise buyers. Banking and telecom operators in the UAE now prioritize operational expenditure models that bundle hardware, software, and facility management. This behavioral shift concentrates purchasing authority among a smaller cohort of systems integrators with sovereign wealth backing, marginalizing independent value-added resellers without direct vendor authorization.
Middle East Data Center Server Market Segmentation
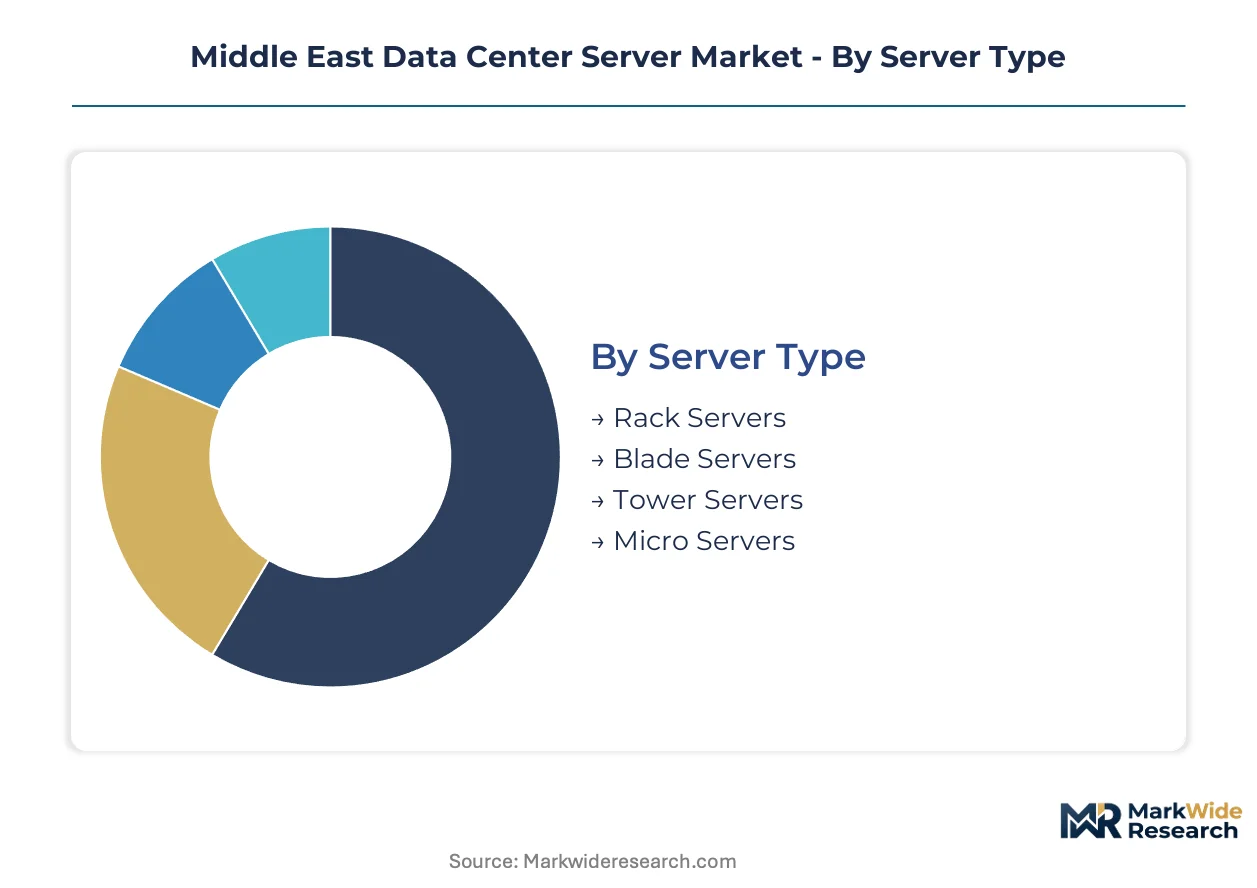
Server procurement patterns across Gulf Cooperation Council states diverge sharply by deployment architecture and workload placement. Understanding these segment boundaries clarifies why energy-efficiency mandates from Saudi Arabia's Communications, Space and Technology Commission and data localization rules from the UAE's Telecommunications and Digital Government Regulatory Authority affect some categories more severely than others.
Server Type:
Integration depth varies substantially—rack and blade configurations dominate facility-scale deployments, while tower and micro variants serve distributed or embedded compute scenarios.
- Rack Servers:Standardized 19-inch form factors with redundant hot-swappable power supplies and 45°C ambient thermal tolerance. Demand concentrates in Dubai and Abu Dhabi colocation corridors where sovereign wealth-backed hyperscale projects require uniform density for cloud-native workload consolidation.
- Blade Servers:High-density chassis architectures sharing power and cooling infrastructure across multiple compute nodes. Banking and financial services institutions in Riyadh favor these for trading floor virtualization, collapsing procurement cycles toward managed infrastructure contracts.
- Tower Servers:Standalone vertical enclosures suited to branch office and remote facility deployments. Small and medium enterprises across Kuwait and Qatar deploy these where rack infrastructure proves economically prohibitive.
- Micro Servers:Compact single-socket designs optimized for lightweight web serving and edge caching. Telecom operators position these at 5G base station adjacencies to minimize latency for autonomous systems.
Rack servers lead volumes today; micro servers are gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive infrastructure layers from operational expenditure models that bundle hardware with management services.
- Virtualization:Hypervisor-based resource abstraction enabling consolidated workload placement on shared physical hosts. Enterprise data centers across Saudi Arabia running mature VMware stacks face substantial migration complexity when adopting cloud-native configurations.
- Cloud Computing:Distributed resource pools delivered via subscription or consumption-based contracting. BFSI institutions throughout the UAE are shifting procurement authority toward systems integrators with sovereign wealth backing, marginalizing traditional value-added resellers.
- Automation:Infrastructure-as-code and orchestration platforms reducing manual provisioning overhead. Facility operators in Dammam and Jeddah deploy these to compress server deployment timelines amid compressed procurement cycles.
- Edge Computing:Micro data center architectures positioned proximal to data generation sources. This segment climbs the fastest as telecom operators build latency-sensitive infrastructure for industrial IoT and autonomous vehicle workloads.
Virtualization retains installed base dominance; edge computing shows the steepest expansion trajectory.
End User:
Application criticality determines redundancy specifications and thermal design requirements across buyer categories.
- Telecommunications:Carrier-grade availability requirements driving N+1 power and cooling architectures. Etisalat and stc Group deployments across the UAE and Saudi Arabia anchor demand for liquid-cooled rack configurations.
- BFSI:Regulatory compliance and low-latency transaction processing priorities. Banks in Dubai International Financial Centre prioritize operational expenditure models that transfer capital risk to managed infrastructure providers.
- Government:Domestic data localization mandates and cybersecurity certification requirements. Saudi government cloud initiatives filter server procurement through Communications, Space and Technology Commission energy-efficiency standards.
- Healthcare:Patient data protection and hybrid deployment requirements. UAE Ministry of Health and Prevention facilities mandate on-premises or hybrid models under Telecommunications and Digital Government Regulatory Authority localization rules.
Telecommunications leads current procurement volumes; government segment expansion accelerates with national AI strategy infrastructure mandates.
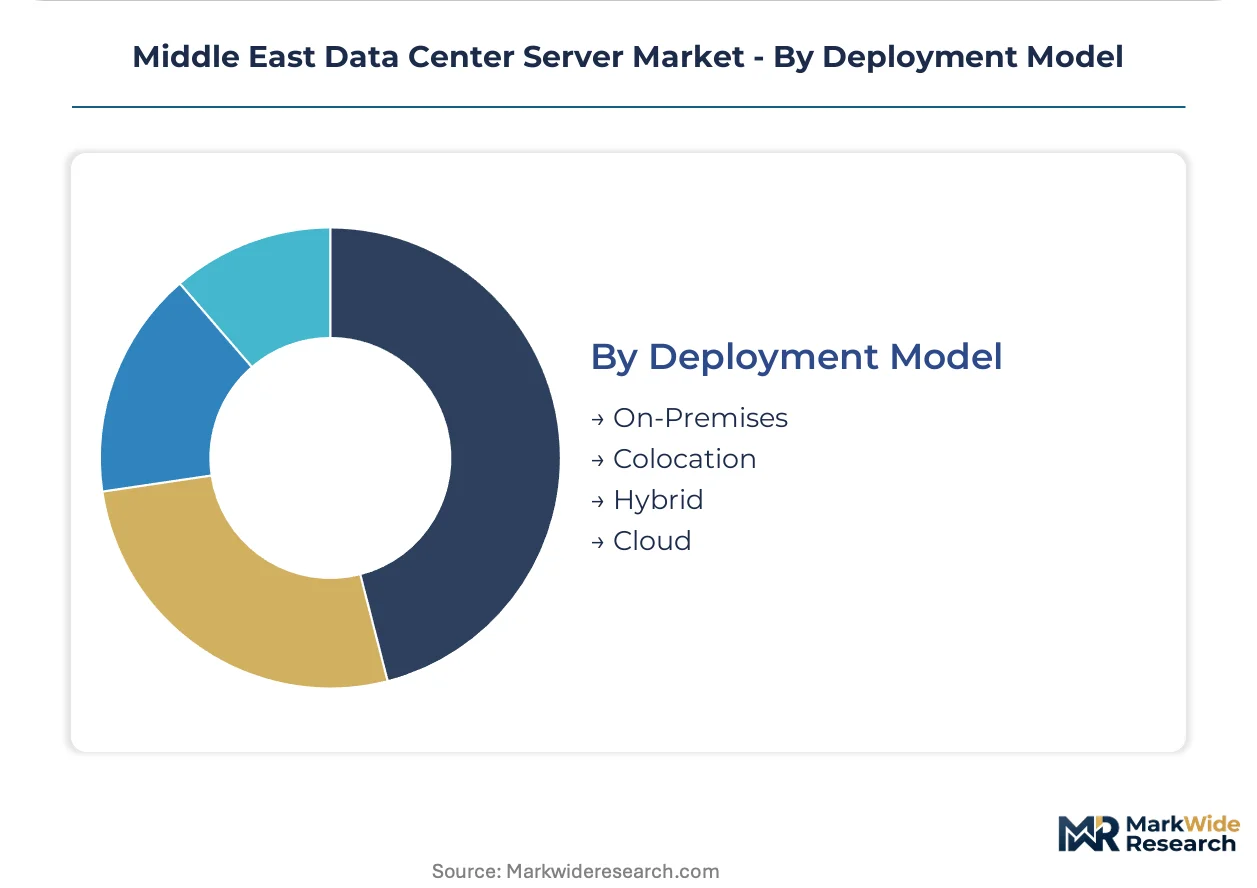
Deployment Model:
Customer type and internal capability determine whether buyers retain infrastructure control or outsource facility management entirely.
- On-Premises:Buyer-operated facilities with direct capital responsibility for power, cooling, and physical security. Large Saudi industrial conglomerates maintain these for legacy application hosting where data sovereignty concerns predominate.
- Colocation:Third-party facility space with buyer-owned server equipment and shared infrastructure services. Dubai and Abu Dhabi corridors concentrate capacity from Equinix, Khazna, and Saudi Telecom Company infrastructure subsidiaries.
- Hybrid:Workload-distributed architectures spanning owned and leased infrastructure. Healthcare providers across the Gulf Cooperation Council favor these to balance patient data localization with burst capacity flexibility.
- Cloud:Fully outsourced compute resources with no physical infrastructure ownership. BFSI procurement teams increasingly mandate these arrangements to convert capital expenditure to operational expenditure.
Colocation captures the largest revenue pool today; hybrid architectures are expanding most quickly as regulatory complexity drives workload placement diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai and Abu Dhabi anchor Middle East data center server demand through sovereign wealth-backed hyperscale corridors. Procurement concentrates in Gulf Cooperation Council states where dual carbon mandates and data localization rules reshape facility specifications.
Saudi Arabia
Riyadh and the Eastern Province drive hyperscale expansion through stc Group and Saudi Telecom Company infrastructure deployments. The Communications, Space and Technology Commission enforces energy-efficiency standards that filter server procurement for new facilities. NEOM Northwest attracts liquid-cooled architecture pilots as the kingdom pursues domestic AI training clusters.
United Arab Emirates
Dubai International Financial Centre banks and Abu Dhabi government cloud initiatives accelerate managed infrastructure contracting. The Telecommunications and Digital Government Regulatory Authority mandates on-premises or hybrid deployment models for healthcare and government end users. Khazna and Equinix expand colocation capacity across the Dubai-Abu Dhabi corridor.
Qatar
Doha-based telecom operators and Qatar Investment Authority-backed digitalization projects generate incremental server demand. Domestic manufacturing mandates limit immediate access to globally optimized supply chains. The Lusail smart city development positions micro data centers for latency-sensitive municipal workloads.
Kuwait
Kuwait City financial institutions and Ministry of Communications cloud migration programs create first-mover opportunities for sovereign cloud node construction. The country's national telecommunications regulator shapes data localization requirements for government procurement. Colocation density remains underdeveloped relative to Saudi Arabia and UAE benchmarks.
Israel
Tel Aviv metropolitan area cybersecurity firms and defense technology contractors demand specialized high-availability compute infrastructure. The country's national cyber directorate influences certification requirements for foreign server vendors seeking public sector access. Haifa and Beer Sheva tech clusters concentrate edge computing deployments for autonomous systems research.
Middle East Data Center Server Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ARM-based and liquid-cooled specializations. The vendor base stratifies across three tiers: global systems integrators with direct sovereign wealth relationships, regional distributors optimizing channel density for blade configurations, and niche specialists navigating geopolitical access friction. Competitive moves concentrate on channel partnership restructuring and pre-certification of compliant rack configurations ahead of formal RFP release.
Within the global systems tier, Hewlett Packard Enterprise and Dell Technologies exemplify divergent go-to-market architectures. HPE leverages direct sales presence in Riyadh and Dubai to anchor enterprise rack deployments, while Dell competes through sustained local distributor partnerships that compress lead times. Huawei Technologies occupies a distinct position where Western vendor access faces friction, positioning ARM-based lines for operators seeking procurement alternatives. These three anchors illustrate how vendor selection increasingly follows geopolitical alignment rather than pure technical specification.
| Leading Market Players |
|---|
| Cisco Systems |
| Fujitsu Limited |
| Hewlett Packard Enterprise |
| Inspur Group |
| Supermicro |
| Dell Technologies |
| Lenovo Group |
| Huawei Technologies |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Liquid cooling infrastructure capex flows from Taiwanese ODMs through Dubai-based systems integrators to Saudi hyperscale operators, compressing margins at each tier while energy-efficiency mandates from the Communications, Space and Technology Commission disqualify lower-cost air-cooled alternatives from state-backed tenders.
Pricing Analysis
Input-cost pass-through from semiconductor memory and advanced thermal components shapes rack server quotations across Gulf Cooperation Council procurement cycles. Three-tier pricing structure across liquid-cooled premium, air-cooled standard, and refurbished economy levels reflects certification grade and after-sales service bundling. Pricing pressure stems from localization content requirements inflating landed costs for imported components. Managed infrastructure providers exhibit lowest price sensitivity; small and medium enterprises in Kuwait and Qatar face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from stc Group and Khazna, while tiered distributor networks serve enterprise blade server configurations across Riyadh and Dubai. Manufacturing concentrates in Taiwan, China, and South Korea for processor and memory components; chassis assembly localizes partially in Saudi Arabia under domestic content mandates. The supply chain draws from specialized copper tubing for liquid cooling, high-grade aluminum for heat dissipation, and redundant power supply units. Single-source vulnerability around advanced GPU accelerators creates procurement risk. Distribution runs through authorized systems integrators with sovereign wealth relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in liquid-cooled premium tiers where Saudi dual carbon mandates eliminate lower-efficiency competition, while operational expenditure contracting shifts revenue recognition toward recurring service streams.
For Market Incumbents: Cement direct sovereign wealth relationships through pre-certification of Communications, Space and Technology Commission-compliant rack configurations ahead of formal RFP release. Deepen backward integration into liquid cooling component supply to offset ODM margin capture. Defend against Huawei Technologies' ARM-based positioning in procurement scenarios where Western vendor access faces friction. For New Entrants and Emerging Players: Launch via specialized edge computing micro server distribution partnerships with Etisalat and stc Group adjacent to 5G base station deployments. Target Kuwait and Qatar capacity gaps where hyperscale colocation density remains underdeveloped relative to Saudi Arabia and UAE benchmarks. Prioritize operational expenditure contracting models that align with BFSI procurement behavioral shifts. For Investors and Strategic Acquirers: Consolidation pressure builds where thermal engineering talent scarcity inflates facility engineering compensation costs beyond independent operator sustainability. Long-term viability favors vertically integrated platforms spanning server hardware, liquid cooling infrastructure, and managed services. Acquisition target archetype: regional systems integrators with direct vendor authorization and sovereign wealth backing. Monitor stc Group and Khazna capex disclosure patterns as inflection indicators for hyperscale demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Pre-Certification | Accelerates sales cycles under Saudi Communications, Space and Technology Commission energy-efficiency mandates. |
| Direct Sovereign Wealth Partnership | Captures margin from traditional tiered resale channels in UAE and Saudi hyperscale corridors. |
| Edge Computing Micro Data Center Deployment | Positions compute proximal to Etisalat and stc Group 5G infrastructure for latency-sensitive workloads. |
| Operational Expenditure Contracting Model | Aligns with Dubai International Financial Centre bank procurement shifts from capital expenditure. |
| Domestic Manufacturing Localization | Satisfies Saudi and Qatar content requirements while reducing tariff exposure on imported components. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility engineering directors, IT procurement officers at BFSI institutions, channel distribution managers, and hyperscale colocation operators with secondary validation against SEC filings from server vendors, hyperscaler capex disclosures, customs and trade data for component imports, and regulatory filings from the Communications, Space and Technology Commission and Telecommunications and Digital Government Regulatory Authority. Bottom-up server shipment estimates and top-down infrastructure investment flows were triangulated to anchor market sizing.
Segment-weighting across server type, deployment model, technology layer, and end-user vertical structured the analytical framework throughout the forecast period. CAGRs were derived from trend extrapolation against infrastructure pipeline visibility and procurement cycle compression patterns. Key inputs included sovereign wealth capital deployment schedules, dual carbon mandate implementation timelines, and national AI strategy infrastructure commitments across Gulf Cooperation Council states.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical vendor access friction scenarios and commodity memory price volatility. Periodic stress-testing of base assumptions is recommended, particularly around evolving cybersecurity certification requirements that could delay revenue recognition on government contracts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Nosql Market