
 MPLS-Based Core Network Market | 2026-2036
MPLS-Based Core Network Market Size, Share, and Industry Trends Forecast 2026-2036
MPLS-Based Core Network Market Foresight
Aftermarket service revenue from legacy MPLS provisioning is narrowing as carriers shift toward software-defined overlays and automated orchestration. Cisco Systems Inc. leverages its installed base of ASR and NCS platforms to sustain recurring support contracts across tier-1 operators. Nokia anchors its position through deep relationships with European PTTs requiring circuit-to-packet migration services.
An MPLS-based core network employs label-switched paths to forward packets across provider backbones without per-hop IP routing table lookups, typically operating at 10 Gbps to 400 Gbps interface speeds with 50 ms restoration targets for carrier-grade reliability. These networks serve commercial purposes by guaranteeing quality-of-service tiers for latency-sensitive enterprise traffic and inter-data-center replication flows. Managed services and cloud connectivity segments attract disproportionate investment as enterprises outsource core operations rather than maintain in-house engineering benches. Data center interconnection applications show the strongest trajectory among application categories, driven by hyperscale leasing models that require deterministic cross-facility links.
The Federal Communications Commission shapes US market access through interconnection and net-neutrality frameworks that influence how MPLS services get priced and bundled. The European Telecommunications Standards Institute and national regulators such as Germany's Federal Network Agency enforce resilience and data-localization standards that preserve MPLS relevance for critical infrastructure operators. Stakeholders must weigh segment routing migration timelines against the sunk cost of existing label distribution protocol deployments when planning capital allocation.
Market Dynamics
Segment routing with MPLS (SR-MPLS) is compressing legacy LDP/RSVP-TE deployments as carriers pursue simplified traffic engineering and reduced operational state. The Federal Communications Commission's net-neutrality frameworks and Germany's Federal Network Agency resilience mandates create divergent procurement pressures across Atlantic markets.
Growth Catalysts
- IPv6-Only Infrastructure Mandates:Government and enterprise networks in Germany and France are eliminating IPv4 dependencies, requiring MPLS cores to transport dual-stack and IPv6-native traffic without performance degradation.
- Financial Services Latency Requirements:High-frequency trading and real-time payment clearing in Frankfurt and Chicago demand deterministic sub-10ms cross-facility connectivity that only circuit-emulated MPLS paths reliably deliver.
- Hyperscale Data Center Leasing:Cloud operators building multi-megawatt campuses in Northern Virginia and the Netherlands require dedicated wavelength and MPLS overlay services for synchronous replication between availability zones.
Market Restraints
- Silicon Supply Concentration:Merchant silicon for 400G forwarding engines concentrates among three foundry sources in Taiwan, creating lead-time vulnerability for router refresh cycles.
- Optical Transport Cost Compression:Coherent pluggable optics at 400G ZR/ZR+ price points are collapsing the economic case for separate MPLS-TP layers in metro aggregation.
- REACH Substance Restrictions:European electronics manufacturing faces phased restrictions on halogenated flame retardants in router chassis and power supplies, complicating supply chain qualification.
Strategic Opportunities
- Private 5G Campus Integration:Industrial manufacturing sites in Bavaria and the US Midwest are deploying localized 5G cores that require MPLS backhaul for enterprise SLA enforcement and roaming handoff.
- Cloud-Native Network Function Hosting:Kubernetes-orchestrated virtualized PE routers enable edge computing providers to offer MPLS VPN termination as-a-service without dedicated hardware.
- Critical Infrastructure Cybersecurity Mandates:The EU NIS2 Directive and US Executive Order 14028 impose segmentation requirements that favor MPLS-based traffic isolation over internet VPN alternatives for operational technology networks.
Industry Challenges
- Multiprotocol Label Distribution Protocol Skill Scarcity:Engineering benches lack depth in LDP, RSVP-TE, and BGP-LU troubleshooting as university curricula pivot toward cloud-native networking.
- Inter-Autonomous System Interconnection Complexity:Carriers must maintain bilateral peering agreements and consistent community-tag semantics across MPLS VPN option-B and option-C implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MPLS-Based Core Network Market |
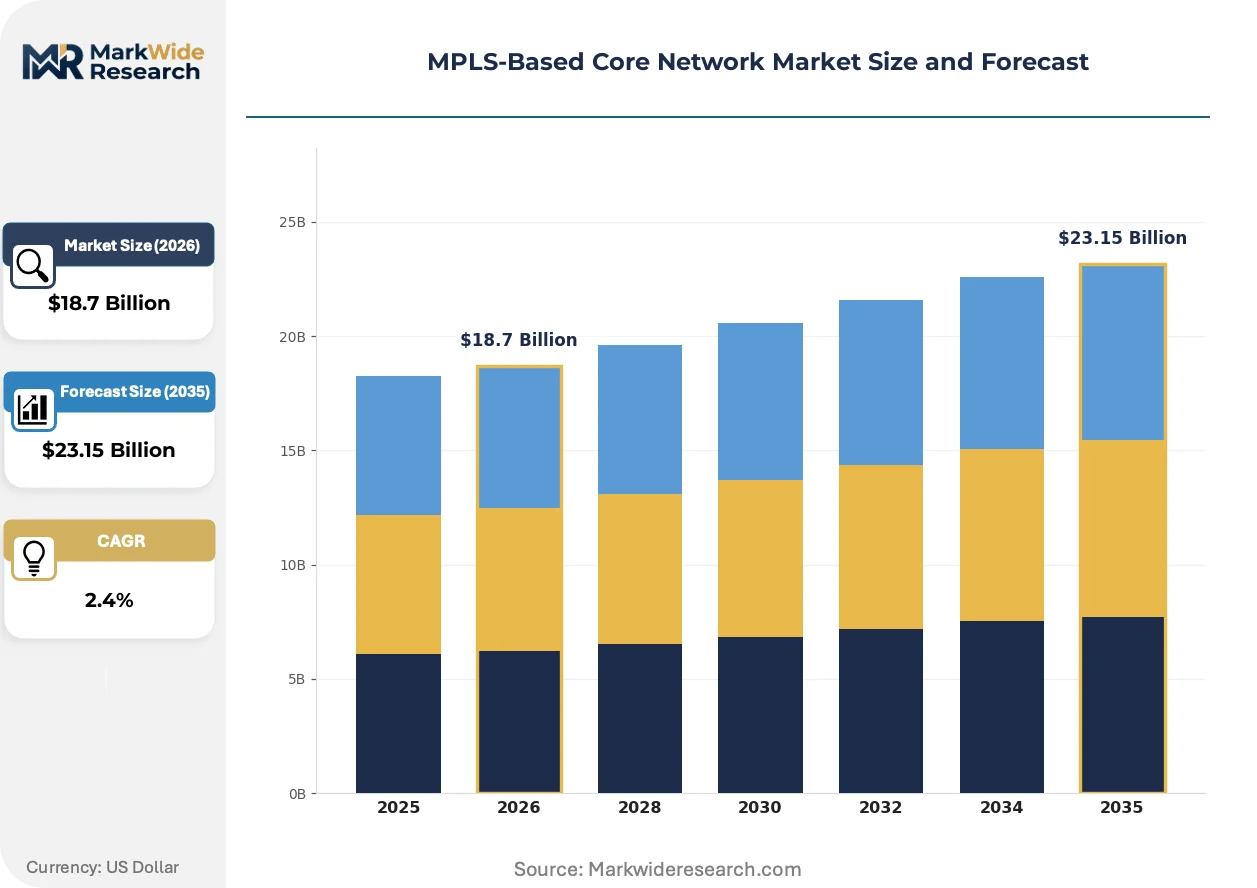
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $23.15 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Network Security, Data Transport, Cloud Connectivity Application: Enterprise Networking, VoIP, Video Conferencing, Data Center Interconnection Deployment Model: On-Premises, Cloud-Based, Hybrid, Dedicated Network End User: Telecommunications Providers, Financial Institutions, Educational Institutions, Government Agencies |
| Companies Covered | Cisco Systems Inc., AT&T Inc., Orange S.A., BT Group plc, Nokia, Verizon Communications Inc., Deutsche Telekom AG, Juniper Networks, NTT Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MPLS-Based Core Network Market Shifts & Advancements
Automation frameworks and intent-based networking are displacing CLI-driven provisioning in carrier core operations. Three developments are compressing traditional deployment timelines and reshaping vendor competitive position.
SR-MPLS with centralized path computation is digitizing traffic engineering workflows previously executed through distributed protocol state. Tier-1 operators in Germany and the United States are deploying controller-based explicit path instantiation for 80% of new VPN deployments. This compression eliminates weeks of manual LSP design and reduces operational touchpoints by collapsing RSVP-TE state maintenance into single-source-of-truth databases.
The EU AI Act and accompanying infrastructure security guidelines are mandating explainable routing decisions for critical network paths serving healthcare and energy sectors. Carriers must now document traffic engineering logic for regulatory audit trails. French and Dutch operators are responding by deploying path computation element architectures with immutable policy logging, prioritizing this capability in RFP evaluations over raw forwarding performance.
Enterprise procurement teams are consolidating vendor relationships and demanding API-driven service orchestration rather than ticket-based provisioning portals. Financial institutions in Frankfurt and London are leading this behavioral shift, replacing multi-vendor MPLS meshes with single-carrier managed SD-WAN underlays. The operational consequence is reduced direct router sales to enterprise premises and expanded managed service attach rates for core network providers.
MPLS-Based Core Network Market Segmentation
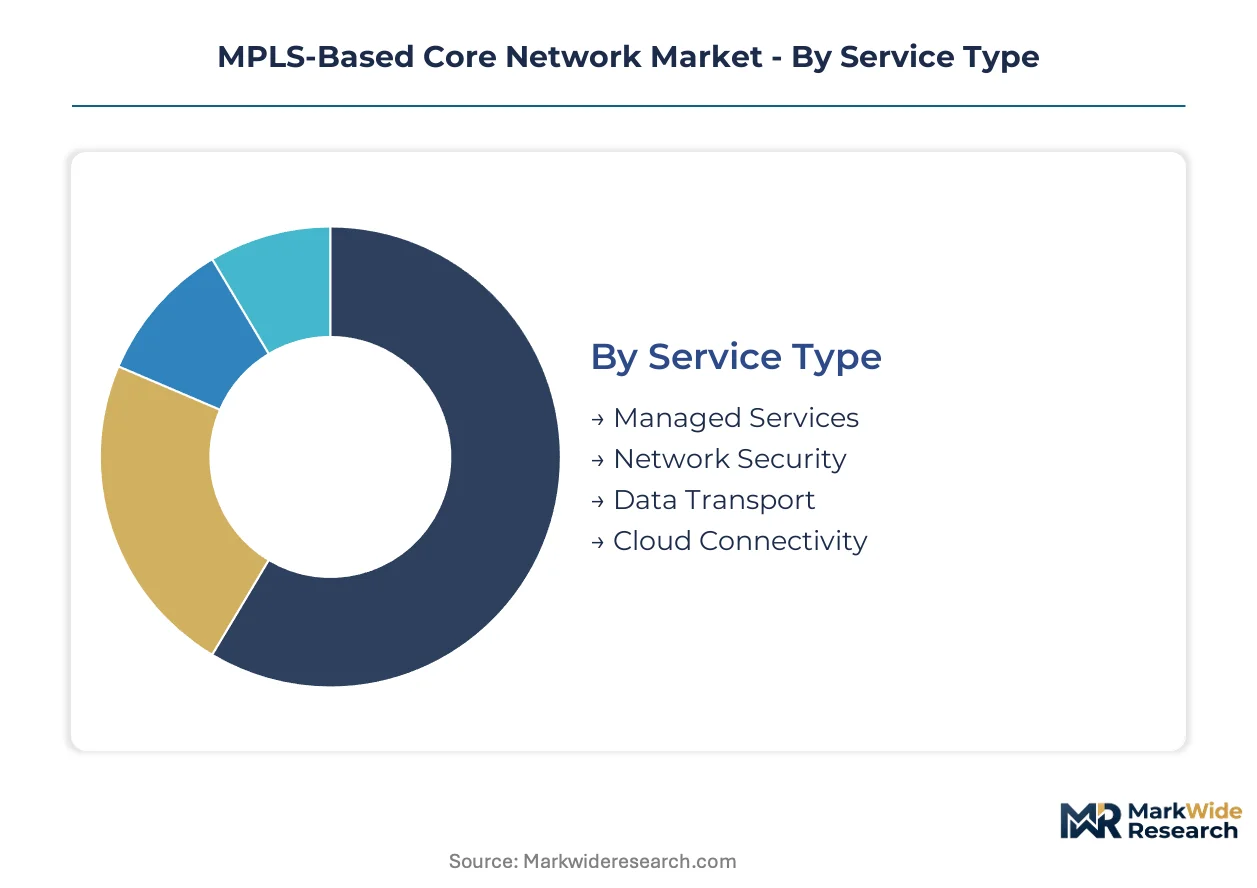
Segmentation in MPLS-based core networks reveals divergent procurement patterns across service delivery models and end-user risk profiles. Financial institutions prioritize deterministic latency guarantees while cloud connectivity segments attract capital from hyperscale leasing arrangements. Understanding these divides enables vendors to align forwarding platform roadmaps with specific customer engineering requirements.
Service Type:
Use-case spectrum spans fully outsourced operations to security-hardened transport layers with divergent margin structures.
- Managed Services:Carriers assume full operational responsibility for label-switched path provisioning, monitoring, and restoration across customer premises equipment. Deutsche Telekom and Verizon Business command premium pricing in Frankfurt and Northern Virginia by embedding 50ms protection switching into SLA frameworks for high-frequency trading venues.
- Network Security:MPLS-TP layers incorporate MACsec encryption and control-plane hardening for critical infrastructure operators. German energy utilities and US healthcare networks under HIPAA and NIS2 mandates drive procurement of segmented traffic isolation over internet VPN alternatives.
- Data Transport:Raw wavelength and packet transport without value-added overlay services.
- Cloud Connectivity:Direct cloud on-ramp integrations with AWS, Azure, and Google Cloud.
Established volume favors Managed Services; emerging adoption favors Cloud Connectivity.
Application:
Application layering determines interface speed requirements ranging from 1 Gbps branch aggregation to 400 Gbps data center trunking.
- Data Center Interconnection:Synchronous replication between availability zones demands deterministic sub-10ms latency that only circuit-emulated MPLS paths reliably deliver. Hyperscale operators in the Netherlands and Northern Virginia are expanding multi-megawatt campus footprints requiring dedicated wavelength and MPLS overlay services.
- Enterprise Networking:Multi-site VPN meshing for distributed manufacturing and retail operations. Bavarian automotive suppliers and US Midwest industrial consortia maintain private MPLS cores to enforce quality-of-service tiers across plant floor and headquarters traffic.
- VoIP:Voice traffic prioritization with strict jitter and packet loss constraints.
- Video Conferencing:Bandwidth-reserved multicast and unicast delivery for real-time collaboration platforms.
Capital deployment concentrates in Data Center Interconnection; refresh cycles sustain Enterprise Networking.
Deployment Model:
Deployment architecture selection reflects customer cloud-native maturity and regulatory data-localization obligations.
- Dedicated Network:Physically isolated infrastructure serving single-tenant requirements with full control-plane autonomy. German Federal Network Agency resilience mandates and EU NIS2 cybersecurity directives preserve demand among critical infrastructure operators requiring immutable audit trails for path computation decisions.
- Hybrid:Split traffic engineering across on-premises MPLS cores and cloud-based virtualized PE functions. Kubernetes-orchestrated network function virtualization enables edge computing providers to offer MPLS VPN termination as-a-service without dedicated hardware investments.
- On-Premises:Customer-operated router fleets with direct CLI and SNMP management access.
- Cloud-Based:Fully virtualized forwarding and control planes hosted in hyperscale facilities.
Regulatory compliance sustains Dedicated Network procurement; operational flexibility drives Hybrid adoption.
End User:
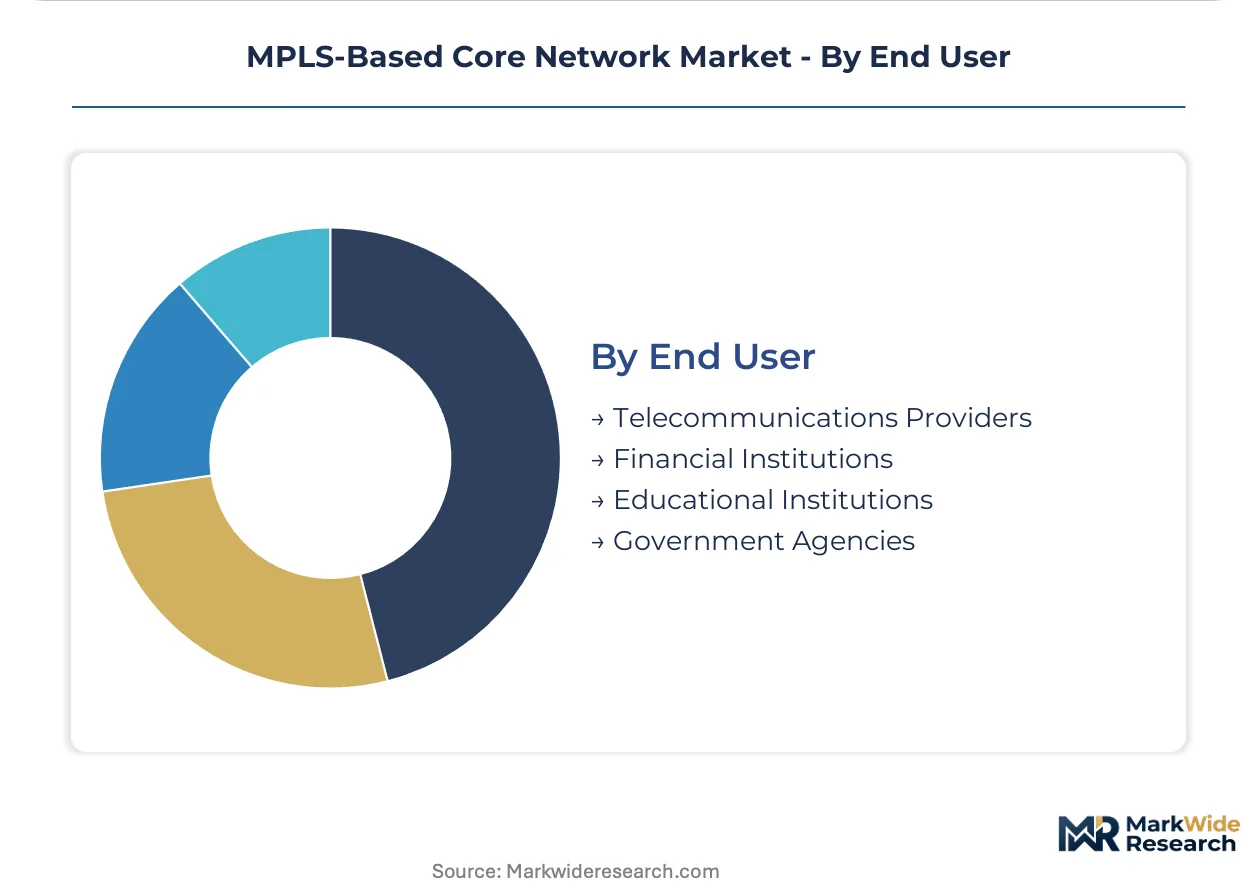
End-user category shapes procurement scale, technical specification depth, and vendor relationship intensity.
- Financial Institutions:Real-time payment clearing and high-frequency trading infrastructure in Frankfurt and Chicago demand sub-10ms cross-facility connectivity with deterministic latency variance bounds. Circuit-emulated MPLS paths remain the only transport technology meeting these jitter constraints for inter-exchange links.
- Telecommunications Providers:Wholesale backbone capacity and retail VPN service delivery. Tier-1 operators in Germany and the United States are deploying SR-MPLS with centralized path computation for 80% of new VPN deployments to collapse RSVP-TE state maintenance into single-source-of-truth databases.
- Government Agencies:Classified and unclassified network segmentation under executive cybersecurity mandates.
- Educational Institutions:Research network federation and campus backbone consolidation.
Technical specification intensity peaks with Financial Institutions; volume concentration rests with Telecommunications Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States exhibit the lowest price elasticity, accepting premium MPLS tariffs for deterministic latency guarantees, while procurement teams in India and Brazil drive harder bargains on per-megabit pricing as they weigh SD-WAN alternatives.
United States
Financial exchanges in Chicago and hyperscale campuses in Northern Virginia sustain demand for sub-10ms circuit-emulated paths. The FCC's net-neutrality frameworks influence how carriers bundle MPLS with broadband access. Verizon and AT&T compete for enterprise VPN contracts across Manhattan and Dallas-Fort Worth financial districts.
Germany
Industrial consortia in Bavaria and automotive suppliers in Baden-Württemberg operate private MPLS cores for plant-floor traffic segmentation. The Federal Network Agency enforces resilience standards that preserve dedicated network procurement for critical infrastructure. Deutsche Telekom anchors wholesale capacity provisioning across Frankfurt's banking corridor.
United Kingdom
London-based trading venues and insurance underwriters require deterministic cross-connectivity to continental European exchanges. Post-Brexit data-localization pressures complicate trans-channel MPLS VPN architectures. BT Group manages legacy backbone modernization across the City and Canary Wharf clusters.
Japan
Tokyo-Osaka financial corridors and manufacturing supply chains in the Chubu region depend on low-jitter transport for real-time settlement systems. METI guidelines on operational technology cybersecurity favor MPLS isolation over internet alternatives. NTT Communications dominates enterprise VPN provisioning across the Kanto megalopolis.
France
Energy utilities under EU NIS2 mandates and healthcare networks in Île-de-France procure segmented MPLS-TP layers for compliance. The CNIL and ANSM enforce audit-trail requirements for critical infrastructure routing decisions. Orange S.A. leverages incumbent relationships with state-owned enterprises in Paris and Lyon.
MPLS-Based Core Network Market Competitive Landscape
Capability concentration sits with integrated systems vendors possessing decades of routing protocol expertise; scale advantage sits with tier-1 carriers operating transcontinental fiber footprints. The market structures around three archetypes: incumbent telecom operators with captive backbone assets, specialist networking vendors selling forwarding platforms, and managed service providers aggregating multi-carrier capacity. Consolidation pressures favor carriers acquiring niche SD-WAN orchestrators, while equipment vendors pursue strategic partnerships with cloud hyperscalers to embed MPLS termination in direct cloud on-ramps.
Among North American networking specialists, Cisco Systems Inc. and Juniper Networks occupy positions as archetypal platform vendors, their installed bases of carrier-grade routers creating switching-cost barriers for incumbent operators. European carrier groups including Deutsche Telekom AG and Orange S.A. exemplify the vertically integrated tier, combining proprietary backbone ownership with enterprise-facing managed service portfolios. Japanese infrastructure provider NTT Communications represents the Asia-Pacific anchor, its subsea cable investments and domestic fiber density supporting regional MPLS VPN reach.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| AT&T Inc. |
| Orange S.A. |
| BT Group plc |
| Nokia |
| Verizon Communications Inc. |
| Deutsche Telekom AG |
| Juniper Networks |
| NTT Communications |
| Others |
Supply & Pricing Matrix
Undercapacity in merchant silicon foundries across Taiwan is compressing lead times for 400G forwarding engines and amplifying pricing power among router vendors serving tier-1 carriers. This utilization squeeze propagates through contract negotiations, with equipment suppliers extracting longer-term commitments and carriers accepting inflation-linked escalators to secure allocation priority.
Pricing Analysis
Long-term offtake agreements dominate procurement between tier-1 operators and integrated systems vendors, though spot-market transactions persist for capacity expansion modules and spares. Price differentiation hinges on deterministic latency guarantees and MACsec encryption certification tiers, with financial institutions in Frankfurt and Chicago accepting substantial premiums for sub-10ms SLAs. Cost compression in metro aggregation is intensifying because coherent pluggable optics at 400G ZR/ZR+ price points are collapsing the economic case for separate MPLS-TP layers. Cloud connectivity segments exhibit the lowest price sensitivity, while enterprise networking teams in India and Brazil drive harder bargains as they weigh SD-WAN alternatives.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for router chassis and power supply assemblies. Merchant silicon concentrates in Taiwan, South Korea, and the United States, while precision optical components and specialized ASIC packaging draw from Japanese and German suppliers. Raw material dependencies include gallium arsenide substrates, halogen-free flame retardants, and rare-earth magnet alloys for cooling systems. Single-source vulnerability concentrates in three foundry sources for 400G forwarding engines. Distribution runs through carrier-direct procurement channels and systems integrators serving enterprise premises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as enterprise procurement teams consolidate vendor relationships and demand API-driven orchestration, creating niches for specialized orchestration providers and cloud-native network function hosts.
For Market Incumbents: Build switching-cost moats through deep integration of SR-MPLS controllers with existing ASR and NCS platform installed bases. Defensive moves include embedding immutable policy logging for EU AI Act compliance and securing multi-year managed service attach contracts with financial institutions. The threat of Kubernetes-orchestrated virtualized PE routers from edge computing entrants demands preemptive certification investment in cloud-native network function hosting capabilities.
For New Entrants and Emerging Players: Private 5G campus integration in Bavarian manufacturing sites and the US Midwest offers underpenetrated white-space for MPLS backhaul solutions. The most penetrable segment is industrial operational technology networks under EU NIS2 and US Executive Order 14028 cybersecurity mandates. A go-to-market angle anchored in segmented traffic isolation for critical infrastructure operators bypasses incumbent carrier relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native network function virtualization as Kubernetes orchestration displaces dedicated hardware investments. Long-term viability favors managed service providers with API-driven provisioning capabilities over pure-play equipment vendors. Acquisition targets should exhibit orchestration software expertise and existing hyperscaler cloud on-ramp partnerships. The signal to watch is enterprise procurement team consolidation toward single-carrier managed SD-WAN underlays.
| Strategic Initiative | Industry Significance |
|---|---|
| SR-MPLS Controller Deployment | Deutsche Telekom and Verizon collapse RSVP-TE state maintenance into centralized databases for 80% of new VPNs. |
| Cloud-Native Network Function Hosting | Kubernetes-orchestrated virtualized PE routers enable edge providers to offer MPLS termination without hardware investments. |
| Private 5G Campus Integration | Bavarian industrial sites deploy localized 5G cores requiring MPLS backhaul for enterprise SLA enforcement. |
| EU AI Act Compliance Certification | French operators deploy path computation architectures with immutable policy logging for healthcare and energy audit trails. |
| Hyperscaler Cloud On-Ramp Partnership | Equipment vendors embed MPLS termination in direct AWS, Azure, and Google Cloud connectivity services. |
Research Methodology
Initial hypotheses were tested against primary input from carrier network architects, enterprise IT procurement officers, and router platform engineers and refined through secondary validation. Stakeholder consultations included tier-1 operator planning teams, financial institution infrastructure leads, and hyperscale data center interconnection specialists. Secondary sources encompassed FCC net-neutrality filings, Germany's Federal Network Agency resilience mandates, ETSI standardization documents, and carrier capex disclosure statements. Bottom-up triangulation across service type and application segments converged with top-down macroeconomic scaling.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include service delivery model, end-user risk profile, deployment architecture, and geographic regulatory cluster. CAGRs were derived from installed base refresh cycles, IPv6 migration timelines, and SR-MPLS adoption curves. Industry-specific inputs incorporated merchant silicon lead times, coherent optics pricing trajectories, and cybersecurity mandate implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native networking entrants or accelerated SRv6 substitution would shift outcomes. Forecasts reflect assumptions regarding carrier migration timelines, foundry capacity allocation, and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Internet Protocol Version 6 (IPv6) Market