
 Europe Augmented Reality (AR) and Mixed Reality (MR) Market | 2026-2036
Europe Augmented Reality (AR) and Mixed Reality (MR) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Augmented Reality (AR) and Mixed Reality (MR) Market Foresight
REACH is expanding compliance obligations for hardware manufacturers importing optical components and rare-earth sensors into the European Economic Area. Tsukat leverages its Warsaw-based development studio to anchor mixed-reality training modules for Polish logistics clients. Nomtek competes across Nordic markets with markerless tracking solutions tailored to maritime maintenance protocols. Lucid Reality Labs specializes in healthcare visualization, sustaining R&D partnerships with university hospitals in the Netherlands and Belgium.
Augmented Reality and Mixed Reality denote systems that overlay or embed digital information—spatially anchored graphics, haptic feedback streams, and real-time sensor fusion—onto physical environments through waveguide optics and simultaneous localization and mapping (SLAM) algorithms. These technologies serve industrial and commercial purposes by reducing task error rates, compressing training timelines, and enabling remote expert collaboration without physical co-location. Head-Mounted Displays dominate hardware value pools due to precision optics costs and enterprise certification barriers, while AR Software captures recurring revenue through subscription-based remote-assistance platforms. Healthcare and Training applications are expanding fastest as hospitals and vocational institutes replace cadaver-based and on-site instruction with immersive simulations.
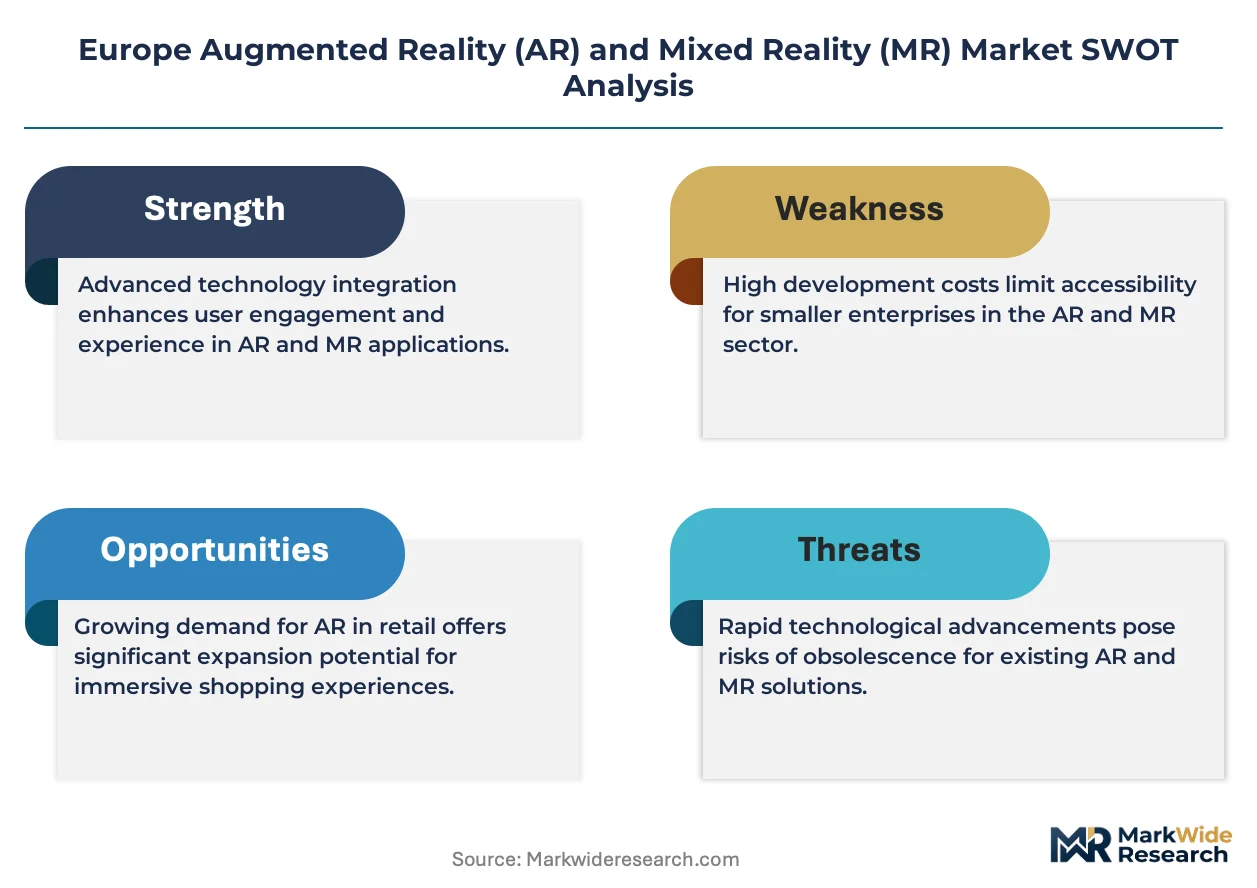
EMA device-software interface guidelines intersect with GDPR biometric data rules to shape how European vendors collect and process gaze-tracking and facial-geometry data. The EU AI Act's risk-classification framework forces MR platform developers to document algorithmic transparency for high-stakes deployment in surgical and aviation maintenance settings. Stakeholders must monitor how CE marking requirements under the MDR evolve to encompass optical see-through displays as Class IIa medical devices.
Market Dynamics
The EU AI Act's risk-classification framework is compressing algorithmic transparency timelines for surgical and aviation maintenance deployments, forcing MR platform developers to restructure documentation workflows before CE marking gates.
Growth Catalysts
- REACH compliance expansion:Optical component manufacturers face expanded substance registration obligations for rare-earth sensors entering the European Economic Area, creating captive demand for compliant sourcing networks.
- Healthcare training digitization:German and French hospital systems are replacing cadaver-based instruction with AR-guided surgical simulations, compressing resident onboarding timelines.
- Industrial maintenance protocols:Bosch and Siemens affiliates in Germany's manufacturing corridor pilot MR-guided remote expert collaboration, reducing field technician dispatch requirements.
Market Restraints
- Waveguide optics cost concentration:Precision optical component fabrication remains concentrated among specialized foundries, creating input cost volatility for Head-Mounted Display manufacturers.
- GDPR biometric friction:Gaze-tracking and facial-geometry data collection faces strict processing constraints under EU privacy rules, limiting real-time personalization features.
- CE marking timeline extension:MDR reclassification of optical see-through displays as Class IIa medical devices is lengthening certification cycles for healthcare-bound hardware.
Strategic Opportunities
- Polish logistics corridor:Warsaw-based development studios anchor mixed-reality training modules for warehouse automation clients, with underpenetrated last-mile operators representing expansion targets.
- Nordic maritime protocols:Markerless tracking solutions tailored to offshore maintenance are displacing marker-dependent systems in Norwegian and Danish shipping fleets.
- EMA-GDPR convergence:Device-software interface guidelines intersecting with biometric data rules create first-mover advantages for vendors with pre-integrated compliance architectures.
Industry Challenges
- SLAM algorithm talent scarcity:Simultaneous localization and mapping expertise concentrates among robotics and autonomous vehicle sectors, creating recruitment competition for spatial computing vendors.
- Legacy system integration friction:Enterprise clients in industrial manufacturing require custom middleware to connect MR platforms with existing SCADA and ERP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Augmented Reality (AR) and Mixed Reality (MR) Market |
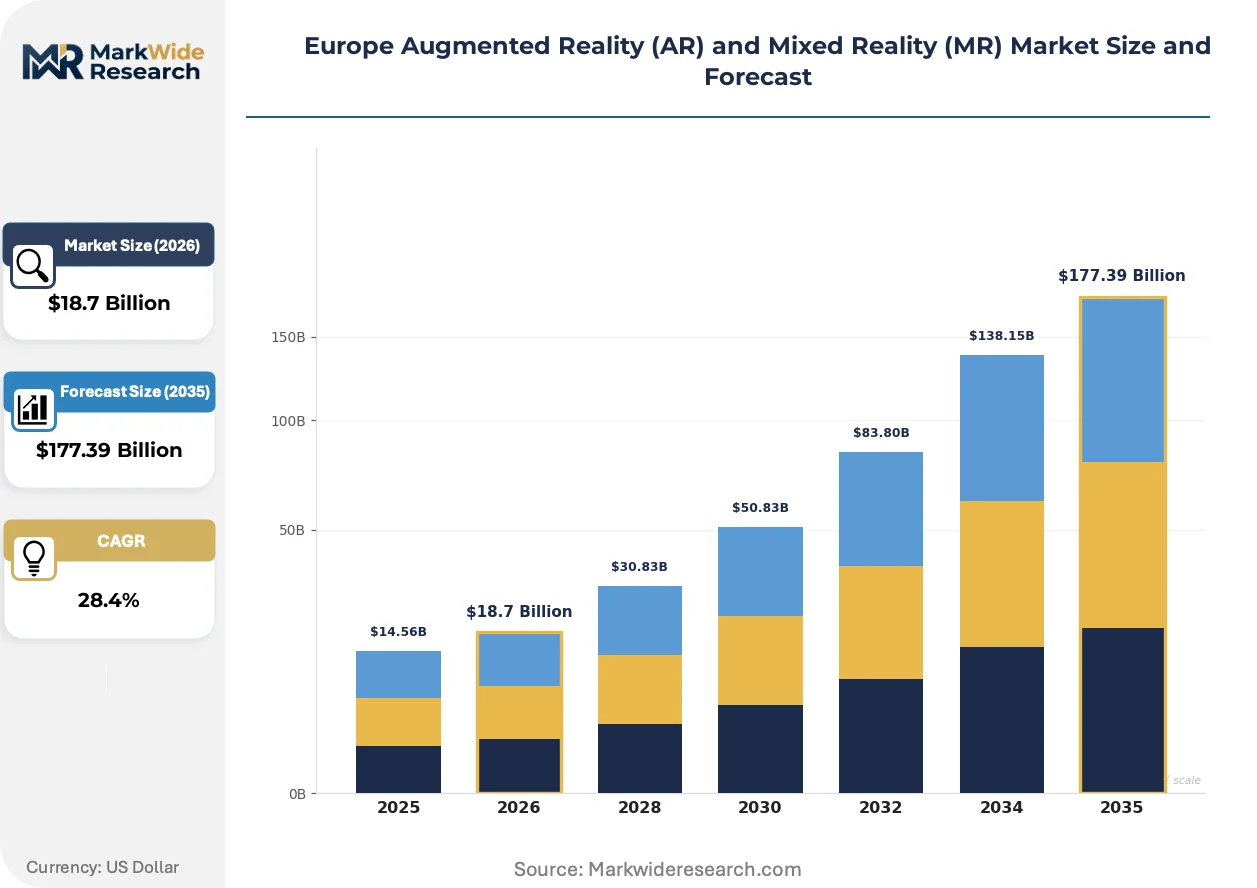
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Head-Mounted Displays, AR Software, MR Platforms End User: Retail, Healthcare, Education, Gaming Technology: Marker-Based, Markerless, Projection-Based, Superimposition Application: Training, Maintenance, Remote Assistance, Visualization |
| Companies Covered | Tsukat, nomtek, Lucid Reality Labs, Giant Lazer, FFFACE.ME, YORD, HQSoftware, Lens That, Delta Reality, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Augmented Reality (AR) and Mixed Reality (MR) Market Shifts & Advancements
Waveguide optics miniaturization and cloud-native spatial computing architectures are redistributing value from hardware stacks toward software-defined experience layers across European enterprise deployments.
Edge-based SLAM processing is decentralizing spatial mapping workloads from centralized servers to on-device chipsets. German automotive suppliers deploy these architectures for real-time quality inspection on assembly lines. The shift compresses latency for millimeter-precision overlay alignment while reducing bandwidth dependencies in factory floor environments.
The EU AI Act's documentation mandates for high-risk AI systems are forcing surgical MR developers to maintain algorithmic audit trails. EMA device-software interface guidelines now require traceability matrices linking training data to clinical decision outputs. Dutch and Belgian university hospitals are piloting standardized transparency frameworks ahead of formal enforcement.
Subscription-based remote assistance platforms are displacing perpetual-license AR software sales in industrial maintenance. German machine-tool operators now procure expert guidance as metered services rather than capital expenditures. The shift concentrates vendor revenue in recurring streams while transferring hardware refresh cycles to platform providers.
Europe Augmented Reality (AR) and Mixed Reality (MR) Market Segmentation
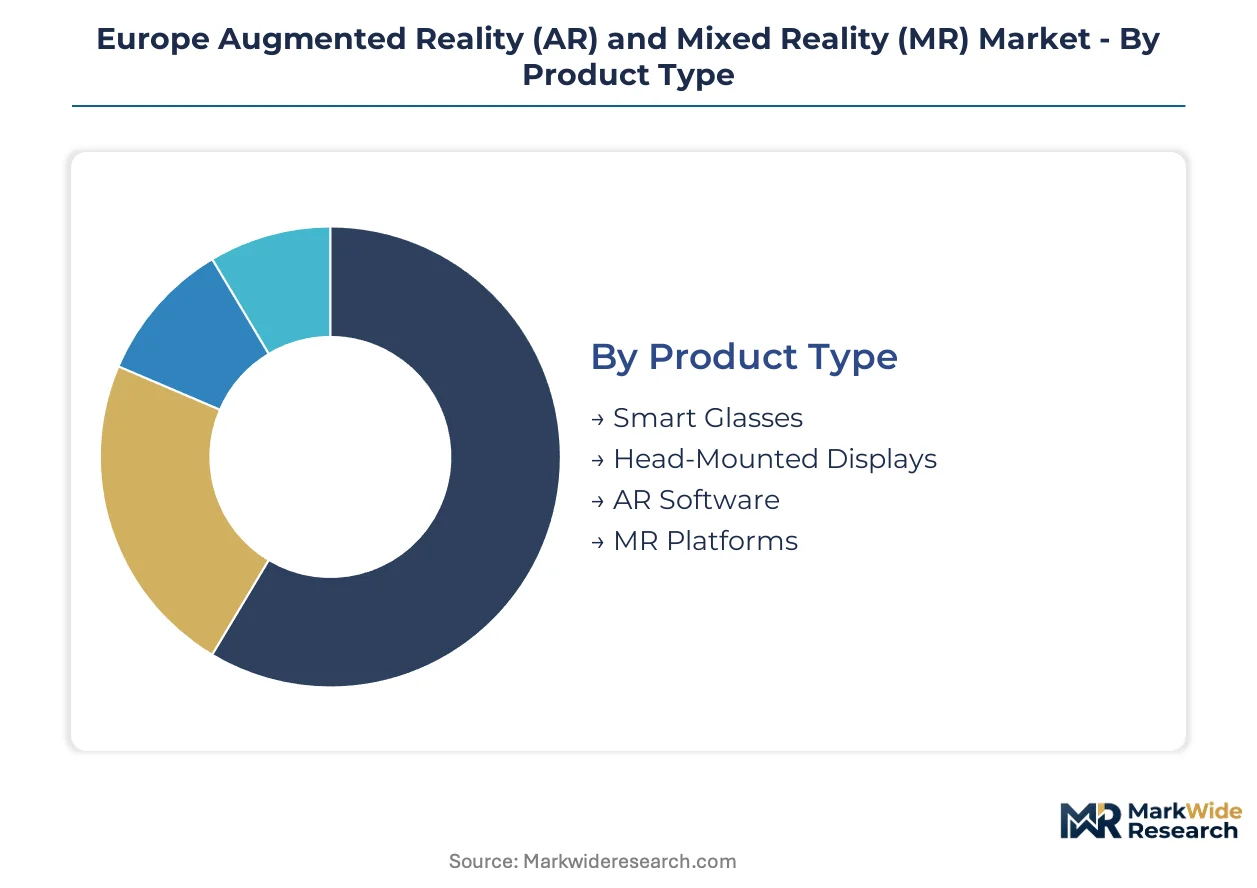
Segmentation in the Europe AR and MR market reveals how hardware cost structures, regulatory compliance burdens, and end-use performance requirements create divergent value pools. Suppliers configure portfolios differently across these dimensions to capture enterprise budgets versus consumer experimentation.
Product Type:
Supply concentration in precision optics foundries and waveguide fabrication facilities determines margin distribution across hardware categories.
- Head-Mounted Displays:Waveguide optics and micro-display assemblies dominate bill-of-materials costs. German automotive suppliers and French surgical training centers drive enterprise procurement volumes despite CE marking delays under MDR reclassification.
- Smart Glasses:Lightweight monocular designs sacrifice field-of-view for all-day wearability. Polish logistics operators and Nordic maritime fleets prioritize form factor over immersion for warehouse picking and deck maintenance workflows.
- AR Software:Subscription-based remote assistance platforms generate recurring revenue streams. Vendors bundle SLAM licensing with cloud hosting to lock in industrial maintenance contracts.
- MR Platforms:Integrated hardware-software stacks targeting high-fidelity spatial computing. EMA-GDPR convergence on biometric data processing raises compliance barriers for surgical and aviation training deployments.
Today's leader: Head-Mounted Displays. Tomorrow's challenger: AR Software.
End User:
Application maturity and procurement budget scale separate segments with proven ROI documentation from experimental deployments.
- Healthcare:German and French hospital systems replace cadaver-based instruction with AR-guided surgical simulations. EMA device-software interface guidelines and GDPR biometric constraints shape vendor qualification requirements.
- Training:Vocational institutes across the Netherlands and Belgium adopt immersive simulations for technical skill transfer. Compressed onboarding timelines justify premium hardware investments.
- Retail:Virtual try-on and spatial merchandising pilots concentrate in luxury flagships. Limited scale prevents dedicated hardware procurement at volume.
- Gaming:Consumer entertainment remains peripheral to European vendor strategies. Studio development focuses on enterprise productivity applications.
Healthcare commands current procurement volumes; Training applications are climbing the fastest as vocational education budgets reallocate.
Technology:
Algorithmic capability differentiation and environmental robustness requirements segment technical approaches by deployment context.
- Markerless:SLAM-based spatial anchoring eliminates environmental preparation. Norwegian and Danish shipping fleets deploy these systems for offshore maintenance where marker placement proves impractical.
- Marker-Based:Visual fiducial tracking delivers sub-millimeter precision at lower computational cost. German automotive assembly lines retain these systems for quality inspection stations with controlled lighting.
- Superimposition:Real-time occlusion handling and depth-consistent rendering. Surgical navigation applications in Dutch university hospitals demand this fidelity tier.
- Projection-Based:Spatial light modulation projects graphics directly onto physical surfaces. Limited adoption outside specialized industrial workstations due to ambient light sensitivity.
Markerless systems hold installed base advantages; Superimposition is gaining share fastest in high-accuracy medical deployments.
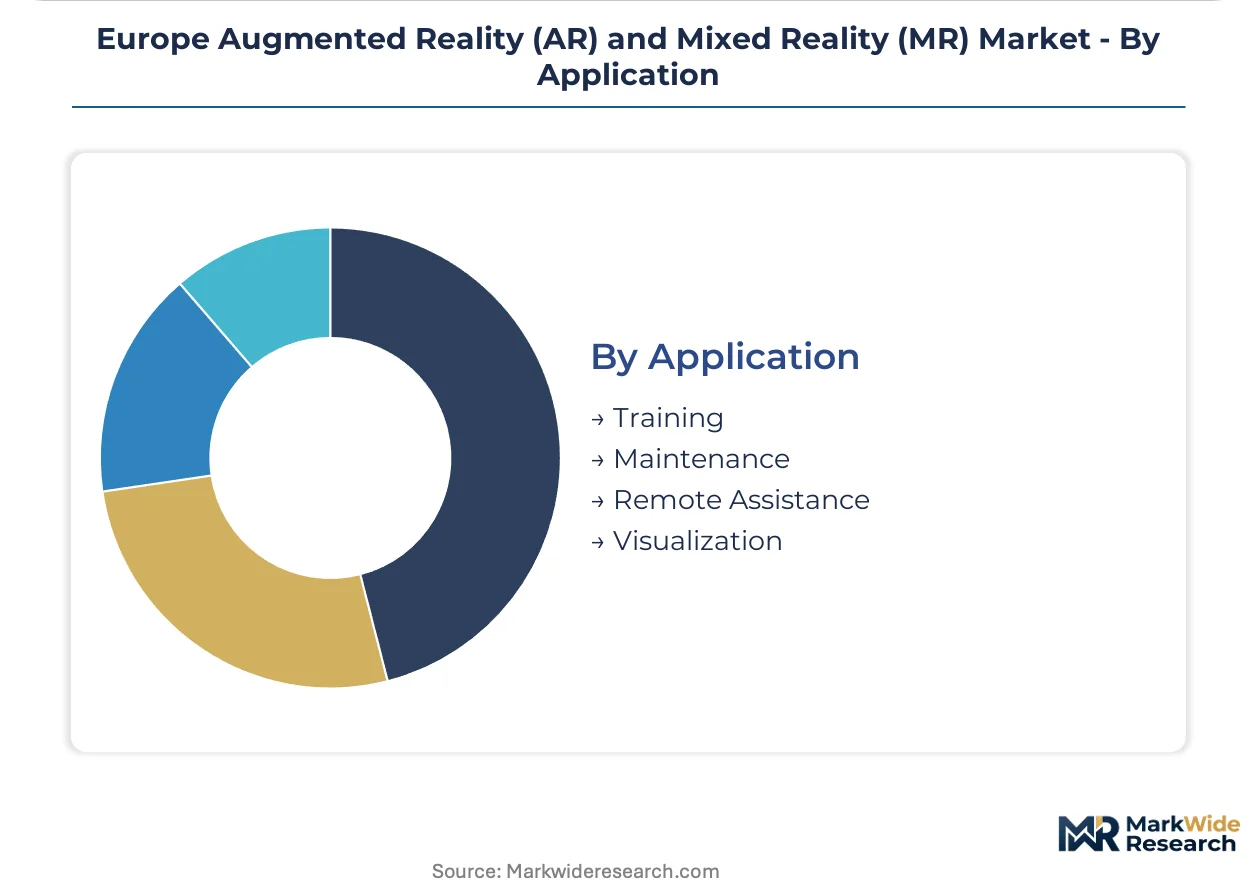
Application:
Task criticality and expert availability determine willingness to absorb hardware costs and integration complexity.
- Remote Assistance:Real-time expert guidance reduces field technician dispatch requirements. Bosch and Siemens affiliates in Germany's manufacturing corridor pilot these workflows for complex equipment diagnostics.
- Maintenance:MR-guided procedures compress repair timelines and error rates. Maritime operators in Nordic waters prioritize hands-free documentation access.
- Training:Immersive simulation replaces hazardous or resource-intensive practice scenarios. Polish logistics clients use Warsaw-developed modules for warehouse automation workforce development.
- Visualization:3D data overlay for design review and pre-surgical planning. Medical device manufacturers in Belgium and the Netherlands sustain R&D partnerships for anatomical modeling.
Remote Assistance dominates current enterprise spending; Maintenance applications show the steepest expansion trajectory as industrial IoT integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spatial computing talent pools concentrate in Germany's industrial belt, the Netherlands' university hospital networks, and Poland's emerging logistics technology corridor.
Germany
Bosch and Siemens affiliates pilot MR-guided maintenance workflows across the manufacturing corridor, reducing field technician dispatch requirements. The EU AI Act's risk-classification framework compresses algorithmic transparency timelines for aviation and surgical deployments. Bavaria and Baden-Württemberg host precision optics foundries supplying waveguide components for Head-Mounted Displays.
France
Hospital systems in Paris and Lyon replace cadaver-based instruction with AR-guided surgical simulations, compressing resident onboarding timelines. ANSM device-software interface guidelines intersect with CNIL biometric data rules to shape vendor qualification requirements. The Île-de-France region anchors healthcare visualization R&D partnerships with medical device manufacturers.
Netherlands
Dutch university hospitals pilot standardized transparency frameworks for surgical MR systems ahead of EU AI Act formal enforcement. EMA guidelines require traceability matrices linking training data to clinical decision outputs. Eindhoven's photonics cluster supplies micro-display assemblies for enterprise Head-Mounted Displays.
Poland
Warsaw-based development studios anchor mixed-reality training modules for warehouse automation clients, with underpenetrated last-mile operators representing expansion targets. REACH compliance obligations for rare-earth sensors create captive demand for compliant sourcing networks. The Mazovia region concentrates logistics technology vendors serving Central European distribution corridors.
Nordic Region
Norwegian and Danish shipping fleets deploy markerless tracking solutions for offshore maintenance where marker placement proves impractical. GDPR biometric constraints limit real-time personalization features for maritime workforce applications. Copenhagen and Oslo harbor technology clusters specializing in hands-free documentation access for deck operations.
Europe Augmented Reality (AR) and Mixed Reality (MR) Market Competitive Landscape
The competitive structure tilts toward specialized development studios with vertical expertise in healthcare, logistics, or maritime applications. The vendor base distributes across tiered archetypes: precision hardware fabricators, software-defined platform operators, and domain-specific solution integrators. Dominant competitive moves include strategic partnerships with university hospitals for clinical validation and geographic anchoring in underpenetrated logistics corridors.
Among Warsaw-based development studios, Tsukat occupies a position within the logistics-specialist archetype. Nomtek represents the Nordic maritime application tier. Lucid Reality Labs exemplifies the healthcare visualization specialist segment, anchoring R&D partnerships with university hospitals in the Netherlands and Belgium.
| Leading Market Players |
|---|
| Tsukat |
| nomtek |
| Lucid Reality Labs |
| Giant Lazer |
| FFFACE.ME |
| YORD |
| HQSoftware |
| Lens That |
| Delta Reality |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up precision optics specialists have consolidated waveguide fabrication capacity across Bavaria and Baden-Württemberg, tightening supply discipline while enabling premium pricing for CE-marked Head-Mounted Displays destined for German surgical training centers.
Pricing Analysis
Bundled hardware-software subscriptions now dominate enterprise procurement, displacing perpetual licenses. Price differentiation rests on EMA compliance tier and GDPR-ready biometric data architectures. Cost compression in mid-tier Smart Glasses intensifies as Polish logistics operators demand volume discounts for warehouse automation rollouts. Healthcare buyers show lowest price sensitivity due to cadaver replacement cost savings.
Supply Chain Analysis
Reverse-logistics networks for Head-Mounted Display refurbishment remain underdeveloped across Europe, creating working capital drag for enterprise fleet operators. Waveguide optics fabrication concentrates in Germany, Taiwan, and the United States. Rare-earth sensor inputs draw from Chinese and Vietnamese processing facilities. Single-source vulnerability in diffractive optical element supply threatens production continuity. Distribution runs through specialized AV integrators serving hospital systems and industrial maintenance divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant component sourcing in Western Europe and lower-cost development talent in Poland's Mazovia corridor, where Warsaw-based studios deliver comparable SLAM expertise at reduced labor rates.
For Market Incumbents: Cement control over EMA pre-certification pathways by acquiring Dutch and Belgian university hospital validation partnerships before EU AI Act enforcement tightens. Prioritize backward integration into waveguide optics fabrication to defend margins against rare-earth sensor cost volatility. Lock in multi-year remote assistance platform subscriptions with Bosch and Siemens affiliates to raise switching costs. For New Entrants and Emerging Players: Systems integrators with existing SCADA middleware relationships represent the fastest channel to industrial maintenance contracts. Target underpenetrated Polish last-mile logistics operators with markerless tracking modules priced below Nordic maritime solutions. Lead with compressed deployment timelines rather than feature depth to bypass incumbent certification advantages. For Investors and Strategic Acquirers: Valuations sit cheapest among Warsaw-based development studios lacking Western European regulatory dossiers but possessing proven SLAM architectures. Five-to-ten-year viability hinges on EMA-GDPR convergence compliance rather than pure technical capability. Monitor CE marking timeline extensions under MDR reclassification as inflection signal for hardware-focused acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pre-Certification Partnership | Establishes clinical validation pathway ahead of EU AI Act risk-classification enforcement. |
| Waveguide Optics Backward Integration | Captures precision optics margin pool concentrated in Bavarian foundries. |
| Polish Logistics Corridor Expansion | Exploits REACH-compliant sourcing proximity and underpenetrated last-mile automation demand. |
| Subscription Platform Migration | Converts German machine-tool operators from perpetual licenses to recurring revenue streams. |
| GDPR-Ready Biometric Architecture | Pre-integrates gaze-tracking compliance for Dutch and Belgian university hospital deployments. |
Research Methodology
Multiple input streams — structured interviews with surgical training directors and biomedical engineers, procurement database analysis from German hospital systems, and EMA device-software interface guideline review — were reconciled against customs records for waveguide optics imports and hyperscaler spatial computing capex disclosures. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across the analysis window.
Historical adoption curves for AR-guided maintenance in German automotive assembly lines were cross-referenced against expert panel assessments of EU AI Act implementation timelines. The forecast framework modeled hardware-software splits, end-user verticals, and technology tiers across the projection horizon. CAGR derivation incorporated SLAM algorithm talent scarcity indices and MDR reclassification probability weights.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction expansions and rare-earth export licensing shifts. Practitioners should monitor CE marking queue lengths for optical see-through displays and EMA transparency framework pilot results for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market