
 Austria Data Center Networking Market | 2026-2036
Austria Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Data Center Networking Market Insights
The EU Green Deal is restructuring procurement criteria for Austrian data center operators, mandating measurable energy efficiency in network equipment deployments. Cisco Systems leverages its Vienna-based engineering presence to sustain channel relationships with domestic cloud builders. Arista Networks anchors high-frequency trading connectivity in the Vienna Stock Exchange ecosystem. Huawei Technologies competes aggressively on optical networking tenders despite EU supply chain scrutiny.
Austria data center networking encompasses the switching, routing, and security infrastructure interconnecting compute and storage resources within and between facilities, typically operating at 100 Gbps to 400 Gbps port speeds with sub-microsecond latency requirements for high-performance workloads. Its primary purpose is enabling reliable, scalable data exchange for cloud services, enterprise applications, and telecommunications traffic. Ethernet switching dominates current deployments due to cost-performance optimization for east-west traffic patterns, while SD-WAN adoption is accelerating among Austrian enterprises seeking hybrid cloud connectivity without MPLS dependency. Firewall appliances command premium positioning as regulatory pressure intensifies around data sovereignty and cross-border transfer controls.
Austrian data center networking falls under BSI-KritisV critical infrastructure regulations, EU NIS2 Directive transposition, and national telecommunications law administered by RTR, creating layered compliance obligations for operators. These frameworks shape demand by mandating redundant connectivity architectures, incident reporting protocols, and supplier security vetting that favor established vendors with certification depth. Stakeholders must monitor how EU chip sovereignty initiatives and domestic semiconductor funding alter vendor eligibility for public sector contracts.
Market Dynamics
The EU AI Act is compressing deployment timelines for Austrian data center operators, forcing simultaneous upgrades to network observability, audit logging, and cross-border traffic governance that reshape capital allocation priorities.
Growth Catalysts
- BSI-KritisV Compliance Mandates:Austria's critical infrastructure regulations require redundant switching architectures for financial and energy sector facilities, driving replacement cycles for aging core routers.
- Vienna Hyperscale Clustering:Concentration of cloud buildouts in the capital's enterprise corridor creates dense demand for 400 Gbps interconnect fabrics and low-latency edge switching.
- EU Green Deal Procurement Rules:Energy efficiency benchmarks for network equipment are tilting vendor selection toward silicon architectures with measurable power-to-throughput ratios.
Market Restraints
- Optics Supply Concentration:Dependency on Asian manufacturing for 400 Gbps coherent optical modules creates lead time volatility and inventory carrying costs for Austrian integrators.
- NIS2 Transposition Friction:Austria's delayed alignment with EU cybersecurity directives is freezing procurement decisions among risk-averse public sector buyers awaiting final implementation guidance.
- Copper Interconnect Substitution:Passive optical cabling is displacing traditional copper DAC assemblies in top-of-rack deployments, stranding installed base investments for enterprise data centers.
Strategic Opportunities
- Tyrol Edge Computing Expansion:Industrial automation corridors in western Austria are underserved by hyperscale presence, creating whitespace for distributed micro-data center networking.
- AI Training Cluster Convergence:InfiniBand-Ethernet hybrid fabrics are opening new integration service revenue streams for domestic systems integrators serving research institutions.
- RTR Spectrum Harmonization:Austria's telecommunications regulator is clearing 6 GHz bands for private 5G campus networks, enabling wireless backhaul alternatives for remote facility interconnection.
Industry Challenges
- Network Automation Skill Scarcity:Austrian enterprises face acute shortages of engineers proficient in intent-based networking and infrastructure-as-code tooling, extending deployment timelines.
- Multivendor Certification Overlap:Fragmented security certification requirements across BSI, EUCC, and Common Criteria schemes are inflating pre-deployment validation costs for equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Data Center Networking Market |
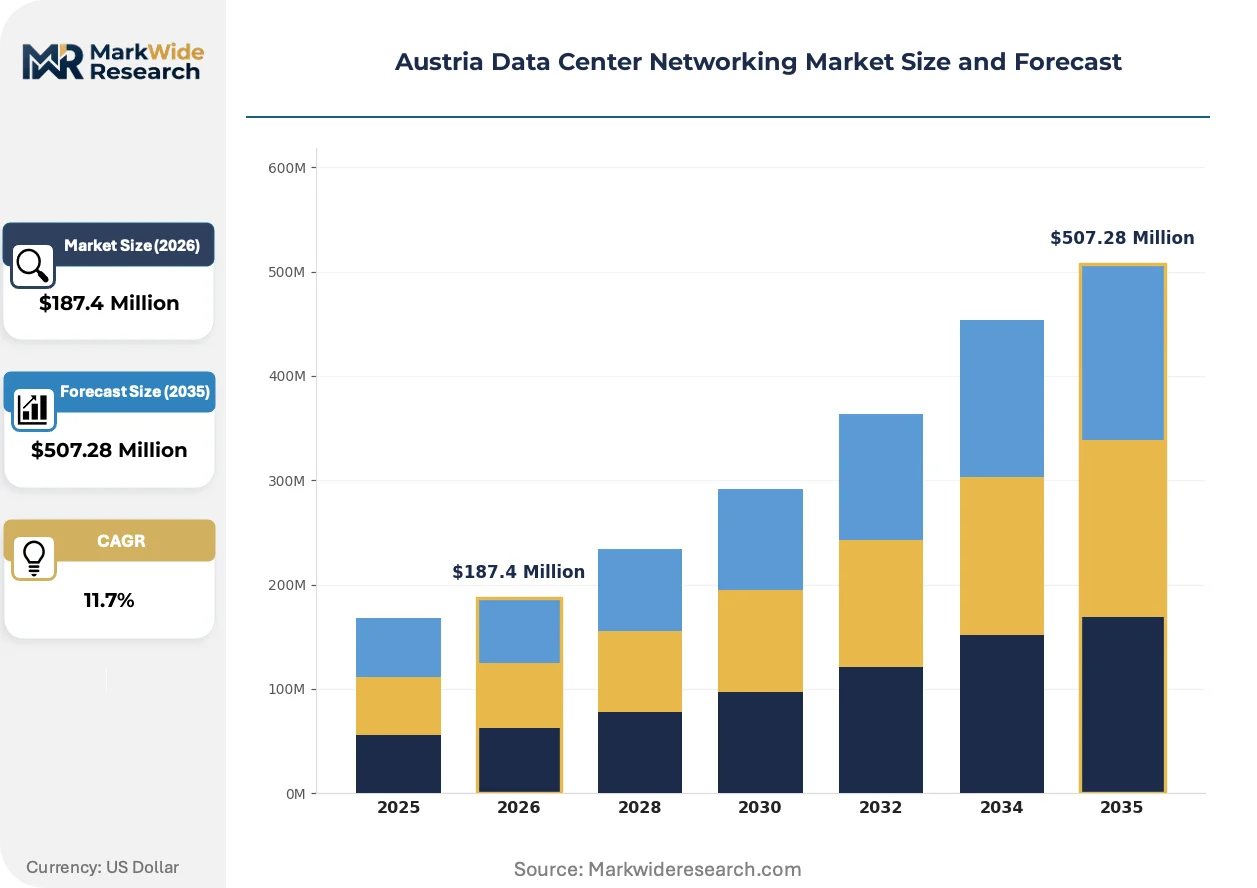
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Switch, Firewall, Load Balancer Technology: Ethernet, MPLS, SD-WAN, Optical Networking Use Case: Cloud Computing, Virtualization, Big Data, Disaster Recovery End User: Enterprises, Telecom Providers, Government, Managed Service Providers |
| Companies Covered | Cisco Systems, Arista Networks, VMware, Huawei Technologies, Dell Technologies, IBM, Broadcom, A1 Telekom Austria Group, NTT Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Data Center Networking Market Trends and Innovations
Intent-based networking is displacing CLI-driven administration in Austrian enterprise data centers, compressing operational error rates while demanding new orchestration skill sets from domestic IT services providers.
Software-defined networking controllers are decentralizing traffic engineering authority from hardware-centric architectures to programmable fabric management. Austrian financial services firms are adopting these platforms aggressively to support real-time workload mobility across hybrid cloud footprints. This shift is compressing differentiation margins for traditional chassis-based switching vendors while elevating subscription revenue from controller licensing.
The EU AI Act's risk classification framework is mandating granular network telemetry retention for high-risk AI system hosting environments. Austrian operators must now deploy packet-level inspection and flow logging at unprecedented scale, driving demand for specialized monitoring fabrics. Colocation providers in Vienna are responding by pre-installing compliant observability infrastructure to accelerate tenant onboarding.
Consumption-based network procurement is displacing perpetual licensing among mid-sized Austrian enterprises seeking to align infrastructure spending with actual traffic growth. Systems integrators are capturing this shift through managed network-as-a-service offerings that bundle hardware, software, and operational support. The model is most visible in Styria's manufacturing belt, where capital-constrained automotive suppliers favor opex treatment for connectivity upgrades.
Austria Data Center Networking Market Segmentation
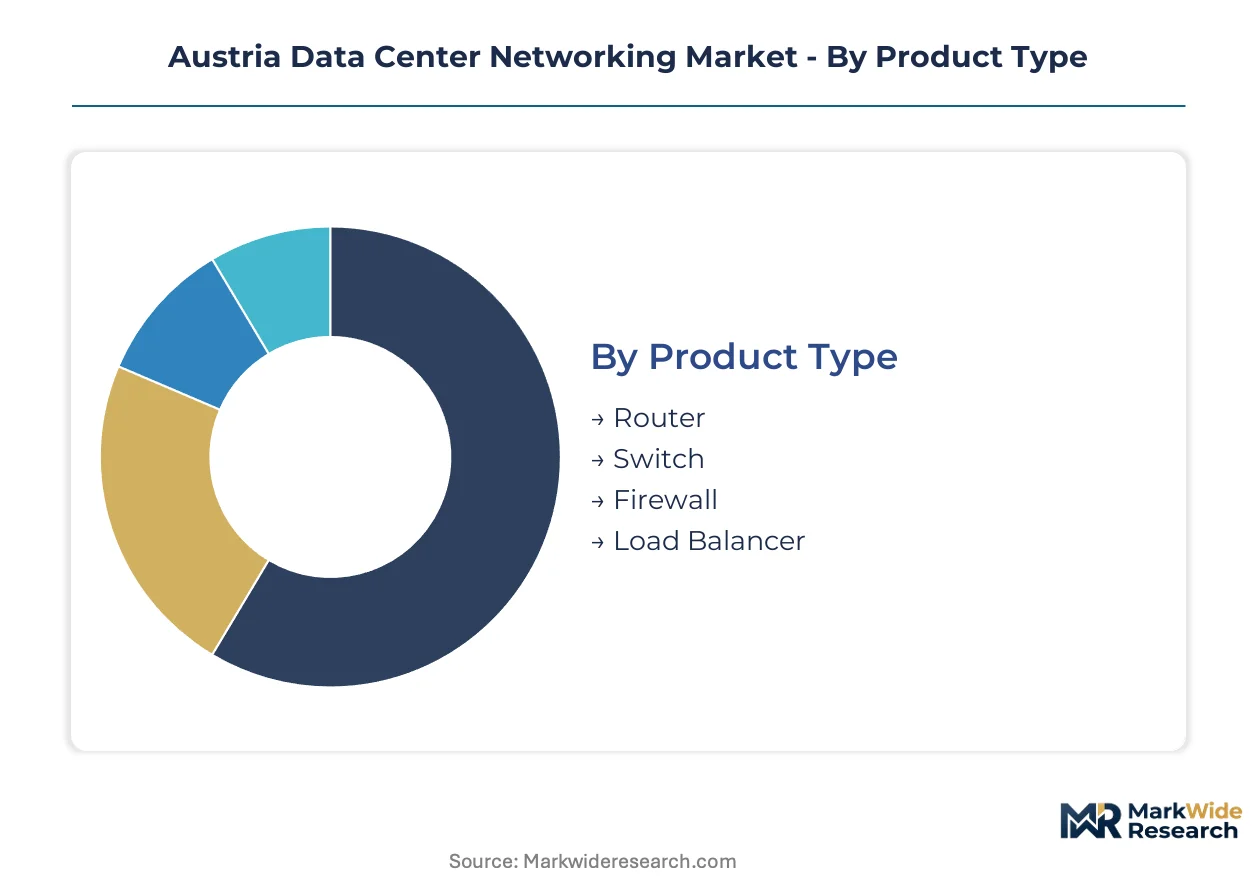
Segmentation of Austria's data center networking market reveals how procurement decisions cluster around specific workload requirements and compliance obligations. Understanding these divisions illuminates where capital concentrates and which technology trajectories will reshape infrastructure planning over the forecast window.
Product Type:
Ethernet switching dominates current deployments through cost-performance optimization for east-west traffic patterns within Austrian facilities.
- Router:Core routing platforms handle inter-facility traffic and internet exchange connectivity, with demand concentrating in Vienna's hyperscale corridor where BSI-KritisV mandates redundant backbone architectures for financial sector operators.
- Switch:Top-of-rack and spine-leaf Ethernet switches constitute the volume foundation of Austrian deployments, with 400 Gbps port speeds gaining traction among cloud builders seeking to minimize latency for AI training clusters.
- Firewall:Next-generation firewall appliances command premium positioning as EU AI Act and data sovereignty regulations intensify deep packet inspection requirements for cross-border traffic governance.
- Load Balancer:Application delivery controllers distribute traffic across compute pools, serving managed service providers in Styria's manufacturing belt that require high availability for multi-tenant cloud offerings.
Switch leads on scale; firewall leads on momentum.
Technology:
Technology selection in Austrian data centers tracks the tension between proven interoperability and programmable flexibility demanded by modern workload orchestration.
- Ethernet:Standardized Layer 2/3 switching protocols deliver the cost basis for most Austrian enterprise deployments, with 100 Gbps now baseline and 400 Gbps penetration accelerating among Vienna's colocation providers.
- MPLS:Traditional multiprotocol label switching retains footprint in legacy financial networks but faces displacement as SD-WAN alternatives reduce dependency on carrier-provisioned private circuits.
- SD-WAN:Software-defined wide area networking is expanding most quickly among mid-sized Austrian enterprises seeking hybrid cloud connectivity without MPLS cost structures, particularly in Tyrol's industrial automation corridors.
- Optical Networking:Coherent optical transport enables metro and long-haul interconnect between Austrian facilities, though supply concentration in Asian manufacturing modules creates lead time volatility for integrators.
Ethernet leads on scale; SD-WAN leads on momentum.
Use Case:
Workload-specific networking requirements in Austria diverge sharply between latency-sensitive financial applications and throughput-bound research computing.
- Cloud Computing:Multi-tenant infrastructure demands elastic network provisioning with API-driven automation, concentrating investment among Vienna's hyperscale cluster where colocation providers pre-install observability fabrics to accelerate tenant onboarding.
- Virtualization:Software-defined compute environments require east-west traffic optimization within server racks, with Austrian enterprises adopting intent-based networking to reduce operational error rates in virtual machine migration scenarios.
- Big Data:Distributed analytics frameworks push bandwidth requirements horizontally across storage nodes, serving research institutions in Graz and Linz that are deploying InfiniBand-Ethernet hybrid fabrics for AI training convergence.
- Disaster Recovery:Synchronous replication between geographically separated facilities mandates sub-millisecond latency links, with BSI-KritisV regulations mandating redundant paths for critical infrastructure operators in the energy and financial sectors.
Cloud computing leads on scale; big data leads on momentum.
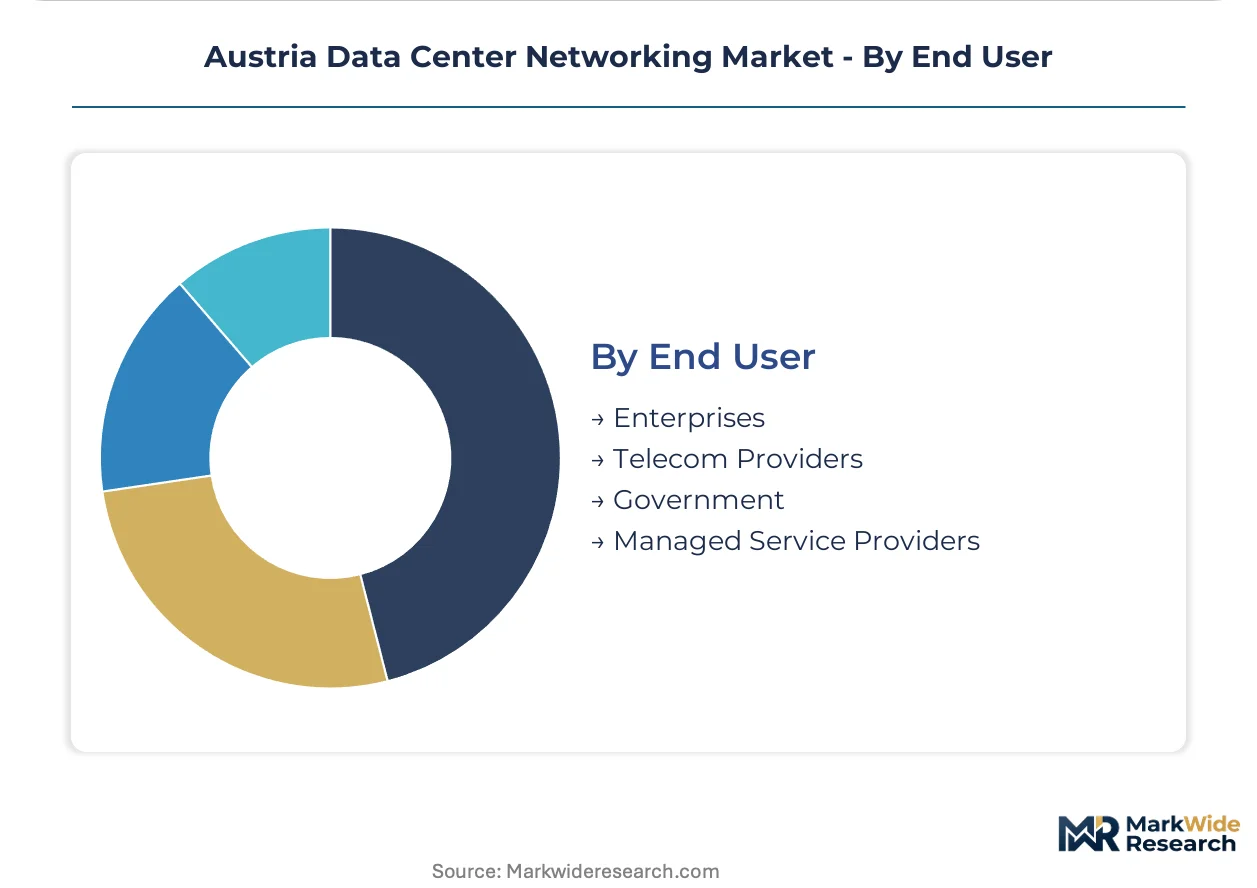
End User:
End user segmentation in Austria reflects divergent procurement authority between centralized government frameworks and decentralized enterprise decision-making.
- Enterprises:Private sector operators across Vienna's enterprise corridor drive volume demand for programmable switching fabrics, with consumption-based procurement models gaining traction among capital-constrained automotive suppliers in Styria.
- Telecom Providers:Incumbent carriers and altnet operators deploy networking infrastructure for wholesale colocation and managed services, with RTR spectrum harmonization in 6 GHz bands enabling private 5G campus network alternatives.
- Government:Federal and state agencies operate under strict BSI-KritisV and NIS2 compliance frameworks, with delayed transposition of EU cybersecurity directives currently freezing procurement decisions among risk-averse public sector buyers.
- Managed Service Providers:Domestic systems integrators bundle hardware, software, and operational support into network-as-a-service offerings, capturing opex preference among mid-sized Austrian enterprises seeking to align spending with actual traffic growth.
Enterprises lead on scale; managed service providers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austria's data center networking industry traces its lineage to Vienna's emergence as a Central European telecommunications hub during the post-war period, when neutral positioning attracted international carriers seeking interconnection points between Eastern and Western bloc infrastructure. The capital's geographic centrality established foundational fiber routes that now anchor hyperscale clustering decisions.
Vienna Metropolitan Area
Financial services firms and hyperscale colocation operators drive 400 Gbps interconnect demand across the capital's enterprise corridor. BSI-KritisV critical infrastructure regulations mandate redundant backbone architectures for operators serving energy and banking sectors. The Vienna Stock Exchange ecosystem anchors low-latency trading connectivity requirements that favor specialized switching platforms.
Styria Manufacturing Belt
Automotive suppliers and capital-constrained industrial enterprises favor consumption-based network procurement models aligned with actual traffic growth. EU Green Deal procurement rules enforce energy efficiency benchmarks for network equipment deployed across Graz-area production facilities. Domestic systems integrators capture recurring revenue through managed network-as-a-service bundles.
Tyrol Industrial Automation Corridor
Western Austria's underserved status relative to hyperscale presence creates whitespace for distributed micro-data center networking serving precision manufacturing. RTR spectrum harmonization in 6 GHz bands enables private 5G campus network alternatives for wireless backhaul between remote facilities. Innsbruck-area research institutions pilot InfiniBand-Ethernet hybrid fabrics for AI training convergence.
Upper Austria Technology Cluster
Linz-based research computing centers push bandwidth requirements horizontally across storage nodes for distributed analytics frameworks. National semiconductor funding initiatives alter vendor eligibility criteria for public sector contracts requiring domestic value-add verification. Steel industry automation drives edge computing networking specifications for real-time process control.
Austria Data Center Networking Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and compliance automation capabilities in Austria's data center networking market. The vendor base stratifies between chassis-based switching incumbents with established BSI certification portfolios and programmable fabric challengers capturing software-defined revenue streams. Three archetypes dominate: full-stack infrastructure vendors with domestic engineering presence, specialized switching pure-plays with financial sector anchoring, and telecommunications operators with wholesale colocation integration. Competitive moves concentrate on strategic partnerships with domestic systems integrators and portfolio diversification into intent-based networking orchestration.
Within the established infrastructure tier, Cisco Systems leverages its Vienna-based engineering presence to sustain channel relationships, while Arista Networks occupies a position exemplifying high-frequency trading connectivity specialization. Huawei Technologies sits within the optical networking segment despite EU supply chain scrutiny affecting public sector eligibility. These three anchors illustrate how vendor selection criteria diverge between private sector cloud builders and compliance-constrained government buyers.
| Leading Market Players |
|---|
| Cisco Systems |
| Arista Networks |
| VMware |
| Huawei Technologies |
| Dell Technologies |
| IBM |
| Broadcom |
| A1 Telekom Austria Group |
| NTT Ltd |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal procurement mandates for measurable power-to-throughput ratios are forcing Austrian data center operators toward silicon architectures with embedded telemetry, compressing vendor margins on legacy chassis while elevating premium positioning for compliant equipment.
Pricing Analysis
Consumption-based network procurement separates premium intent-based networking bundles from standard perpetual licensing from economy-grade refurbished hardware resales. Price differentiation hinges on BSI-KritisV certification depth and after-sales operational support tiers. Cost compression in mid-market switching stems from hyperscale buyers consolidating volume commitments. Capital-constrained automotive suppliers in Styria exhibit highest price sensitivity; Vienna financial sector operators show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Czech Republic anchor hub-and-spoke fulfillment patterns for Austrian integrators. Optical module manufacturing concentrates in Taiwan, South Korea, and China, creating single-source vulnerability for 400 Gbps coherent components. Copper interconnect stranding accelerates inventory obsolescence risk. Distribution runs through Vienna-based value-added resellers with BSI certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Austria's data center networking market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France exceed Austrian operational overhead by meaningful margins, attracting workload migration that sustains Vienna hyperscale clustering.
For Market Incumbents: Acquire domestic systems integrators with established BSI-KritisV certification pipelines to counter Huawei Technologies' aggressive optical networking tenders. Consolidate channel control through backward integration into Vienna-based engineering services. Certification investment in EUCC and Common Criteria schemes defends against multivendor validation cost inflation.
For New Entrants and Emerging Players: Begin with Tyrol's industrial automation corridors where private 5G campus network whitespace remains underserved by incumbent hyperscale presence. Target precision manufacturing facilities seeking distributed micro-data center networking outside Vienna's enterprise corridor. Partner with RTR-licensed spectrum holders for wireless backhaul integration services.
For Investors and Strategic Acquirers: Asymmetric upside sits with programmable fabric challengers capturing software-defined revenue streams from chassis-based switching incumbents. Long-term viability favors vendors with intent-based networking orchestration capabilities and established channel relationships with Austrian managed service providers. Monitor NIS2 transposition finalization as inflection indicator for public sector procurement reactivation.
| Strategic Initiative | Industry Significance |
|---|---|
| Intent-Based Networking Platform Launch | Reduces operational error rates for Austrian enterprises adopting infrastructure-as-code tooling. |
| BSI-KritisV Certification Investment | Unlocks public sector procurement eligibility under Austria's critical infrastructure regulations. |
| Domestic Systems Integrator Acquisition | Captures recurring network-as-a-service revenue from Styria's capital-constrained automotive suppliers. |
| 6 GHz Private 5G Campus Partnership | Enables wireless backhaul alternatives for Tyrol's remote precision manufacturing facilities. |
| Optical Module Supply Agreement | Mitigates lead time volatility from Asian manufacturing concentration for 400 Gbps deployments. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic regions, with primary inputs from each. Data collection combined structured interviews with data center infrastructure directors, network engineering leads at financial services firms, procurement officers at colocation providers, and channel managers at value-added resellers. Secondary validation drew from RTR regulatory filings, BSI certification databases, hyperscaler capex disclosures, and EU NIS2 implementation tracking. Bottom-up equipment shipment analysis triangulated against top-down infrastructure spending estimates.
Rate-of-change decomposition segmented expansion across product type, technology, use case, and end user dimensions throughout the forecast period. CAGRs derived from regression analysis of historical deployment velocity against regulatory milestone timing and cloud buildout announcements. Industry-specific inputs included BSI-KritisV compliance cost modeling and EU AI Act risk classification impact on observability infrastructure demand.
Several conditions sit outside the modeled scope, including unannounced hyperscale facility locations, pre-emptive regulatory amendments, and semiconductor supply disruptions beyond current lead time volatility. Forecasts reflect documented assumptions around NIS2 transposition timing and EU chip sovereignty initiative implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Data Center Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market