
 US Dark Fiber Network Market | 2026-2036
US Dark Fiber Network Market Size, Share, and Industry Trends Forecast 2026-2036
US Dark Fiber Network Market Intelligence
Metro fiber builders in Dallas-Fort Worth and Northern Virginia is pivoting toward long-haul conduit pairs to serve hyperscale campuses. Zayo Group Holdings leverages its 16 million fiber-mile footprint to anchor wholesale contracts with cloud operators. Lumen Technologies sustains legacy intercity routes while competing for enterprise dedicated circuits in secondary markets.
US Dark Fiber Networks consist of unlit optical fiber strands installed in underground conduit, typically operating at single-mode specifications with attenuation below 0.35 dB per kilometer at 1550 nanometers, leased to customers who supply their own transmission electronics and lighting equipment. Wholesale networks dominate volume as carrier-neutral operators aggregate strand access for multiple tenants, while private networks command premium positioning among financial services firms requiring physical route diversity. Enterprise networks represent the fastest structural expansion as healthcare systems and research universities procure dark fiber for campus interconnect and disaster recovery topology.
FCC pole attachment rules under Section 224 and state public utility commissions shape deployment economics by governing access rates and timelines for fiber overbuilds. The NTIA Broadband Equity, Access, and Deployment program and state-level dig-once mandates are redirecting public infrastructure dollars toward conduit-ready corridors. Stakeholders must monitor how BEAD funding timelines intersect with utility pole access disputes to calibrate construction schedules against committed lease obligations.
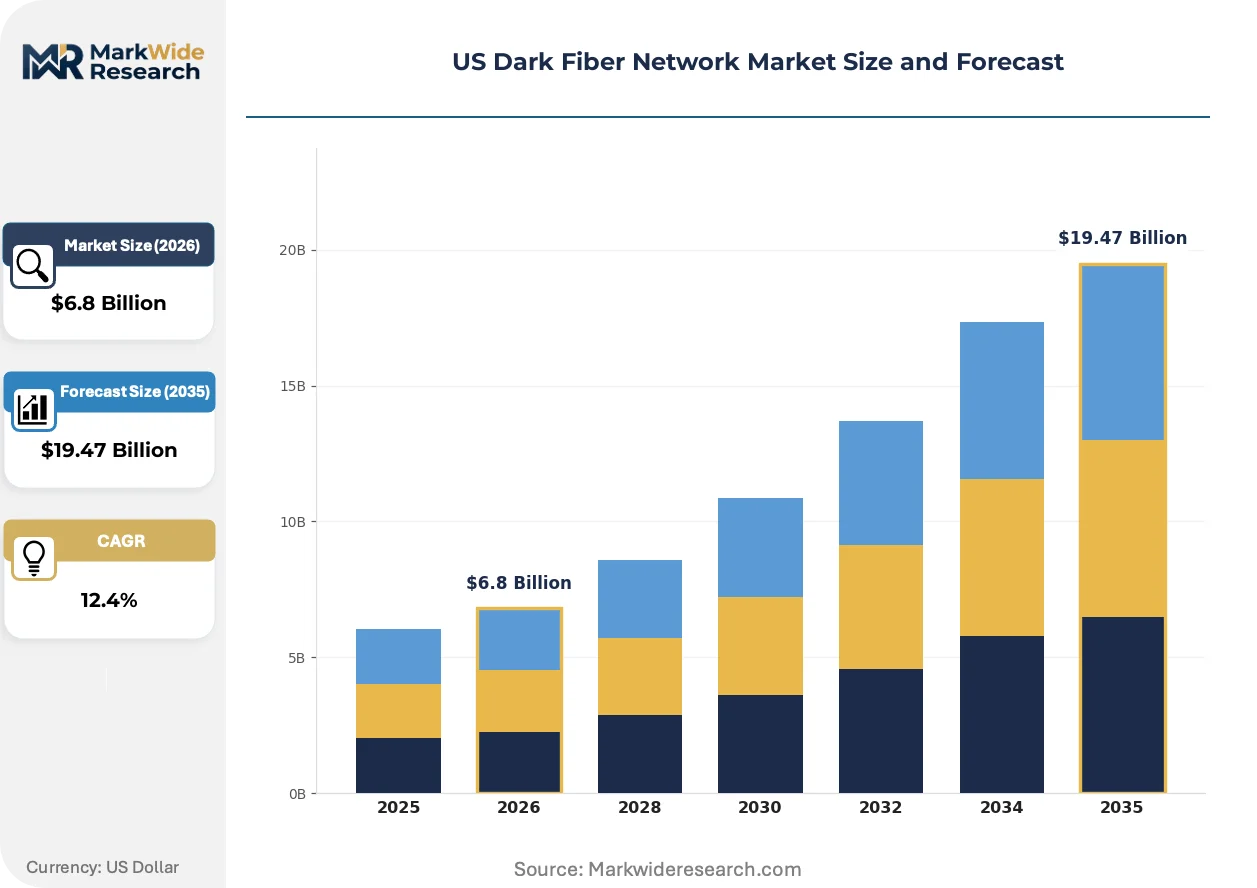
Market Dynamics
Hyperscale cloud providers are consolidating physical infrastructure procurement around dedicated dark fiber conduit, compressing traditional carrier wholesale hierarchies and forcing route-specific construction commitments in Texas, Virginia, and California corridors.
Growth Catalysts
- BEAD Funding Alignment:The NTIA Broadband Equity, Access, and Deployment program redirects public infrastructure dollars toward conduit-ready corridors, accelerating strand availability in underserved metro rings.
- Hyperscale Campus Expansion:Cloud operators are procuring dark fiber for dedicated inter-campus links, creating anchor demand that justifies long-haul construction economics.
- Dig-Once Mandates:State-level policies in Texas and Virginia require conduit installation during road and utility projects, reducing incremental deployment costs for fiber builders.
Market Restraints
- Right-of-Way Access Friction:FCC Section 224 pole attachment disputes with electric utilities delay overbuild timelines and inflate make-ready costs in suburban corridors.
- Construction Labor Scarcity:Specialized fiber splicing and directional drilling crews concentrate in established metro markets, constraining expansion velocity in secondary cities.
- Optical Equipment Substitution:Coherent optical transceivers at 800G and 1.6T capacities enable wavelength leasing over lit fiber, reducing the cost advantage of unlit strand procurement for mid-bandwidth users.
Strategic Opportunities
- Healthcare Campus Interconnect:Hospital systems in secondary metros are procuring dark fiber for campus disaster recovery topology, creating demand outside traditional financial services verticals.
- Research University Networks:Universities with federal research grants require physical route diversity for data replication, opening procurement channels distinct from commercial carrier sales.
- Edge Data Center Backhaul:Distributed compute nodes in Phoenix, Columbus, and Atlanta need dedicated fiber pairs, extending addressable geography beyond established hyperscale corridors.
Industry Challenges
- Route Certification Complexity:Financial services buyers require documented physical diversity certificates that trace conduit paths across multiple carrier handoffs, extending sales cycles.
- Legacy SONET Integration:Enterprise customers with existing TDM infrastructure face protocol translation costs when lighting dark fiber with modern packet-optical equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dark Fiber Network Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $19.47 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Network Type: Private Networks, Wholesale Networks, Carrier Networks, Enterprise Networks Connectivity Mode: Dedicated Connection, Leased Connection, Point-to-Point, Multipoint Service Provider: Telecom Companies, Internet Service Providers, Data Center Operators, Municipal Networks End User: Enterprises, Educational Institutions, Government Agencies, Research Facilities |
| Companies Covered | Zayo Group Holdings, Lumen Technologies, AT&T, Crown Castle Fiber, Verizon Communications, Comcast Corporation, Uniti Group, Consolidated Communications, GTT Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dark Fiber Network Market Strategic Shifts & Innovations
Open optical line systems are disrupting traditional vendor lock-in, enabling hyperscale operators to source transponders and amplifiers independently from fiber leases and compressing equipment procurement cycles.
Coherent pluggable optics operating at 400ZR and 800ZR standards is decentralizing network architecture decisions away from incumbent carrier engineering teams. Cloud operators now source their own transceivers from multiple vendors and light dark fiber directly, bypassing traditional managed wavelength services. This shift compresses the value capture of lit-fiber providers and forces wholesale operators to compete on route diversity rather than equipment integration.
FCC infrastructure deployment rules under Section 224 are reshaping pole attachment economics by mandating timeline certainty for fiber overbuilds. The regulatory pressure reduces utility stall tactics and accelerates construction schedules in suburban and rural corridors. Wholesale operators in Texas and Florida are responding by pre-negotiating bulk pole access agreements to secure construction windows ahead of lease commitments.
Enterprise procurement patterns are fragmenting away from long-term IRU contracts toward shorter-term dark fiber leases with renewal options. Healthcare systems and research universities in secondary markets now favor five-year terms with expansion clauses over traditional twenty-year indefeasible rights of use. This compression is visible most acutely in the Midwest, where institutional buyers prioritize capital flexibility over rate stability.
US Dark Fiber Network Market Segmentation
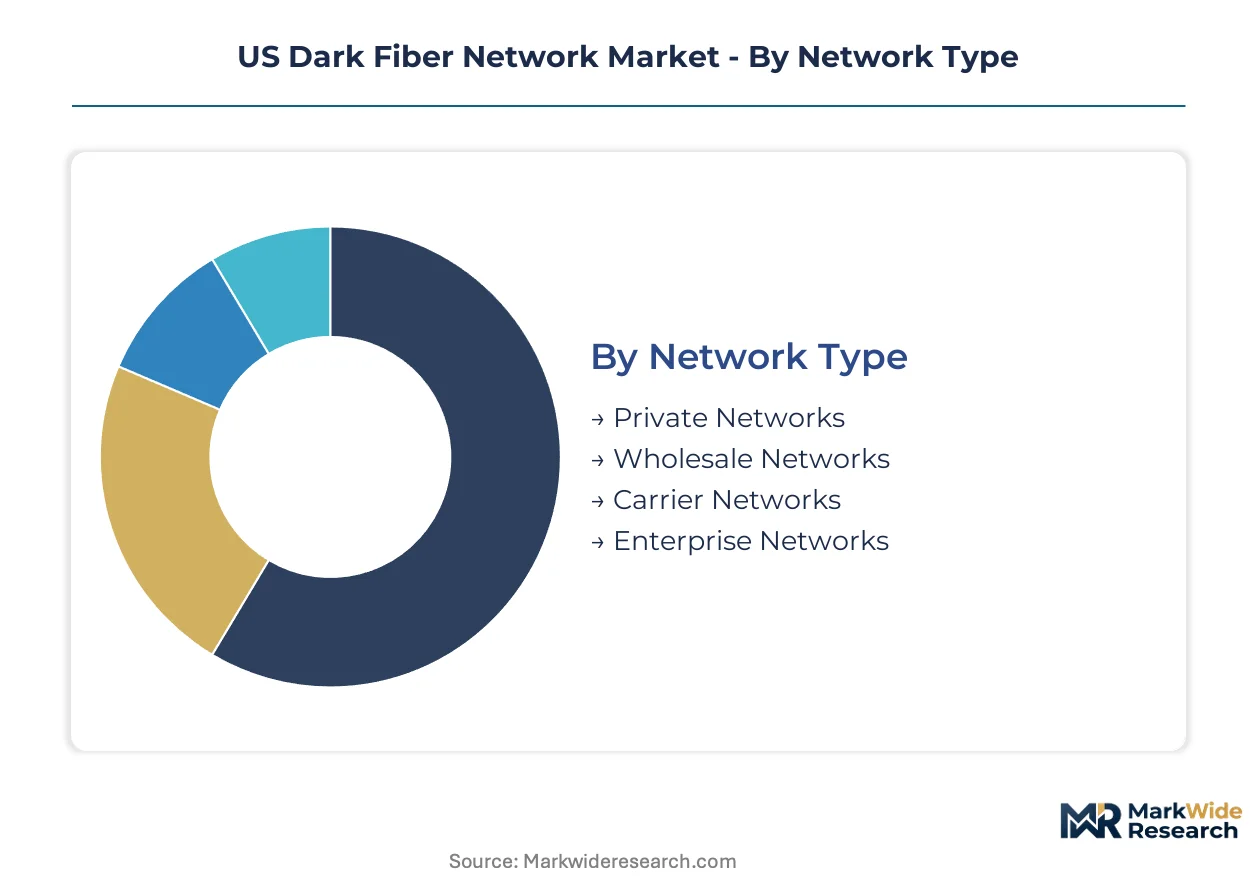
Dark fiber procurement patterns diverge sharply across customer archetypes, with hyperscale cloud operators demanding route-specific conduit while institutional buyers prioritize capital flexibility over long-term commitments. Understanding these segment boundaries clarifies where construction economics justify greenfield deployment versus lease aggregation.
Network Type:
Standardization decreases from wholesale aggregation models toward fully customized private builds, with enterprise procurement occupying a hybrid middle ground.
- Wholesale Networks:Carrier-neutral operators aggregate strand access for multiple tenants across shared conduit infrastructure. Demand concentrates in Northern Virginia and Dallas-Fort Worth data center corridors where Zayo Group Holdings and similar operators anchor cloud provider contracts through route diversity rather than equipment integration.
- Private Networks:Single-tenant dark fiber installations serving financial services firms and hyperscale operators who supply proprietary transmission electronics. Financial buyers in Chicago and New York require documented physical diversity certificates tracing conduit paths across multiple carrier handoffs, extending sales cycles but commanding premium positioning.
- Carrier Networks:Legacy intercity routes maintained by incumbent operators for dedicated circuit services. Lumen Technologies sustains these assets while competing for enterprise procurement in secondary markets where construction labor scarcity constrains expansion velocity.
- Enterprise Networks:Fastest structural expansion as healthcare systems and research universities procure dark fiber for campus interconnect and disaster recovery topology. Midwest institutional buyers favor five-year lease terms with expansion clauses over traditional twenty-year indefeasible rights of use.
Leading the category by volume: Wholesale Networks. Expanding most quickly: Enterprise Networks.
Connectivity Mode:
Cost tiers stratify from dedicated conduit pairs at premium rates toward shared multipoint architectures that reduce per-megabit economics for mid-bandwidth users.
- Dedicated Connection:Exclusive fiber strand assignments with guaranteed physical isolation. Hyperscale cloud providers in Texas and California corridors procure these for inter-campus links, creating anchor demand that justifies long-haul construction economics despite right-of-way access friction.
- Point-to-Point:Direct fiber pairs between two endpoints without intermediate aggregation. Research universities with federal grants require these configurations for data replication topology, opening procurement channels distinct from commercial carrier sales.
- Leased Connection:Term-based access to existing dark fiber infrastructure with renewal options. Healthcare systems in secondary metros favor this capital-flexible structure over ownership.
- Multipoint:Shared fiber access supporting multiple endpoints through passive optical splitting. Coherent optical transceivers at 800G and 1.6T capacities enable wavelength leasing alternatives that reduce the cost advantage of unlit strand procurement for this segment.
Commanding highest margins: Dedicated Connection. Gaining share fastest: Point-to-Point.
Service Provider:
Supply concentration varies from national telecom footprints toward hyperlocal municipal builds with divergent construction timelines and pole access economics.
- Telecom Companies:National-scale operators with established intercity conduit and FCC Section 224 pole attachment agreements. Pre-negotiated bulk pole access in Texas and Florida secures construction windows ahead of lease commitments.
- Data Center Operators:Vertically integrated fiber builds serving captive facilities and adjacent tenants. Edge data center nodes in Phoenix, Columbus, and Atlanta need dedicated fiber pairs, extending addressable geography beyond established hyperscale corridors.
- Internet Service Providers:Regional fiber builders pivoting from residential broadband toward commercial dark fiber services. NTIA BEAD funding redirects public infrastructure dollars toward conduit-ready corridors that accelerate strand availability.
- Municipal Networks:Publicly owned fiber infrastructure with state-level dig-once policy support. Texas and Virginia mandates require conduit installation during road and utility projects, reducing incremental deployment costs for these operators.
Highest volume concentration: Telecom Companies. Steepest expansion trajectory: Data Center Operators.
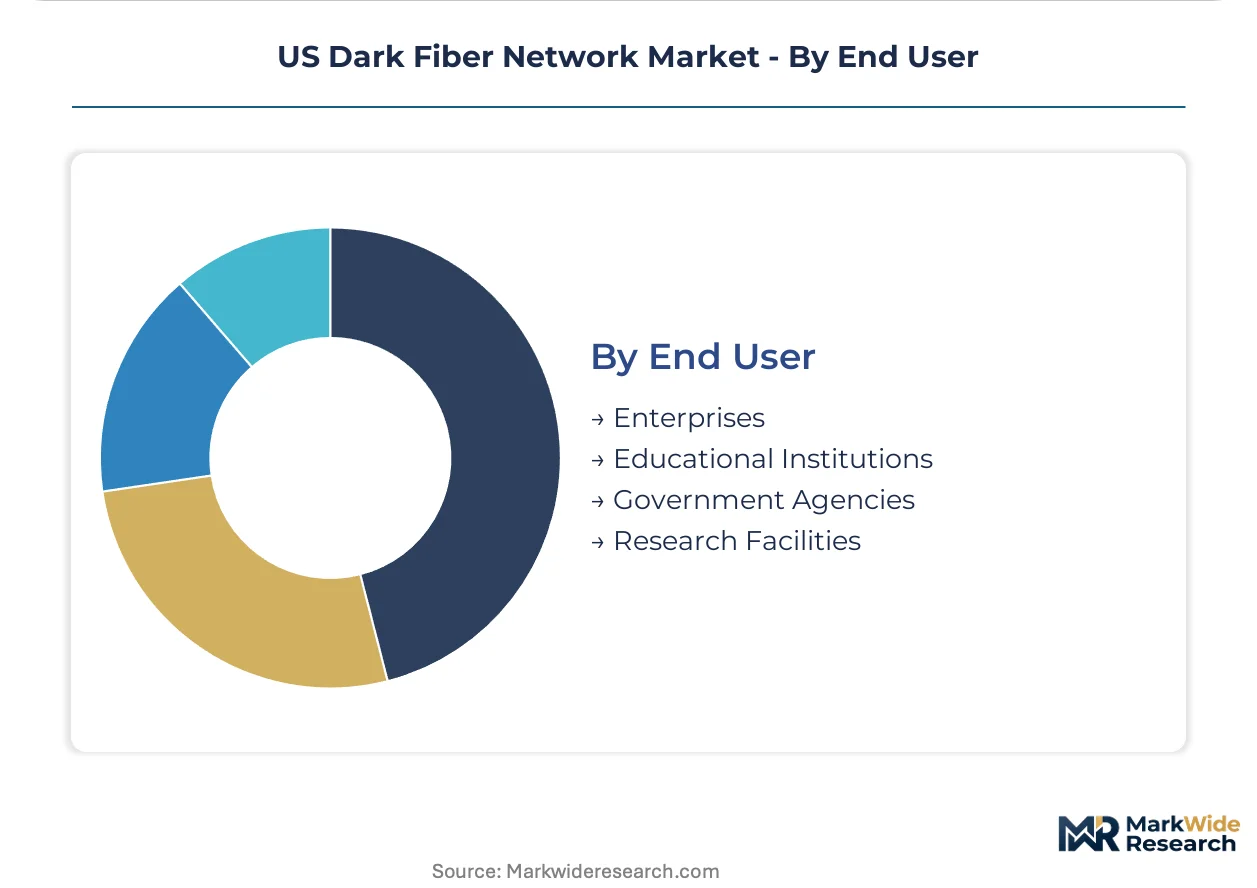
End User:
Maturity gradients separate established financial services procurement from emerging institutional demand with distinct technical certification requirements.
- Enterprises:Diverse commercial buyers spanning financial services, healthcare, and technology verticals. Financial services firms require route certification complexity that traces conduit paths across multiple carrier handoffs.
- Research Facilities:Federal grant recipients requiring physical route diversity for data replication. These buyers operate procurement channels distinct from commercial carrier sales.
- Educational Institutions:Universities procuring dark fiber for campus interconnect and disaster recovery. State-level dig-once policies in Virginia and Texas accelerate availability for these buyers.
- Government Agencies:Public sector buyers with procurement timelines tied to NTIA BEAD funding schedules. Stakeholders must monitor how these timelines intersect with utility pole access disputes.
Dominating procurement volume: Enterprises. Climbing the fastest: Research Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Underground conduit corridors in Texas, Virginia, and California anchor US dark fiber deployment density. These three states concentrate hyperscale data center construction and corresponding fiber demand. FCC infrastructure rules and state dig-once policies redirect public construction dollars toward strand-ready infrastructure.
Northern Virginia
Data center operators in Loudoun and Prince William counties consume dedicated conduit pairs for inter-campus links. Virginia's dig-once mandates require fiber installation during state road projects, reducing deployment friction. Ashburn and Manassas anchor the highest strand density corridor in the United States.
Texas Triangle
Dallas-Fort Worth hyperscale campuses drive procurement of long-haul dark fiber for cloud infrastructure expansion. Texas Transportation Code provisions mandate conduit installation during highway construction, lowering incremental fiber deployment costs. Austin and San Antonio secondary markets attract edge data center backhaul demand.
California Bay Area
Research universities and technology campuses in Santa Clara and San Mateo counties require physical route diversity for data replication topology. California Public Utilities Commission pole access rules govern attachment rates for fiber overbuilds. Silicon Valley conduit scarcity pushes construction toward Sacramento and Central Valley extensions.
Greater Chicago
Financial services firms in the Loop and surrounding suburbs demand documented physical diversity certificates for trading infrastructure. Illinois Commerce Commission regulations shape utility pole access timelines for suburban fiber routes. Aurora and Elk Grove Village data center clusters sustain secondary market strand demand.
Phoenix Metro
Edge data center nodes in Mesa and Chandler need dedicated fiber pairs for distributed compute backhaul. Arizona dig-once policies align municipal road construction with conduit deployment schedules. The market extends addressable geography beyond established hyperscale corridors as cloud operators diversify thermal risk.
US Dark Fiber Network Market Key Industry Players
Established wholesale operators occupy the standard tier; emerging data center verticals pursue captive fiber control. The market structure concentrates around national-scale conduit owners with FCC Section 224 pole attachment agreements. Three archetypes dominate: carrier-neutral aggregators, incumbent telecom legacy route holders, and hyperscale-integrated builders. Competitive moves center on bulk pole access pre-negotiation and route-specific construction commitments ahead of lease obligations.
Among national-scale wholesale operators, Zayo Group Holdings and Lumen Technologies exemplify divergent strategic positioning. Zayo leverages its sixteen million fiber-mile footprint to anchor cloud provider contracts through route diversity. Lumen sustains legacy intercity assets while competing for enterprise procurement in secondary markets where construction labor scarcity constrains expansion velocity. Crown Castle Fiber occupies a position within the infrastructure-focused tier, representing the data center-integrated archetype that verticalizes fiber ownership with captive facility deployment.
| Leading Market Players |
|---|
| Zayo Group Holdings |
| Lumen Technologies |
| AT&T |
| Crown Castle Fiber |
| Verizon Communications |
| Comcast Corporation |
| Uniti Group |
| Consolidated Communications |
| GTT Communications |
| Others |
Cost & Logistics Intelligence
Coherent pluggable optics at 400ZR and 800ZR standards are compressing equipment procurement cycles while simultaneously fragmenting supplier power away from incumbent carriers toward hyperscale operators who source transponders independently from fiber leases. This technology shift concentrates pricing leverage with route owners who can offer physical diversity certificates while eroding the value capture of lit-fiber providers who previously bundled equipment with strand access.
Pricing Analysis
Equipment-light leasing structures dominate as hyperscale operators unbundle transmission electronics from fiber procurement. Price differentiation hinges on route certification grade and physical diversity documentation, with financial services buyers paying premiums for traced conduit paths across multiple carrier handoffs. Cost compression runs through mid-bandwidth tiers as coherent optical transceivers enable wavelength leasing alternatives that narrow the cost gap with unlit strands. Enterprise healthcare systems exhibit highest price sensitivity, favoring five-year lease terms with expansion clauses over twenty-year indefeasible rights of use.
Supply Chain Analysis
Freight logistics for optical cable and conduit materials concentrate domestic manufacturing in South Carolina, North Carolina, and Tennessee production facilities. Fiber draws from Corning's New York and North Carolina plants alongside OFS Optics' Georgia and Alabama operations. Single-source vulnerability centers on specialized fusion splicing equipment from Fujikura and Sumitomo Electric. Distribution runs through carrier-neutral data center operators who aggregate strand access for multiple tenants across shared conduit infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
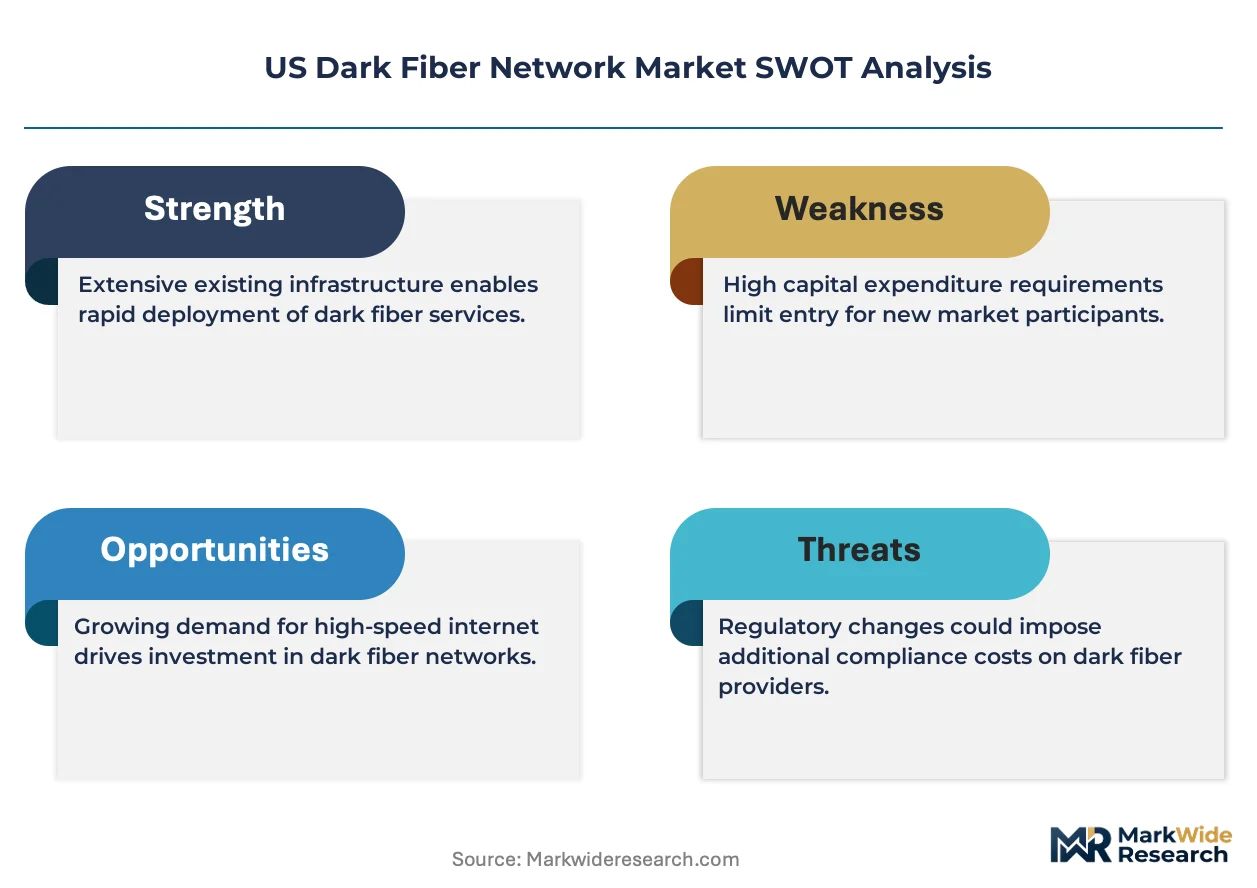
FCC Section 224 pole attachment rules erect a cost-of-compliance moat that favors established wholesale operators with pre-negotiated bulk access agreements, marginalizing entrants lacking regulatory affairs infrastructure.
For Market Incumbents: Acquire stranded conduit assets in secondary metros to preempt emerging edge data center backhaul demand. Consolidate construction labor pools through acquisition of specialized directional drilling crews in Phoenix and Columbus corridors. Defend against coherent optical substitution by emphasizing physical route diversity certificates that wavelength services cannot replicate.
For New Entrants and Emerging Players: Launch via municipal network partnerships in Texas and Virginia dig-once corridors to bypass pole attachment disputes with electric utilities. Target healthcare campus interconnect in Midwest secondary markets where institutional buyers prioritize capital flexibility over incumbent brand recognition. Pursue research university procurement channels that operate outside commercial carrier sales structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure fund roll-ups of regional fiber builders with captive data center relationships. Long-term viability favors carriers with FCC Section 224 compliance infrastructure and bulk pole access agreements spanning multiple states. Monitor NTIA BEAD funding timeline acceleration as inflection signal for construction labor scarcity intensification.
| Strategic Initiative | Industry Significance |
|---|---|
| Route Diversity Certification Investment | Financial services buyers require documented physical path tracing across multiple carrier handoffs. |
| Bulk Pole Access Pre-negotiation | FCC Section 224 compliance reduces utility stall tactics and secures construction windows. |
| Coherent Optics Partnership | 400ZR and 800ZR transceiver sourcing enables hyperscale operators to light fiber independently. |
| Edge Data Center Vertical Integration | Phoenix and Columbus nodes extend addressable geography beyond established hyperscale corridors. |
| Healthcare Campus Lease Structuring | Five-year terms with expansion clauses match Midwest institutional buyer capital flexibility preferences. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with fiber network engineers, data center development executives, utility pole access negotiators, and enterprise procurement managers. FCC Section 224 docket filings, NTIA BEAD program disbursement schedules, state public utility commission rate cases, and fiber-mileage disclosure forms supplied validation benchmarks. Bottom-up strand inventory estimates triangulated against top-down hyperscale capex allocation patterns.
Reconciliation across construction permit databases, labor union membership rolls, and conduit deployment schedules informed the analytical framework. Segmentation dimensions spanned network type, connectivity mode, service provider archetype, and end-user vertical across the projection horizon. CAGRs derived from weighted averaging of deployment velocity scenarios against committed lease obligations. Hyperscale campus expansion timelines and dig-once policy adoption curves served as industry-specific forecast inputs.
Utility pole access litigation delays, optical equipment substitution acceleration, and BEAD funding disbursement timing are the dominant revision risks to modeled construction schedules. Forecasts reflect documented assumptions about labor availability and regulatory timeline certainty. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Italy Data Center Networking Market