
 Managed Network Services Market | 2026-2036
Managed Network Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Network Services Market Analysis
Software-defined wide-area networking is tilting enterprise traffic away from legacy MPLS circuits toward cloud-orchestrated connectivity fabrics. Dataprise leverages its channel partner density to dominate mid-market deployments across the United States. Integris anchors its competitive position through vertical specialization in healthcare and financial services compliance. TPx Communications extends its footprint by bundling unified communications with managed network offerings for distributed enterprises.
Managed network services encompass the outsourcing of network infrastructure operations, monitoring, and optimization to third-party providers, typically delivered through software-defined controllers, policy-driven automation engines, and 24/7 security operations centers that maintain uptime thresholds exceeding 99.9% availability. These services relieve internal IT organizations from capital-intensive hardware refresh cycles while ensuring continuous alignment with evolving threat landscapes and bandwidth demands. Security services within the service type dimension commands premium pricing due to escalating ransomware frequency and zero-day vulnerability exposure. Cloud-based deployment models are outpacing on-premises alternatives as enterprises distribute workloads across multi-region hyperscaler footprints. SD-WAN technology is displacing MPLS in new installations, though Ethernet retains dominance in campus and data center interconnect scenarios where deterministic latency remains non-negotiable.
The FCC governs broadband access and network neutrality parameters affecting managed service provider interconnection agreements in the United States, while the EU AI Act and GDPR impose data governance constraints on cross-border network traffic management within European deployments. NIST cybersecurity frameworks and ISO 27001 certification requirements are hardening procurement criteria for government and regulated industry contracts. Stakeholders must monitor convergence between zero-trust architecture mandates and existing network segmentation paradigms to anticipate capability investments that preserve contract eligibility.
Market Dynamics
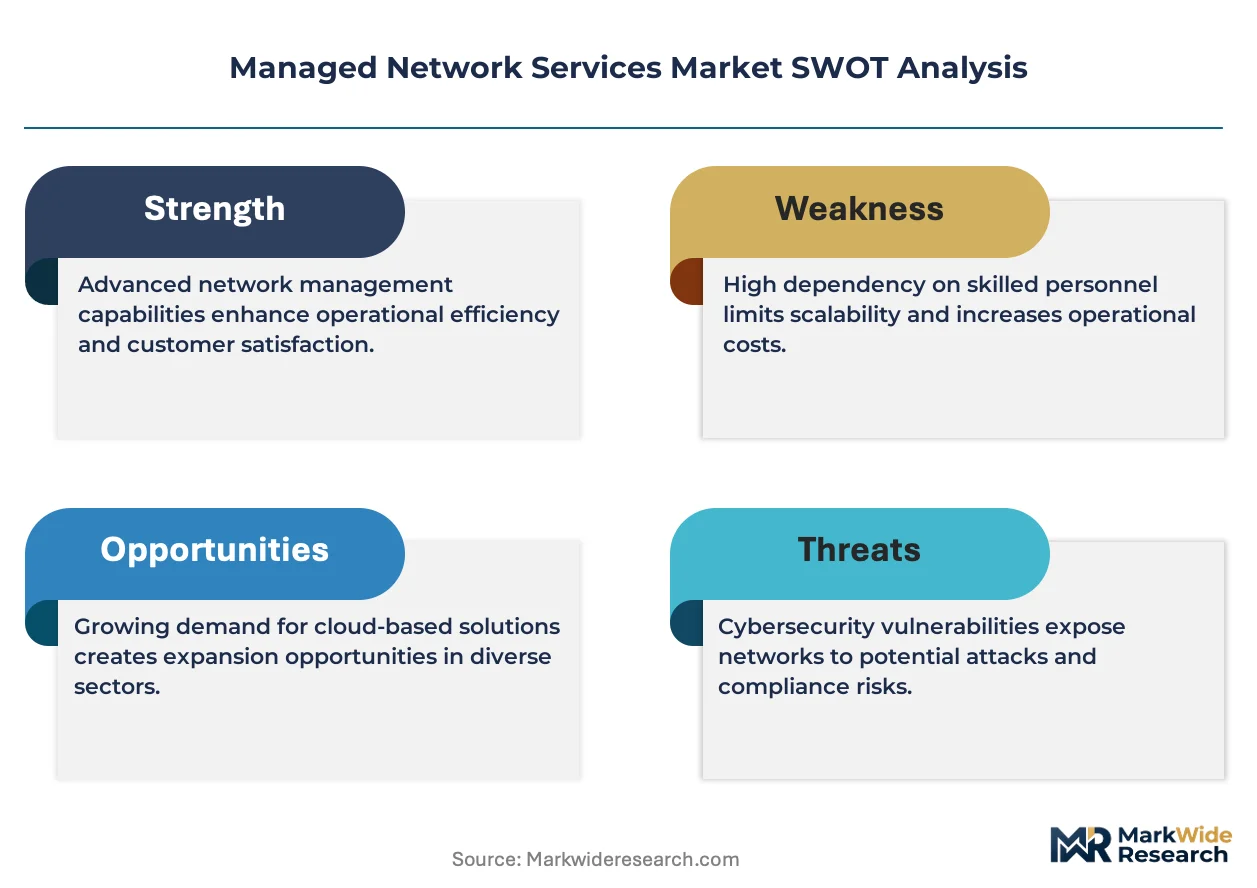
SD-WAN technology is compressing MPLS replacement cycles while zero-trust mandates from NIST and equivalent bodies harden procurement criteria for government contracts. Service providers must rearchitect delivery stacks to maintain eligibility.
Growth Catalysts
- Telemedicine Infrastructure:Healthcare systems are outsourcing network operations to support remote diagnostics and patient monitoring platforms. HIPAA compliance requirements drive preference for certified managed service providers.
- FCC Net Neutrality Framework:Evolving interconnection rules reshape contract structures for broadband-dependent services. Providers adapt pricing models to reflect new traffic management constraints.
- Industry 4.0 Deployments:German manufacturing clusters accelerate managed network adoption to connect industrial IoT sensors and automated production lines. Real-time data flows demand sub-10 millisecond latency guarantees.
Market Restraints
- Skilled Engineering Scarcity:Shortage of certified network architects and security operations specialists limits service expansion. Training pipelines cannot match deployment velocity.
- Legacy Hardware Lock-in:Enterprises face switching costs from embedded MPLS contracts and proprietary campus Ethernet installations. Technical debt delays cloud-orchestrated migration timelines.
- Cross-border Data Friction:GDPR and EU AI Act impose governance constraints on traffic routing between European and non-European endpoints. Compliance architecture adds operational overhead.
Strategic Opportunities
- Edge Computing Convergence:Managed network providers can bundle connectivity with distributed compute nodes at cellular tower sites and factory floors. SD-WAN controllers orchestrate both traffic and containerized workloads.
- Outcome-based Contracting:Enterprise buyers shift from port-speed pricing to availability and application-performance guarantees. Providers capture margin through automation-driven efficiency gains.
- India Manufacturing Corridors:PLI scheme incentives attract electronics and automotive production requiring industrial-grade network infrastructure. Greenfield facilities bypass legacy constraints entirely.
Industry Challenges
- Multi-vendor Integration Complexity:Enterprises demand seamless interoperability between cloud security brokers, SD-WAN controllers, and existing firewall investments. Technical validation cycles extend sales timelines.
- 24/7 Security Operations Scale:Ransomware frequency forces continuous monitoring investment. Threat detection staffing costs erode service margins at mid-market price points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Network Services Market |
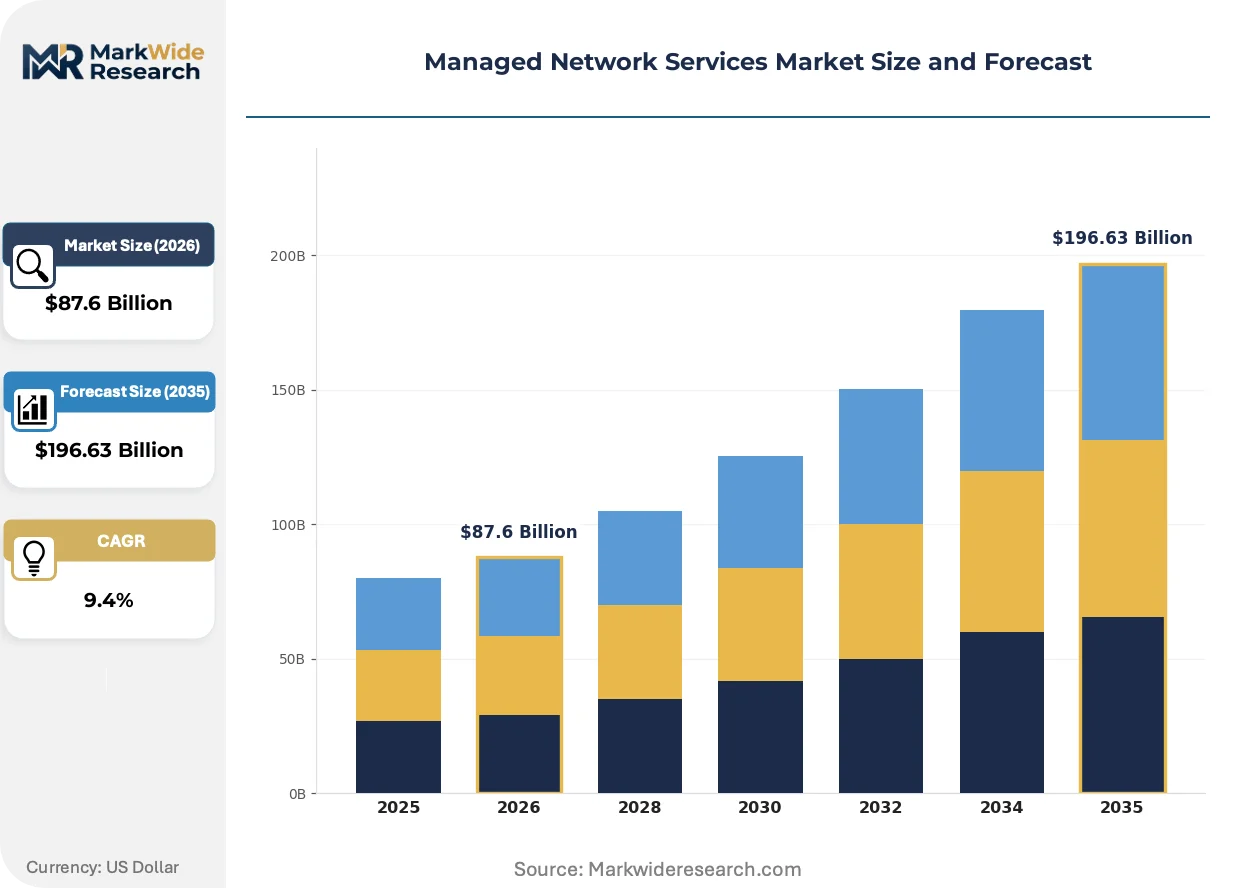
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Monitoring, Incident Management, Performance Management, Security Services Deployment Model: On-Premises, Hybrid, Cloud-Based, Co-Location End User: Enterprises, SMEs, Telecommunications, Government Technology: SD-WAN, MPLS, VPN, Ethernet |
| Companies Covered | Dataprise, Innowise, Integris, TPx Communications, Net at Work LLC, Xavor Corporation, BetterWorld Technology, Realnets, Sage IT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Network Services Market Emerging Trajectories
Automation engines and policy-driven controllers are replacing manual network configuration. Service delivery models compress toward self-healing infrastructure with embedded compliance validation.
Secure Access Service Edge architecture is digitizing branch office connectivity by converging SD-WAN with cloud-delivered security stacks. Financial services firms and healthcare systems adopt SASE fastest, driven by distributed workforce requirements. The technology is digitizing perimeter security into identity-aware microsegmentation, collapsing hardware refresh cycles from five years to eighteen months.
The EU AI Act imposes algorithmic transparency requirements on network traffic management systems using machine learning for anomaly detection. European deployments must document automated decision logic for regulatory audit. Managed service providers serving German automotive and French pharmaceutical clusters invest most heavily in explainable AI tooling to preserve contract eligibility.
Enterprise sourcing teams now unbundle hardware procurement from operational management, contracting connectivity as a utility while retaining capital expenditure flexibility. Systems integrators and direct carrier relationships displace traditional value-added reseller channels. This pattern concentrates most visibly among United States mid-market manufacturers consolidating multi-site contracts under single-provider frameworks.
Managed Network Services Market Segmentation
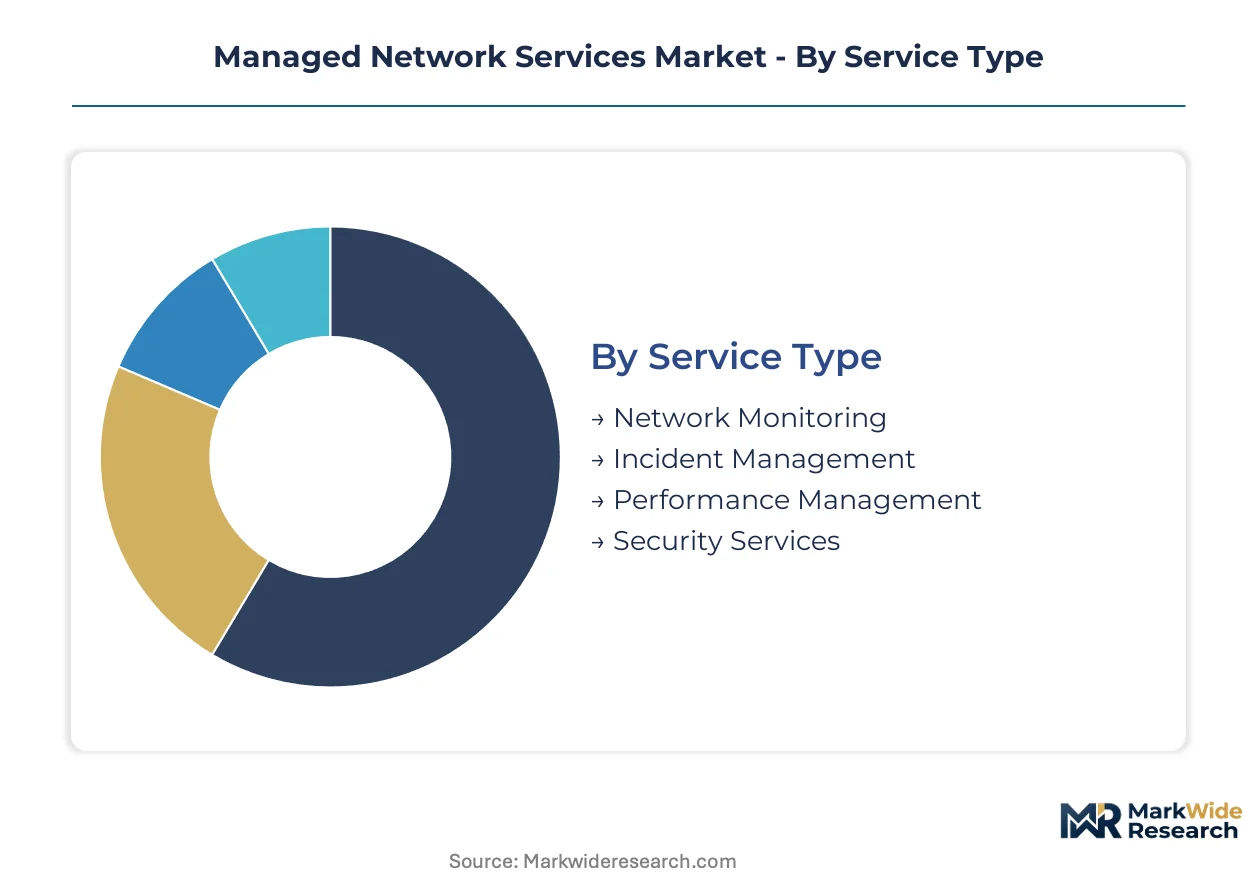
Segmentation in managed network services reveals how procurement priorities diverge across infrastructure maturity levels and compliance exposure. Buyers with legacy MPLS contracts face different migration economics than greenfield cloud-native deployments. Understanding these fault lines allows providers to align automation investments with segments exhibiting the steepest willingness-to-pay trajectories.
Service Type:
Mature operational disciplines dominate procurement budgets while emerging security capabilities capture premium pricing expansion.
- Network Monitoring:Continuous infrastructure telemetry collection through SNMP, flow analysis, and synthetic transaction testing. Manufacturing clusters in Germany anchor demand as Industry 4.0 sensor density multiplies endpoint visibility requirements. Real-time dashboarding and predictive threshold alerting justify multi-year contracts.
- Security Services:Integrated threat detection, firewall management, and zero-trust policy enforcement delivered through 24/7 security operations centers. Healthcare systems in the United States prioritize this segment under HIPAA breach notification pressure and escalating ransomware frequency against patient data repositories.
- Incident Management:Escalation workflows and root-cause analysis for network degradation events. IT teams in financial services demand sub-15-minute response guarantees.
- Performance Management:Application-aware traffic shaping and quality-of-service optimization. Video-intensive enterprises drive adoption for latency-sensitive collaboration platforms.
Network Monitoring retains volume leadership; Security Services holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates capital-intensive ownership models from operational expenditure flexibility.
- Cloud-Based:Fully managed connectivity orchestrated through hyperscaler-integrated controllers with policy automation and elastic bandwidth scaling. Distributed enterprises across the United States favor this model to collapse hardware refresh cycles and align spending with actual consumption patterns.
- Hybrid:Split architecture preserving on-premises control planes for sensitive workloads while bursting traffic through cloud gateways. German automotive suppliers adopt hybrid frameworks to satisfy GDPR data residency mandates for engineering data while leveraging cloud analytics.
- On-Premises:Dedicated hardware appliances and private controller instances within customer facilities. Defense contractors and classified government networks maintain this posture.
- Co-Location:Provider-managed equipment housed in third-party data centers with cross-connect access to carrier-neutral ecosystems. Content delivery networks optimize last-mile presence through this model.
Cloud-Based deployment is climbing the fastest; On-Premises retains entrenched positions in regulated verticals.
End User:
Customer type determines contract structure complexity and compliance certification requirements.
- Enterprises:Multi-site organizations with 500+ employees requiring unified policy enforcement across heterogeneous branch topologies. These buyers negotiate outcome-based availability guarantees and demand SOC 2 Type II attestation.
- Government:Federal, state, and municipal agencies procuring through FedRAMP-authorized or equivalent frameworks. NIST zero-trust mandates reshape technical evaluation criteria.
- SMEs:Mid-market organizations purchasing standardized service tiers through channel partners with compressed implementation timelines.
- Telecommunications:Carriers and ISPs outsourcing network operations to specialist providers for operational cost reduction.
Enterprises command the largest contract values; Government represents the most rigorous certification barrier.
Technology:
Application context dictates transport selection between deterministic legacy circuits and software-defined alternatives.
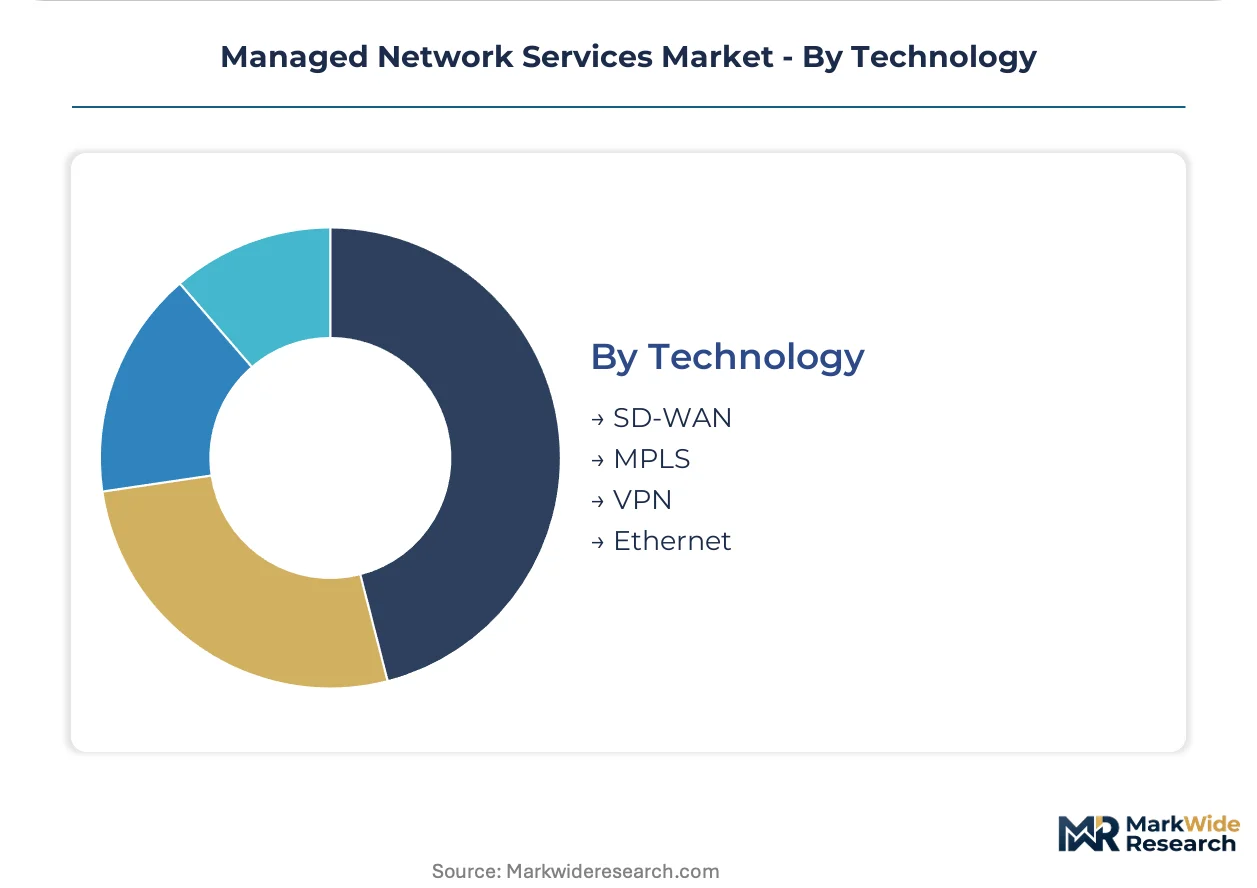
- SD-WAN:Policy-driven path selection across multiple underlay transports with centralized orchestration and application-aware routing. Retail chains and distributed healthcare clinics deploy SD-WAN to aggregate broadband, LTE, and MPLS into resilient fabrics.
- Ethernet:Dedicated layer-2 connectivity for campus interconnect and data center replication requiring guaranteed latency and zero packet loss. Financial exchanges and high-frequency trading infrastructure depend on Ethernet for microsecond precision.
- MPLS:Label-switched private networks with traffic engineering and quality-of-service guarantees. Legacy enterprise WANs retain MPLS for voice and video trunking.
- VPN:Encrypted tunnel overlays for remote workforce access and site-to-site connectivity at lowest cost points.
Ethernet retains dominance in latency-critical infrastructure; SD-WAN is gaining share fastest across greenfield deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade in managed network services flows predominantly from technology-exporting economies toward manufacturing and healthcare-importing regions. The United States maintains a services surplus in this category while Germany and India represent accelerating demand centers with distinct procurement profiles.
United States
Healthcare systems and federal agencies drive contract volume. FCC net neutrality rules reshape interconnection pricing for broadband-dependent offerings. The Washington DC-to-Boston corridor concentrates government procurement while Texas anchors energy-sector deployments.
Germany
Automotive suppliers and industrial machinery producers demand sub-10 millisecond latency guarantees for Industry 4.0 sensor networks. EU AI Act documentation requirements apply to ML-driven traffic management systems. Manufacturing clusters in Bavaria and Baden-Württemberg deploy managed SD-WAN at scale.
India
PLI scheme incentives attract electronics and automotive production requiring industrial-grade infrastructure. TRAI regulations govern cross-border data routing for multinational deployments. Manufacturing corridors in Tamil Nadu and Gujarat adopt greenfield network architectures without legacy MPLS constraints.
United Kingdom
Financial services firms in London prioritize SASE adoption for distributed workforce security. GDPR compliance architecture adds operational overhead to European traffic management. The London-Edinburgh axis hosts the densest concentration of outcome-based managed network contracts.
Japan
Precision manufacturing and robotics sectors demand deterministic latency for automated production lines. METI industrial digitization programs subsidize private 5G and managed network convergence. The Nagoya-Toyota industrial zone leads deployment density for time-sensitive networking applications.
Managed Network Services Market Vendor Landscape
On the supply side, the industry is moderately consolidated around three strategic tiers. Global systems integrators and telecommunications carriers occupy the upper tier with comprehensive portfolio breadth. Mid-market specialists dominate the middle tier through vertical industry expertise and regional channel density. Pure-play technology vendors anchor the lower tier with focused automation tooling. Competitive dynamics center on strategic partnerships with hyperscaler platforms and outcome-based contract restructuring.
Among United States-based providers, Dataprise exemplifies the mid-market channel-density archetype while Integris occupies a position within vertical-specialist positioning. TPx Communications represents the bundled-services approach combining unified communications with network management. These three anchors illustrate how geographic concentration and service bundling differentiate competitive positioning.
| Leading Market Players |
|---|
| Dataprise |
| Innowise |
| Integris |
| TPx Communications |
| Net at Work LLC |
| Xavor Corporation |
| BetterWorld Technology |
| Realnets |
| Sage IT |
| Others |
Supply Flow & Price Mechanics
Semiconductor fabrication capacity concentration in Taiwan and South Korea feeds directly into SD-WAN controller hardware costs, compressing margin pools for mid-market managed service providers while hyperscaler-integrated competitors capture pricing power through volume commitments.
Pricing Analysis
Industrial OEM buyers anchor a subscription-tiered pricing structure across cloud-based deployment models. Three-tier pricing separates SOC 2 Type II certified security bundles from standard monitoring tiers and baseline connectivity packages. Cost compression in the mid-market intensifies because hyperscaler partnerships allow larger providers to undercut on infrastructure overhead. Healthcare systems exhibit least price sensitivity due to HIPAA breach liability exposure, while SME manufacturing clusters drive hardest bargain on per-port economics.
Supply Chain Analysis
Upstreame silicon supply draws from Taiwan, South Korea, and the United States for SD-WAN appliance chipsets and security operations center server infrastructure. Optical transceiver components and hyperscaler data center capacity constitute secondary input dependencies. Single-source vulnerability around advanced networking silicon creates procurement risk for providers lacking diversified vendor qualifications. Distribution runs through direct carrier relationships and systems integrator channels that displace traditional value-added reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from hyperscaler-native network-as-a-service offerings that bundle connectivity with compute and storage, eroding the standalone managed network value proposition.
For Market Incumbents: Build compliance certification moats around FedRAMP and ISO 27001 attestation to lock out unqualified entrants from government and healthcare contracts. Deepen backward integration into proprietary automation tooling to reduce hyperscaler dependency and preserve margin on orchestration layers. Counter hyperscaler encroachment by verticalizing around Industry 4.0 latency guarantees that cloud-native alternatives cannot match.
For New Entrants and Emerging Players: Pursue white-space expansion in India manufacturing corridors where PLI-subsidized greenfield facilities bypass legacy MPLS constraints entirely. Target German automotive supplier clusters seeking hybrid deployment models to satisfy GDPR data residency mandates. Lead with edge-compute bundling at cellular tower sites to differentiate from established SD-WAN pure-plays.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-market specialists possessing dense channel partner networks but lacking hyperscaler integration. Five-to-ten year viability hinges on automation-driven efficiency gains that sustain outcome-based contracting margins. Watch for NIST zero-trust mandate enforcement velocity as inflection indicator for security services premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Partnership Deepening | AWS, Azure, and GCP integration locks in elastic infrastructure pricing advantages against carrier-dependent rivals. |
| Vertical Compliance Certification | FedRAMP and HIPAA attestation opens federal and healthcare procurement pipelines with 24-month contract cycles. |
| Edge Compute Convergence | Cellular tower and factory floor node deployment captures containerized workload orchestration beyond pure connectivity. |
| Outcome-Based Contract Restructuring | Availability guarantees replace port-speed pricing, aligning provider incentives with customer application performance. |
| Explainable AI Tooling Investment | EU AI Act documentation capabilities preserve contract eligibility for German automotive and French pharmaceutical clusters. |
Methodological Framework
A spread of perspectives from managed service provider CTOs, enterprise IT procurement officers, channel partner principals, and security operations center directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FCC regulatory filings, NIST cybersecurity framework documentation, hyperscaler capex disclosures, and EU AI Act implementation guidance. Bottom-up service tier demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompass service type, deployment model, end-user category, and underlying transport technology. CAGRs derived from weighted scenario analysis incorporating telemedicine infrastructure buildout velocity, Industry 4.0 sensor density trajectories, and zero-trust mandate adoption curves. Cross-border data friction coefficients and skilled engineering scarcity indices informed regional growth differentials.
Sensitivities concentrate around FCC net neutrality rule revisions, EU AI Act enforcement intensity, and hyperscaler pricing aggression in the mid-market. Forecasts reflect documented assumptions regarding SD-WAN displacement timelines and MPLS contract rollover schedules. Cross-checking against carrier Ethernet pricing benchmarks and enterprise IT outsourcing survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Nosql Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Content Delivery Network (CDN) Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Europe Data Center Networking Market