
 North America Healthcare Cloud Computing Market | 2026-2036
North America Healthcare Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Healthcare Cloud Computing Market Insights
Mid-sized hospital systems are unwinding legacy on-premise data center commitments as payer reimbursement models shift toward value-based care. Microsoft leverages its Azure healthcare API portfolio to anchor enterprise contracts with integrated delivery networks. Amazon Web Services competes through specialized health data lake architectures that reduce genomic processing costs for research institutions.
Healthcare cloud computing encompasses the delivery of computing services—servers, storage, databases, networking, software, and analytics—over the internet to healthcare organizations, with systems typically architected for 99.99% uptime and end-to-end encryption meeting FIPS 140-2 standards. The primary purpose is enabling real-time clinical decision support, population health analytics, and seamless interoperability across disparate electronic health record systems. Software as a Service dominates current spending as hospitals prioritize subscription-based electronic health record modules over capital-intensive infrastructure builds. Hybrid Cloud deployments represent the fastest-expanding architecture as providers balance HIPAA-mandated data sovereignty with elastic compute demands for seasonal patient volume spikes.
FDA oversight of software-as-a-medical-device and HIPAA Security Rule enforcement by the Office for Civil Rights shape product development roadmaps and procurement criteria for cloud vendors seeking hospital contracts. State-level Medicaid agencies in California and New York impose supplemental data residency requirements that fragment compliance obligations across multi-state health systems. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic tools deployed via cloud infrastructure to anticipate validation and liability frameworks.
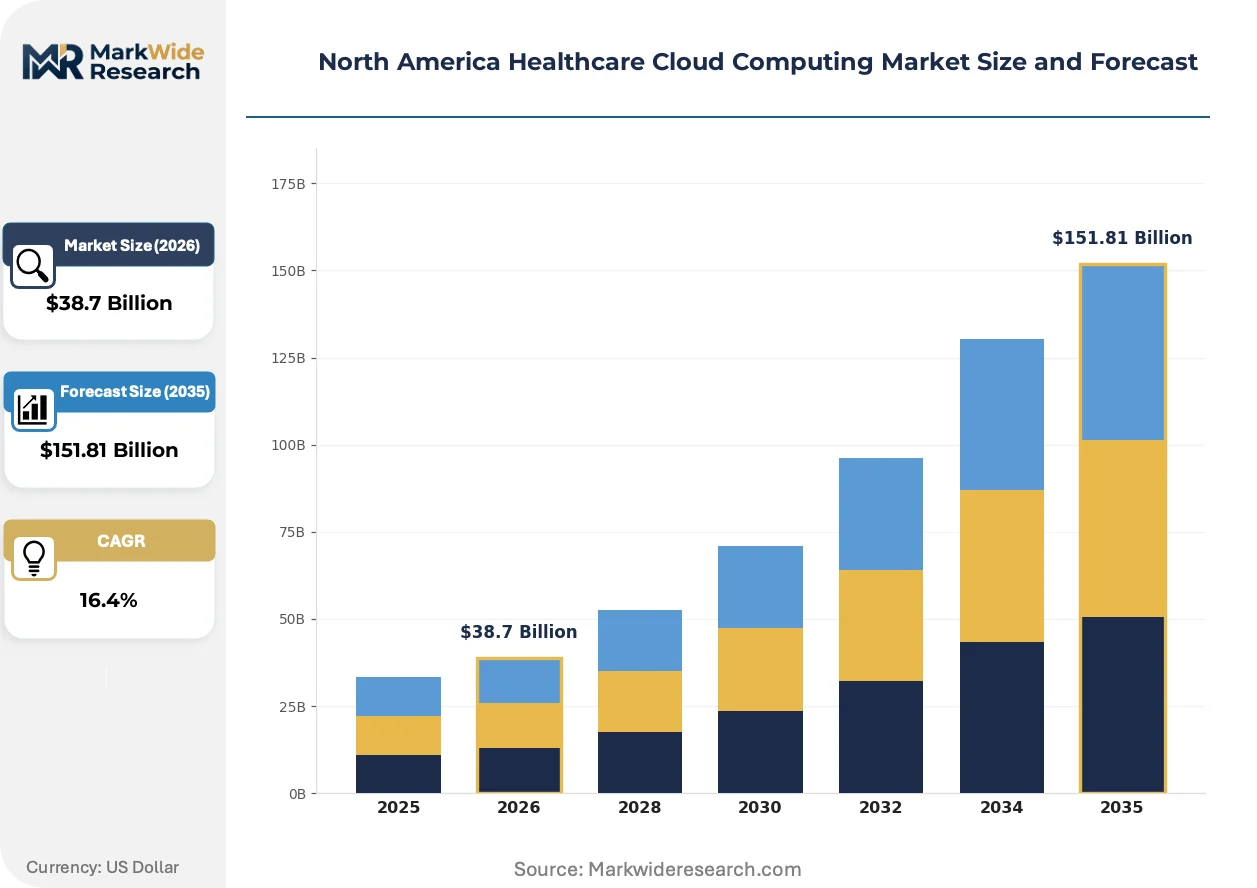
Market Dynamics
Federal interoperability mandates and Medicare reimbursement policies are forcing mid-sized hospital systems to unwind legacy on-premise data center commitments. HIPAA Security Rule enforcement by the Office for Civil Rights tightens compliance requirements while cybersecurity threats multiply.
Growth Catalysts
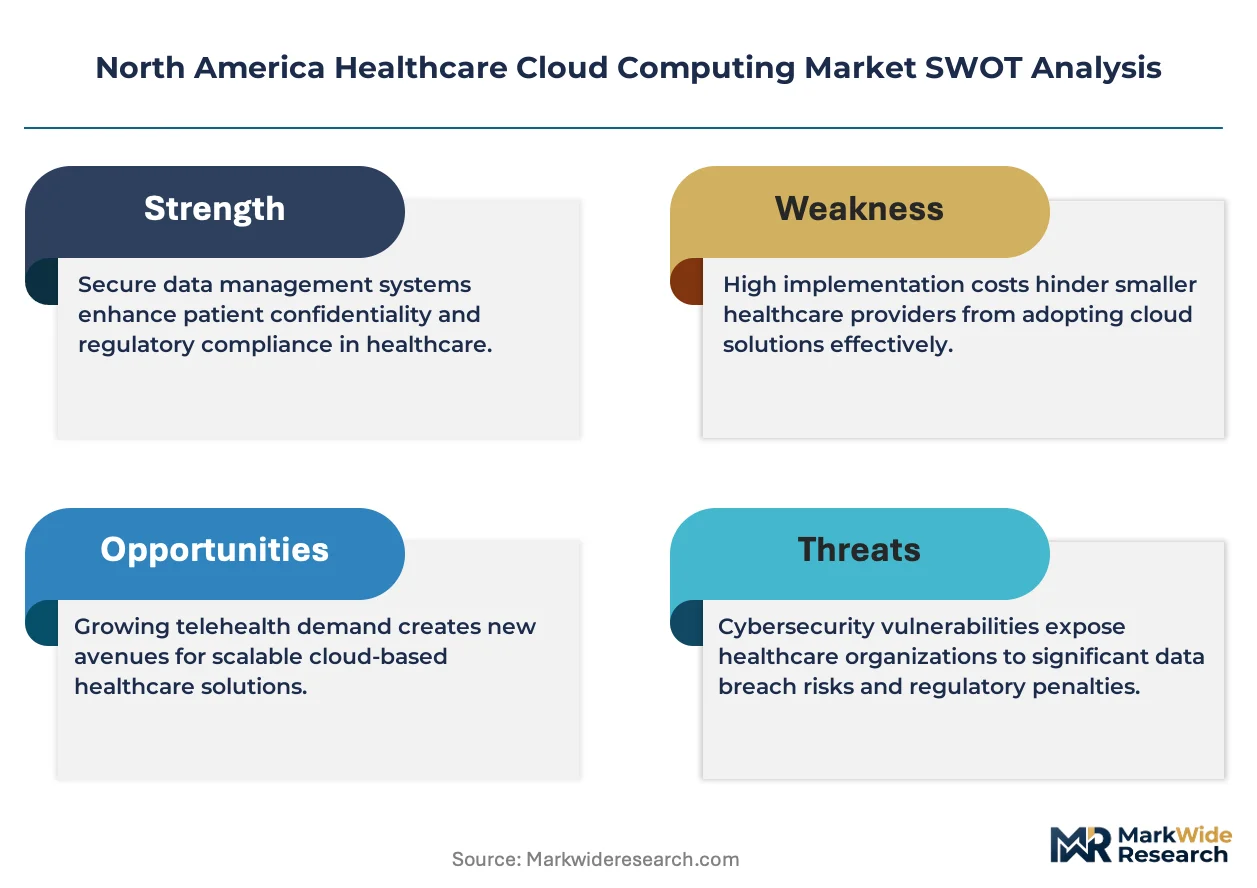
- HIPAA Security Rule Enforcement:The Office for Civil Rights intensifies audits of cloud service providers, compelling hospitals to migrate patient data to compliant architectures. Rural hospital networks accelerate adoption to meet tightened security standards.
- Medicare Value-Based Reimbursement:Payer models shift toward outcome-based care, requiring real-time analytics infrastructure. Integrated delivery networks invest in cloud platforms to track quality metrics and coordinate across facilities.
- Federal Interoperability Mandates:The 21st Century Cures Act implementation demands seamless electronic health record exchange. Health systems deploy cloud-native APIs to connect disparate clinical systems.
Market Restraints
- State-Level Data Residency Fragmentation:California and New York Medicaid agencies impose supplemental data sovereignty requirements. Multi-state health systems face compliance complexity that slows procurement cycles.
- FDA Software-as-Medical-Device Oversight:Cloud-hosted diagnostic algorithms require premarket validation. Validation timelines extend vendor sales cycles and inflate implementation costs.
- Cybersecurity Insurance Premium Volatility:Ransomware attacks against healthcare cloud infrastructure drive coverage costs upward. Smaller hospital systems delay migration decisions due to uncertain total cost of ownership.
Strategic Opportunities
- Genomic Data Lake Architectures:Research institutions seek elastic compute for population-scale sequencing projects. Cloud vendors can anchor long-term contracts through specialized bioinformatics pipelines.
- Hybrid Cloud Sovereignty Solutions:Providers balance HIPAA-mandated on-premise data control with burst compute for seasonal patient volumes. Architecture vendors capture margin through orchestration software.
- AI-Enabled Diagnostic Tool Validation Services:FDA guidance on machine learning-based devices creates advisory demand. Cloud platforms that embed compliance workflows differentiate in enterprise procurement.
Industry Challenges
- Health Informatics Talent Scarcity:Cloud architecture expertise intersects with clinical workflow knowledge in limited labor pools. Health systems compete with technology firms for hybrid-skilled engineers.
- Electronic Health Record Integration Complexity:Legacy EHR systems from dominant vendors resist API standardization. Cloud migration projects stall on data mapping and workflow reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Healthcare Cloud Computing Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software as a Service, Platform as a Service, Infrastructure as a Service, Healthcare Information Exchange Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-cloud End User: Hospitals, Clinics, Pharmaceuticals, Insurance Providers Application: Data Storage, Disaster Recovery, Workflow Management, Collaboration Tools |
| Companies Covered | Amazon Web Services, Microsoft, IBM Corporation, Oracle, Google, athenahealth, Cerner Corporation, CareCloud, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Healthcare Cloud Computing Market Trends and Innovations
Healthcare cloud infrastructure is bifurcating between hyperscale platforms and specialized vertical solutions. This structural split reflects diverging buyer priorities around customization versus standardization.
Containerized microservices architectures are bifurcating the traditional monolithic EHR deployment model. Epic and Cerner clients in academic medical centers adopt Kubernetes-orchestrated modules for discrete clinical functions. This technology is compressing vendor lock-in by enabling modular procurement from competing specialists.
FDA draft guidance on predetermined change control plans for AI-enabled devices is reshaping cloud validation requirements. Machine learning models deployed via infrastructure-as-code pipelines must document modification protocols before market entry. Diagnostic imaging vendors in Massachusetts and California health systems are restructuring DevOps workflows to embed continuous compliance monitoring.
Subscription-based SaaS procurement is displacing capital-intensive perpetual licenses in mid-sized hospital capital budgets. Chief financial officers prioritize operating expenditure predictability over depreciation schedules. Texas and Florida health systems lead this shift, negotiating multi-year enterprise agreements with usage-based scaling clauses.
North America Healthcare Cloud Computing Market Segmentation
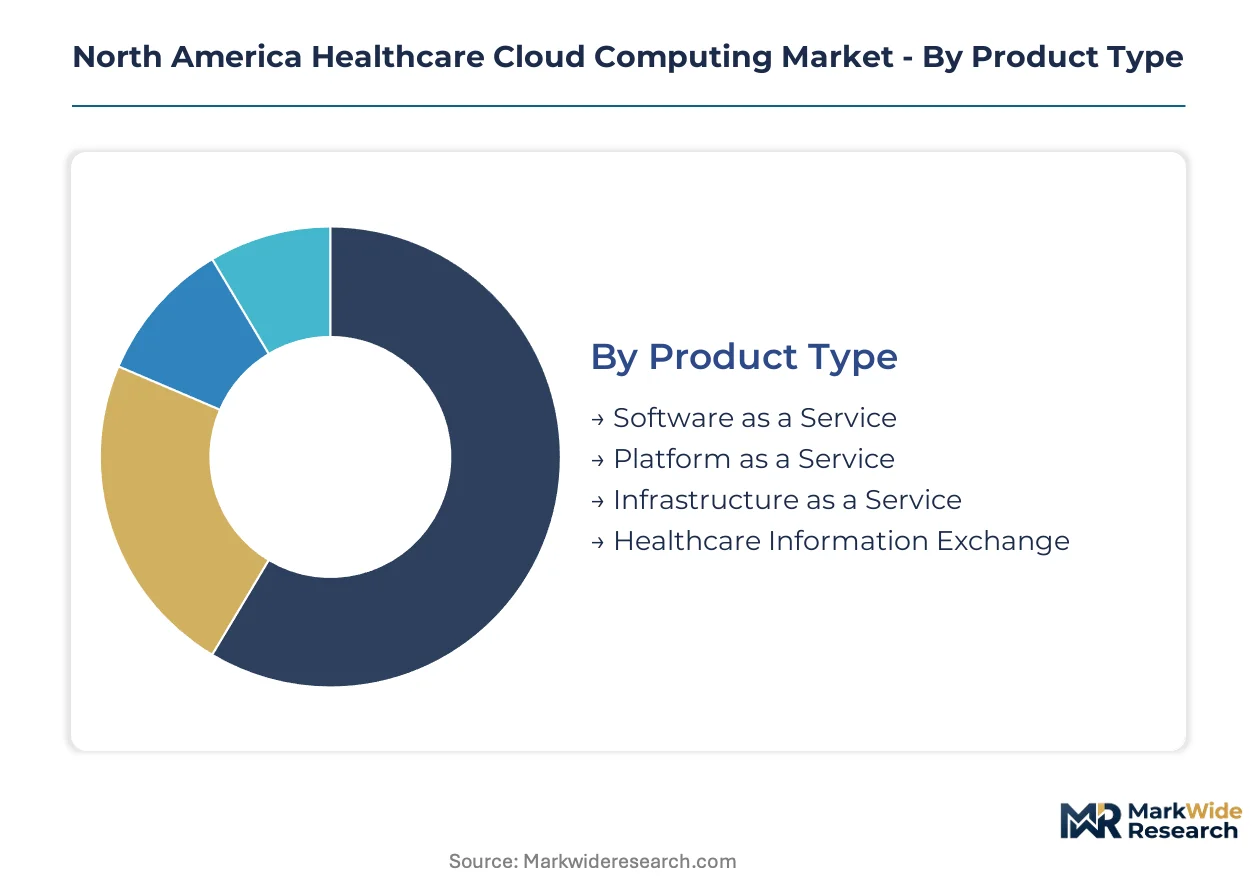
Cloud procurement patterns across North America diverge sharply by organizational scale and regulatory exposure. Segmentation reveals how rural hospital networks, urban academic centers, and pharmaceutical research campuses activate distinct architectural preferences. Understanding these fault lines enables vendors to align subscription tiers with compliance burdens and compute intensity.
Product Type:
Domestic demand concentrates in subscription-based models that convert capital expenditure to predictable operating budgets, while export-oriented licensing remains minimal given HIPAA data residency constraints.
- Software as a Service:Subscription-based electronic health record modules and clinical workflow applications dominate hospital procurement. United States integrated delivery networks prioritize SaaS to accelerate interoperability compliance without infrastructure capital.
- Infrastructure as a Service:Raw compute, storage, and networking resources delivered on-demand support genomic processing and seasonal patient volume spikes. Canadian research institutions and United States academic medical centers drive adoption for elastic bioinformatics workloads.
- Platform as a Service:Development environments with pre-configured compliance frameworks enable health IT teams to deploy containerized applications.
- Healthcare Information Exchange:Cloud-native interoperability hubs facilitate cross-provider data sharing under federal mandate.
Software as a Service commands the established base. The steepest expansion runs through Infrastructure as a Service.
Deployment:
Cost tiering separates budget-constrained rural systems from enterprise health networks with dedicated security operations centers.
- Hybrid Cloud:Architectures blending on-premise HIPAA-controlled data stores with public cloud burst compute address sovereignty requirements. United States mid-sized hospital systems adopt this model to balance compliance with cost elasticity during flu season surges.
- Private Cloud:Dedicated single-tenant environments serve organizations with strict data residency obligations. State Medicaid agencies in California and New York mandate this architecture for beneficiary records.
- Public Cloud:Shared infrastructure delivers lowest unit economics for non-clinical workloads and development environments.
- Multi-cloud:Distributing workloads across competing hyperscale providers reduces vendor lock-in and outage risk.
Hybrid Cloud commands the established base. The steepest expansion runs through Multi-cloud as procurement teams diversify supplier risk.
End User:
Application complexity and regulatory scrutiny create distinct customer maturity tiers across the care continuum.
- Hospitals:Enterprise health systems with 24/7 uptime requirements and multi-facility coordination needs anchor cloud spending. United States hospital networks drive demand for real-time analytics supporting Medicare value-based reimbursement.
- Pharmaceuticals:Research divisions require elastic compute for clinical trial data management and regulatory submission pipelines. North American biotech clusters leverage cloud for FDA-compliant documentation workflows.
- Clinics:Smaller outpatient facilities prioritize cost-efficient SaaS solutions over infrastructure management.
- Insurance Providers:Payers utilize cloud platforms for claims processing and population health risk stratification.
Hospitals command the established base. The steepest expansion runs through Pharmaceuticals as trial complexity escalates.
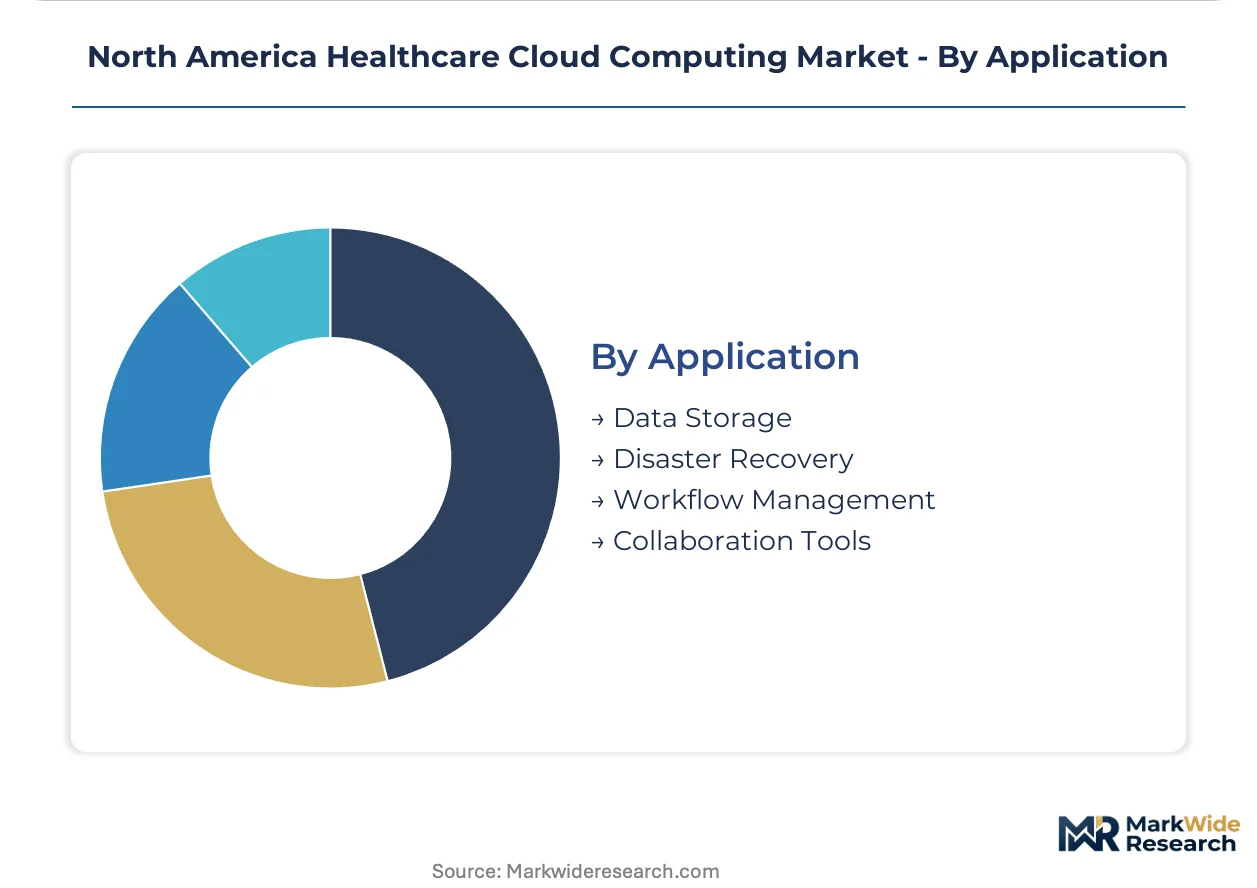
Application:
Volume intensity separates storage-heavy archives from collaboration tools with lighter infrastructure footprints.
- Data Storage:Petabyte-scale patient imaging archives and longitudinal health records demand tiered storage economics. United States radiology networks and Canadian provincial health systems drive capacity expansion for diagnostic imaging retention.
- Disaster Recovery:HIPAA-mandated business continuity requires geographically distributed backup with sub-hour recovery objectives. Rural hospital networks in Texas and Florida invest following ransomware incidents.
- Workflow Management:Clinical task orchestration and patient flow optimization tools reduce administrative overhead.
- Collaboration Tools:Secure messaging and telehealth platforms enable distributed care team coordination.
Data Storage commands the established base. The steepest expansion runs through Disaster Recovery as cyber resilience becomes a board-level priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports specialized health data center infrastructure to United States hospital networks while Mexico supplies nearshore cloud operations talent for North American service delivery. Cross-border data flows concentrate along the Detroit-Windsor corridor and Texas-Mexico logistics channels.
United States
Federal interoperability mandates and Medicare value-based reimbursement drive hospital system consolidation onto cloud-native architectures. HIPAA Security Rule enforcement by the Office for Civil Rights intensifies compliance audits of cloud service providers. The Boston-Cambridge health tech cluster anchors enterprise contract negotiations for integrated delivery networks seeking real-time analytics infrastructure.
Canada
Provincial health systems in Ontario and Quebec invest in cloud disaster recovery following ransomware incidents against rural hospital networks. Health Canada and the Office of the Privacy Commissioner impose supplemental data residency requirements for beneficiary records. Toronto's health informatics talent pool supplies cloud architecture expertise to North American research institutions managing genomic data lakes.
Mexico
Nearshore cloud operations centers in Guadalajara and Mexico City deliver bilingual technical support for United States health systems. The federal data protection framework and state-level health information regulations create compliance complexity for cross-border patient data management. Monterrey's technology corridor attracts capital from hyperscale providers establishing Latin American health cloud infrastructure nodes.
North America Healthcare Cloud Computing Market Competitive Landscape
Player mix skews toward hyperscale technology platforms with specialized healthcare compliance portfolios. Market structure concentrates around three dominant cloud service providers commanding enterprise hospital contracts. Strategic archetypes include infrastructure-as-a-service hyperscalers, healthcare-specific software platforms, and hybrid cloud orchestration specialists. Competitive moves center on API ecosystem expansion and embedded compliance workflow development.
Within the hyperscale tier, Amazon Web Services and Microsoft exemplify platform-centric positioning through healthcare API portfolios and enterprise delivery network anchoring. IBM Corporation occupies a position bridging legacy health IT integration with cloud-native architectures. These three entities represent the dominant competitive anchors as hospital procurement teams evaluate total cost of ownership against HIPAA-validated security frameworks.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM Corporation |
| Oracle |
| athenahealth |
| Cerner Corporation |
| CareCloud |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
Subscription-based SaaS procurement replacing perpetual licensing simultaneously redistributes cloud infrastructure investment toward operating expenditure models and compresses upfront capital barriers for mid-sized hospital systems. This substitution dynamic shifts vendor revenue recognition patterns while expanding addressable buyer pools across rural hospital networks and outpatient clinic chains.
Pricing Analysis
Next-generation AI-enabled diagnostic platforms command substantial premiums over legacy infrastructure-as-a-service offerings, while prior-generation on-premise data center contracts trade at distressed valuations. Three-tier pricing structure across enterprise, mid-market, and entry-level SaaS tiers dominates procurement, with HIPAA certification grade and integration complexity serving as primary differentiation drivers. Cost compression in entry-level tiers is intensifying because hyperscale providers compete for clinic network volume. Rural hospital systems exhibit highest price sensitivity, while academic medical centers prioritize compliance validation over unit economics.
Supply Chain Analysis
Inventory cycles for specialized healthcare compliance hardware stretch to sixteen weeks, constraining rapid deployment timelines for hybrid cloud rollouts. Supply concentrates in the United States, Canada, and Mexico, with hyperscale data center infrastructure drawing from domestic fabrication facilities and nearshore assembly operations. Critical dependencies include FIPS 140-2 validated encryption modules, HIPAA-compliant storage arrays, and container orchestration software. Single-source vulnerability in specialized health IT talent pools creates procurement risk. Distribution runs through direct enterprise sales teams and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal interoperability mandates and AI diagnostic validation requirements are accelerating technology turnover, creating asymmetric opportunity for vendors with embedded compliance workflows.
For Market Incumbents: Compound API ecosystem density through acquisition of specialized interoperability vendors, neutralizing emerging platform challengers. Expand vertical integration into healthcare-specific security operations centers to capture margin from cyber insurance premium volatility. Anchor enterprise contracts with integrated delivery networks through multi-year HIPAA-validated infrastructure commitments. For New Entrants and Emerging Players: AI-enabled diagnostic tool validation services represent a critical service-layer gap where hyperscale incumbents under-serve. Target pharmaceutical research campuses with genomic data lake architectures as the most penetrable segment. Pursue channel partnerships with academic medical center IT departments as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors hybrid cloud orchestration specialists with healthcare compliance portfolios. Long-term viability hinges on regulatory workflow embedding rather than raw compute scale. Acquisition target archetype: mid-cap firms with FDA-validated AI deployment pipelines. Monitor FDA draft guidance on predetermined change control plans as the key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Sovereignty Architecture | Enables HIPAA-compliant data residency with elastic burst compute for seasonal patient volumes. |
| AI Diagnostic Validation Service | Embeds FDA compliance workflows into DevOps pipelines for machine learning deployment. |
| Genomic Data Lake Partnership | Anchors long-term contracts with research institutions through specialized bioinformatics pipelines. |
| API Ecosystem Expansion | Accelerates 21st Century Cures Act interoperability compliance for integrated delivery networks. |
| Health IT Talent Acquisition | Addresses scarcity of cloud architecture expertise intersecting with clinical workflow knowledge. |
Research Methodology
Desk research of SEC filings from hyperscale cloud providers, CMS Medicare reimbursement databases, and FDA software-as-medical-device guidance preceded structured interviews with hospital CIOs, health system procurement directors, and biomedical informatics specialists. Primary fieldwork with cloud architecture vendors and GPO contract managers combined with secondary validation against hospital capital expenditure surveys and interoperability compliance audits. Bottom-up deployment estimates triangulated against top-down healthcare IT spending forecasts.
Variance decomposition across deployment model, organization scale, application complexity, and state-level regulatory cluster shaped analytical framework outputs over the projection horizon. CAGRs derived from segmented adoption curves weighted by Medicare reimbursement policy phase-ins and HIPAA enforcement intensity. Forecast inputs incorporated genomic sequencing volume growth and ransomware incident frequency as healthcare-specific demand drivers.
Underlying assumptions cover sustained federal interoperability mandate enforcement and stable hyperscale capex allocation to healthcare verticals, with deviation risk concentrated in FDA AI guidance timeline shifts and state-level data residency fragmentation. Forecasts reflect documented assumptions without precision claims. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Commercial Cloud Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Cloud Database Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Cloud Microservices Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Cloud Management Market
Cloud Computing
Cloudifier Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Private Cloud Market